
 Mining Shovel Market | 2026-2036
Mining Shovel Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Shovel Market Foresight
Electric-drive specification tiers above 500-ton payload capacity is collapsing the historical cost gap with diesel alternatives. Caterpillar Inc. leverages its integrated powertrain manufacturing to control premium electric shovel supply chains. Komatsu Ltd. anchors its position through autonomous haulage compatibility across its P&H shovel line. SANY Group competes aggressively on delivery speed for mid-tier hydraulic units in emerging mining jurisdictions.
A mining shovel is a heavy-duty excavation machine engineered with boom-mounted dipper arms and crowd mechanisms, typically rated by payload capacity ranging from 20 tons to over 100 tons, designed to load haul trucks in open-pit surface mining operations. Electric shovels deploy alternating-current dragline motors and solid-state rectifier systems that cut fuel consumption by half versus diesel equivalents while demanding higher grid infrastructure investment. Hydraulic shovels dominate copper and gold applications where breakout force and mobility across benches prove decisive; extra large shovels above 400 tons concentrate margin pools in iron ore and oil sands contracts where single-machine output dictates fleet economics.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe are accelerating diesel shovel phase-outs and redirecting capital toward electric and cable-shovel platforms. China's MIIT enforces GB 36886 non-road emission limits that constrain hydraulic shovel deployments in the country's northern coal basins. Stakeholders must weigh grid reliability against fuel price volatility when selecting powertrain architectures for decade-long mine development cycles.
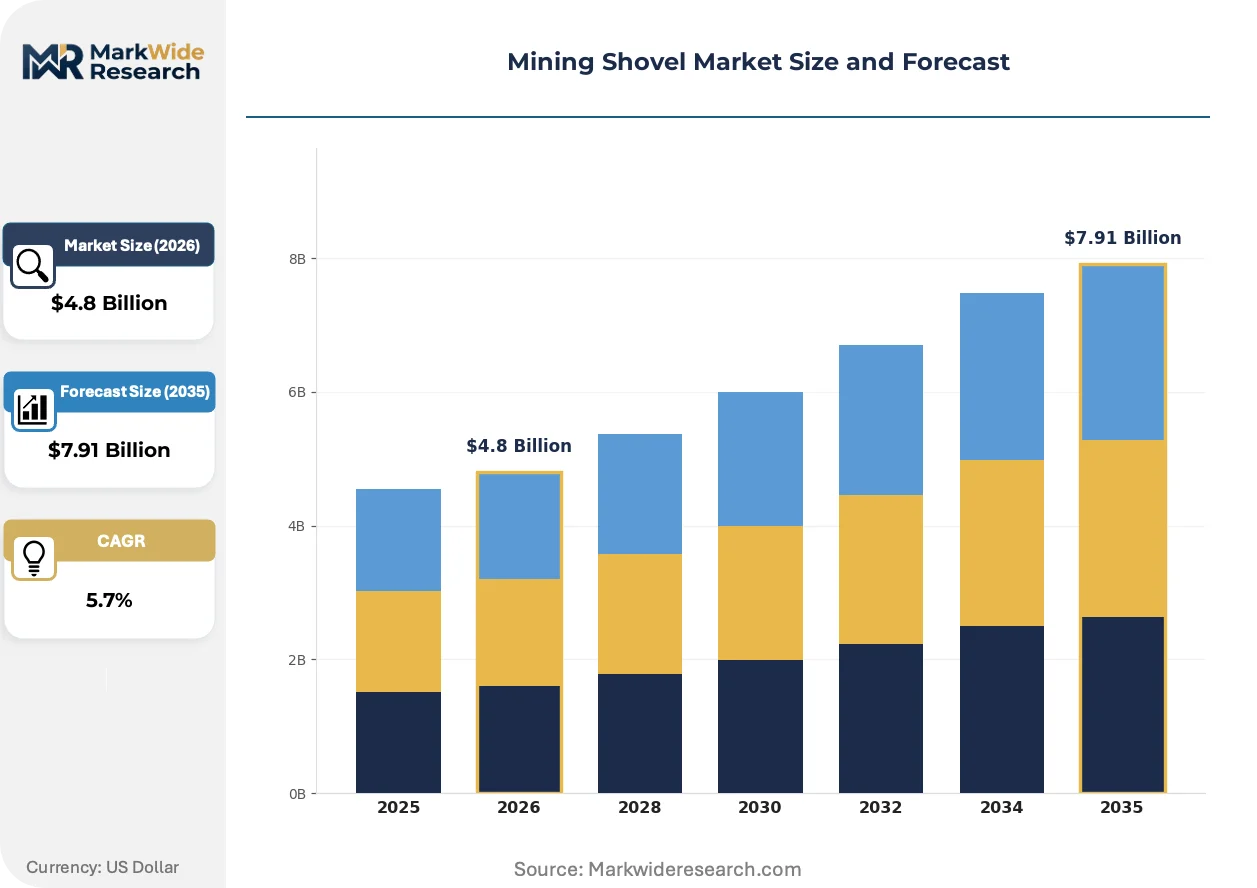
Market Dynamics
EPA Tier 4 Final emissions standards and EU Stage V regulations are forcing diesel-to-electric conversions across surface mining fleets, collapsing the historical cost gap between powertrain architectures and redrawing competitive positioning among equipment suppliers.
Growth Catalysts
- Copper Fleet Renewals:South American copper producers are accelerating shovel replacements to access deeper ore bodies, driving demand for 400-ton-plus electric-drive units in Chile and Peru.
- GB 36886 Enforcement:China's MIIT is tightening non-road emission limits across northern coal basins, compelling state-owned miners to retire legacy hydraulic fleets ahead of schedule.
- Pilbara Iron Ore Concentration:Western Australia's iron ore district demands ultra-class shovels above 500 tons, where single-machine output economics justify premium electric specifications.
Market Restraints
- Grid Infrastructure Dependency:Electric shovel deployment requires substation investment and transmission line extension, constraining adoption in remote greenfield sites lacking grid access.
- Copper Price Volatility:Breaker and motor winding costs fluctuate with LME copper pricing, compressing margins for manufacturers with fixed-price contracts.
- Specialized Foundry Concentration:Cast dipper and boom fabrications concentrate among a limited supplier base in heavy-industry regions, creating bottleneck risk for large-component lead times.
Strategic Opportunities
- Autonomous Haulage Integration:Shovel-to-truck interoperability standards create openings for suppliers offering unified fleet management platforms across loading and hauling operations.
- Indonesian Nickel Expansion:Battery-grade nickel projects in Sulawesi and Halmahera require mid-tier hydraulic units for selective mining, an underpenetrated segment for electric-drive specialists.
- EU Green Deal Funding:European mining equipment lessors can access transition financing for diesel-to-electric conversions under the Sustainable Finance Taxonomy.
Industry Challenges
- Electrification Skill Shortage:Maintenance technicians trained in AC drive systems and solid-state rectifier diagnostics remain scarce relative to diesel-mechanic availability.
- Legacy Fleet Integration:Mixed-powertrain operations complicate spare parts logistics and maintenance scheduling for diversified mining contractors.
- Certification Timeline Compression:EPA and EU Stage V homologation cycles for new electric shovel variants extend delivery schedules by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Shovel Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Shovels, Hydraulic Shovels, Cable Shovels, Diesel Shovels End User: Coal Mining, Metal Mining, Mineral Mining, Quarrying Operation Type: Continuous Operation, Batch Operation, Semi-Automated, Manual Size: Small Shovels, Medium Shovels, Large Shovels, Extra Large Shovels |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., Liebherr Group, Hitachi Construction Machinery, Epiroc AB, SANY Group, XCMG Group, Doosan Infracore, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Shovel Market Shifts & Advancements
Alternating-current drive systems and solid-state power electronics are collapsing the performance gap with diesel-hydraulic alternatives, while regulatory mandates and buyer procurement models accelerate technology transition timelines.
Solid-state rectifier systems are supplanting mechanical Ward Leonard drive sets in electric shovel powertrains. Iron ore operators in Western Australia are specifying these systems for new 500-ton-class orders. The technology is compressing maintenance intervals and enabling regenerative braking energy recovery that mechanical drives cannot match.
EU Stage V non-road emission regulations are prohibiting diesel engine sales for new shovel deployments above 560 kW rated power after 2025. European quarry and aggregate operators are redirecting capital toward cable-shovel and trolley-assist hydraulic platforms. German and Scandinavian contractors are prioritizing grid-connected electric specifications to avoid Stage V compliance costs and fuel volatility.
Performance-based maintenance contracts are displacing time-and-material service agreements for ultra-class shovel fleets. Major iron ore and copper producers in Australia and Chile are unbundling equipment purchase from lifecycle support, awarding multi-year availability guarantees to OEM service divisions. This shift concentrates aftermarket revenue with manufacturers possessing embedded telemetry and predictive analytics capabilities.
Mining Shovel Market Segmentation
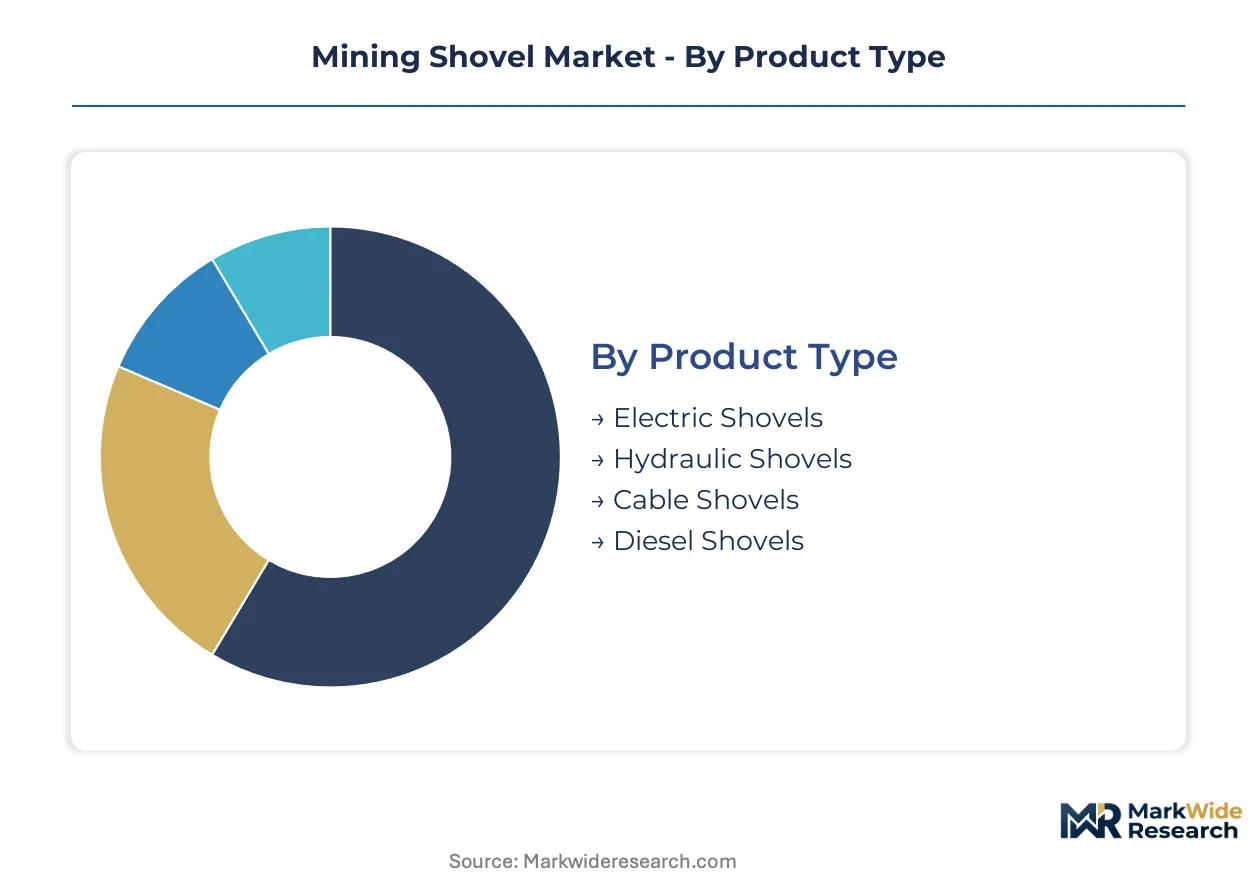
Powertrain architecture and payload class dictate procurement channels and lifecycle economics in mining shovel markets. Equipment lessors, OEM direct sales, and contractor rental pools each align with distinct segment specifications.
Product Type:
Channel distribution splits sharply by powertrain: electric shovels flow through utility-integrated project finance, hydraulic units dominate dealer networks, and diesel variants retreat to secondary markets.
- Electric Shovels:Alternating-current drive systems with solid-state rectifiers cut fuel consumption by half versus diesel alternatives. Western Australia's Pilbara iron ore district specifies these for 500-ton-class orders where grid infrastructure exists and single-machine output economics justify capital intensity.
- Hydraulic Shovels:Diesel or diesel-electric powertrains deliver breakout force and bench mobility for selective mining. Copper and gold applications in Chile and Peru concentrate demand here where terrain variability rewards hydraulic articulation over fixed-cable operation.
- Cable Shovels:Trolley-assist electric platforms serve European quarry operators facing EU Stage V diesel prohibitions above 560 kW.
- Diesel Shovels:Legacy fleets in remote greenfield sites without grid access; EPA Tier 4 Final compliance costs are accelerating phase-outs.
Electric shovels dominate installed base in iron ore. Hydraulic shovels are where expansion concentrates in copper and nickel applications.
End User:
Customer type determines specification tier and financing structure, with state-owned miners favoring electric platforms and diversified contractors mixing powertrains.
- Coal Mining:China's northern coal basins drive retirement of legacy hydraulic fleets under MIIT GB 36886 enforcement; state-owned operators redirect capital toward compliant electric specifications.
- Metal Mining:Copper producers in Chile and Peru anchor ultra-class electric shovel demand for deeper ore body access; fleet renewal cycles concentrate margin pools here.
- Mineral Mining:Battery-grade nickel projects in Indonesia's Sulawesi and Halmahera require mid-tier hydraulic units for selective extraction.
- Quarrying:European aggregate operators prioritize cable-shovel and trolley-assist platforms to avoid Stage V compliance costs.
Metal mining commands premium specification tiers. Coal mining is climbing the fastest as emission enforcement accelerates replacement cycles.
Operation Type:
Automation readiness separates procurement pools, with integrated mining companies specifying interoperability standards that fragmented contractors cannot meet.
- Continuous Operation:24/7 loading cycles in Pilbara iron ore demand shovel-to-truck telemetry integration and predictive maintenance contracts.
- Batch Operation:Intermittent loading for contractor fleets with mixed powertrain logistics and simpler service agreements.
- Semi-Automated:Operator-assisted crowd and hoist functions with collision avoidance; bridging technology for autonomy transition.
- Manual:Legacy deployments in artisanal and small-scale mining; shrinking specification tier as labor costs rise.
Continuous operation dominates ultra-class fleet economics. Semi-automated is where technology investment concentrates.
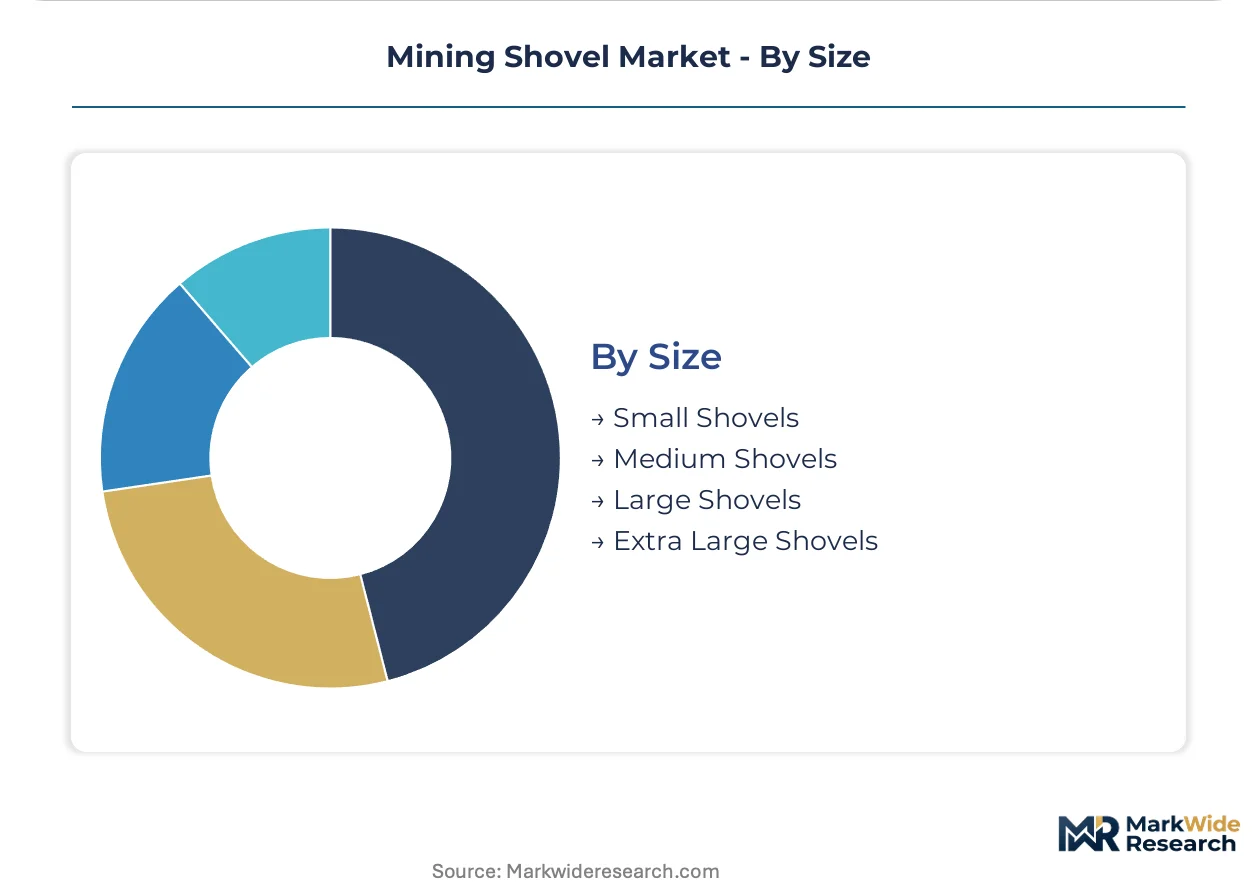
Size:
Payload class stratifies supplier relationships and aftermarket revenue concentration, with extra-large units capturing multi-year availability guarantees.
- Extra Large Shovels:Above 400 tons, these concentrate in iron ore and oil sands where single-machine output dictates fleet economics and justifies embedded telemetry and predictive analytics capabilities.
- Large Shovels:200-400 ton range serving copper and gold applications; performance-based maintenance contracts are displacing time-and-material agreements here.
- Medium Shovels:50-200 tons for selective mining and nickel laterite extraction; SANY Group competes aggressively on delivery speed in this tier.
- Small Shovels:Below 50 tons for quarrying and construction material extraction; price-sensitive segment with compressed margins.
Extra large shovels dominate aftermarket revenue pools. Medium shovels are gaining share fastest in emerging mining jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across mining jurisdictions. Australian iron ore operators absorb premium electric specifications without volume hesitation, while Indonesian nickel contractors optimize around mid-tier hydraulic delivery speed and capital efficiency.
Australia
Western Australia's Pilbara iron ore district commands ultra-class shovel deployments above 500 tons. EPA standards and state-level decarbonization roadmaps accelerate diesel-to-electric conversions. Perth-based equipment lessors structure project finance around grid-integrated powertrain specifications.
Chile
Copper producers in the Atacama Desert pursue deeper ore body access through 400-ton-plus electric fleet renewals. The Ministry of Mining's emission reduction protocols tighten diesel equipment permitting. Antofagasta and Calama anchor shovel demand concentration for Codelco and private operators.
China
Northern coal basins in Shanxi and Inner Mongolia face accelerated hydraulic fleet retirement under MIIT GB 36886 enforcement. State-owned miners redirect capital toward compliant electric specifications. Xuzhou and Changzhou fabrication clusters supply domestic mid-tier replacement demand.
Indonesia
Battery-grade nickel projects in Sulawesi and Halmahera require selective mining capabilities favoring hydraulic articulation. The Ministry of Energy and Mineral Resources coordinates domestic content requirements for mining equipment procurement. Morowali Industrial Park concentrates mid-tier shovel deployment for laterite extraction.
Peru
Southern copper belt operators in Arequipa and Cusco specifications mirror Chilean ultra-class trends. The Ministry of Environment's mining sector emission inventories pressure diesel fleet phase-outs. Cerro Verde and Antamina anchor electric shovel demand for porphyry copper operations.
Mining Shovel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the mining shovel market. Integrated powertrain manufacturers command premium positioning in electric-drive segments above 500 tons, while mid-tier hydraulic specialists compete on delivery compression and capital efficiency. Three archetypes dominate: utility-integrated project finance providers, autonomous haulage compatibility platforms, and emerging-market speed-to-site fabricators. Competitive moves concentrate on backward integration into foundry and motor winding supply, plus multi-year availability guarantee contracts that unbundle equipment purchase from lifecycle support.
Within the integrated powertrain tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by captive manufacturing scope and fleet management platform reach. SANY Group exemplifies the emerging-market speed archetype, anchoring competitive positioning around delivery velocity for mid-tier hydraulic specifications in jurisdictions with compressed project timelines.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| Liebherr Group |
| Hitachi Construction Machinery |
| Epiroc AB |
| SANY Group |
| XCMG Group |
| Doosan Infracore |
| Sandvik AB |
| Others |
Supply & Pricing Matrix
Solid-state rectifier systems replacing mechanical Ward Leonard drive sets are redrawing supply geography toward motor-winding clusters in Germany and Japan while compressing maintenance-contract pricing premiums that previously justified electric-drive capital intensity. This substitution dynamic simultaneously concentrates procurement leverage among grid-integrated mine operators and fragments pricing power for legacy hydraulic service networks.
Pricing Analysis
Performance-based maintenance contracts now drive lifetime value, displacing time-and-material agreements for ultra-class fleets. Three-tier pricing structure across premium, standard, and economy levels separates embedded-telemetry electric specifications from basic hydraulic units and legacy diesel conversions. Price differentiation hinges on predictive analytics bundling and regional grid reliability. Cost compression in mid-tier hydraulic segments is intensifying because SANY Group and XCMG Group compete on delivery velocity. Contractor fleets show highest price sensitivity; Pilbara iron ore operators absorb premium electric specifications without volume hesitation.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes are elevating inbound logistics costs for cast dipper and boom fabrications. Supply concentrates in China, Germany, and South Korea for AC drive motors and solid-state power electronics. Raw material dependencies include copper for motor windings, high-grade steel for structural components, and rare earth elements for permanent magnet systems. Single-source vulnerability concentrates in specialized foundry capacity for 400-ton-plus dipper castings. Distribution runs through OEM direct sales for electric specifications and dealer networks for hydraulic units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware sales as iron ore and copper producers unbundle equipment purchase from multi-year availability guarantees. Predictive maintenance contracts and embedded telemetry subscriptions now capture margin pools that previously accrued to aftermarket parts distributors.
For Market Incumbents: Consolidate backward integration into motor winding and foundry supply to defend against emerging-market speed specialists. Captive manufacturing of AC drive systems and solid-state rectifiers protects margin pools as Chinese fabricators compress delivery timelines for mid-tier hydraulic units. Lock in grid-integrated project finance relationships with Australian and Chilean operators before emission enforcement accelerates fleet renewal cycles.
For New Entrants and Emerging Players: Anchor in Indonesian nickel laterite extraction where selective mining requirements favor hydraulic articulation and domestic content rules create procurement friction for established OEMs. Battery-grade nickel projects in Sulawesi and Halmahera represent underpenetrated white space for mid-tier 50-200 ton specifications. Pursue speed-to-site delivery contracts with compressed lead times as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated powertrain manufacturers with captive electric-drive supply chains. Long-term viability over the next decade rests on embedded telemetry capabilities and predictive analytics platforms that capture recurring service revenue. Target acquisition archetypes include autonomous haulage compatibility specialists and foundry operators with 400-ton-plus casting capacity. Watch EPA Tier 4 Final and EU Stage V enforcement timelines as inflection indicators for diesel fleet retirement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Winding | Caterpillar and Komatsu secure captive AC drive supply against copper price volatility. |
| Autonomous Haulage Compatibility Investment | Unified fleet management platforms capture shovel-to-truck interoperability standards in Pilbara operations. |
| Performance-Based Maintenance Contract Expansion | Iron ore producers unbundle equipment purchase from multi-year availability guarantees with OEM service divisions. |
| Indonesian Domestic Content Partnership | Morowali Industrial Park procurement rules favor local assembly joint ventures for nickel laterite extraction. |
| Solid-State Rectifier Platform Standardization | Regenerative braking energy recovery compresses maintenance intervals versus mechanical Ward Leonard systems. |
Research Methodology
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this study. Primary fieldwork across mining jurisdictions combined with secondary validation from customs and trade data, SEC filings, and equipment registration databases. Bottom-up triangulation against top-down macroeconomic indicators ensured segmentation integrity across powertrain architectures and payload classes.
Sensitivity analysis tested forecast outputs against copper price volatility, grid infrastructure buildout assumptions, and emission enforcement timelines. The analytical framework modeled powertrain type, payload capacity tier, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derived from historical shipment data and replacement cycle analysis incorporated mine development pipeline tracking and fleet age distribution inputs.
Decision-makers should treat outputs as directional under assumptions of sustained copper demand and progressive emission enforcement; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding grid reliability and fuel price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Global Dozers Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Mining Drill Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Surface Drilling Rig Market