
 Hydraulic Seals Market | 2026-2036
Hydraulic Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Seals Market Intelligence
Specialized industrial distribution is reconfiguring around regional service centers that stock customized seal kits for just-in-time maintenance. Parker Hannifin Corporation leverages its captive distribution network to control specification conversations with fleet operators. SKF Group sustains engineering-led sales through diagnostic tools that predict seal degradation intervals. Freudenberg Sealing Technologies anchors European aftermarket channels with material science expertise in fluoroelastomer compounds.
Hydraulic seals are precision-machined or molded elastomeric components designed to prevent fluid leakage between reciprocating or rotating surfaces in pressurized systems, typically operating at pressures from 3,000 to 10,000 psi depending on construction and aerospace grades. Their primary purpose is maintaining system efficiency, preventing contamination ingress, and extending actuator service life in mobile and stationary hydraulic equipment. Rod seals command durable replacement demand due to continuous exposure to external abrasion in construction and mining machinery, while polyurethane formulations capture preference in high-pressure industrial equipment for superior extrusion resistance. O-rings retain volume leadership across maintenance channels though margin pools concentrate in application-specific piston seal geometries for aerospace and defense platforms.
FDA regulations govern seals deployed in food processing hydraulics, REACH restricts phthalate plasticizers in European-sourced compounds, and China's GB standards mandate pressure-testing protocols for imported sealing assemblies. These frameworks elevate compliance costs for commodity producers while rewarding suppliers with certified material traceability systems. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions as regulators scrutinize fluoropolymer seal chemistries.
Market Dynamics
EPA emissions standards and REACH chemical compliance are compressing specification cycles for hydraulic seals, forcing compound reformulation and certified material traceability as table stakes for supplier qualification across construction and aerospace channels.
Growth Catalysts
- Construction machinery replacement cycles:Fleet operators across China's industrial equipment sector are accelerating seal kit procurement as domestic OEMs expand hydraulic component sourcing.
- Fluoroelastomer material science advances:Aerospace and defense platforms demand application-specific piston seal geometries with superior extrusion resistance at 10,000 psi operating pressures.
- REACH compliance elevation:Phthalate plasticizer restrictions in European-sourced compounds are rewarding suppliers with certified material traceability systems and technical documentation capabilities.
Market Restraints
- Fluoropolymer chemistry scrutiny:Per- and polyfluoroalkyl substance restrictions under evolving EPA frameworks are elevating compliance costs for commodity producers without certified reformulation pipelines.
- Polyurethane feedstock volatility:MDI and polyether polyol price swings compress margin pools for high-pressure industrial equipment seal manufacturers.
- Precision machining concentration:Multi-axis CNC capacity for aerospace-grade seal geometries clusters in Germany and Japan, creating supply bottleneck risks for qualified component sourcing.
Strategic Opportunities
- Diagnostic-enabled predictive maintenance:Engineering-led sales through seal degradation interval prediction tools are capturing specification conversations with fleet operators in mining and construction.
- Food processing hydraulics certification:FDA-regulated seal deployments in beverage and dairy equipment represent underpenetrated margin pools for fluoroelastomer compound specialists.
- Just-in-time regional service center networks:Customized seal kit stocking at proximity maintenance hubs is displacing centralized distribution for mobile hydraulic equipment operators.
Industry Challenges
- Compound formulation talent scarcity:Fluoroelastomer compounding expertise concentrates with aging technical workforces in European and Japanese material science centers.
- Multi-standard certification timelines:Simultaneous GB standard pressure-testing, REACH chemical compliance, and FDA material approval processes extend product launch cycles by 18-24 months.
- Legacy system geometry lock-in:Existing actuator designs in installed construction machinery fleets constrain seal profile innovation and limit premium compound adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Seals Market |
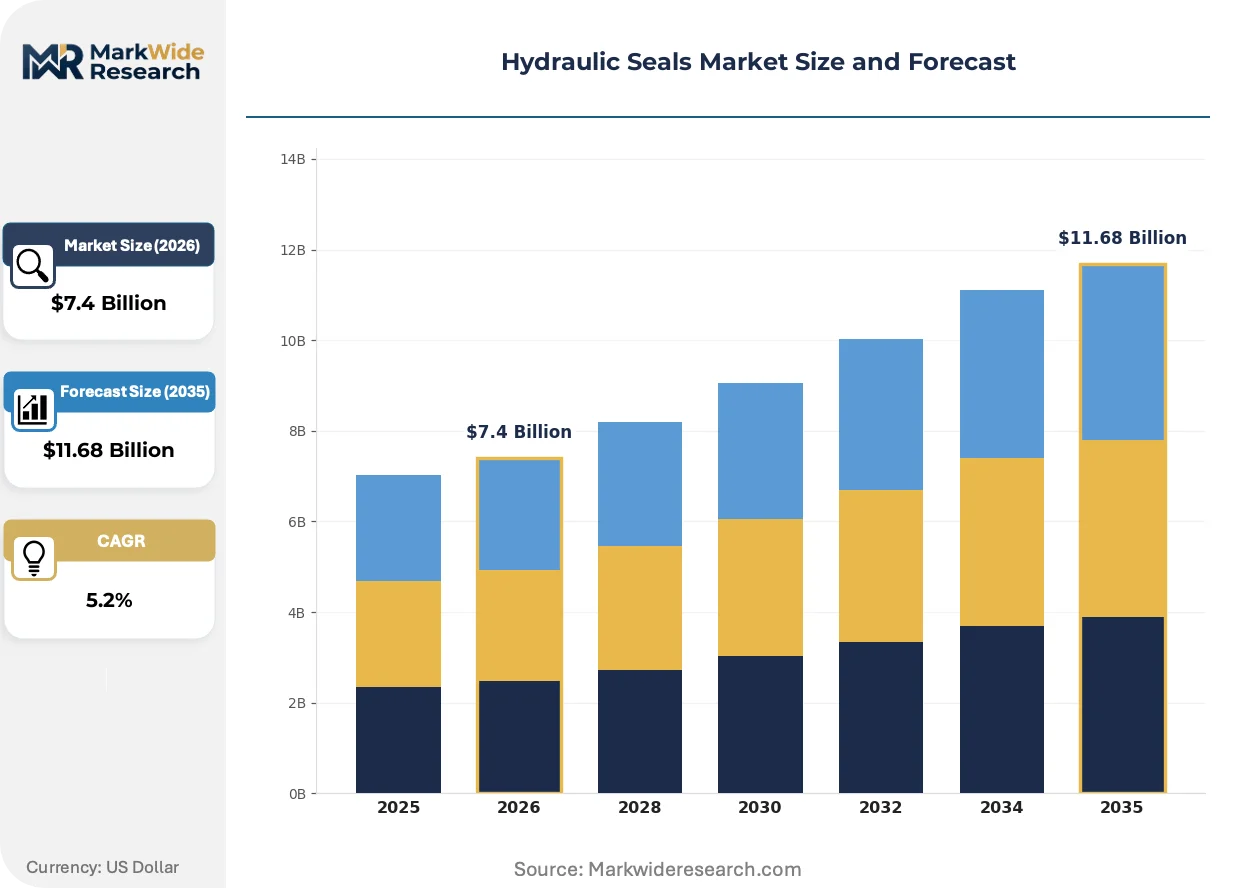
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.68 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Rod Seals, Piston Seals, Gaskets Material: Nitrile, Polyurethane, Viton, Silicone End User: Aerospace, Automotive, Manufacturing, Oil & Gas Application: Industrial Equipment, Construction Machinery, Automotive Systems, Marine |
| Companies Covered | SKF Group, NOK Corp., Parker Hannifin Corporation, Hydac International, Greene Tweed & Co, Trelleborg AB, Hallite Seals International Ltd., Kastas Sealing Technologies, Freudenberg Sealing Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Seals Market Strategic Shifts & Innovations
Digital specification tools and predictive degradation analytics are compressing traditional distributor-led sales cycles, while material science advances in perfluoroelastomer compounds open temperature and chemical resistance envelopes previously unreachable with standard fluoroelastomer formulations.
Perfluoroelastomer seal compounds with operating temperatures extending to 325°C are rendering obsolete standard FKM formulations in aerospace hydraulic actuators and semiconductor manufacturing equipment. Defense contractors and wafer fabrication facilities are specifying these materials for critical sealing positions despite 4-6x cost premiums. The technology is rendering obsolete decade-old material selection heuristics that prioritized cost over thermal stability in high-reliability applications.
REACH Annex XVII restrictions on intentionally added microplastics are forcing compounders to eliminate PTFE micropowder fillers from polyurethane seal formulations. Industrial hydraulic equipment manufacturers must recertify extrusion-resistant rod seal designs under revised compound specifications. European mobile machinery OEMs are responding by qualifying alternative nano-ceramic filler systems that maintain extrusion resistance without regulatory exposure.
Fleet operators are consolidating seal procurement through integrated maintenance management platforms that bypass traditional industrial distributor channels. Construction and mining equipment lessors are unbundling seal replacement from OEM service contracts, directing volume to specialized seal kit suppliers with regional stocking capabilities. This pattern concentrates in China's domestic equipment fleet market where state-owned construction groups centralize hydraulic system maintenance procurement.
Hydraulic Seals Market Segmentation
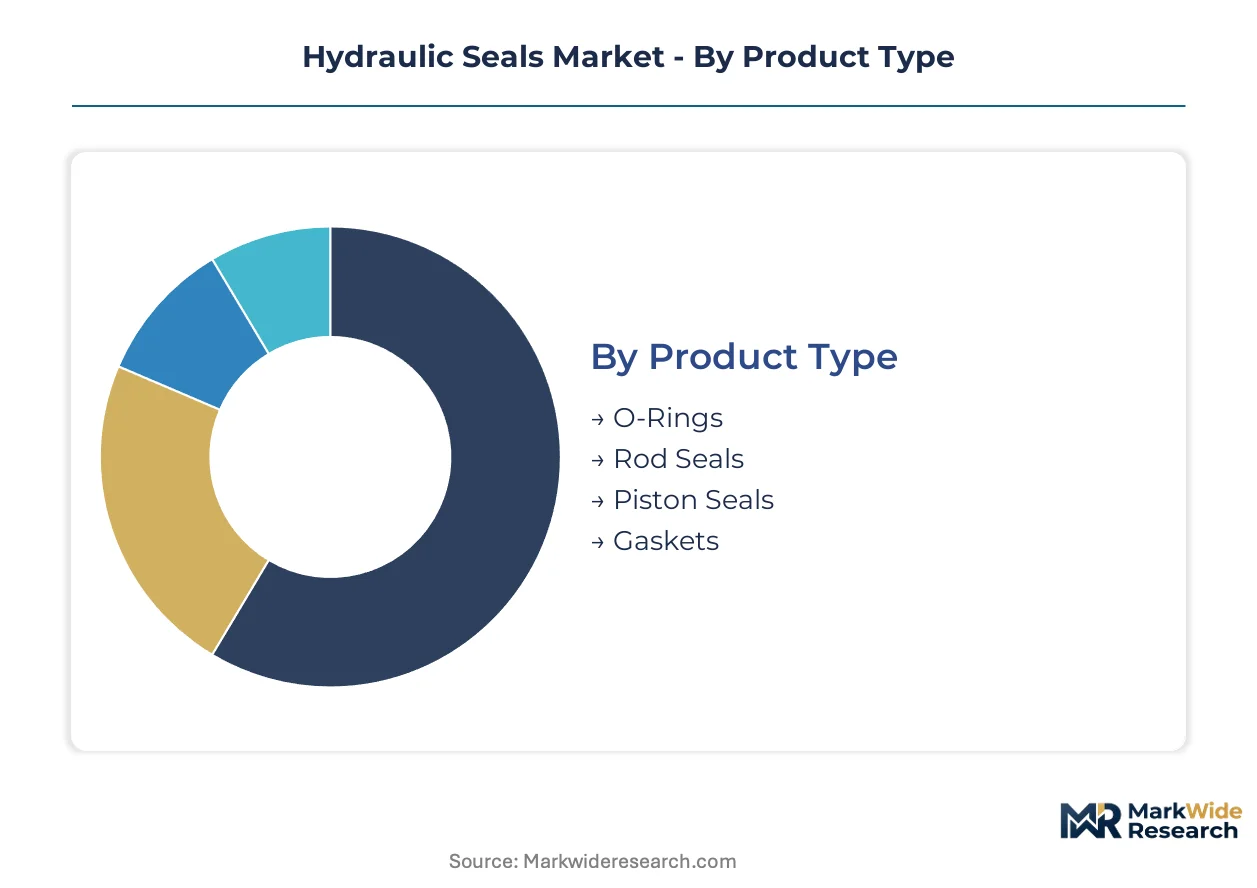
Hydraulic seal procurement patterns diverge sharply across replacement cycles, with construction fleets prioritizing rod seal availability while aerospace contractors demand certified piston seal geometries. Segmentation reveals how material specification, end-use reliability requirements, and regional regulatory compliance reshape supplier qualification pathways.
Product Type:
After-sales service intensity varies dramatically by seal geometry, with rod seals demanding continuous field replacement support while O-rings flow through commodity distribution channels.
- Rod Seals:These precision-machined elastomeric components prevent fluid leakage along reciprocating actuator shafts in construction and mining equipment. Fleet operators in China's industrial equipment sector accelerate procurement cycles as domestic OEMs expand hydraulic component sourcing, driving replacement demand from continuous external abrasion exposure.
- O-Rings:Molded circular elastomeric profiles provide static and dynamic sealing across low-to-moderate pressure hydraulic interfaces. Volume leadership concentrates in maintenance channels serving general industrial equipment, though margin pools remain thin without application-specific certification.
- Piston Seals:Complex geometries seal pressurized fluid between piston and cylinder bore in directional control applications. Aerospace and defense platforms specify these components for 10,000 psi operating pressures with superior extrusion resistance requirements.
- Gaskets:Static sealing elements prevent leakage between mating flanges in hydraulic manifold assemblies. Demand clusters in stationary industrial equipment with extended service intervals and lower replacement frequency.
Rod seals hold the largest share; momentum sits with piston seals as aerospace specification cycles compress.
Material:
Cost tiers separate commodity nitrile compounds from certified fluoroelastomer formulations required for high-temperature aerospace applications.
- Polyurethane:Thermoset elastomer formulations deliver superior extrusion resistance and abrasion tolerance in high-pressure industrial equipment. MDI and polyether polyol feedstock volatility compresses margin pools for manufacturers serving construction machinery fleets.
- Viton:Fluoroelastomer compounds withstand aggressive hydraulic fluids and temperature extremes to 200°C in aerospace actuators. REACH phthalate plasticizer restrictions elevate compliance costs while rewarding suppliers with certified material traceability systems.
- Nitrile:Acrylonitrile-butadiene rubber dominates general-purpose hydraulic sealing with balanced oil resistance and cost economics. Commodity producers face margin pressure from multi-standard certification timelines extending product launches.
- Silicone:Polysiloxane-based elastomers maintain flexibility across extreme temperature ranges in food processing and medical hydraulic systems. FDA regulations govern deployment in beverage and dairy equipment with specialized compliance documentation.
Nitrile captures volume leadership; Viton climbs the fastest on aerospace specification upgrades.
End User:
Application maturity determines whether procurement flows through OEM captive supply or independent aftermarket channels.
- Aerospace:Defense contractors and commercial aviation OEMs demand perfluoroelastomer seals with 325°C temperature tolerance despite substantial cost premiums. Multi-axis CNC capacity for precision geometries clusters in Germany and Japan, creating qualified component sourcing bottlenecks.
- Construction Machinery:Fleet operators consolidate procurement through integrated maintenance management platforms that bypass traditional industrial distributors. State-owned construction groups in China centralize hydraulic system maintenance procurement.
- Automotive:Hydraulic steering and braking systems specify molded seals with high-volume production economics. EPA emissions standards compress specification cycles forcing compound reformulation for supplier qualification.
- Oil & Gas:Downhole and surface equipment demands chemical-resistant compounds for hydrocarbon exposure. REACH Annex XVII microplastic restrictions force PTFE filler elimination from polyurethane formulations.
Construction machinery holds the largest share; aerospace gains share fastest on thermal stability requirements.
Application:
Geographic concentration of installed equipment fleets dictates regional service center stocking strategies for customized seal kits.
- Construction Machinery:Mobile equipment fleets across Asia-Pacific drive seal replacement cycles with just-in-time maintenance requirements. Regional service centers stock customized kits displacing centralized distribution.
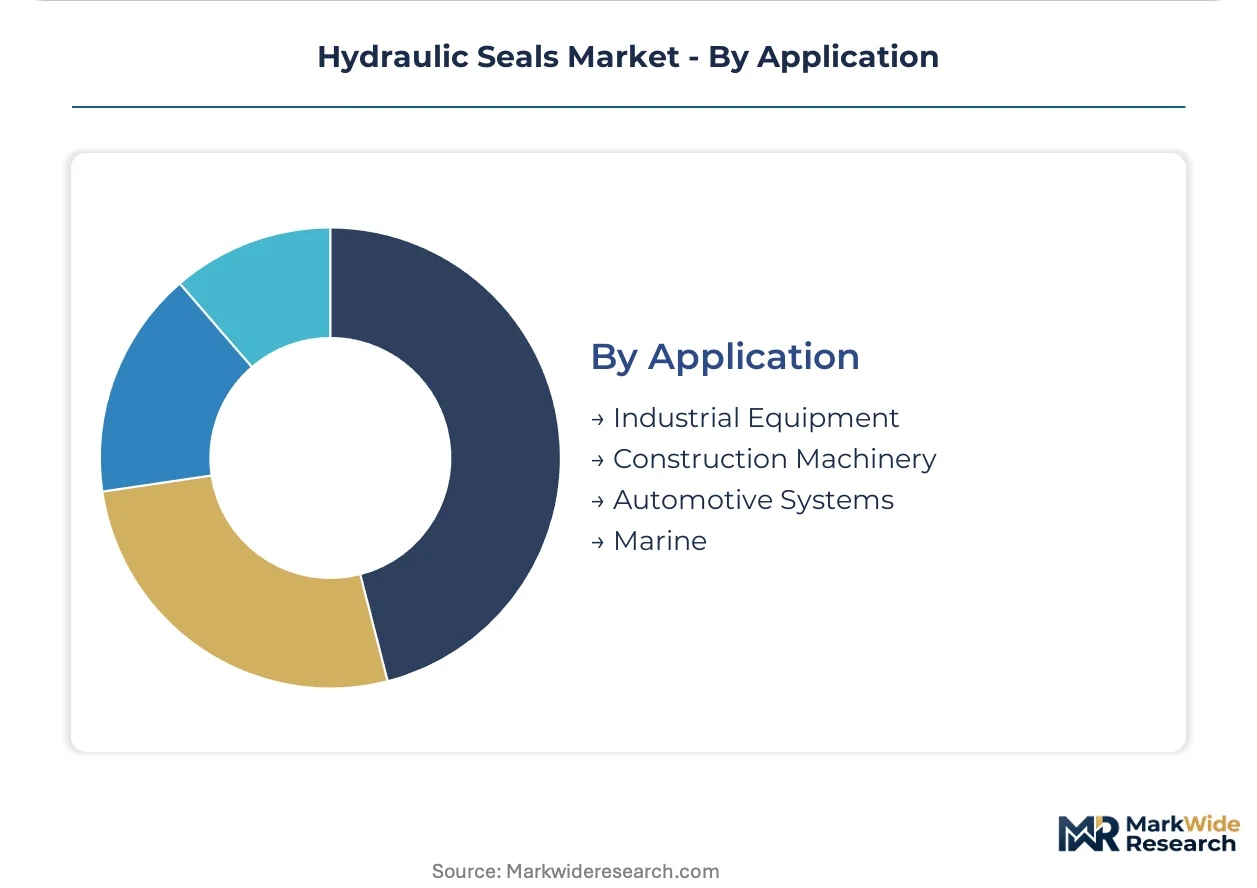
- Industrial Equipment:Stationary hydraulic presses and machine tools specify polyurethane formulations for 3,000-10,000 psi operating pressures. Manufacturing sector demand concentrates in China's domestic OEM supply chain expansion.
- Automotive Systems:Power steering racks and brake hydraulic circuits require precision-molded seals with high-volume cost structures. OEM service contract unbundling directs volume to specialized seal kit suppliers.
- Marine:Offshore and commercial vessel hydraulics face saltwater corrosion and biofouling challenges. Specialized fluoroelastomer compounds address extended service intervals in remote operating environments.
Industrial equipment holds the largest share; construction machinery expands most quickly on fleet replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions standards and REACH chemical compliance are elevating material specification requirements for hydraulic systems across major industrial economies. Construction machinery fleets drive seal replacement cycles with distinct regional patterns. Manufacturing clusters concentrate precision-machining capacity for aerospace-grade components.
China
Domestic OEMs expanding hydraulic component sourcing accelerate seal kit procurement from state-owned construction groups. GB standards mandate pressure-testing protocols for imported sealing assemblies. Yangtze River Delta manufacturing hubs concentrate polyurethane formulation capacity for high-pressure industrial equipment.
Germany
Multi-axis CNC capacity for aerospace-grade seal geometries clusters around Stuttgart and Munich precision engineering centers. REACH Annex XVII microplastic restrictions force PTFE filler elimination from polyurethane formulations. Baden-Württemberg suppliers recertify extrusion-resistant rod seal designs under revised compound specifications.
United States
Defense contractors specify perfluoroelastomer seals with 325°C temperature tolerance for aerospace hydraulic actuators. FDA regulations govern seal deployments in food processing hydraulics across Midwest dairy equipment manufacturers. Houston-area oilfield service firms demand chemical-resistant compounds for hydrocarbon exposure.
Japan
Fluoroelastomer compounding expertise concentrates with aging technical workforces in Nagoya and Osaka material science centers. METI industrial policy supports domestic supply chain resilience for critical sealing components. Kanto region precision molders serve semiconductor manufacturing equipment with temperature-extreme formulations.
India
Construction machinery fleet operators consolidate procurement through integrated maintenance management platforms. BIS standards elevate compliance documentation requirements for imported sealing assemblies. Gujarat industrial corridors attract seal kit suppliers establishing regional stocking capabilities for mobile hydraulic equipment.
Hydraulic Seals Market Key Industry Players
On the supply side, the industry is consolidating around material science specialists with certified traceability systems and precision-machining capabilities. The vendor base separates into three strategic archetypes: integrated motion control conglomerates with captive distribution networks, dedicated sealing technology specialists with formulation expertise, and regional fabricators serving aftermarket maintenance channels. Dominant competitive moves include backward integration into polymer compounding operations and geographic expansion through proximity service center networks.
Among European material science specialists, Freudenberg Sealing Technologies and Trelleborg AB exemplify the formulation-led archetype with fluoroelastomer compound capabilities. SKF Group occupies a position representing the integrated engineering services model, leveraging diagnostic tools to anchor specification conversations. These three entities sit within distinct competitive vectors—compound specialization, systems integration, and predictive maintenance enablement—rather than direct product substitution competition.
| Leading Market Players |
|---|
| SKF Group |
| NOK Corp. |
| Parker Hannifin Corporation |
| Hydac International |
| Greene Tweed & Co |
| Trelleborg AB |
| Hallite Seals International Ltd. |
| Kastas Sealing Technologies |
| Freudenberg Sealing Technologies |
| Others |
Cost & Logistics Intelligence
Stuttgart precision engineering clusters anchor aerospace-grade seal machining capacity, concentrating pricing power among German and Japanese suppliers who command premiums for qualified multi-axis CNC output. This geographic concentration of certified material traceability systems shapes downstream contract structures, with REACH-compliant fluoroelastomer compounds carrying substantial cost premiums over commodity nitrile alternatives.
Pricing Analysis
Certification level creates the primary spread between commodity and premium tiers, with FDA-grade silicone and REACH-certified Viton formulations commanding three to four times nitrile economics. Three-tier pricing structure separates aerospace-qualified perfluoroelastomers from industrial-grade polyurethane and economy nitrile for general maintenance. Cost compression in standard rod seal categories is intensifying because Chinese domestic OEMs are expanding captive sourcing. Fleet operators in construction machinery exhibit highest price sensitivity, while defense contractors demonstrate lowest sensitivity due to reliability mandates.
Supply Chain Analysis
Freudenberg and Trelleborg manufacturing footprints concentrate European fluoroelastomer compounding, while NOK and Japanese precision molders anchor Asian capacity for semiconductor and aerospace applications. Raw material flows draw from German MDI suppliers for polyurethane formulations, Belgian fluoropolymer feedstocks for aerospace grades, and Chinese acrylonitrile for nitrile rubber. Single-source vulnerability concentrates in Nagoya and Osaka technical centers where aging workforces threaten fluoroelastomer expertise continuity. Distribution runs through Parker Hannifin's captive network and SKF's engineering-led channels alongside specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fluoroelastomer compounding expertise resides with shrinking technical workforces in European and Japanese material science centers, constraining supply expansion and elevating acquisition premiums for qualified formulation capabilities.
For Market Incumbents: Insulate formulation expertise through targeted retention programs and knowledge-capture systems before technical workforce attrition accelerates. Deepen backward integration into polymer compounding to secure captive supply of REACH-compliant feedstocks. Prioritize regional service center expansion in China's Yangtze River Delta to intercept fleet operator procurement consolidation. For New Entrants and Emerging Players: Build out nano-ceramic filler system capabilities to capture European OEM demand displaced by REACH Annex XVII PTFE restrictions. Target India's Gujarat industrial corridors for regional stocking infrastructure serving mobile hydraulic equipment. Pursue diagnostic-enabled predictive maintenance partnerships with construction equipment lessors to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors material science specialists with certified traceability systems over commodity fabricators facing margin compression. Long-term viability hinges on fluoroelastomer compounding depth and multi-standard certification infrastructure rather than volume scale. Monitor EPA per- and polyfluoroalkyl substance restriction timelines as inflection signal for compound reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive REACH-compliant feedstock supply secures margin protection against regulatory escalation. |
| Regional Service Center Expansion | Proximity stocking in China's industrial corridors intercepts fleet operator procurement consolidation. |
| Diagnostic Tool Development | SKF-style predictive maintenance platforms capture specification conversations with mining operators. |
| Perfluoroelastomer Capacity Addition | Temperature-extreme formulations address aerospace and semiconductor equipment upgrade cycles. |
| Multi-Standard Certification Investment | Simultaneous GB, REACH, and FDA approval capability compresses rival product launch timelines. |
Research Approach
A spread of perspectives from maintenance directors at construction fleet operators, OEM procurement teams, fluoroelastomer compound technical leads, and aftermarket service heads converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed sealing specialists, REACH Annex XVII regulatory notices, and GB standard pressure-testing protocols. Bottom-up equipment fleet analysis and top-down industrial production indices were triangulated to anchor volume estimates.
Demand-supply balance modeling across the projection horizon incorporated segmentation by seal geometry, material grade tier, end-use industry, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and OEM sourcing expansion patterns rather than extrapolation. Industry-specific forecast inputs included construction machinery fleet age distributions and aerospace platform specification upgrade pipelines.
Stress conditions across MDI-polyether polyol feedstock volatility, EPA fluoropolymer restriction severity, and Chinese domestic OEM sourcing capture were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technical workforce attrition rates and multi-standard certification timeline extensions. Quarterly review of REACH Annex XVII amendment proposals and perfluoroalkyl substance regulatory developments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Resistance Welding Products Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Hooklifts Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Precision Ballscrews Market
Material Handling Equipment
Explosion Proof Crane Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Stacker Crane Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Stacker Market
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Outdoor Power Equipment (OPE) Market