
 Hydraulic Drilling Rig Market | 2026-2036
Hydraulic Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Drilling Rig Market Insights
North American rig fabricators is realigning capacity toward high-pressure hydraulic systems as exploration depths extend below 15,000 feet. Epiroc AB leverages its automation portfolio to dominate underground mining rig configurations. Caterpillar Inc. sustains manufacturing scale through captive engine-hydraulic integration. Sandvik AB differentiates through drill string telemetry that reduces non-productive time.
A hydraulic drilling rig employs pressurized fluid circuits to transmit torque and thrust to downhole drill bits, typically operating at pressures exceeding 3,000 psi and flow rates calibrated to formation hardness. These systems serve primarily to advance boreholes for mineral extraction, hydrocarbon recovery, and subsurface characterization. Crawler rigs anchor the product mix in rough-terrain mining sites where flotation and gradeability determine deployment economics, while truck-mounted rigs capture share in urban construction boring where highway mobility reduces mobilization cost. Automated control systems represent the fastest-expanding technology segment as operators reduce reliance on manual pipe handling in high-risk environments.
OSHA drilling safety standards and EPA emissions frameworks shape equipment specifications in the United States, while the EU Green Deal and F-Gas Regulation constrain hydraulic fluid chemistries in European deployments. The International Organization for Standardization (ISO) 18758 certification for surface drilling rigs increasingly gates market access for export-oriented manufacturers. Stakeholders must monitor how methane intensity benchmarks and carbon border adjustments reshape total cost of ownership calculations for fleet replacement decisions.
Market Dynamics
EPA methane emissions rules are forcing fleet replacement cycles in the Permian Basin as contractors retire legacy pneumatic systems ahead of compliance deadlines. This regulatory compression is redrawing capital allocation across North American shale plays.
Growth Catalysts
- Pad drilling density:Multi-well pad configurations in Texas shale plays require higher-specification hydraulic systems capable of sequential lateral drilling without rig mobilization.
- EU F-Gas Regulation:European contractors face mandatory hydraulic fluid chemistry transitions, creating replacement demand for compliant rig configurations in Germany and Poland mining corridors.
- Underground automation:Mining operators in Chile and Australia are specifying autonomous rod handling systems to reduce exposure in high-risk extraction depths.
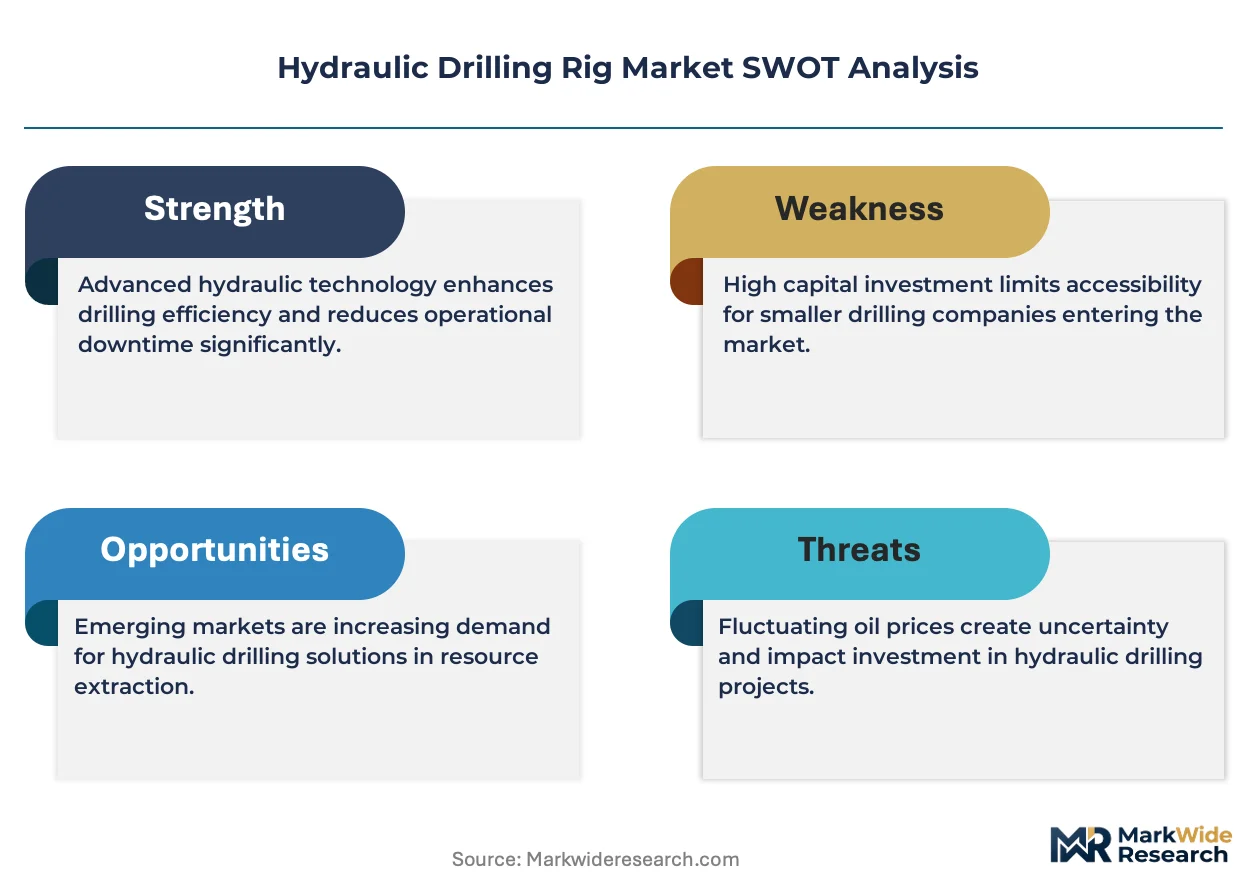
Market Restraints
- Steel alloy supply concentration:High-pressure cylinder manufacturing depends on specialized chromium-molybdenum feedstock sourced primarily from Chinese and Russian metallurgical suppliers.
- Technical limitation at extreme depth:Hydraulic seal integrity degrades beyond 20,000 feet equivalent circulating density, constraining ultra-deep exploratory drilling.
- OSHA silica exposure standards:Dust suppression retrofit requirements add capital burden to legacy crawler rig fleets operating in granite and sandstone formations.
Strategic Opportunities
- Geothermal energy expansion:Germany and France are tendering closed-loop binary systems requiring adapted hydraulic rig specifications for sedimentary heat reservoir access.
- Drill string telemetry convergence:Integration of real-time vibration sensors with automated weight-on-bit control enables predictive maintenance contracts in Scandinavian tunnelling projects.
- IRA clean energy tax credits:US geothermal and carbon capture well construction qualifies for investment incentives, redirecting oilfield service capacity toward low-carbon applications.
Industry Challenges
- ISO 18758 certification timeline:Surface rig manufacturers face 18-24 month approval cycles for export markets, delaying revenue recognition on international orders.
- Electro-hydraulic technician scarcity:Automated control systems require cross-trained personnel capable of diagnosing both PLC logic and high-pressure mechanical faults.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Drilling Rig Market |
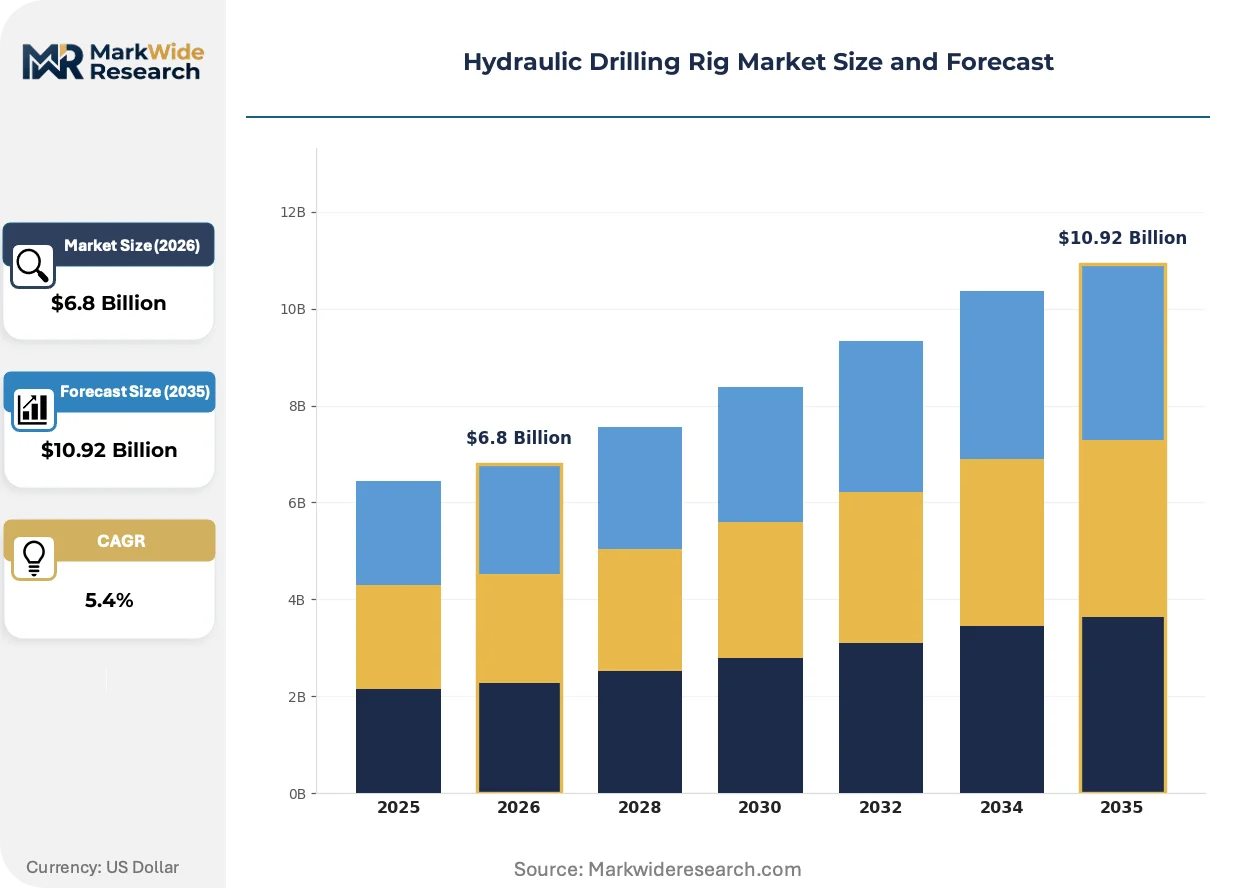
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crawler Rigs, Truck-Mounted Rigs, All-Terrain Rigs, Skid Rigs, Pod Rigs Technology: Automated Control Systems, Remote Monitoring, Pressure Control, Mud Circulation, Torque Monitoring Application: Mining, Geotechnical Investigations, Construction Boring, Water Well Drilling, Seismic Exploration End User: Mining Contractors, Construction Firms, Energy Developers, Geological Surveyors, Environmental Agencies |
| Companies Covered | Caterpillar Inc., Furukawa Rock Drill Co. Ltd., Epiroc AB, Weir Group, Xuzhou Construction Machinery Group, Atlas Copco AB, Boart Longyear Group Ltd., Junjin CSM, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Drilling Rig Market Trends and Innovations
Electrification of auxiliary power systems is compressing the traditional engine-hydraulic bundling model. Equipment buyers now specify modular architectures that accommodate future battery-hybrid retrofits without structural modification.
Variable displacement pump technology is decentralizing power distribution across multi-function rig circuits. Epiroc and Sandvik are deploying intelligent load-sensing systems that match hydraulic output to real-time bit torque requirements. This architecture eliminates centralized manifold complexity and reduces parasitic energy loss by isolating idle circuits during single-function operations.
The EU Green Deal's carbon border adjustment mechanism is reshaping equipment import economics. European contractors now face embedded carbon audits on rig purchases from non-EU fabricators, accelerating localization of final assembly in Poland and Romania. North American exporters must document Scope 3 emissions or absorb tariff penalties on cross-Atlantic sales.
Service contracting is fragmenting from bundled maintenance toward component-level subscription models. Large mining houses in Western Australia and Chile are unbundling hydraulic system overhauls from OEM service agreements, instead sourcing aftermarket cylinder rebuilds from independent fluid power specialists. This disintermediation compresses OEM spare parts margins while expanding third-party certification requirements.
Hydraulic Drilling Rig Market Segmentation
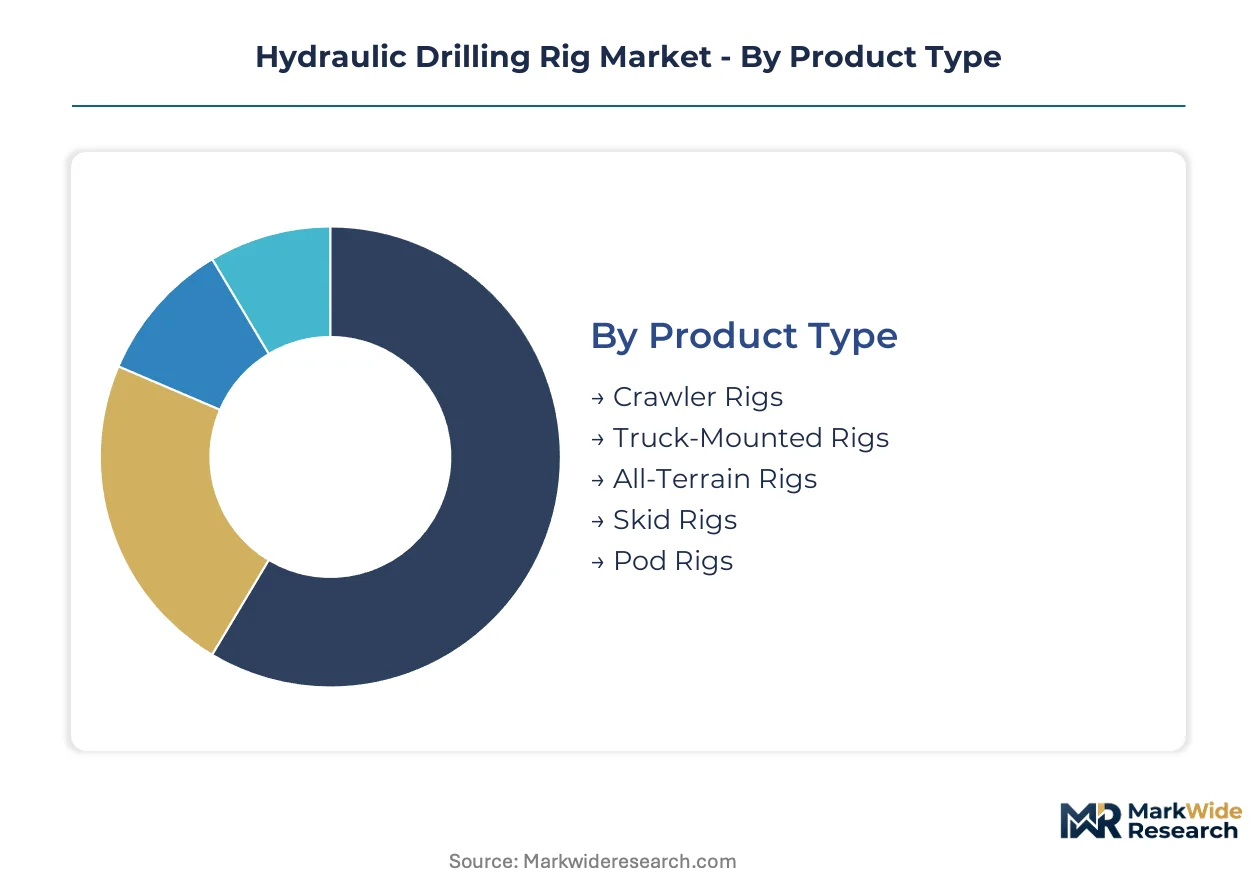
Segmentation in hydraulic drilling rigs reflects divergent certification burdens across deployment environments. Mining operations in Chile and Australia demand ISO 18758 compliance plus autonomous safety protocols, while construction boring in Texas prioritizes OSHA silica standards and EPA emissions certification.
Product Type:
ISO 18758 certification applies universally to surface rig configurations, though crawler and truck-mounted variants face additional OSHA and EPA layering in US deployments.
- Crawler Rigs:Tracked undercarriage systems deliver flotation and gradeability exceeding 35% slopes in rough-terrain mining sites. Australian iron ore operators in the Pilbara specify these for autonomous haulage integration. Demand concentrates in Western Australia and northern Chile where pit geometry rewards mobility over highway transit.
- Truck-Mounted Rigs:Highway-legal chassis reduce mobilization cost for urban geotechnical contracts. Texas construction firms deploy these for rapid site rotation across Dallas-Fort Worth infrastructure corridors. EPA methane compliance adds retrofit burden to legacy pneumatic auxiliary systems.
- All-Terrain Rigs:Articulated carriers bridge crawler flotation with truck mobility for Scandinavian tunnelling projects.
- Skid Rigs:Modular platform designs anchor permanent pad drilling configurations in Permian Basin shale plays.
- Pod Rigs:Containerized transport formats serve remote geothermal exploration in Iceland and Kenya Rift Valley.
Crawler rigs sit at the top of the volume ranking, with all-terrain rigs climbing the fastest on tunnelling automation demand.
Technology:
Cost tier stratification separates premium automated systems from baseline mechanical monitoring, with mid-tier remote monitoring capturing share in mid-cap mining operations.
- Automated Control Systems:PLC-driven rod handling and weight-on-bit modulation eliminate manual intervention in high-risk extraction depths. Chilean copper operators specify these for depths exceeding 1,500 meters where rock burst hazards concentrate. Integration with Sandvik drill string telemetry enables predictive maintenance contracting.
- Remote Monitoring:Satellite-linked diagnostics transmit vibration and pressure data to centralized maintenance hubs. Western Australian mining houses unbundle these services from OEM agreements to independent fluid power specialists. Capital burden runs 40-60% below full automation while delivering comparable uptime metrics.
- Pressure Control:Managed pressure drilling circuits maintain annular pressure within narrow windows for geothermal reservoir access.
- Mud Circulation:Closed-loop systems filter drilling fluid for reuse in water-scarce jurisdictions like Saudi Arabia and Nevada.
- Torque Monitoring:Real-time bit torque sensors prevent stuck-pipe incidents in directional shale laterals.
Automated control systems command the premium tier by margin, with remote monitoring expanding most quickly among cost-constrained mid-tier operators.
Application:
Customer type divergence shapes specification: mining contractors prioritize uptime guarantees, while environmental agencies emphasize emissions documentation.
- Mining:Hard-rock extraction in granite, copper, and iron ore formations drives specification for 3,000+ psi hydraulic circuits. Australian and Chilean operators specify autonomous configurations to reduce exposure in high-risk depths. EPA and EU F-Gas Regulation constrain fluid chemistry selection for export-oriented fleet replacements.
- Geotechnical Investigations:Soil sampling and foundation verification require rapid mobilization across dispersed urban sites. German infrastructure tenders specify EU Green Deal compliance documentation for embedded carbon in rig procurement. Truck-mounted configurations dominate for highway mobility.
- Construction Boring:Pile foundation and tunnel pilot hole drilling concentrate in Texas, California, and Florida urban corridors.
- Water Well Drilling:Aquifer access in Sub-Saharan Africa and India favors skid-mounted simplicity over automation.
- Seismic Exploration:Shallow borehole arrays for oil and gas prospecting deploy pod rigs for helicopter transport in remote terrain.
Mining anchors absolute volume, with geotechnical investigations gaining share fastest on infrastructure stimulus in Germany and Poland.
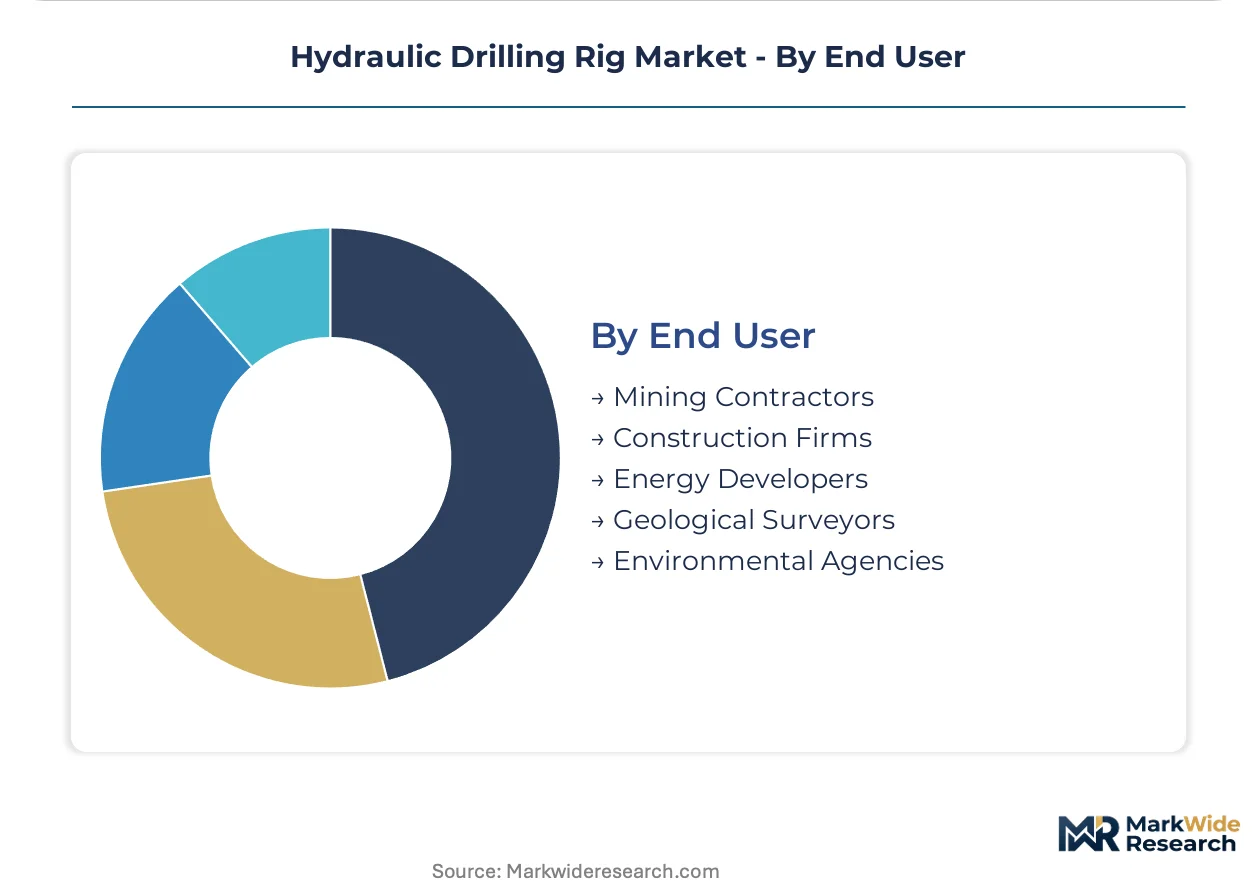
End User:
Supply concentration in high-pressure cylinder manufacturing creates procurement risk differentiation: mining contractors secure long-term metallurgical contracts, while environmental agencies accept spot-market exposure.
- Mining Contractors:Tier-one operators in Western Australia and Chile specify integrated service contracts spanning equipment, maintenance, and telemetry. Backward integration into hydraulic component sourcing defends margin position against Chinese and Russian alloy supply volatility.
- Construction Firms:Fragmented US and German contractors prioritize equipment leasing over ownership to preserve balance sheet flexibility. OSHA silica retrofit requirements concentrate capital burden on legacy crawler fleet operators.
- Energy Developers:Geothermal and carbon capture well construction qualifies for US IRA clean energy tax credits.
- Geological Surveyors:Government-funded mineral resource mapping in Canada and Finland specifies ISO 18758 certification for equipment eligibility.
- Environmental Agencies:Groundwater monitoring and remediation drilling prioritize emissions documentation for EU carbon border adjustment compliance.
Mining contractors dominate procurement volume, with energy developers showing the steepest expansion trajectory on geothermal tendering in Germany and France.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting rig fabrication toward jurisdictions with lower compliance costs. The EU Green Deal's carbon border adjustment mechanism penalizes embedded emissions in imported equipment. North American fabricators exploit this gap by localizing assembly in lower-cost EU accession states.
United States
Permian Basin operators are retiring legacy pneumatic systems ahead of EPA methane compliance deadlines. The IRA extends clean energy tax credits to geothermal and carbon capture well construction. Rig demand concentrates in Texas shale plays and North Dakota where pad drilling density requires higher-specification hydraulic systems.
Germany
EU F-Gas Regulation mandates hydraulic fluid chemistry transitions for mining contractors in the Ruhr and Lusatia corridors. Geothermal tendering for closed-loop binary systems is expanding rig specifications for sedimentary heat reservoir access. Fabricators in North Rhine-Westphalia are localizing final assembly to avoid carbon border tariffs.
Chile
Copper operators in the Atacama Desert specify autonomous rod handling systems for depths exceeding 1,500 meters where rock burst hazards concentrate. The national mining regulator enforces proximity detection standards for underground equipment. Antofagasta and Calama anchor procurement for integrated service contracts spanning equipment and telemetry.
Australia
Iron ore operators in Western Australia's Pilbara region specify crawler rigs for autonomous haulage integration. The national safety regulator mandates ISO 18758 certification for surface drilling equipment. Perth-based mining houses are unbundling hydraulic system overhauls from OEM agreements toward independent fluid power specialists.
Poland
Underground coal and copper mining in the Silesian Voivodeship drives demand for high-pressure hydraulic circuits. EU F-Gas Regulation compliance creates replacement demand for rig configurations in the Katowice mining corridor. Final assembly localization is accelerating as exporters document Scope 3 emissions to avoid tariff penalties.
Hydraulic Drilling Rig Market Competitive Landscape
Swedish and American producers anchor the premium automation tier; Chinese and Japanese specialists hold the standardized equipment segment. The vendor base splits between consolidated engine-hydraulic integrators and fragmented component specialists. Two strategic archetypes dominate: captive vertical integration of power systems and modular telemetry integration. Competitive moves concentrate on geographic capacity relocation and certification pre-positioning for EU carbon border adjustments.
Within the automation-focused tier, Epiroc AB and Sandvik AB exemplify the convergence of drill string telemetry with predictive maintenance contracting. Caterpillar Inc. represents the scale-driven archetype through captive engine-hydraulic bundling. Among Asian fabricators, Xuzhou Construction Machinery Group occupies a position in the cost-optimized crawler rig segment.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Furukawa Rock Drill Co. Ltd. |
| Epiroc AB |
| Weir Group |
| Xuzhou Construction Machinery Group |
| Atlas Copco AB |
| Boart Longyear Group Ltd. |
| Junjin CSM |
| Sandvik AB |
| Others |
Pricing and Supply Chain Analysis
Chromium-molybdenum alloy feedstock flows from Chinese and Russian metallurgical suppliers through high-pressure cylinder fabricators into three distinct equipment tiers, with EPA methane compliance and EU F-Gas Regulation layering certification premiums onto North American and European deliveries.
Pricing Analysis
Distributor margins compress most acutely in the standardized crawler rig segment where Xuzhou Construction Machinery Group and Japanese specialists compete on landed cost. Three-tier pricing structure across premium, standard, and economy levels separates autonomous telemetry-integrated systems from baseline mechanical configurations, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from unbundling trends in Western Australia and Chile where mining houses source aftermarket cylinder rebuilds from independent fluid power specialists. Construction firms in Texas exhibit highest price sensitivity due to fragmented leasing preferences, while tier-one mining contractors in the Pilbara prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Russian chromium-molybdenum suppliers who anchor high-pressure cylinder manufacturing for crawler and truck-mounted rig configurations. Hydraulic pump assemblies and intelligent load-sensing manifolds draw from German, Swedish, and Japanese precision component specialists. Tariff exposure intensifies as the EU Green Deal's carbon border adjustment mechanism penalizes embedded emissions in cross-Atlantic equipment shipments. Distribution runs through OEM-direct channels for integrated automation systems and independent fluid power distributors for aftermarket components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where North American fabricators exploit lower compliance costs by localizing final assembly in Poland and Romania to circumvent EU carbon border tariffs.
For Market Incumbents: Deepen captive engine-hydraulic integration to defend margin position against modular battery-hybrid retrofit architectures that threaten traditional bundling models. Anchor capacity in EU accession states to pre-position for ISO 18758 certification timelines while independent fluid power specialists disintermediate aftermarket service contracts. Prioritize drill string telemetry R&D to sustain predictive maintenance contracting advantages. For New Entrants and Emerging Players: IRA clean energy tax credits in the United States open a window for geothermal and carbon capture well construction equipment specialization. Target the German and French closed-loop binary geothermal tendering pipeline where adapted hydraulic specifications face limited incumbent pre-positioning. Pursue component-level subscription service models to bypass OEM spare parts margin capture. For Investors and Strategic Acquirers: Consolidation pressure builds where electro-hydraulic technician scarcity constrains automated system deployment at scale. Five-to-ten-year viability favors fabricators with demonstrated EU F-Gas Regulation compliance pathways and localized assembly documentation. Watch for inflection where carbon border adjustment enforcement accelerates Scope 3 emissions disclosure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Mitigates Chinese and Russian chromium-molybdenum concentration risk for high-pressure cylinder production. |
| EU Assembly Localization | Documents Scope 3 emissions to avoid carbon border tariff penalties on cross-Atlantic rig sales. |
| Autonomous Rod Handling Development | Addresses Chilean and Australian mining safety mandates for depths exceeding 1,500 meters. |
| Component-Level Service Unbundling | Captures aftermarket margin as Western Australian mining houses abandon OEM maintenance agreements. |
| Battery-Hybrid Retrofit Architecture | Accommodates future electrification without structural modification as auxiliary power systems decarbonize. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining interviews with rig fleet managers at Permian Basin contractors, procurement leads at Australian iron ore operators, hydraulic system engineers at German mining equipment fabricators, and aftermarket service heads at Chilean copper concentrators. Secondary validation draws from EPA enforcement databases, EU F-Gas Regulation implementation notices, ISO 18758 certification registries, and customs trade data on chromium-molybdenum alloy shipments. Bottom-up rig deployment counts triangulate against top-down exploration capital expenditure disclosures.
Granularity-level framing models product type at the crawler-truck-skid-pod level, technology at the automation-remote-monitoring tier, and application at the mining-geotechnical-geothermal split across the projection horizon. CAGRs derive from equipment replacement cycle analysis tied to regulatory compliance deadlines and pad drilling density expansion in Texas shale plays. Forecast inputs incorporate methane intensity benchmark trajectories and carbon border adjustment implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden Chinese alloy export restrictions or accelerated EPA methane rule phase-ins. Forecasts reflect documented assumptions on regulatory enforcement timelines and mining capital commitment patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Automation in Mining Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Auger Drilling Machine Market
Mining Equipment
Surface Mining Market