
 Auger Drilling Machine Market | 2026-2036
Auger Drilling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Auger Drilling Machine Market Analytics
Modular attachment systems for truck-mounted platforms is consolidating buyer preference across mid-cap fleet operators. Liebherr-International AG leverages its crane-to-driller integration architecture to anchor European infrastructure contracts. Caterpillar Inc. competes through dealer density and aftermarket parts availability across North American job sites. BAUER Maschinen GmbH specializes in high-torque rotary heads for diaphragm wall and bored-pile applications where specification tolerance is narrow.
An auger drilling machine employs a helical screw blade to extract soil or rock while advancing a borehole, with torque ratings spanning from five hundred to over five hundred thousand newton-meters depending on foundation depth and substrate density. The equipment serves geotechnical investigation, structural pile installation, and environmental sampling where precise hole geometry prevents sidewall collapse or groundwater infiltration. Truck-mounted augers dominate commercial foundation work where mobilization speed and reach depth justify capital outlay, while handheld and mini variants address confined-space utility installation and agricultural post-setting where maneuverability outweighs production volume. Hydraulic technology leads in heavy-duty segments for its power-to-weight ratio and variable speed control, though electric augers gain specification in noise-restricted urban corridors and emissions-regulated zones.
The EPA enforces diesel exhaust standards that push fleet operators toward Tier 4 Final or electric powertrains in US construction zones, while REACH and CE marking frameworks in Europe restrict hydraulic fluid formulations and mandate operator guarding systems that alter machine design priorities. OSHA excavation safety protocols and ISO 18758 drilling equipment standards further shape procurement checklists for foundation contractors. Stakeholders must track how emerging battery-electric torque delivery systems perform against hydraulic benchmarks in continuous-duty pile applications before committing to platform transitions.
Market Dynamics
Hydraulic-electric hybrid torque delivery systems are compressing the capital-lifecycle tradeoff that has governed foundation contractor procurement for decades. Tier 4 Final compliance deadlines and urban noise ordinances now force simultaneous powertrain and acoustic redesign, altering equipment specification priorities across municipal and private infrastructure bids.
Growth Catalysts
- US EPA Tier 4 Final mandates:Diesel exhaust standards accelerate fleet turnover toward electrified or hybrid auger platforms, expanding addressable equipment demand.
- Diaphragm wall specifications:High-torque rotary head requirements for deep-foundation projects in Germany and China pull specialized hydraulic system procurement.
- Urban corridor density:Geotechnical complexity in metropolitan expansion zones necessitates purpose-built drilling configurations with variable speed control.
Market Restraints
- Steel and hydraulic component volatility:Input cost swings for high-grade alloys and precision-machined rotary heads compress margin predictability for OEMs.
- Specialized technician scarcity:Deep-foundation equipment maintenance requires hydraulic-electric cross-training that vocational pipelines have not scaled to match.
- REACH formulation compliance:European hydraulic fluid restrictions impose reformulation costs and supply qualification timelines that extend procurement cycles.
Strategic Opportunities
- India infrastructure acceleration:National highway and metro expansion programs create first-mover positioning for modular truck-mounted auger configurations.
- Battery-electric torque benchmarking:Performance validation against hydraulic baselines in continuous-duty pile applications opens specification pathways for emission-restricted zones.
- Telematics-integrated service contracts:Real-time wear monitoring and predictive maintenance bundling reshape aftermarket revenue models for fleet operators.
Industry Challenges
- ISO 18758 certification timelines:Testing and documentation requirements for drilling equipment safety standards extend product launch windows.
- Legacy hydraulic fleet interoperability:Mixed-platform job sites complicate maintenance training and spare parts inventory management for contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auger Drilling Machine Market |
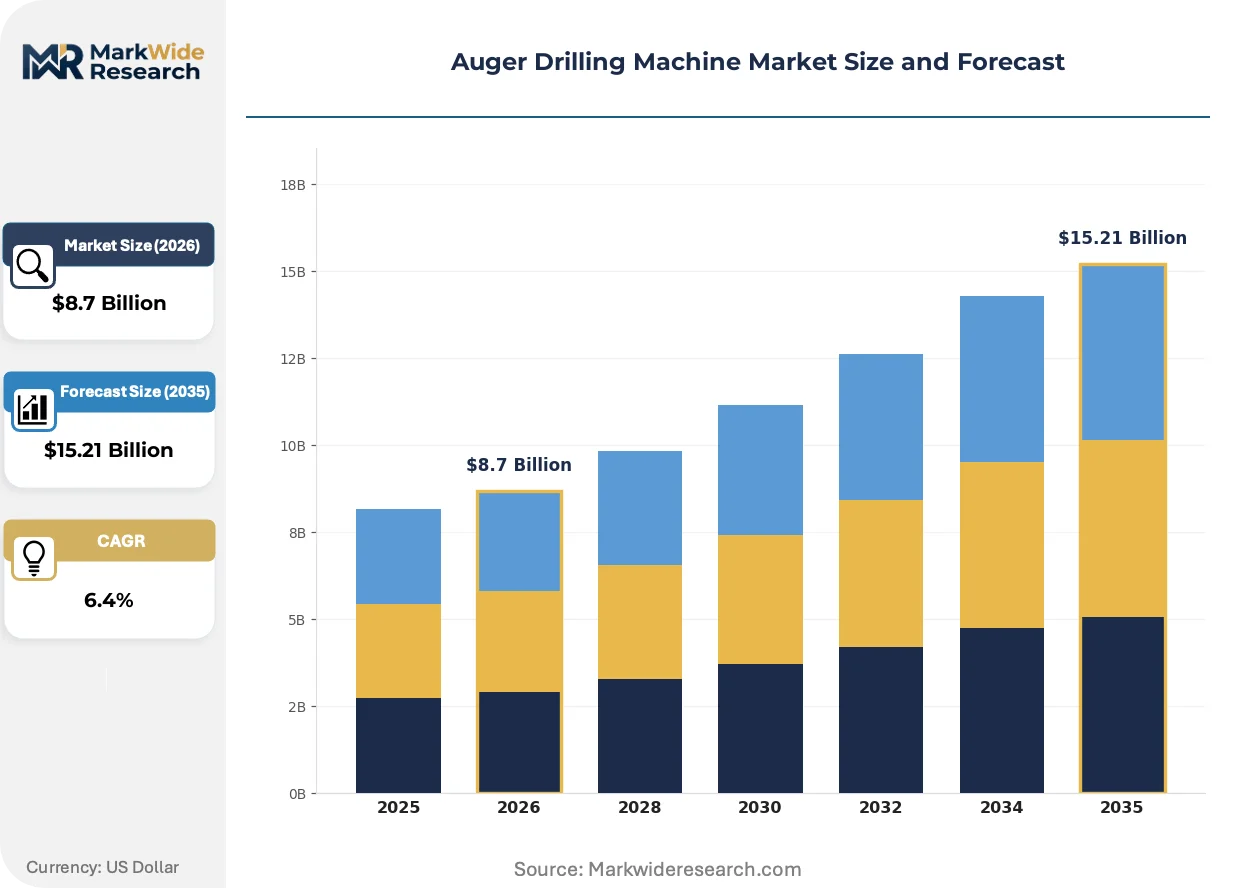
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Augers, Ride-On Augers, Truck-Mounted Augers, Mini Augers Application: Foundation Drilling, Soil Sampling, Environmental Studies, Utility Installation End User: Construction Companies, Environmental Agencies, Agriculture Sector, Mining Companies Technology: Hydraulic Augers, Electric Augers, Pneumatic Augers, Mechanical Augers |
| Companies Covered | Liebherr-International AG, Terex Corporation, Soilmec S.p.A., BAUER Maschinen GmbH, Herrenknecht AG, Caterpillar Inc., Little Beaver Inc., Agromaster Agricultural Machinery, Marl Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auger Drilling Machine Market Evolving Landscape
Equipment intelligence and powertrain diversification are compressing the traditional specification boundaries between heavy-duty foundation rigs and agile urban deployment platforms. These shifts alter how torque delivery, operator interface, and service architecture are bundled and priced.
Electrified hydraulic powerpacks are unifying the torque density of diesel systems with the variable-load efficiency of battery-electric architectures. Foundation contractors in noise-restricted German and Dutch urban cores specify these hybrids to meet municipal acoustic ordinances without sacrificing bore penetration rates. The technology is unifying previously separate equipment categories—truck-mounted production rigs and compact crawler units—into modular platform families with swappable power modules.
REACH and EU Green Deal frameworks restrict hydraulic fluid biodegradability thresholds and mandate extended producer responsibility for equipment end-of-life. OEMs reformulate seal materials and fluid pathways to accommodate bio-based alternatives with equivalent viscosity stability. European foundation specialists now prioritize CE-marked machines with closed-loop fluid systems that satisfy both operational duty cycles and environmental compliance documentation.
Rental and managed-service models displace outright purchase for mid-cap fleet operators facing capital allocation uncertainty. Equipment providers unbundle maintenance, telematics, and operator training into subscription tiers that align costs with project cash flows. This restructuring concentrates in North American municipal infrastructure contractors where bond-financed work programs create irregular equipment utilization patterns.
Auger Drilling Machine Market Segmentation
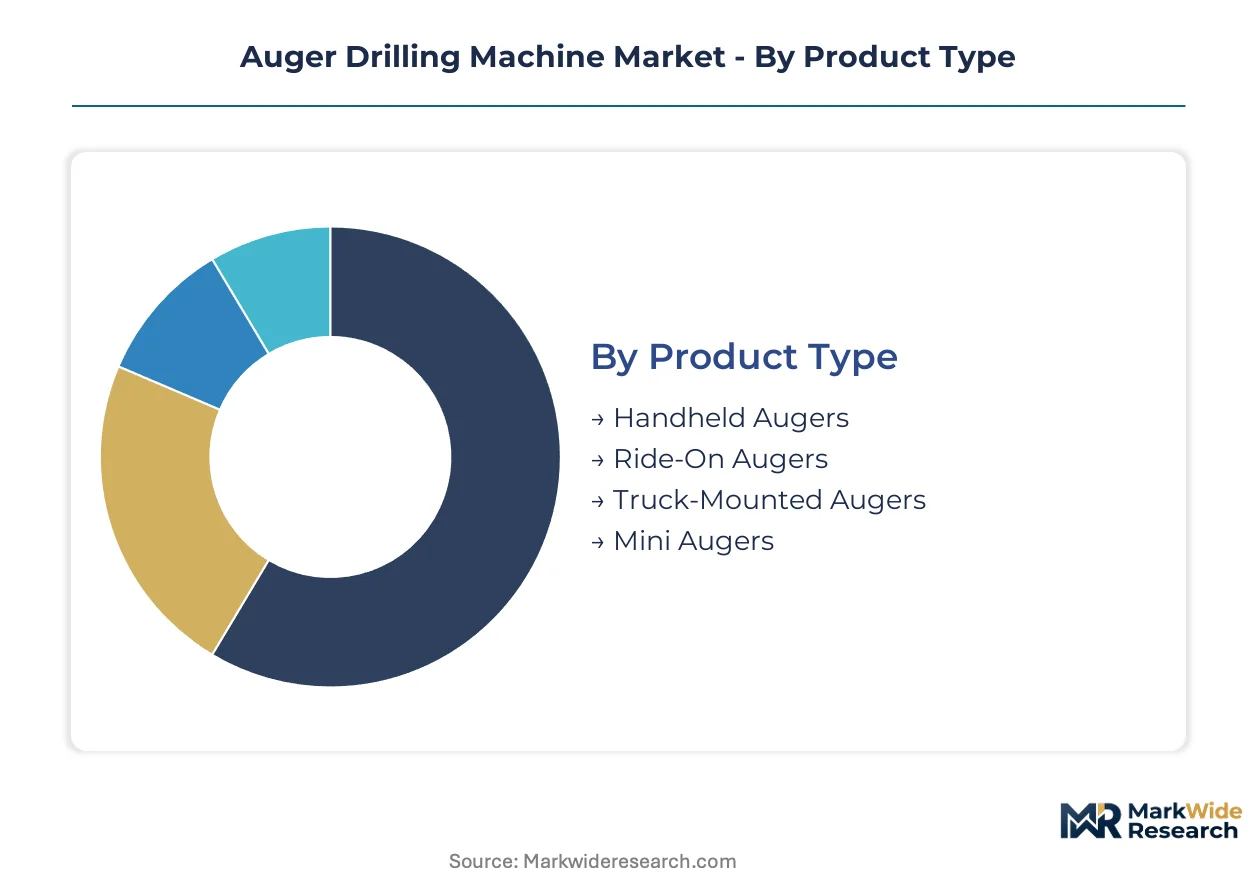
Auger drilling equipment segments diverge sharply on torque density, mobilization footprint, and regulatory compliance burden. Specification patterns track foundation depth requirements, substrate density, and municipal noise ordinances that reshape procurement priorities across contractor tiers.
Product Type:
CE marking and EPA Tier 4 Final certification burdens concentrate disproportionately on ride-on and truck-mounted platforms, while handheld and mini variants face lighter conformity costs but tighter operator guarding standards.
- Handheld Augers:Compact helical units weighing under 15 kilograms for post-setting, soil sampling, and confined-space utility work. Demand clusters with agricultural cooperatives in the Midwest and vineyard operators in California where maneuverability trumps production volume. OSHA excavation safety protocols and state-level operator certification requirements shape rental fleet specifications.
- Ride-On Augers:Self-propelled platforms with torque ratings from 2,000 to 50,000 newton-meters for mid-depth foundation and geotechnical investigation. Municipal infrastructure contractors in Texas and Florida specify these for sidewalk-to-curbline utility corridors where truck access is restricted. Tier 4 Final compliance deadlines accelerate diesel-to-electric conversions in urban procurement zones.
- Truck-Mounted Augers:High-mobility production rigs with telescopic booms and hydraulic rotary heads exceeding 100,000 newton-meters. Deep-foundation specialists in Germany and China deploy these for diaphragm wall and bored-pile applications where specification tolerance is narrow.
- Mini Augers:Crawler-based compact units for basement underpinning and interior renovation sites. Japanese and South Korean contractors favor these for seismic retrofit work in dense urban cores.
Leading the category by volume: Truck-Mounted Augers. Expanding most quickly: Ride-On Augers.
Application:
Cost tier stratification separates capital-intensive foundation drilling from lower-margin environmental and utility segments, with soil sampling occupying a mid-tier position on equipment utilization rates.
- Foundation Drilling:Structural pile installation for high-rise, bridge, and industrial substructures requiring precise hole geometry and sidewall stability. German and Chinese contractors drive specification for high-torque rotary heads in diaphragm wall applications. Geotechnical complexity in urban corridor expansions necessitates purpose-built configurations with variable speed control.
- Soil Sampling:Geotechnical investigation and site characterization for engineering feasibility studies. Environmental consulting firms in the Northeast and Pacific Northwest standardize on hollow-stem auger systems for groundwater monitoring well installation.
- Environmental Studies:Contaminated site assessment and remediation boring where fluid containment and decontamination protocols add operational overhead. EPA enforcement of diesel exhaust standards pushes fleet operators toward electric powertrains in sensitive ecological zones.
- Utility Installation:Power, telecommunications, and water infrastructure in municipal rights-of-way. Mid-cap contractors in the Sun Belt favor rental and managed-service models to align costs with irregular bond-financed work programs.
Dominating by revenue: Foundation Drilling. Climbing the fastest: Utility Installation.
End User:
Customer type determines procurement modality—outright purchase versus rental subscription—based on capital allocation discipline and fleet utilization predictability.
- Construction Companies:Foundation and general contractors with project-based equipment needs. Tier 1 firms in Germany and the United States consolidate preference for modular attachment systems with swappable power modules.
- Environmental Agencies:Federal, state, and municipal regulators conducting site assessment and monitoring. Procurement prioritizes hollow-stem and continuous-flight auger systems with closed-loop fluid containment for contamination-sensitive operations.
- Agriculture Sector:Vineyards, orchards, and fencing contractors requiring seasonal, low-duty-cycle equipment. Handheld and mini auger demand concentrates in California's Central Valley and Pacific Northwest berry operations.
- Mining Companies:Exploration and blast-hole drilling operations in hard-rock substrates. Exploration divisions in Nevada and Western Australia specify high-torque hydraulic platforms for reverse-circulation sampling.
Largest procurement volume: Construction Companies. Steepest expansion trajectory: Environmental Agencies.
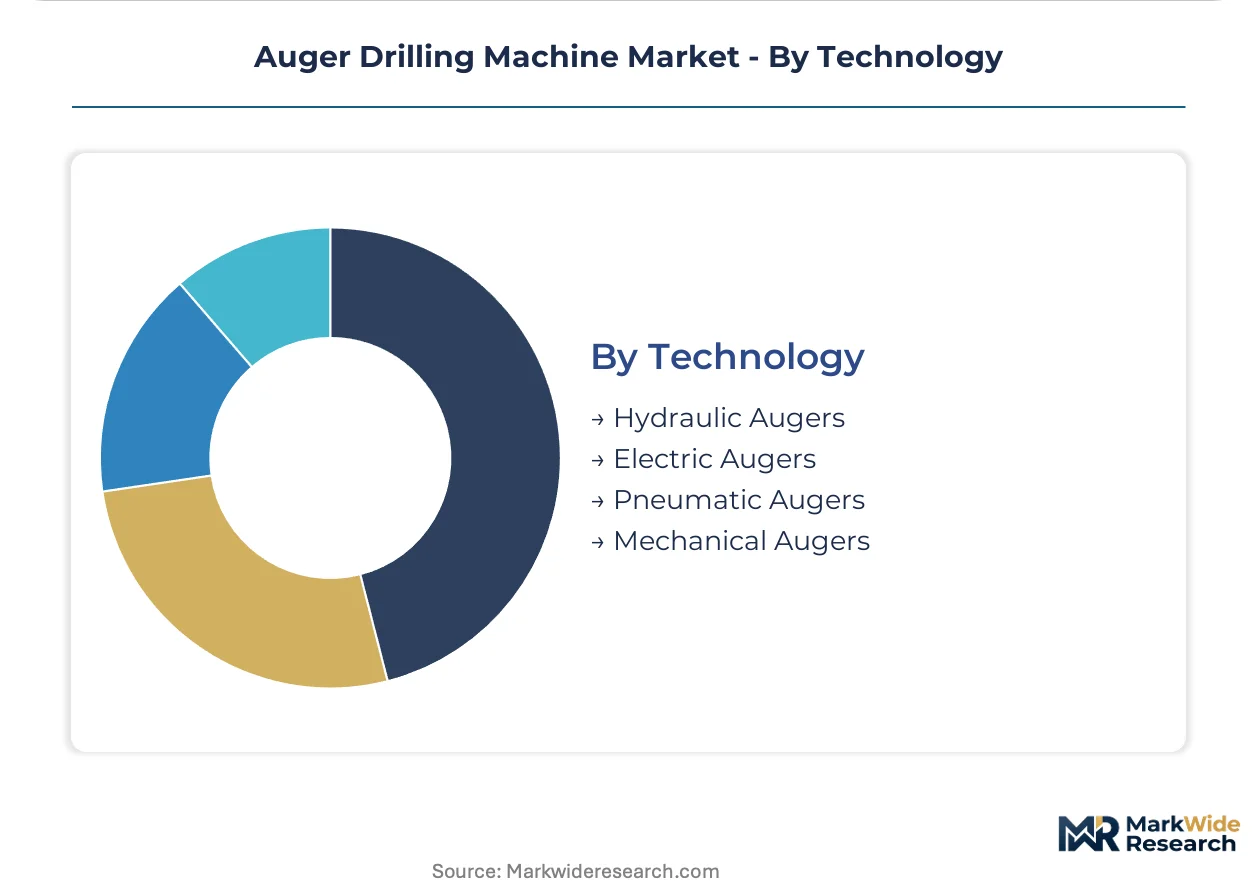
Technology:
Maturity curves separate established hydraulic dominance from emerging electric architectures, with pneumatic and mechanical systems occupying legacy niches.
- Hydraulic Augers:Power-dense torque delivery through variable-displacement pumps and high-pressure fluid circuits. Foundation contractors in Germany, China, and the United States specify these for continuous-duty pile applications where penetration rate consistency is critical. REACH and EU Green Deal frameworks restrict hydraulic fluid biodegradability thresholds, forcing OEM reformulation of seal materials and fluid pathways.
- Electric Augers:Battery-electric and tethered systems for noise-restricted urban corridors and emissions-regulated zones. Dutch and German municipal contractors specify electrified hydraulic powerpacks to meet acoustic ordinances without sacrificing bore penetration rates.
- Pneumatic Augers:Compressed-air drive systems for explosive atmospheres and underground mining where spark suppression is mandatory. Limited specification outside coal and hard-rock mining jurisdictions.
- Mechanical Augers:Direct mechanical power take-off from tractor or carrier powertrains. Agricultural and small-scale utility applications in cost-sensitive markets.
Highest installed base: Hydraulic Augers. Gaining share fastest: Electric Augers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures the most sophisticated hydraulic auger systems, yet the United States and China consume the highest equipment volumes for foundation drilling. Production concentrates where precision engineering clusters intersect with deep-foundation expertise. Demand patterns diverge between mature replacement markets and infrastructure acceleration zones.
United States
Foundation contractors in Texas and Florida drive truck-mounted auger procurement for municipal utility corridors. EPA Tier 4 Final mandates accelerate diesel-to-electric conversions in urban procurement zones. The Sun Belt's bond-financed infrastructure programs create irregular utilization patterns that favor rental and managed-service models.
Germany
Diaphragm wall specifications pull high-torque rotary head demand from specialized foundation contractors. REACH and EU Green Deal frameworks restrict hydraulic fluid biodegradability thresholds, forcing OEM reformulation of seal materials. Bavarian engineering clusters anchor precision manufacturing of closed-loop fluid systems for CE-marked export machines.
China
Metro expansion and high-rise construction in Shanghai and Shenzhen absorb truck-mounted production rigs with torque ratings exceeding 100,000 newton-meters. National infrastructure targets concentrate procurement through state-linked contractors. Yangtze River Delta fabrication centers supply modular platform families with swappable power modules.
India
National highway and metro expansion programs create first-mover positioning for modular truck-mounted auger configurations. Central public works departments specify equipment through tender processes that prioritize capital efficiency over lifecycle cost. Maharashtra and Gujarat infrastructure corridors concentrate deployment of mid-torque ride-on platforms.
Japan
Seismic retrofit work in Tokyo and Osaka drives demand for crawler-based mini augers in dense urban cores. METI efficiency standards shape equipment specification for basement underpinning and interior renovation sites. Kanto region contractors favor compact units with acoustic suppression for noise-restricted residential zones.
Auger Drilling Machine Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive distribution networks. Equipment procurement decisions flow through dealer density, aftermarket parts availability, and telematics-integrated service bundling. Three archetypes dominate: crane-to-driller integrators, high-torque rotary specialists, and full-line construction equipment manufacturers. Geographic expansion and strategic partnerships constitute the primary competitive vectors as OEMs seek positioning in India's infrastructure acceleration and China's metro buildout.
Among German-based precision engineering groups, Liebherr-International AG and BAUER Maschinen GmbH exemplify divergent specialization strategies—one anchored in crane-to-driller integration architecture, the other in high-torque rotary heads for specification-critical diaphragm wall applications. Caterpillar Inc. represents the full-line construction equipment archetype, competing through dealer density and aftermarket parts availability across North American job sites. These three occupy positions that reflect the market's segmentation between integrated platform families, specialized deep-foundation tools, and broad distribution coverage.
| Leading Market Players |
|---|
| Liebherr-International AG |
| Terex Corporation |
| Soilmec S.p.A. |
| BAUER Maschinen GmbH |
| Herrenknecht AG |
| Caterpillar Inc. |
| Little Beaver Inc. |
| Agromaster Agricultural Machinery |
| Marl Technologies Inc. |
| Others |
Value Network & Pricing Analysis
Specialized hydraulic-electric cross-trained technicians in Bavaria and Baden-Württemberg command wage premiums that widen the spread between premium CE-marked rigs and standard-tier equipment, compressing mid-market positioning as OEMs absorb labor-cost differentials into tiered pricing architectures.
Pricing Analysis
Cost-down pressure on ride-on platforms accelerates as EPA Tier 4 Final compliance deadlines force simultaneous powertrain and acoustic redesign. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales service bundling, with foundation contractors in Texas and Florida exhibiting highest price sensitivity due to irregular bond-financed utilization patterns. Premium truck-mounted configurations in Germany and China retain pricing power through narrow specification tolerance for diaphragm wall applications.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Peoria anchor hub-and-spoke patterns that position finished machines within 48-hour mobilization reach of foundation corridors. Manufacturing draws from high-grade alloy foundries in Germany, precision-machined rotary head suppliers in Japan, and hydraulic component clusters in the United States. Single-source vulnerability concentrates in specialized torque motor production, with distribution running through OEM-captive dealer networks that bundle aftermarket parts availability into procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as control over precision-machined rotary head production determines margin capture in high-torque segments.
For Market Incumbents: Cement dealer density advantages in North American municipal corridors through telematics-integrated service contracts that lock out rental-platform competitors. Extend backward integration into hydraulic-electric powerpack assembly to capture hybrid technology premiums before battery-electric torque validation matures. For New Entrants and Emerging Players: Direct equipment-as-a-service platforms offer the lowest customer-acquisition cost route into mid-cap fleet operators facing capital allocation uncertainty. Target India's national highway expansion programs with modular truck-mounted configurations that prioritize capital efficiency over lifecycle cost in tender-driven procurement environments. For Investors and Strategic Acquirers: The window for entry favors precision-engineering specialists with captive rotary head production and CE marking infrastructure already in place. Watch battery-electric torque benchmarking results in continuous-duty pile applications as the inflection signal for platform transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Hydraulic Powerpack Development | Unifies diesel torque density with battery-electric efficiency for German and Dutch urban acoustic compliance. |
| Telematics-Integrated Service Contracts | Reshapes aftermarket revenue models for North American municipal infrastructure contractors facing irregular utilization. |
| Modular Platform Family Expansion | Enables swappable power modules that compress specification boundaries between truck-mounted rigs and crawler units. |
| Backward Integration into Rotary Head Manufacturing | Captures margin in high-torque diaphragm wall applications where specification tolerance is narrowest. |
| India Infrastructure Market Entry | Positions first-mover advantage in national highway and metro expansion programs through tender-optimized configurations. |
Research Methodology
Independent corroboration across foundation contractor procurement directors, OEM product strategy leads, and aftermarket service heads underwrites the qualitative findings in this study. Secondary validation draws from equipment registration databases, customs trade records for high-grade alloy imports, and SEC filings from listed construction equipment manufacturers. Bottom-up demand modeling across torque rating tiers and top-down macroeconomic triangulation anchored the market sizing framework.
Rate-of-change decomposition across the projection horizon separates replacement-cycle dynamics from infrastructure-driven expansion demand. Segmentation dimensions modeled include product type, application, end user, and technology architecture, with regional regulatory clusters treated as cross-cutting variables. CAGRs were derived from fitted growth curves against historical equipment shipment patterns, incorporating battery-electric penetration assumptions and REACH formulation compliance timelines as industry-specific inputs.
Inputs from foundation contractor interviews and OEM technical documentation were available through the study window; gaps in real-time fleet utilization telemetry introduce uncertainty bands around aftermarket service revenue projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Smart Mining Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
DTH Drill Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Horizontal Shaft Impact Crusher Market