
 Construction and Mining Equipment Spare Parts Market | 2026-2036
Construction and Mining Equipment Spare Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Construction and Mining Equipment Spare Parts Market Insights
Digital parts distribution networks are reshaping how construction and mining operators procure critical components, with platforms now linking remote job sites directly to manufacturer inventories. Caterpillar Inc. leverages its global dealer network to sustain aftermarket revenue streams across mature mining districts. Komatsu Ltd. anchors its competitive stance through telematics-integrated parts forecasting that reduces unplanned downtime for fleet operators. Hitachi Construction Machinery Co Ltd. differentiates by specializing in hydraulic systems for ultra-class excavators operating in high-abrasion environments.
Construction and Mining Equipment Spare Parts encompass replacement components engineered to OEM specifications for earthmoving, excavation, and mineral processing machinery, typically manufactured from alloyed steels, hardened rubbers, and engineered composites to withstand cyclic loading and abrasive wear. These parts restore original equipment performance, safety margins, and operational availability across heavy-duty industrial applications. Hydraulic parts command substantial margin pools due to precision machining requirements and frequent replacement intervals in high-pressure systems. Engine components face structural pressure from emissions compliance retrofit cycles, while undercarriage parts represent a mature segment with stable demand tied to tracked vehicle utilization rates. Electrical parts are gaining share as electrified and autonomous machine architectures proliferate across surface mining fleets.
EPA non-road diesel regulations in the United States, REACH substance restrictions in Europe, and China's GB standards for construction machinery emissions collectively elevate material traceability and remanufacturing requirements across the supply chain. These frameworks compel parts suppliers to certify chemical compositions and document end-of-life handling protocols to maintain market access. Stakeholders must monitor how carbon border adjustment mechanisms and circular economy mandates recalibrate sourcing economics for steel-intensive undercarriage and engine components.
Market Dynamics
Telematics-integrated predictive maintenance systems are compressing replacement cycles and reconfiguring inventory positioning across remote mining districts, forcing distributors to relocate parts stock closer to active extraction zones rather than traditional urban hubs.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Non-road diesel engine retrofit mandates in the United States are accelerating fleet overhaul programs and expanding the addressable market for emissions-compliant turbochargers, aftertreatment systems, and electronic control modules.
- Iron ore production intensity:Western Australia's Pilbara region sustains elevated demand for undercarriage components as producers maximize utilization rates on ultra-class haul trucks operating in high-abrasion conditions.
- Alloyed steel forging advances:Precision casting techniques for hydraulic cylinder barrels are extending service intervals in high-pressure excavation systems, reducing total cost of ownership for fleet operators.
Market Restraints
- Scrap steel price volatility:Input cost fluctuations for alloyed steels used in track shoes and ground-engaging tools compress margin predictability for forged component suppliers.
- Regional supplier concentration:Specialized foundry capacity for heat-treated undercarriage parts clusters in select industrial corridors, creating geographic vulnerability to logistics disruptions.
- REACH substance documentation:European chemical traceability requirements impose compliance overhead on rubber compound formulations for seals and gaskets, lengthening supplier qualification timelines.
Strategic Opportunities
- Autonomous fleet electrification:Battery-electric and trolley-assist haulage systems in Canadian oil sands operations are opening demand for high-voltage electrical distribution components and thermal management parts.
- Remanufacturing incentives:China's circular economy promotion policies and extended producer responsibility frameworks are elevating certified remanufactured hydraulic pumps as cost-competitive alternatives to new OEM units.
- Direct-to-site distribution platforms:Digital procurement networks connecting remote Indonesian nickel mining concessions to manufacturer inventories are disintermediating traditional dealer stocking models.
Industry Challenges
- Precision machining workforce scarcity:Shortages of CNC operators capable of tolerances required for hydraulic valve bodies constrain production scaling for high-pressure component suppliers.
- Legacy equipment interoperability:Retrofitting telematics sensors onto 1990s-era excavator architectures requires custom harness fabrication and protocol translation, complicating fleet standardization efforts.
- Multi-jurisdiction certification overlap:Simultaneous compliance with EPA emissions, ISO quality management, and site-specific mine safety standards extends product launch timelines for engine component manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction and Mining Equipment Spare Parts Market |
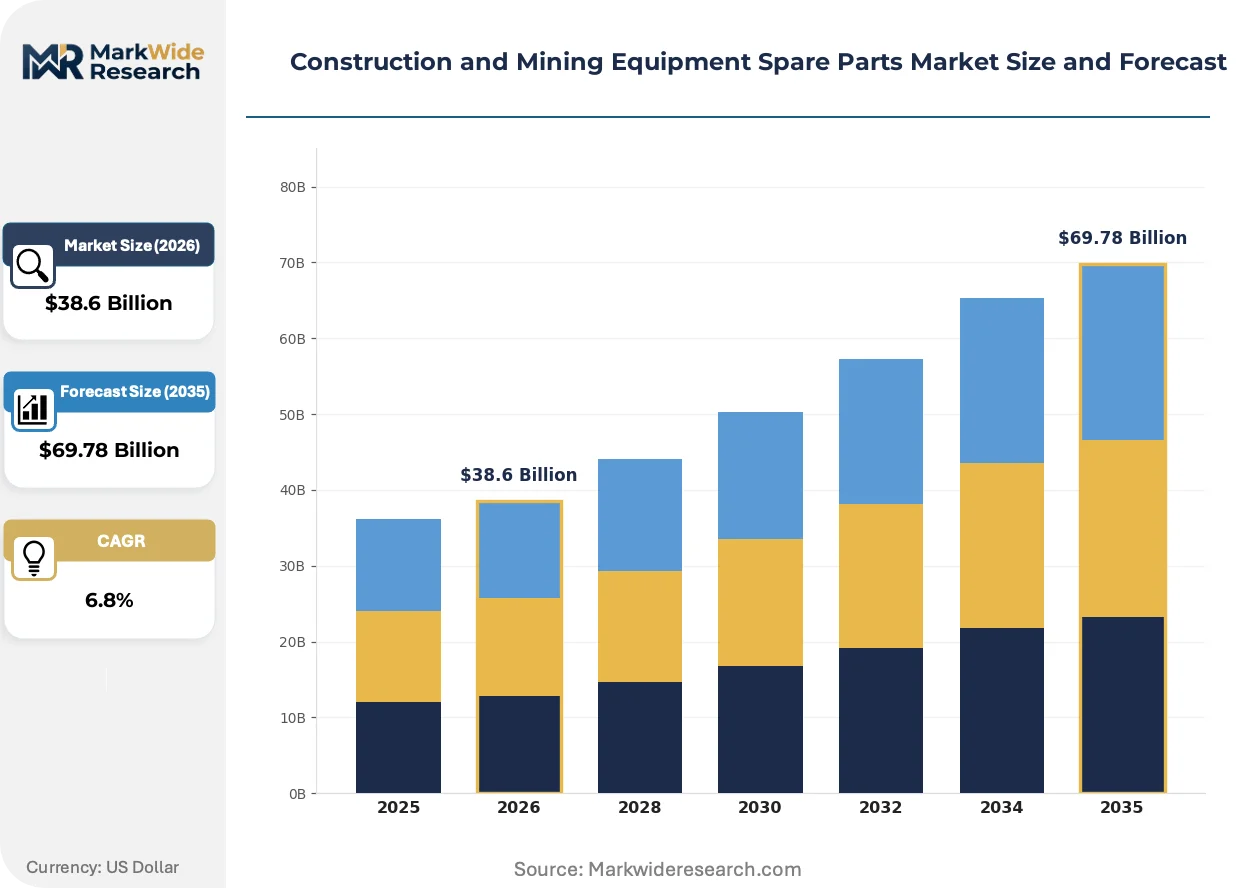
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Parts, Engine Components, Undercarriage Parts, Electrical Parts End User: Construction Companies, Mining Corporations, Equipment Distributors, Maintenance Service Providers Material: Steel, Rubber, Plastic, Composite Distribution Channel: Online Retailers, Direct Sales, Wholesale Distributors, Service Centers |
| Companies Covered | Caterpillar Inc., Komatsu Ltd, Hitachi Construction Machinery Co Ltd, Volvo Construction Equipment, Metso Corporation, John Deere, Doosan Infracore, CNH Industrial, Sany Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction and Mining Equipment Spare Parts Market Trends and Innovations
Additive manufacturing for complex hydraulic manifolds and wear-resistant ground-engaging tools is transitioning from prototyping to production-scale deployment, altering sourcing economics for low-volume, high-complexity replacement parts.
Directed energy deposition for nickel-alloy hydraulic valve bodies is collapsing lead times for obsolete component reproduction from 16 weeks to under 72 hours. Mining contractors in Chile's copper belt are adopting printed spare inventories for critical path equipment. This capability is collapsing the economic rationale for mass warehousing of slow-moving SKUs in regional distribution centers.
REACH substance restriction expansions by ECHA are compelling reformulation of high-performance hydraulic fluids and seal elastomers used in European construction equipment. Suppliers must recertify chemical composition documentation across entire product lines. The hydraulic systems segment faces the steepest compliance burden as biodegradable fluid alternatives require redesigned seal compatibility profiles.
Fleet operators in Australia's Bowen Basin are consolidating procurement through integrated maintenance contracts that bundle parts supply with labor and equipment availability guarantees. Traditional parts-only distributors are losing share to outcome-based service providers. This consolidation is most pronounced in surface coal operations where unplanned downtime costs exceed $15,000 per hour on electric rope shovels.
Construction and Mining Equipment Spare Parts Market Segmentation
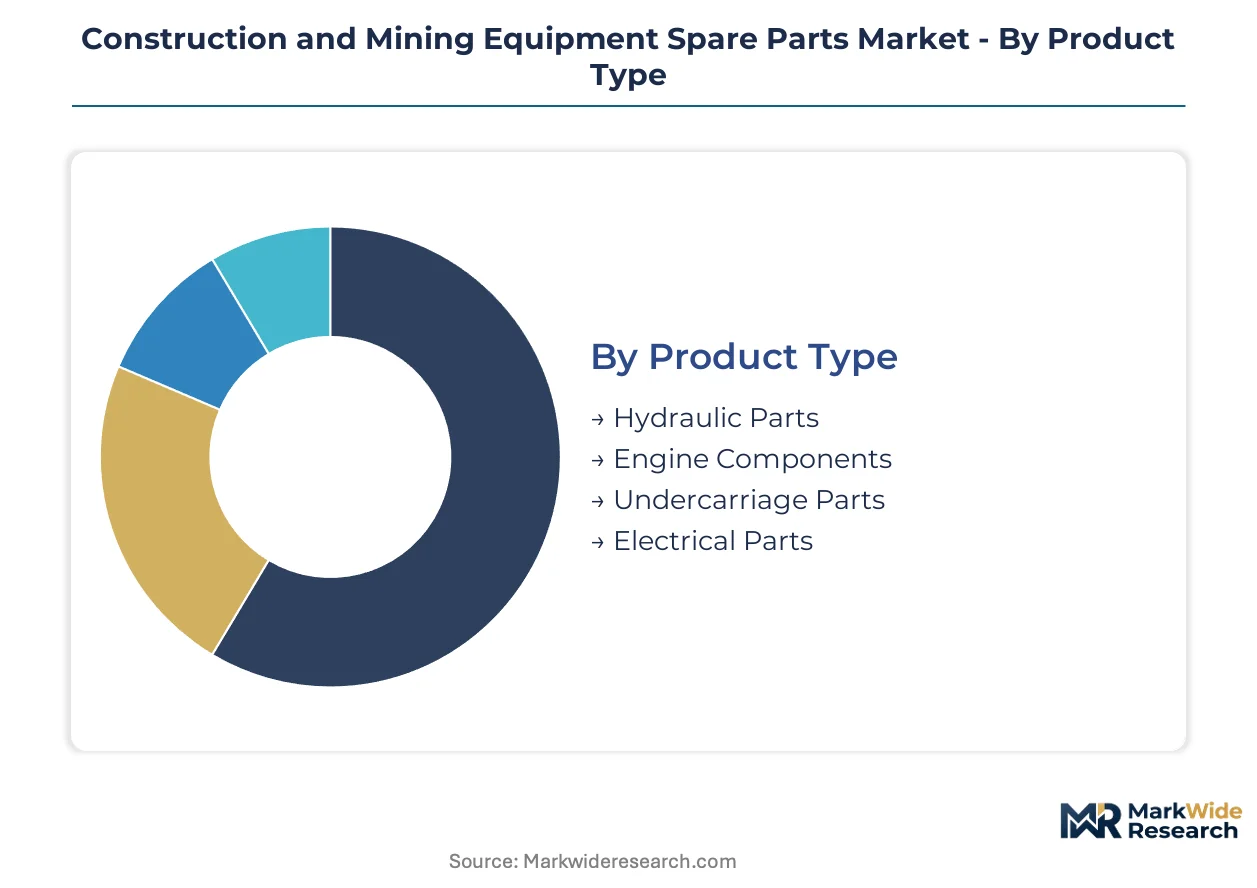
Segmentation in construction and mining equipment spare parts reveals how procurement priorities diverge across operational contexts. Fleet operators select components based on abrasion exposure, pressure cycling demands, and regulatory compliance requirements rather than uniform specifications.
Product Type:
Equipment architecture dictates replacement intensity across hydraulic, engine, undercarriage, and electrical systems.
- Hydraulic Parts:Precision-machined cylinders, valves, and manifolds manufactured from alloyed steels and hardened seals withstand cyclic pressures exceeding 350 bar in excavation systems. Western Australia's Pilbara iron ore operations consume premium hydraulic barrels as ultra-class excavators maximize bucket fill rates in high-abrasion conditions. Established volume favors undercarriage parts; emerging adoption favors electrical parts.
- Engine Components:Turbochargers, fuel injection systems, and aftertreatment modules engineered to EPA Tier 4 Final specifications reduce nitrogen oxide emissions in non-road diesel applications. United States fleet operators facing compliance deadlines are accelerating retrofit programs across aging haul truck populations.
- Undercarriage Parts:Track shoes, rollers, and idlers forged from boron-alloyed steels absorb ground impact in tracked excavators and dozers. Indonesian nickel mining concessions sustain replacement demand as laterite extraction expands fleet utilization rates.
- Electrical Parts:High-voltage distribution components and battery thermal management systems support electrified haulage architectures. Canadian oil sands operations are trialing trolley-assist systems that elevate demand for power electronics and motor controllers.
Margin concentration tracks machining complexity rather than unit volume alone.
End User:
Procurement authority sits differently with asset owners than with contracted service providers.
- Construction Companies:Project-based operators maintain lean spare inventories and rely on rapid fulfillment for critical path equipment. Urban infrastructure contractors in Germany prioritize REACH-compliant seal formulations to avoid worksite chemical restrictions.
- Mining Corporations:Captive maintenance divisions in Western Australia and Chile stockpile high-wear components to guarantee availability guarantees exceeding 95 percent on electric rope shovels. Volume concentration favors mining corporations; margin expansion favors maintenance service providers.
- Equipment Distributors:Authorized dealer networks balance manufacturer inventory commitments against regional demand patterns. Komatsu's global dealer infrastructure exemplifies captive aftermarket channel control.
- Maintenance Service Providers:Outcome-based contractors bundle parts supply with labor and uptime guarantees, displacing traditional parts-only transactions. Australia's Bowen Basin coal operators now procure integrated maintenance contracts rather than discrete component orders.
Channel power is shifting from distributors to availability-guarantee specialists.
Material:
Substrate selection balances wear resistance against regulatory traceability requirements.
- Steel:Heat-treated alloy grades dominate ground-engaging tools and undercarriage components subjected to impact loading. Scrap price volatility compresses margin predictability for forged track shoe suppliers concentrated in select industrial corridors.
- Rubber:Nitrile and fluorocarbon elastomers seal high-pressure hydraulic circuits against fluid ingress. ECHA reformulation mandates are extending supplier qualification timelines for European construction equipment applications.
- Plastic:Engineering polymers reduce weight in non-structural housings and electrical insulation. Electrical parts are gaining polymer content as machine architectures electrify.
- Composite:Carbon fiber-reinforced panels protect hydraulic reservoirs and electronic enclosures from impact damage. Additive manufacturing is expanding composite applications in complex manifold geometries.
Steel retains volume dominance; composites claim the steepest expansion trajectory.
Distribution Channel:
Physical proximity to extraction zones is displacing traditional urban warehousing.
- Online Retailers:Digital platforms connecting remote job sites to manufacturer inventories collapse procurement lead times. Indonesian nickel concessions now bypass dealer networks for critical hydraulic components.
- Direct Sales:OEM-controlled channels preserve margin capture and technical support integration. Caterpillar's dealer network sustains aftermarket revenue through captive parts distribution.
- Wholesale Distributors:Regional stockists aggregate demand across fragmented contractor bases. Pilbara iron ore producers maintain large captive inventories that reduce distributor relevance.
- Service Centers:Integrated facilities combine component supply with installation and warranty administration. Telematics-integrated predictive maintenance is compressing replacement cycles and forcing stock relocation closer to active extraction zones.
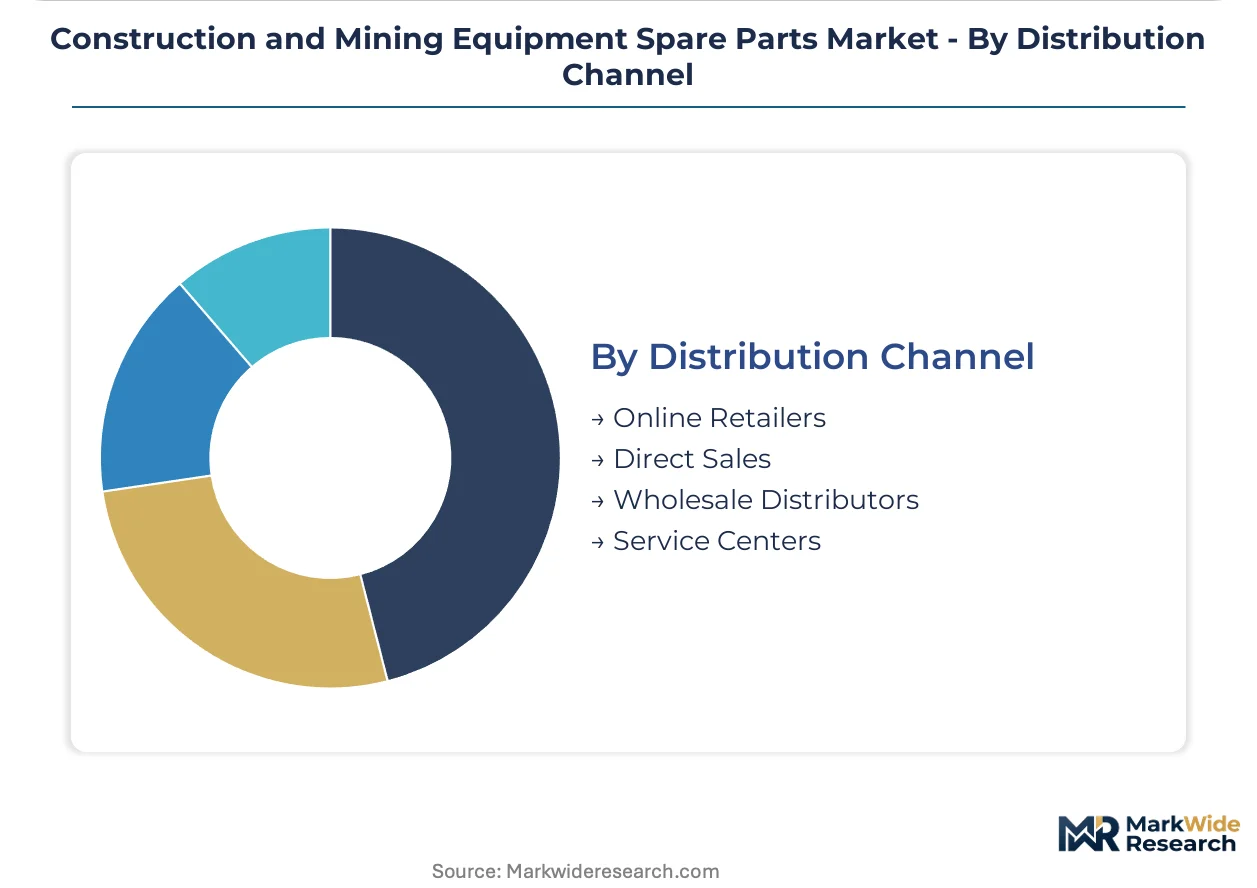
Direct sales anchor revenue stability; online platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Western Australia's Pilbara iron ore belt, where captive inventory strategies compress distributor margins, while Indonesian nickel concessions leverage digital procurement platforms to bypass traditional dealer networks entirely.
United States
EPA Tier 4 Final compliance deadlines are accelerating fleet overhaul programs across aging haul truck populations in Arizona's copper belt and Wyoming's Powder River Basin coal fields. The EPA's non-road diesel emissions standards mandate turbocharger and aftertreatment retrofits that expand the addressable market for compliant engine components. Pittsburgh-based foundry clusters supply heat-treated undercarriage forgings to Appalachian surface mining operations facing compressed replacement cycles.
Australia
Western Australia's Pilbara iron ore producers maintain large captive spare parts inventories to guarantee equipment availability exceeding 95 percent on electric rope shovels. The country's national mining safety regulator enforces strict maintenance documentation protocols that elevate demand for certified remanufactured hydraulic components. Queensland's Bowen Basin coal operators are consolidating procurement through integrated maintenance contracts that bundle parts supply with labor and uptime guarantees.
China
GB standards for construction machinery emissions and circular economy promotion policies are elevating certified remanufactured hydraulic pumps as cost-competitive alternatives to new OEM units. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate fleet electrification trials in Inner Mongolia's coal districts. Xuzhou's machinery manufacturing cluster anchors domestic supply chains for alloyed steel undercarriage components serving Mongolian copper-gold projects.
Chile
Copper mining contractors in the Atacama Desert are adopting additive-manufactured spare inventories for critical path equipment, collapsing lead times for obsolete hydraulic valve bodies from 16 weeks to under 72 hours. The national mining regulator's environmental compliance frameworks extend product launch timelines for engine component suppliers. Antofagasta's mining services corridor concentrates precision machining capacity for high-pressure hydraulic systems operating in high-altitude conditions.
Indonesia
Nickel mining concessions in Sulawesi and Halmahera are leveraging direct-to-site distribution platforms that disintermediate traditional dealer stocking models entirely. The country's mineral export ban policies are accelerating downstream processing investments that expand fleet utilization rates for laterite extraction equipment. Jakarta-based logistics hubs are relocating parts stock closer to active extraction zones rather than traditional urban warehousing centers.
Construction and Mining Equipment Spare Parts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in forging and precision machining. The vendor base organizes around three structural tiers: full-line OEMs with captive distribution networks, specialized hydraulic and undercarriage component manufacturers, and emerging digital procurement platforms. Consolidation pressure concentrates among mid-scale forging operations facing scrap steel price volatility. Dominant competitive moves include backward integration into alloyed steel supply chains and geographic expansion through regional service center networks.
Among Japanese-headquartered machinery manufacturers, Komatsu Ltd and Hitachi Construction Machinery Co Ltd exemplify contrasting strategic archetypes within the premium equipment tier. Komatsu Ltd occupies a position emphasizing telematics-integrated aftermarket services, while Hitachi Construction Machinery Co Ltd represents specialization in ultra-class excavation systems. Caterpillar Inc anchors the North American competitive structure through its extensive dealer network infrastructure. These three entities collectively illustrate how geographic origin and organizational scale map to distinct market positioning strategies across hydraulic, engine, and undercarriage component ecosystems.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd |
| Hitachi Construction Machinery Co Ltd |
| Volvo Construction Equipment |
| Metso Corporation |
| John Deere |
| Doosan Infracore |
| CNH Industrial |
| Sany Group |
| Others |
Pricing and Supply Chain Analysis
The Trans-Siberian rail corridor's freight rate volatility compresses margin buffers for European distributors sourcing heat-treated undercarriage forgings from Xuzhou, forcing three-tier pricing stratification that separates premium OEM-certified components from standard aftermarket alternatives and economy-grade remanufactured units.
Pricing Analysis
The customization-premium spread between configured-to-order hydraulic cylinders and standard catalog parts runs 40-60 percent, with contract-based long-term offtake agreements dominating mining corporation procurement. Price differentiation rests on REACH certification tier and geographic delivery cost to remote extraction zones. Cost compression in economy-grade track shoes intensifies as Indonesian nickel concessions bypass dealer markups through direct digital procurement. Maintenance service providers exhibit lowest price sensitivity due to bundled availability guarantees, while project-based construction contractors negotiate aggressively on standard SKUs.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese trading houses anchor working capital for Australian and Chilean mining contractors, enabling 90-day payment terms that mask underlying scrap steel price volatility. Geographic supply concentration centers on China's Jiangsu province for alloyed steel forgings, Germany's Ruhr Valley for precision-machined hydraulic valves, and India's Tamil Nadu for rubber compound seals. Raw material dependencies draw from Australian iron ore, Indonesian nickel laterite, and South African chromium. Single-source vulnerability in specialized foundry capacity for heat-treated undercarriage parts creates geographic exposure. Distribution runs through OEM-captive dealer networks, though direct-to-site digital platforms gain share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment electrification fragments procurement authority between traditional maintenance divisions and emerging energy infrastructure teams, creating niche opportunities for electrical system specialists unburdened by legacy hydraulic expertise.
For Market Incumbents: Insulate aftermarket revenue by backward integration into alloyed steel supply chains and captive certification of remanufactured hydraulic pumps under China's circular economy frameworks. The threat of additive manufacturing specialists collapsing lead times for obsolete components demands accelerated telematics integration to lock in predictive maintenance contracts. Channel control through regional service center networks remains the priority lever against digital platform disintermediation. For New Entrants and Emerging Players: Build out additive manufacturing capacity for nickel-alloy hydraulic valve bodies serving Chile's copper belt, where 72-hour production cycles create sustainable advantage against 16-week traditional lead times. The most penetrable white space sits in battery-electric haulage thermal management components for Canadian oil sands operations. A direct-to-site distribution partnership with Indonesian nickel concessions bypasses entrenched dealer relationships entirely. For Investors and Strategic Acquirers: Precision machining specialists with CNC tolerance capabilities for 350-bar hydraulic systems represent the most defensible acquisition archetype amid workforce scarcity. Long-term viability over the next decade hinges on electrification exposure and remanufacturing certification infrastructure. The signal to monitor is EPA Tier 5 pre-announcement timing, which would trigger fleet overhaul acceleration and expand compliant engine component addressable markets.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Integrated Predictive Maintenance | Compresses replacement cycles and locks in parts revenue through availability guarantees exceeding 95 percent on electric rope shovels. |
| Backward Integration into Alloyed Steel Supply | Insulates margin predictability against scrap price volatility concentrated in select industrial corridors. |
| Additive Manufacturing Scale-Up | Collapses lead times for obsolete hydraulic components from 16 weeks to under 72 hours in Chile's copper belt. |
| Remanufacturing Certification Investment | Positions certified hydraulic pumps as cost-competitive alternatives under China's circular economy promotion policies. |
| Direct-to-Site Digital Platform Launch | Disintermediates traditional dealer networks for Indonesian nickel concessions seeking rapid hydraulic component fulfillment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors at Pilbara iron ore operations, aftermarket service heads at OEM dealer networks, and procurement leads at Indonesian nickel concessions; and secondary validation against EPA emissions filings, Australian mining safety regulator maintenance documentation protocols, and customs records for alloyed steel undercarriage component trade flows. Bottom-up equipment fleet sizing triangulated against top-down market value estimates across the analysis window.
Forecast inputs considered equipment utilization rates in high-abrasion conditions, EPA compliance retrofit cycle timing, and electrification trial adoption curves across Canadian oil sands and Inner Mongolian coal districts. Segmentation dimensions modeled include product type, end user procurement authority, material substrate selection, and distribution channel evolution. CAGRs were derived from replacement intensity projections tied to telematics-integrated predictive maintenance penetration.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing specialists or battery-electric drivetrain suppliers would shift outcomes beyond modeled parameters. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Barite Crusher Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Smart Mining Market
Mining Equipment
Hydraulic Drilling Rig Market