
 Africa Mining Market | 2026-2036
Africa Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Mining Market Analysis
Software-defined mine planning and predictive maintenance subscriptions is restructuring how capital equipment vendors monetize relationships with African operators. Anglo American sustains integrated pit-to-port control across Southern African platinum and diamond assets. Glencore leverages its trading infrastructure to anchor offtake positions in DRC copper-cobalt corridors. BHP Group competes through automated haulage deployment at South African and Namibian sites.
Africa mining encompasses the systematic extraction of metallic and non-metallic mineral deposits from geological formations across the continent, employing open-pit, underground, and solution mining methods with ore grades typically ranging from 0.5% to 5% for base metals and 3-8 grams per tonne for gold deposits. The primary purpose is supplying raw material feedstock for global metal production, construction aggregate, and thermal or metallurgical coal for energy generation. Gold extraction retains mature margin pools in West African greenstone belts, while copper applications in electrification infrastructure represent the fastest-growing demand vector. Coal for regional energy generation faces structural decline as power utilities pivot toward renewable baseload, though metallurgical coal maintains construction-linked demand.
South Africa's Department of Mineral Resources and Energy, the DRC's mining code enforcement apparatus, and Zambia's tax royalty frameworks collectively shape licensing timelines, local content thresholds, and export duty structures across the continent. ISO 14001 environmental management standards and the Extractive Industries Transparency Initiative influence access to project finance from development institutions and commercial lenders. Stakeholders must monitor how battery metal offtake pre-commitments interact with evolving beneficiation mandates to determine capital allocation sequencing.
Market Dynamics
Battery-grade cobalt offtake pre-commitments from electric vehicle manufacturers are restructuring capital allocation timelines across the African copper belt, compressing project development cycles and intensifying competition for shovel-ready assets.
Growth Catalysts
- Beneficiation mandates:Zambia's escalating local content thresholds and export duty frameworks are compelling foreign operators to build downstream processing capacity, creating captive feedstock demand for regional smelters.
- Automated haulage systems:Deployment of autonomous truck fleets at Namibian and South African open-pit operations is reducing unit operating costs and extending mine life at marginal ore bodies.
- Copper-cobalt corridor concentration:The Democratic Republic of Congo's geological endowment in the Central African Copperbelt continues to attract development capital despite infrastructure deficits, anchored by tier-one deposit scale.
Market Restraints
- Energy cost volatility:Diesel and grid electricity price instability across Southern African power pools erodes margin predictability for deep underground platinum and gold operations.
- Artisanal supply concentration:Informal cobalt production from unlicensed sites in southeastern DRC introduces ESG liability and supply chain traceability complexity for battery metal offtakers.
- Grid infrastructure deficit:Transmission bottlenecks between mine sites and port corridors in Mozambique and Tanzania constrain export volume scalability for new greenfield projects.
Strategic Opportunities
- Green hydrogen integration:Namibia's renewable energy endowment positions the country for electrolyzer-powered mining equipment trials, potentially displacing diesel in heavy haulage.
- Platinum group metal recycling:South Africa's above-ground stockpiles of spent automotive catalysts represent underexploited secondary feedstock for palladium and rhodium recovery.
- Regional power pool arbitrage:Cross-border electricity trading frameworks under the Southern African Power Pool enable load-shifting strategies for energy-intensive beneficiation plants.
Industry Challenges
- Geotechnical engineering scarcity:Deep-level mechanized mining in the Witwatersrand basin requires specialized rock mechanics expertise that regional universities struggle to replenish.
- ISO 14001 certification timelines:Environmental management system audits for greenfield projects in Madagascar and Guinea routinely extend beyond 18 months, delaying construction commencement.
- Legacy asset integration:Brownfield copper expansions in Zambia must thread new shaft infrastructure around century-old colonial-era workings with incomplete geological records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Mining Market |
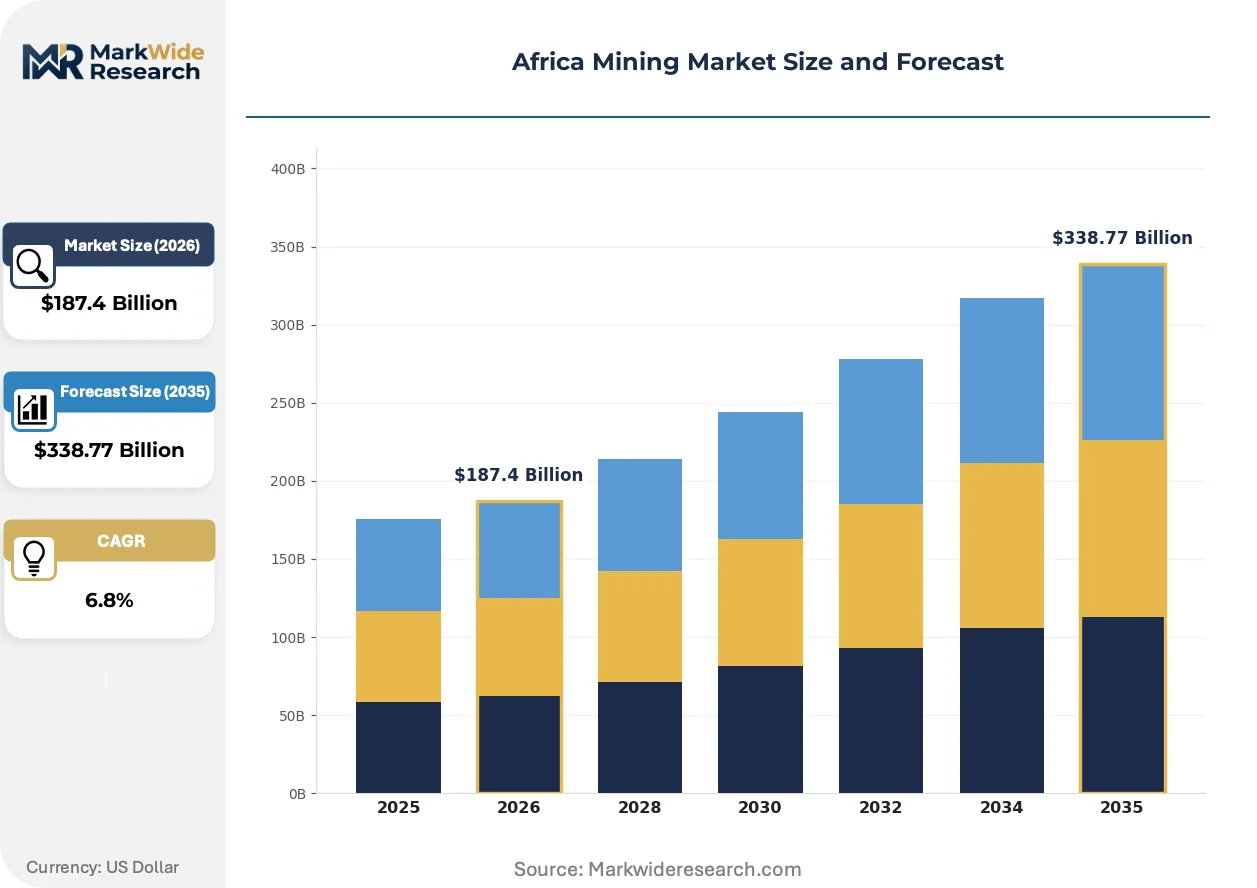
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold, Diamond, Coal, Copper Application: Metal Production, Mineral Extraction, Construction, Energy Generation End User: Mining Companies, Construction Firms, Power Utilities, Exporters Distribution Channel: Direct Sales, Distributors, Online Platforms, Retailers |
| Companies Covered | BHP Group, Glencore, Anglo American, AngloGold Ashanti, Gold Fields, Anglo American Platinum, Sibanye Gold, Harmony Gold, Impala Platinum Holdings, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Mining Market Emerging Trajectories
Digital twin platforms and predictive maintenance algorithms are displacing calendar-based equipment overhaul schedules, while regulatory pressure on scope-three emissions intensifies scrutiny of diesel-dependent extraction methods.
Autonomous drilling rigs equipped with real-time ore-grade sensors are expanding into narrow-reef platinum operations previously deemed too geologically complex for mechanization. Anglo American's Mogalakwena complex and Impala Platinum's Rustenburg shafts are deploying these systems to reduce face exposure and improve extraction selectivity. The technology is expanding into workforce restructuring, compressing skilled operator headcounts while elevating data analyst and remote operations center roles.
South Africa's Carbon Tax Act and the DRC's revised mining code enforcement apparatus are mandating emissions disclosure and community development fund contributions that alter project economics. The Extractive Industries Transparency Initiative compliance requirements now condition access to development finance from AfDB and commercial lenders. Platinum producers with scope-one intensity above sector benchmarks face capital cost premiums, accelerating renewable microgrid adoption at Bushveld Complex operations.
Integrated pit-to-port control software subscriptions are displacing perpetual license models for mine planning and fleet management systems. Tier-one operators in Botswana's diamond sector and Ghana's gold belts now demand outcome-based contracts tied to throughput guarantees rather than seat-based fees. This shift concentrates vendor bargaining power with equipment OEMs capable of bundling hardware, software, and aftermarket services under unified performance agreements.
Africa Mining Market Segmentation
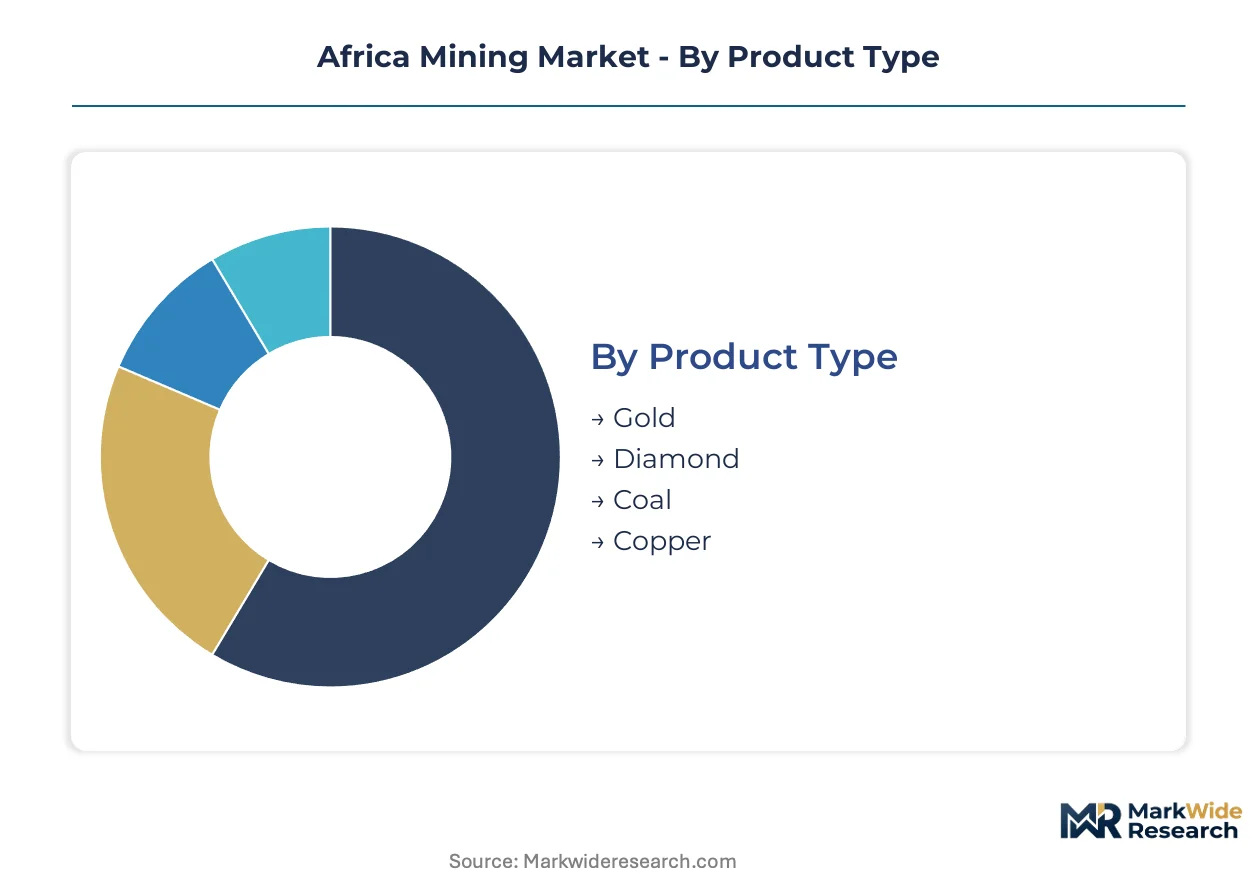
Mineral extraction across Africa demands precise segmentation to capture divergent capital intensity, ore grade economics, and export corridor dependencies. Each dimension reveals distinct procurement patterns and infrastructure requirements that shape operator technology choices and partnership structures.
Product Type:
Replacement cycles for extraction equipment vary dramatically by mineral hardness and deposit depth, driving divergent reinvestment timelines across Africa's geological belts.
- Gold:Narrow-reef deposits in the Witwatersrand basin and greenstone belts of Ghana and Mali require specialized mechanized drilling and backfill systems. Demand clusters around West African greenstone extensions where ore grades above 3 grams per tonne justify deep-level capital deployment.
- Copper:Porphyry and sediment-hosted deposits in the Central African Copperbelt span the DRC-Zambia border with ore grades typically ranging from 0.5% to 3%. Electrification infrastructure buildouts in Asia and Europe are accelerating offtake pre-commitments for solvent extraction-electrowinning output.
- Diamond:Kimberlite pipes in Botswana and alluvial deposits in Angola demand distinct processing flowsheets. Botswana's Orapa and Jwaneng operations anchor carat recovery volumes through dense medium separation circuits.
- Coal:Thermal deposits in South Africa's Mpumalanga province and metallurgical seams in Mozambique serve divergent end-markets. Regional power utilities in Southern African Power Pool jurisdictions remain the dominant offtakers despite renewable substitution pressures.
Volume placements concentrate in copper and gold; the faster expansion belongs to copper as battery metal demand intensifies.
Application:
Margin structures across application categories reflect divergent beneficiation depth and transport cost exposure.
- Metal Production:Smelting, refining, and electrowinning operations convert concentrate into cathode, bullion, or sponge. Zambia's copperbelt smelters and South Africa's platinum refineries anchor regional downstream capacity.
- Mineral Extraction:Open-pit and underground operations employing drill-blast-load-haul sequences constitute the upstream foundation. Autonomous haulage trials at Namibian and South African sites are compressing unit operating costs.
- Construction:Aggregate and dimension stone supply for infrastructure projects across Nigeria, Kenya, and Ethiopia. Local procurement mandates in public works contracts are securing captive demand for domestic quarries.
- Energy Generation:Thermal coal combustion in power stations and metallurgical coal injection in blast furnaces. Mozambique's Moatize expansion and South Africa's Eskom supply contracts dominate volume flows.
Revenue concentration sits with mineral extraction; metal production is climbing fastest as beneficiation mandates deepen.
End User:
Procurement sophistication varies sharply across buyer categories, from integrated majors to fragmented construction subcontractors.
- Mining Companies:Tier-one operators like Anglo American and Glencore deploy integrated pit-to-port control systems. Their capital allocation prioritizes automated haulage and predictive maintenance subscriptions over perpetual software licenses.
- Power Utilities:Eskom, ZESCO, and regional counterparts under the Southern African Power Pool negotiate long-term coal supply agreements. Fuel procurement teams face mounting pressure to diversify toward renewable baseload.
- Construction Firms:Infrastructure contractors across Nigeria, Kenya, and Ethiopia source aggregate and cement feedstock through spot markets. Project finance covenants increasingly mandate local content verification.
- Exporters:Trading houses and commodity merchants arbitrage between African mine gates and Asian smelters. Glencore's offtake positions in DRC copper-cobalt corridors exemplify this intermediation role.
Contract value concentrates with mining companies; power utilities are expanding most quickly as grid stabilization investments resume.
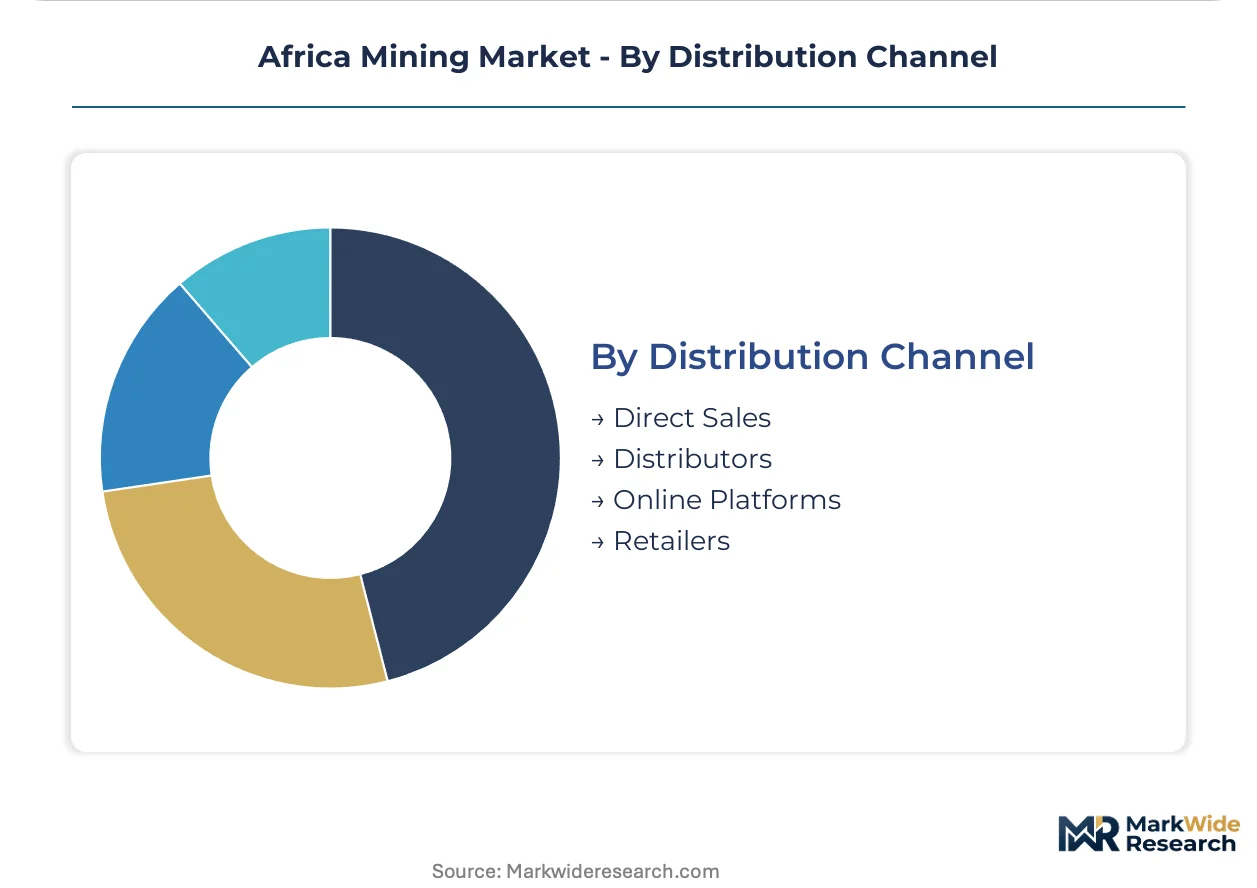
Distribution Channel:
Channel selection reflects equipment complexity, spare parts criticality, and operator technical capability.
- Direct Sales:OEMs like Caterpillar and Komatsu negotiate performance-based contracts with tier-one operators. These agreements bundle hardware, software, and aftermarket services under unified throughput guarantees.
- Distributors:Regional dealers maintain parts inventories and field service capacity across remote mining districts. Their geographic coverage determines aftermarket capture rates in Zambia and the DRC.
- Online Platforms:Procurement portals for consumables and standard spares are gaining traction among mid-tier operators. Limited penetration reflects connectivity gaps and preference for physical inspection.
- Retailers:Local supply houses serve artisanal and small-scale mining segments with basic tools and protective equipment. Informal supply chains in southeastern DRC introduce traceability complexity for downstream offtakers.
Transaction value concentrates in direct sales; distributor networks are gaining share fastest as mid-tier fleets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Africa exports the majority of its extracted mineral wealth while consuming minimal refined metal domestically, creating persistent trade imbalances that beneficiation mandates attempt to reverse. South Africa and the Democratic Republic of Congo anchor continental production volumes, though infrastructure gaps constrain value-added processing.
South Africa
The Bushveld Complex hosts the world's largest platinum group metal reserves, with Anglo American Platinum and Impala Platinum Holdings operating concentrated smelting corridors around Rustenburg and Polokwane. The Department of Mineral Resources and Energy enforces local content thresholds and carbon tax disclosures under the Carbon Tax Act. Johannesburg-Pretoria logistics clusters coordinate concentrate export through Richards Bay and Durban port terminals.
Democratic Republic of Congo
The Central African Copperbelt supplies over two-thirds of global cobalt feedstock, with Glencore and BHP Group competing for tier-one copper-cobalt assets near Kolwezi and Tenke Fungurume. The mining code enforcement apparatus mandates community development contributions and export duty frameworks that alter project economics. Southeastern artisanal mining zones introduce supply chain traceability complexity for battery metal offtakers.
Zambia
Copperbelt provinces spanning the Copperbelt and North-Western regions host sediment-hosted deposits with ore grades between 0.5% and 3%, attracting solvent extraction-electrowinning investments. The Zambia Revenue Authority's escalating royalty and tax frameworks compel foreign operators toward downstream smelter construction. Kitwe-Chingola industrial corridors anchor regional beneficiation capacity expansion.
Ghana
Ashanti and Western region greenstone belts retain mature gold margin pools with ore grades above 3 grams per tonne, sustaining deep-level capital deployment from AngloGold Ashanti and Gold Fields. The Minerals Commission enforces environmental permits and local procurement regulations under the Minerals and Mining Act. Obuasi-Tarkwa mining districts concentrate mechanized extraction and carbon-in-leach processing infrastructure.
Namibia
Erongo region uranium and diamond deposits, alongside emerging green hydrogen trials, position the country for electrolyzer-powered mining equipment pilots that could displace diesel haulage. The Ministry of Mines and Energy coordinates renewable energy concessions with extraction lease frameworks. Walvis Bay corridor development aims to reduce South African port dependency for bulk commodity exports.
Africa Mining Market Vendor Landscape
Capital-heavy integrated miners compete with trading-house intermediaries that anchor offtake without owning extraction assets. The market structures around tier-one operators with pit-to-port control capabilities, mid-tier specialists in single-commodity belts, and commodity merchants arbitraging geographic price spreads. Three archetypes dominate: diversified majors with automated haulage scale, platinum-dominant specialists with narrow-reef mechanization expertise, and trading-anchored intermediaries with DRC corridor positions. Competitive moves concentrate on automated fleet deployment and renewable microgrid integration.
Within the diversified major tier, BHP Group and Anglo American occupy positions defined by autonomous haulage trials across Southern African sites and integrated software subscriptions replacing perpetual licenses. Glencore exemplifies the trading-anchored archetype, leveraging offtake infrastructure in copper-cobalt corridors without direct operational ownership of tier-one deposits. AngloGold Ashanti and Gold Fields sit within the gold-specialist tier, concentrated in West African greenstone belts where ore grade economics justify deep-level capital allocation against narrowing margin pools.
| Leading Market Players |
|---|
| BHP Group |
| Glencore |
| Anglo American |
| AngloGold Ashanti |
| Gold Fields |
| Anglo American Platinum |
| Sibanye Gold |
| Harmony Gold |
| Impala Platinum Holdings |
| Others |
Supply Flow & Price Mechanics
Autonomous haulage system deployments across Namibian and South African open-pit operations are compressing unit operating costs while concentrating procurement power with equipment OEMs capable of bundling hardware, software, and aftermarket services. This technology transition simultaneously reshapes capital expenditure timelines and supplier consolidation dynamics across the African copper belt.
Pricing Analysis
Margin tightening in mid-tier operator tiers reflects the shift from perpetual software licenses toward outcome-based subscriptions tied to throughput guarantees. Price differentiation rests on automation integration depth and renewable microgrid certification status, with tier-one operators least sensitive due to captive maintenance capabilities. Cost compression accelerates in construction aggregate segments as local procurement mandates intensify competitive bidding.
Supply Chain Analysis
Refurbishment flows for heavy mining equipment center on South African industrial corridors, where component remanufacturing extends fleet life cycles. Geographic supply concentrates in China for battery-grade processing reagents, South Africa for platinum group metal refining capacity, and the DRC for cobalt feedstock. Raw material dependencies span diesel fuel from regional refineries, grinding media from Indian steel mills, and explosives from specialized chemical suppliers. Single-source vulnerability persists in haul truck engine supply. Distribution runs through OEM direct sales for tier-one operators and regional distributor networks for mid-tier fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into downstream beneficiation capacity represents the decisive competitive race across the African mining sector, with copper-cobalt corridor operators pursuing captive smelter investments to satisfy escalating local content mandates.
For Market Incumbents: Deepen pit-to-port software integration to lock in subscription revenue streams and defend against trading-house intermediaries anchoring offtake without operational assets. Prioritize renewable microgrid certification to secure development finance access under tightening ESG disclosure requirements. Expand automated haulage deployments to extend mine life at marginal ore bodies.
For New Entrants and Emerging Players: Capture construction aggregate procurement contracts tied to infrastructure buildouts across Nigeria, Kenya, and Ethiopia where local content verification creates barrier-protected demand. Target artisanal mining formalization programs in southeastern DRC for traceability-compliant cobalt supply. Pursue joint venture structures with established logistics providers to overcome port infrastructure deficits.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified majors seeking automated fleet scale or trading houses consolidating copper-cobalt corridor positions. Long-term viability hinges on operators with demonstrated community development fund compliance and ISO 14001 certification timelines within sector benchmarks. Monitor battery metal offtake pre-commitment volumes as inflection indicator for capital allocation sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Haulage Deployment | Anglo American's pit-to-port control demonstrates throughput gains that compress unit costs at marginal ore bodies. |
| Beneficiation Capacity Buildout | Zambia's escalating royalty frameworks compel foreign operators toward captive smelter construction. |
| Renewable Microgrid Integration | Namibia's green hydrogen trials position electrolyzer-powered equipment to displace diesel in heavy haulage. |
| Digital Twin Platform Adoption | Predictive maintenance algorithms displace calendar-based overhaul schedules across platinum narrow-reef operations. |
| Artisanal Supply Chain Formalization | Traceability-compliant cobalt sourcing addresses ESG liability for battery metal offtakers in the DRC. |
Methodological Framework
SEC filings, Extractive Industries Transparency Initiative disclosures, and Southern African Power Pool generation data formed the secondary backbone, cross-referenced against primary interviews with mine planning engineers, procurement directors at tier-one operators, renewable energy project developers, and logistics coordinators at Richards Bay and Durban terminals. Bottom-up equipment deployment tallies and top-down mineral export value flows were triangulated to reconcile volume estimates.
Historical capital expenditure patterns and ore grade economics across the analysis window established baseline growth trajectories. Segmentation modeling captured mineral type, application depth, end-user procurement sophistication, and distribution channel structure. CAGRs were derived from mineral-specific demand vectors including battery metal offtake pre-commitments and power utility fuel diversification pressures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to grid infrastructure buildout pace, artisanal mining formalization progress, and carbon tax enforcement intensity across Southern African jurisdictions. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Connected Mining Market
Mining Equipment
Mining Tester Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Rock Duster Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Underground Mining Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Smart Mining Market
Mining Equipment
Magnetic Sweepers Market