
 Surface Mining Market | 2026-2036
Surface Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Mining Market Analysis
Ultra-high-capacity dump truck specifications above 400-ton payload is bifurcating the equipment procurement landscape. BHP Group leverages captive maintenance networks to sustain fleet uptime across Pilbara operations. Rio Tinto anchors autonomous haulage leadership through its integrated mine-to-port systems. Vale SA differentiates via deep-water port logistics that compete on Atlantic Basin delivery cycles.
Surface mining denotes the mechanical removal of overburden and ore deposits from exposed terrain using open excavation methods, with pit slope angles typically engineered between 35 and 55 degrees depending on geotechnical stability and stripping ratios. The primary commercial purpose centers on extracting near-surface mineral reserves where underground shaft development would exceed economic thresholds. Strip mining of thermal coal retains mature volume dominance across Powder River Basin-style deposits, though open-pit copper operations capture expanding margin pools as electrification-grade concentrate premiums widen. Mountaintop removal persists in specific Appalachian regulatory jurisdictions but confronts structural decline as utility procurement shifts toward lower-carbon alternatives.
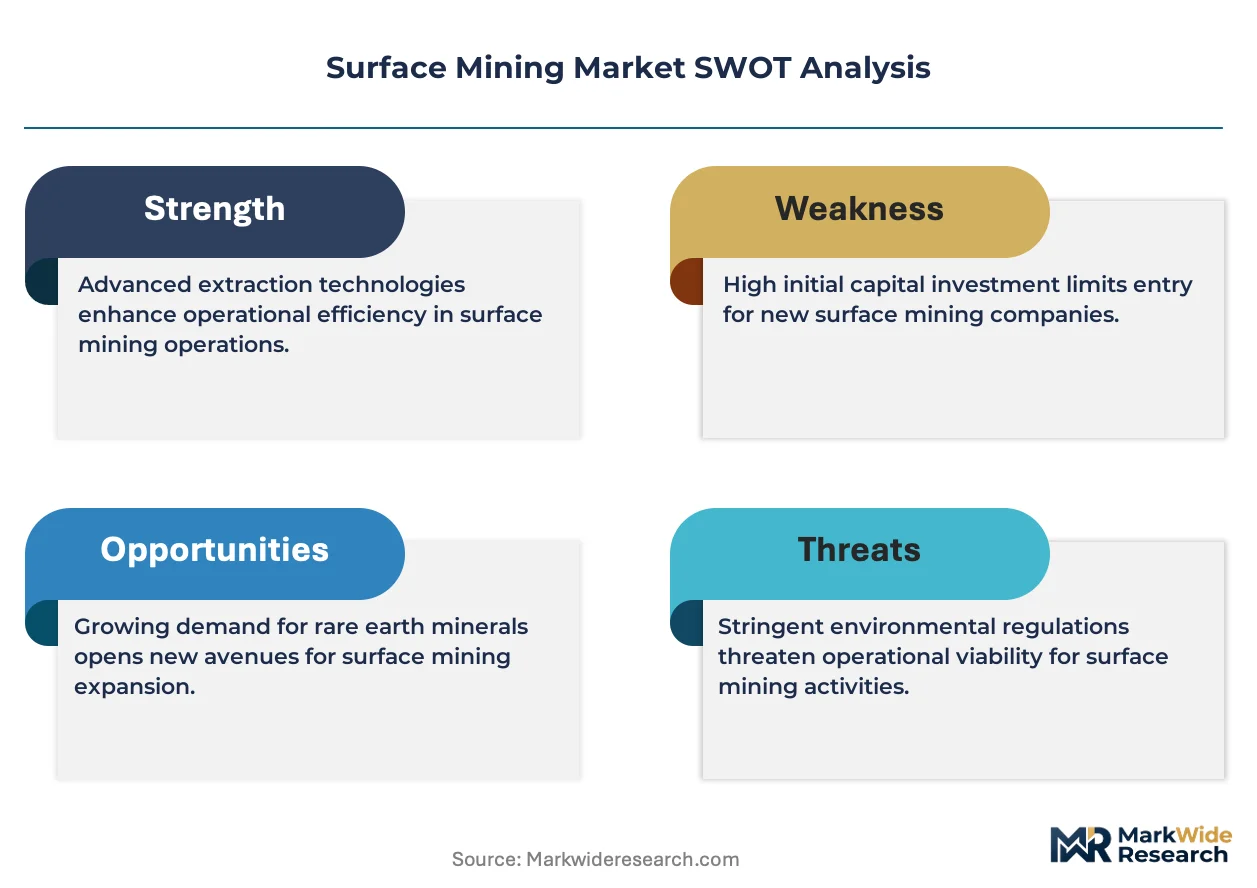
OSHA mandates govern worker exposure limits to respirable silica and diesel particulate matter across US surface operations, while EPA Clean Air Act provisions shape permitting timelines for greenfield pit development. The EU Green Deal carbon border adjustment mechanism pressures export-oriented mines to document scope-one and scope-two emissions intensity. Stakeholders must monitor how tightening tailings storage facility standards from multiple national mining regulators reshape capital allocation toward dry-stack alternatives and in-pit disposal architectures.
Market Dynamics
Autonomous haulage systems are decomposing the traditional owner-operator fleet model across large-scale surface operations, forcing capital reallocation toward integrated mine-to-port automation architectures and captive maintenance networks.
Growth Catalysts
- Copper electrification pull:Energy utilities are expanding concentrate offtake agreements for grid infrastructure and EV supply chains, tightening long-term contract structures.
- EU Green Deal carbon border mechanism:Export-oriented mines face documentation mandates for scope-one and scope-two emissions intensity, accelerating low-carbon process investment.
- Autonomous truck deployment:Large-scale pit operators are retrofitting haul fleets with collision-avoidance and centralized dispatch systems, compressing labor cost structures.
Market Restraints
- Diesel particulate exposure limits:OSHA mandates governing respirable silica and diesel particulate matter across US surface operations are extending permitting timelines and compliance costs.
- Equipment supply concentration:Ultra-high-capacity dump truck manufacturing above 400-ton payload concentrates among three integrated OEMs, creating procurement bottlenecks.
- Tailings facility liability:Multiple national mining regulators are tightening tailings storage standards, redirecting capital toward dry-stack alternatives and in-pit disposal.
Strategic Opportunities
- Western Australia basin expansion:Pilbara iron ore operators are integrating autonomous haulage with deep-water port logistics, capturing Atlantic Basin delivery cycle advantages.
- In-pit crushing and conveying:Convergence of mobile crushing units with overland conveyor systems is displacing diesel truck haulage in greenfield copper developments.
- US Inflation Reduction Act:Critical minerals production tax credits are incentivizing domestic copper and rare earth surface extraction project financing.
Industry Challenges
- Autonomous systems integration:Legacy fleet management platforms require complete replacement to interface with centralized dispatch algorithms, extending commissioning timelines.
- Geotechnical specialist scarcity:Qualified pit slope stability engineers and mine planning optimization analysts command premium compensation, constraining expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Mining Market |
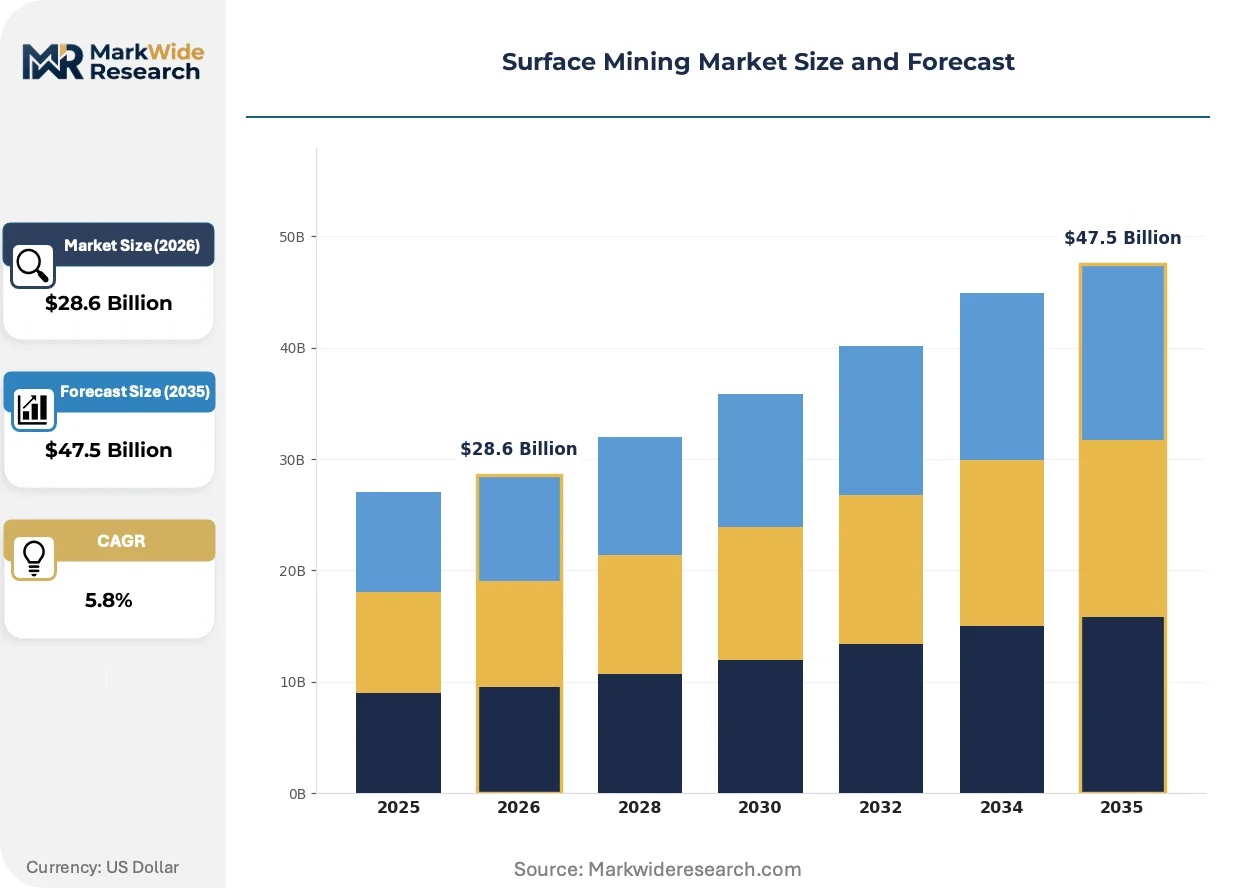
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Dump Trucks, Drills, Loaders Operating Technique: Strip Mining, Open-pit Mining, Mountaintop Removal, Dredging Material Extracted: Coal, Copper, Iron Ore, Bauxite End User: Energy Sector, Manufacturing, Construction, Infrastructure |
| Companies Covered | Vale SA, Newmont Corporation, Glencore, Zijin Mining, China Molybdenum, BHP Group, Freeport-McMoRan, ArcelorMittal Mining, Rio Tinto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Mining Market Emerging Trajectories
Digital twin technology and electrified mobile equipment are converging to compress operating cost structures while tightening environmental compliance margins across open-pit operations.
Electrified trolley-assist and battery-electric haul trucks are decomposing the diesel-dominated energy model in surface mining. Tier-one copper operators in Chile and Peru are piloting 300-ton-class electric trucks on dedicated trolley lines. This technology is decomposing fuel procurement contracts and maintenance intervals while forcing grid infrastructure investment at mine sites.
EPA Clean Air Act provisions are extending greenfield pit permitting timelines through enhanced ambient air quality modeling requirements. New source review thresholds now capture fugitive dust and mobile source emissions in consolidated impact assessments. Western US copper developers are responding with enclosed crushing circuits and covered ore stockpiles to accelerate approval cycles.
Buyers are consolidating equipment procurement through lifecycle cost contracts rather than upfront capital purchase. Major diversified miners are unbundling maintenance services from OEM supply agreements, instead awarding multi-year performance contracts to third-party specialists. This pattern is most visible across Australian iron ore basins where fleet scale justifies captive technical labor pools.
Surface Mining Market Segmentation
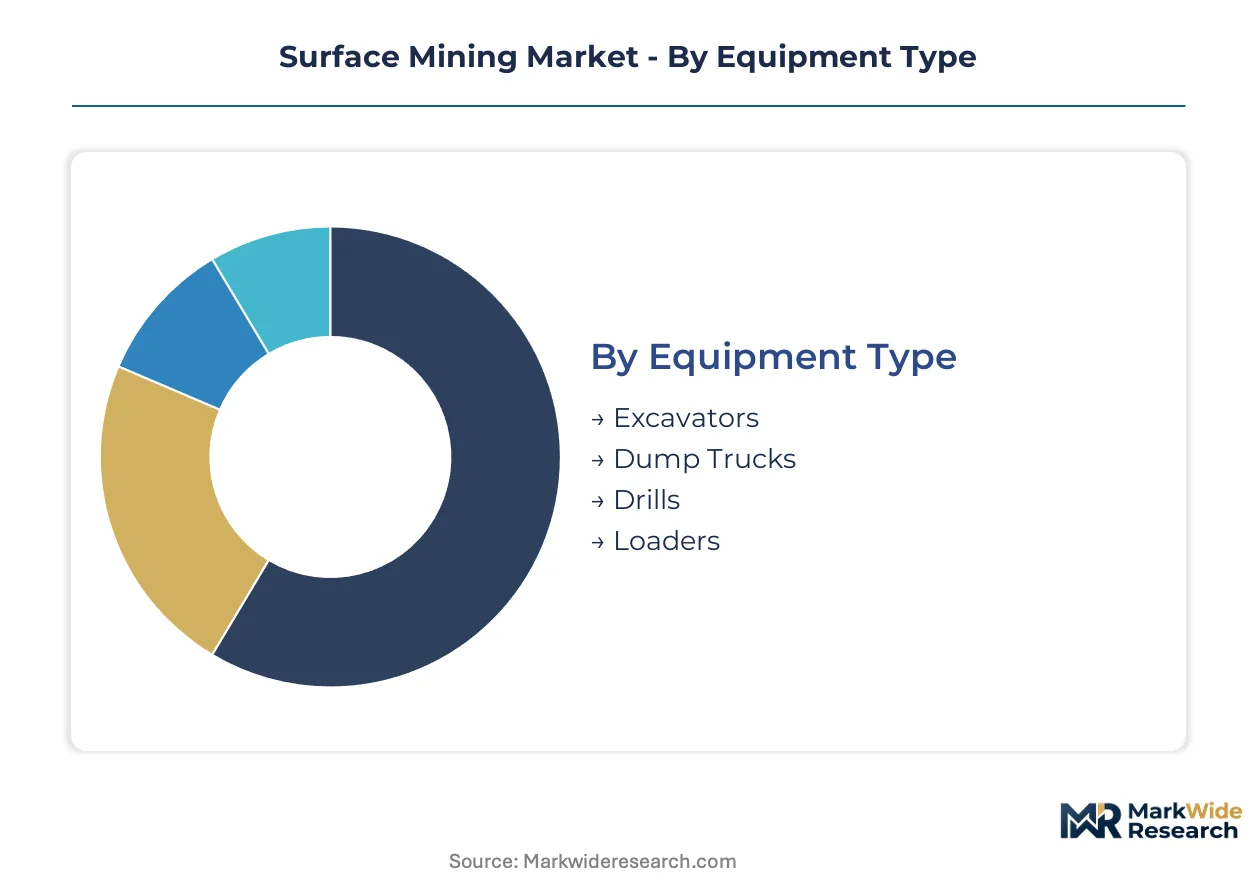
Equipment specifications and extraction methods determine capital deployment patterns across surface mining operations. Mining companies align procurement decisions with deposit geometry, mineral grade, and regulatory compliance requirements.
Equipment Type:
Margin pools concentrate in ultra-high-capacity haulage systems where fleet scale justifies captive maintenance networks.
- Dump Trucks:Payload capacities above 400 tons dominate large-scale copper and iron ore basins. Autonomous retrofit programs at Pilbara and Chilean operations are compressing labor cost structures while extending maintenance intervals.
- Excavators:Electric rope shovels and hydraulic excavators above 100-ton operating weight handle overburden removal in strip mining configurations. Demand clusters in Western Australia where BHP Group and Rio Tinto operate integrated basins requiring matched loading-hauling cycles.
- Drills:Rotary and percussion drilling rigs execute blasthole patterns for ore fragmentation. Pit geometry and rock hardness dictate specification selection.
- Loaders:Wheel loaders and hydraulic shovels perform selective ore extraction and rehandling duties. Underground-to-surface material transfer applications sustain replacement demand.
The dominant share belongs to dump trucks, while excavators are closing the gap fastest through electrification retrofit programs.
Operating Technique:
Application characteristics vary sharply by overburden thickness, terrain morphology, and water table depth.
- Open-pit Mining:Bench-and-berm excavation methods access steeply dipping or deep-seated ore bodies. Chilean copper porphyries and Peruvian gold-silver deposits deploy truck-shovel fleets with in-pit crushing and conveying systems displacing diesel haulage.
- Strip Mining:Horizontal seam removal dominates thermal coal extraction across Powder River Basin-style deposits. Dragline-overburden removal paired with truck-and-shovel coal recovery sustains mature volume positions despite utility procurement shifts.
- Mountaintop Removal:Valley-fill overburden disposal persists in specific Appalachian regulatory jurisdictions. EPA Clean Water Act enforcement and utility decarbonization commitments are constraining permit renewals.
- Dredging:Floating cutter-suction and bucket-ladder systems recover alluvial minerals from submerged deposits. Tin and mineral sands operations in Southeast Asian basins apply this technique where water cover precludes conventional excavation.
Strip mining retains volume leadership in coal basins, though open-pit mining is expanding most quickly through copper electrification projects.
Material Extracted:
Commodity price cycles and end-use demand patterns reshape equipment utilization rates across mineral categories.
- Copper:Sulfide and oxide ore bodies supply concentrate and cathode for grid infrastructure and EV supply chains. Energy utilities are tightening long-term offtake contract structures for electrification-grade material.
- Iron Ore:Hematite and magnetite deposits in the Pilbara and Brazilian Carajás sustain seaborne trade flows. Vale SA differentiates via deep-water port logistics competing on Atlantic Basin delivery cycles.
- Coal:Thermal and metallurgical grades retain diverging demand trajectories as steelmaking persists while power generation retreats. Powder River Basin operations face structural pressure from lower-carbon alternatives.
- Bauxite:Lateritic deposits feed alumina refineries and primary aluminum smelters. Guinea and Australian surface mines supply Atlantic and Pacific Basin smelter networks.
Iron ore commands the largest equipment installed base, while copper is gaining share fastest through electrification infrastructure investment.
End User:
Customer procurement patterns diverge between commodity traders, integrated miners, and state-owned enterprises with diverging risk appetites.
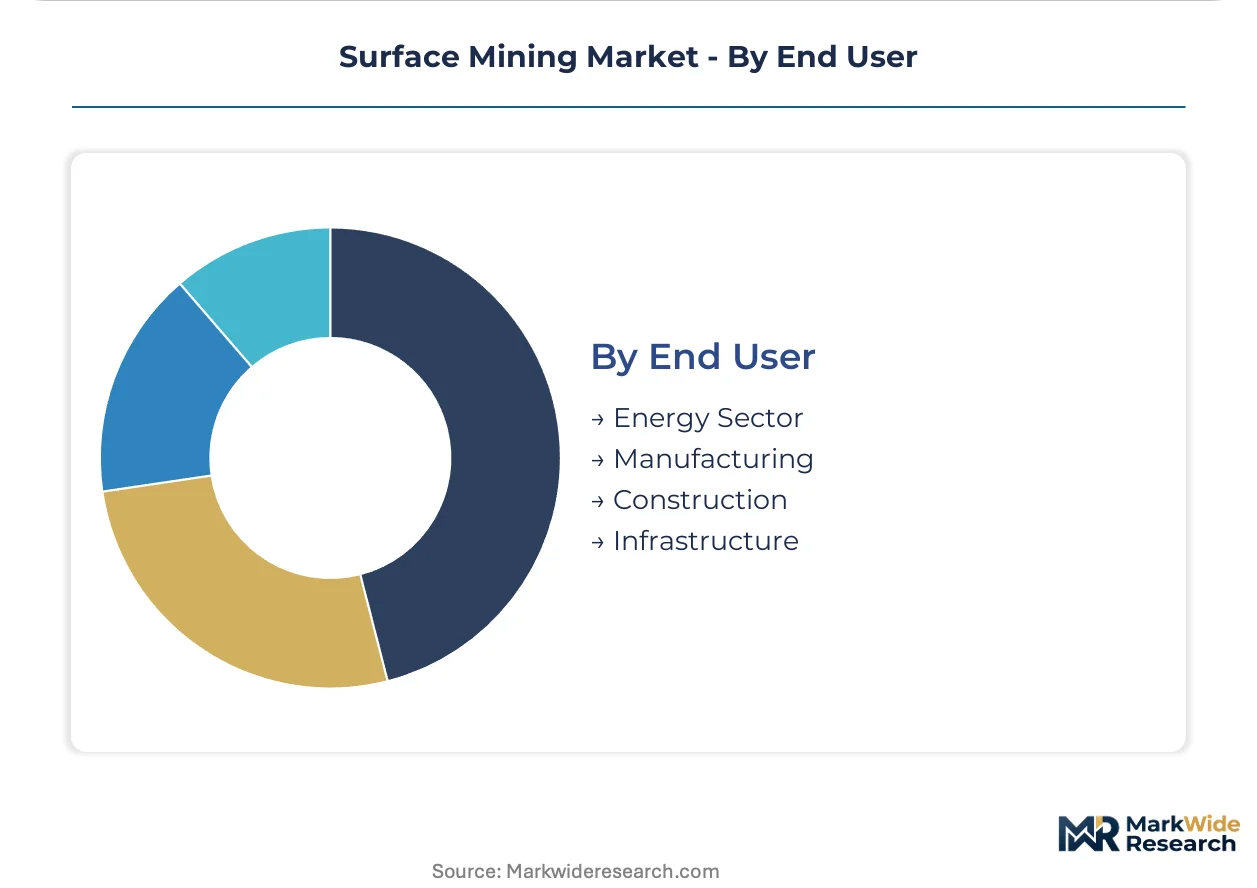
- Energy Sector:Utilities and independent power producers procure thermal coal and uranium for baseload generation. Carbon border adjustment mechanisms are redirecting sourcing toward documented low-carbon supply chains.
- Manufacturing:Steel mills, aluminum smelters, and copper fabricators secure concentrate and ore feedstock under long-term contracts. Just-in-time inventory practices are displacing stockpile-heavy procurement.
- Construction:Cement producers and aggregate suppliers extract limestone, sand, and gravel through quarried surface operations. Urban proximity constraints are tightening permitting timelines.
- Infrastructure:Government-funded projects specify domestic-sourced construction materials under procurement mandates. US Inflation Reduction Act critical minerals provisions are incentivizing domestic surface extraction financing.
The energy sector maintains the deepest equipment relationships, while manufacturing is closing the gap fastest through metals electrification demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-capacity equipment procurement concentrates in mineral-rich jurisdictions where integrated miners operate captive maintenance networks. Australia, Chile, China, and Brazil anchor surface mining investment through distinct regulatory and geological profiles. Peru and South Africa complete the top-tier geography set through copper and platinum group metal extraction.
Australia
Pilbara iron ore basins drive autonomous haulage deployment at scale. EPA Western Australia mandates tailings storage facility audits under updated dam safety protocols. BHP Group and Rio Tinto operate integrated mine-to-port systems across Newman, Port Hedland, and Karratha.
Chile
Copper porphyry deposits supply electrification-grade concentrate to Asian and European utilities. Ministry of Mining enforces closure plan guarantees and progressive rehabilitation bonds. Antofagasta and Calama host truck-shovel fleets with in-pit crushing and conveying retrofits.
China
Domestic coal and rare earth surface extraction sustains equipment replacement cycles. Ministry of Emergency Management tightened open-pit safety inspections following 2023 pit wall failures. Inner Mongolia and Shanxi province basins deploy electric rope shovels above 100-ton operating weight.
Brazil
Carajás iron ore and Minas Gerais pellet feed operations compete on Atlantic Basin delivery cycles. ANM (National Mining Agency) requires dam stability certification for upstream tailings configurations. Vale SA anchors deep-water port logistics through São Luís and Vitória terminals.
Peru
Andean copper-gold skarn and porphyry deposits attract concentrate offtake investment from Chinese smelters. Ministry of Energy and Mines enforces environmental impact study thresholds for greenfield pit development. Arequipa and Ancash regions host open-pit operations with diesel-to-trolley electrification pilots.
Surface Mining Market Vendor Landscape
Concentration sits with diversified mining majors that integrate extraction with logistics and downstream processing. The competitive structure divides between asset-heavy integrated operators, state-backed resource enterprises, and mid-tier specialists with single-commodity focus. Strategic moves center on autonomous fleet deployment and captive maintenance network construction rather than conventional mergers.
Among diversified mining majors, BHP Group, Rio Tinto, and Vale SA exemplify the integrated archetype through Pilbara and Carajás basin dominance. Vale SA occupies a position defined by deep-water Atlantic port access. BHP Group and Rio Tinto anchor autonomous haulage leadership through mine-to-port system integration. State-backed operators including Zijin Mining and China Molybdenum represent the resource-security-driven tier with upstream concentrate control objectives.
| Leading Market Players |
|---|
| Vale SA |
| Newmont Corporation |
| Glencore |
| Zijin Mining |
| China Molybdenum |
| BHP Group |
| Freeport-McMoRan |
| ArcelorMittal Mining |
| Rio Tinto |
| Others |
Supply Flow & Price Mechanics
Electrified trolley-assist systems replacing diesel haulage simultaneously redraw equipment procurement geography toward Chilean and Australian copper basins and compress lifecycle cost premiums against conventional fleets. This substitution dynamic forces OEMs to reprice maintenance contracts around battery-electric uptime guarantees while buyers consolidate procurement through performance-based agreements.
Pricing Analysis
EU Green Deal carbon border adjustment mechanism dictates the pricing tier structure across export-oriented concentrate supply chains. Three-tier pricing structure across electrification-grade premium, industrial-standard, and legacy-economy concentrate levels separates documented low-carbon copper from emissions-intensive alternatives. Cost compression in standard-tier thermal coal contracts is intensifying because utility procurement shifts toward lower-carbon baseload alternatives. Integrated miners with captive port logistics exhibit lowest price sensitivity; mid-tier traders without long-term offtake anchors face margin erosion fastest.
Supply Chain Analysis
Just-in-time inventory practices among Asian smelters are displacing strategic stockpile preferences that historically dominated seaborne iron ore procurement. Ultra-high-capacity dump truck manufacturing concentrates in Germany, Japan, and the United States, while copper concentrate processing capacity clusters in China and Chile. Supply chain risk centers on single-source vulnerability for 400-ton-class autonomous haulage platforms where three integrated OEMs control production. Distribution runs through mine-to-port integrated systems at Pilbara and Carajás basins rather than third-party logistics intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous haulage fragmentation across legacy fleet retrofits and greenfield deployments creates specialist niches for maintenance network operators and electrification retrofit providers. Copper electrification demand from grid infrastructure and EV supply chains multiplies entry points beyond traditional integrated mining majors.
For Market Incumbents: Secure captive maintenance network scale across Pilbara and Chilean basins before third-party specialists capture lifecycle contract volumes. Defend against autonomous systems integration delays by pre-positioning technical labor pools at Antofagasta and Newman clusters. Vertical integration into trolley-assist grid infrastructure at mine sites locks in electrification transition margins. For New Entrants and Emerging Players: Anchor in Peruvian copper-gold skarn districts where Chinese smelter offtake investment outruns local maintenance capacity. Target in-pit crushing and conveying retrofits as the most penetrable equipment segment, with greenfield copper developments in Brazil and Peru requiring displacement of diesel truck haulage. Pursue performance-based maintenance contracts unbundled from OEM supply agreements as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at an electrification capex cycle phase that favors autonomous fleet technology providers and mine-site grid infrastructure developers. Long-term viability over the next decade rests on exposure to copper concentrate supply chains rather than thermal coal basin assets. Watch autonomous truck deployment velocity at tier-one Pilbara operations as the inflection indicator for maintenance network consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Fleet Retrofit | Rio Tinto's mine-to-port integration demonstrates labor cost compression at scale. |
| Trolley-Assist Electrification | Chilean copper operators pilot 300-ton-class electric trucks on dedicated lines. |
| Captive Maintenance Network | BHP Group sustains fleet uptime through technical labor pools at Pilbara. |
| In-Pit Crushing Conveyance | Greenfield copper developments displace diesel haulage with mobile crushing units. |
| Dry-Stack Tailings Transition | ANM dam stability certification redirects capital from conventional storage facilities. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC mining company filings, ANM regulatory submissions, and equipment OEM technical documentation. Mine operations executives, autonomous systems integration specialists, and port logistics directors provided operational validation. EPA Clean Air Act permitting databases and EU carbon border adjustment mechanism draft regulations supplied regulatory boundary conditions. Bottom-up equipment procurement tracking and top-down basin-level production estimates achieved triangulation.
Segmentation dimensions modeled span equipment type, operating technique, material extracted, and end-user procurement pattern across the projection horizon. CAGRs derive from basin-level capacity expansion announcements, autonomous deployment timelines, and concentrate offtake contract structures. Electrification infrastructure investment curves and tailings facility capital reallocation patterns inform industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained copper electrification demand and progressive tailings regulation tightening; material deviation would warrant model refresh. Revision becomes warranted when autonomous truck deployment velocity at tier-one operations crosses below maintenance network capacity expansion thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Smart Mining Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Horizontal Shaft Impact Crusher Market