
 Global Rainwater Harvesting System Market | 2026-2036
Global Rainwater Harvesting System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rainwater Harvesting System Market Outlook
Fragmentation among commercial property developers is recalibrating procurement patterns across the rainwater harvesting value chain. Kingspan Group PLC leverages its insulated panel manufacturing base to bundle storage solutions with building envelope contracts. Graf Group anchors European demand through rotational molding capacity for polyethylene cisterns. Watts Water Technologies competes on filtration integration, connecting rainwater systems to broader plumbing infrastructure portfolios.
A rainwater harvesting system captures, stores, and treats precipitation from roof surfaces and impermeable catchments for non-potable reuse, typically incorporating first-flush diverters, sediment filtration, and UV or chlorine disinfection to meet local water quality parameters. The primary purpose is reducing municipal water withdrawals for irrigation, toilet flushing, cooling towers, and industrial process water. Gravity systems dominate residential installations where elevation differentials eliminate pumping costs, while hybrid configurations are capturing margin pools in commercial projects seeking LEED certification credits. Agricultural end users sustain steady demand for large-diameter cisterns paired with conveyance networks, though filtration and pump segments concentrate value in industrial applications requiring treated process water.
The EPA's Stormwater Pollution Prevention standards and the EU Water Framework Directive shape product specifications for runoff quality and storage materials, while Australia's state-level BASIX requirements in New South Wales mandate minimum rainwater capture volumes in new buildings. China's MEE enforces sponge city construction guidelines that incorporate distributed rainwater retention as gray-green infrastructure. Stakeholders must monitor how evolving municipal plumbing codes treat cross-connection controls between potable and rainwater distribution networks.
Market Dynamics
Municipal water utilities across drought-prone regions are expanding procurement of distributed storage infrastructure, recalibrating capital allocation away from centralized treatment plants toward modular catchment systems that reduce transmission losses and defer pipeline expansion costs.
Growth Catalysts
- EU Green Deal water efficiency mandates:Compliance-driven installations are accelerating across member states as building renovation passports incorporate rainwater capture quotas.
- Australia's BASIX requirements:New South Wales mandates minimum rainwater capture volumes in new buildings, creating guaranteed demand for cistern and filtration contractors.
- China's sponge city construction guidelines:The MEE enforces distributed rainwater retention as gray-green infrastructure, opening procurement channels for modular retention systems in 30 pilot cities.
Market Restraints
- Polyethylene resin price volatility:Rotational molding feedstock costs fluctuate with petrochemical cycles, compressing margins for tank manufacturers without long-term supply contracts.
- Cross-connection control complexity:Municipal plumbing code variations between jurisdictions create compliance friction for system designers seeking multi-state or multi-country certification.
- Groundwater substitution in agricultural zones:Cheap borehole access in India and parts of sub-Saharan Africa undercuts rainwater harvesting economics for irrigation.
Strategic Opportunities
- Indonesia's urban densification:Jakarta's flood mitigation infrastructure bonds are funding integrated rainwater harvesting in public housing, creating a captive channel for gravity-fed residential systems.
- LEED certification credit convergence:Hybrid configurations that combine rainwater reuse with solar thermal systems are capturing margin pools in commercial projects seeking dual sustainability credentials.
- Industrial process water quality gaps:Untapped demand exists for treated rainwater in semiconductor fabs and data center cooling towers requiring low-conductivity feedwater.
Industry Challenges
- Certification timeline compression:NSF/ANSI 61 and AS/NZS 4020 potable contact approvals require 12-18 month validation cycles that delay product launches.
- Integration complexity with legacy stormwater infrastructure:Retrofitting first-flush diverters into existing gutter networks demands skilled labor that remains scarce in secondary construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rainwater Harvesting System Market |
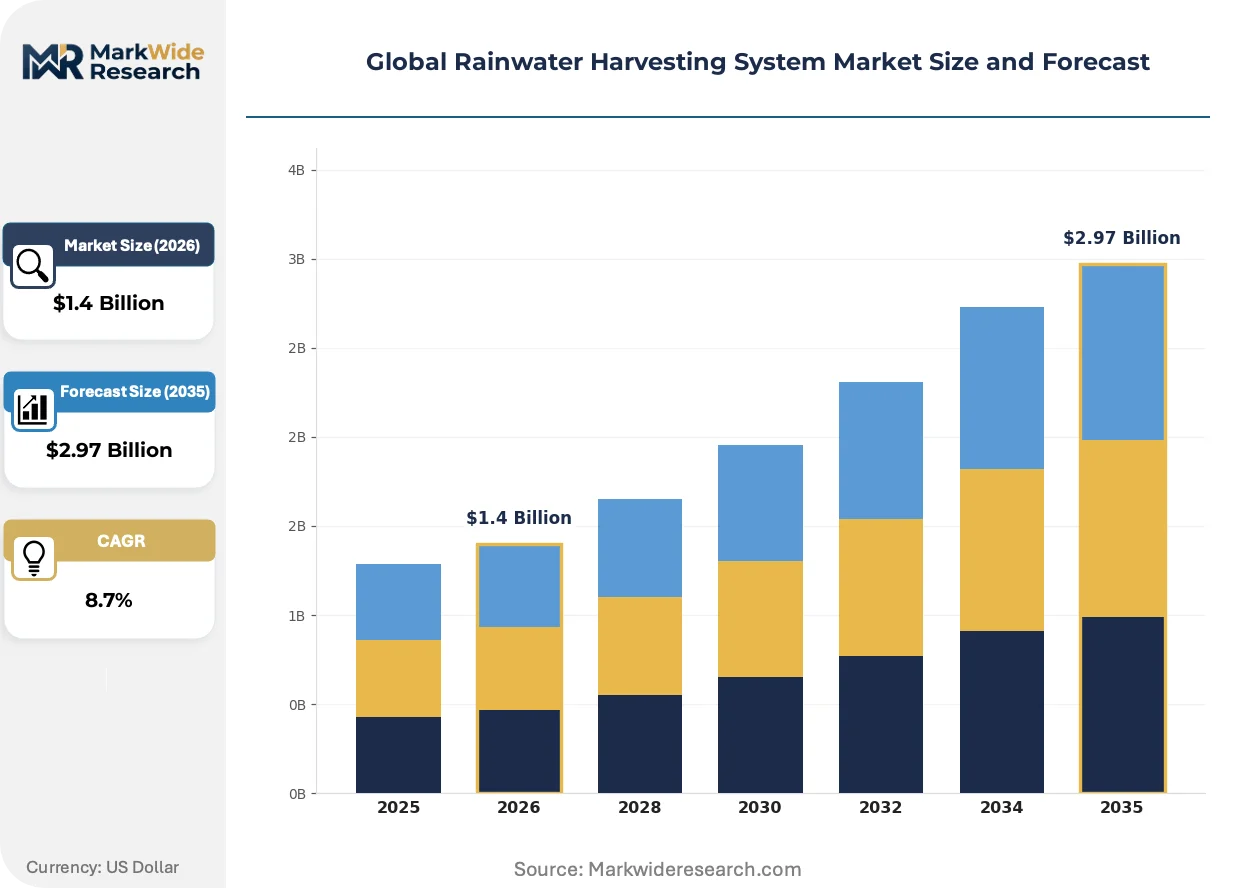
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cisterns, Tanks, Filters, Pumps Technology: Gravity Systems, Pumped Systems, Hybrid Systems, Filtration Systems End User: Residential, Commercial, Agricultural, Industrial Component: Storage, Disinfection, Conveyance, Treatment |
| Companies Covered | Kingspan Group PLC, Graf Group, WISY AG, Watts Water Technologies, Stormsaver Ltd, Ecozi Ltd, Molloy Precast Products Ltd, Innovative Water Solutions LLC, Rainwater Harvesting Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rainwater Harvesting System Market Strategic Shifts
Digital monitoring and predictive maintenance capabilities are penetrating rainwater harvesting systems, transforming passive storage assets into connected infrastructure that utilities can manage remotely.
Smart tank level sensors with cellular connectivity are modularizing system architecture by enabling remote pump control and automated municipal backup switching. Commercial property managers in Australia and Germany are adopting these retrofit kits to reduce manual inspection labor. The technology is modularizing service contracts from hardware sales toward recurring monitoring revenue.
The EU Water Framework Directive's tightening runoff quality standards are forcing cistern manufacturers toward food-grade resin formulations and internal coating upgrades. Industrial consequence includes elevated R&D spend for rotational molders seeking CE marking compliance. Above-ground polyethylene tanks for commercial sites face the steepest specification changes, with German regulators leading enforcement.
Buyer preference is rotating toward performance-guaranteed service contracts rather than component procurement. Facility managers in Singapore and California are demanding guaranteed cubic-meter delivery volumes with penalty clauses for shortfall. This compresses vendor risk onto system operators and favors vertically integrated providers with captive maintenance networks. The shift is most visible in healthcare and education verticals where budget predictability outweighs capital ownership.
Global Rainwater Harvesting System Market Segmentation
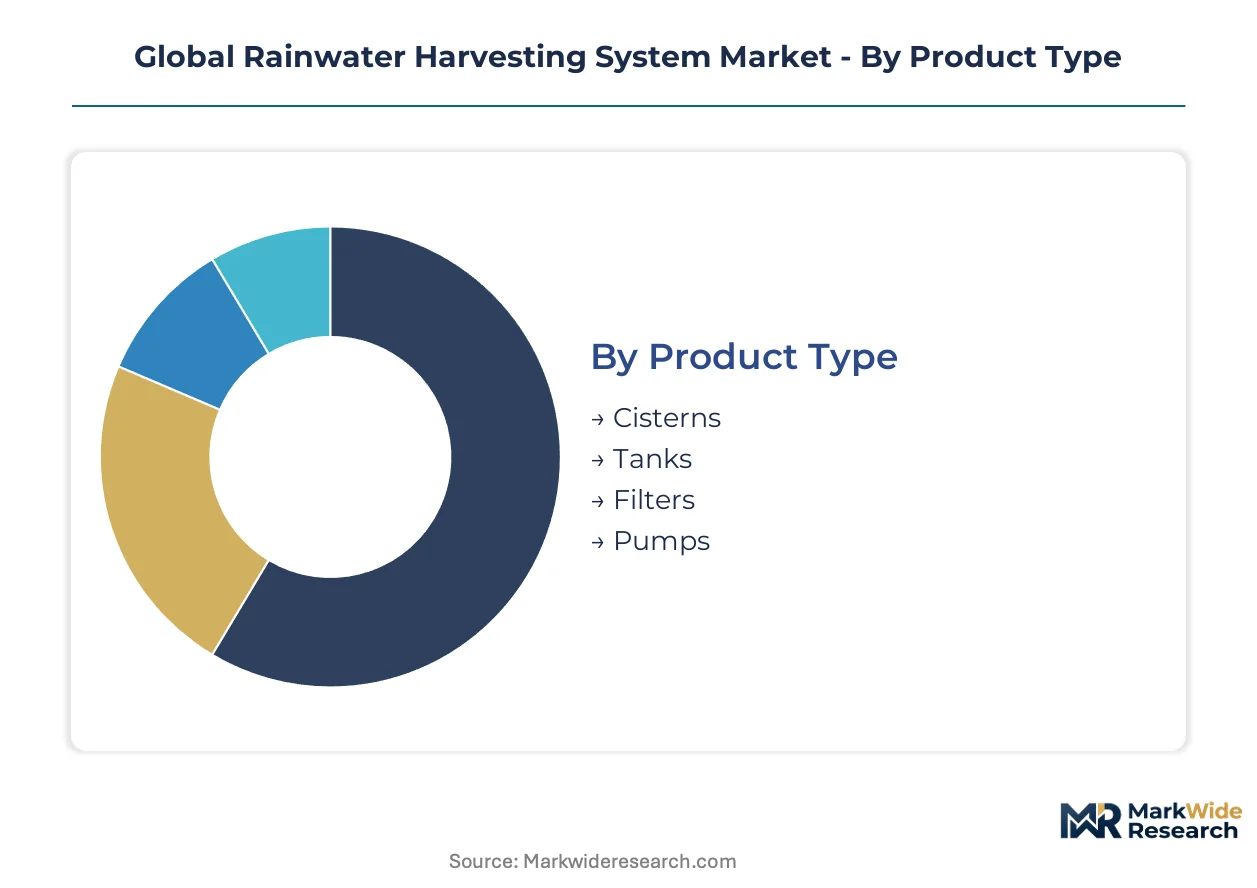
Rainwater harvesting systems fragment across multiple technical and application dimensions. Product architecture, installation context, and water quality requirements each dictate distinct procurement patterns and margin structures across the value chain.
Product Type:
Standardization dominates at the tank level while filtration and pumping equipment demand greater specification flexibility.
- Cisterns:Underground concrete and polyethylene vessels ranging from 1,000 to 50,000 liter capacities anchor system economics. Australian residential construction in New South Wales and Victoria drives volume through BASIX-mandated minimum capture volumes per dwelling.
- Tanks:Above-ground rotational-molded polyethylene dominates commercial and agricultural installations where excavation costs prove prohibitive. German regulators under the EU Water Framework Directive are tightening material specifications for food-grade resin formulations.
- Filters:Sediment and carbon block configurations protect downstream pumps and meet discharge quality standards.
- Pumps:Submersible and surface-mounted units sized to overcome elevation differentials and pressure requirements.
Most installed capacity flows through Cisterns. Expansion is steepest in Filters as water quality mandates tighten across industrial applications.
Technology:
Cost tier separates passive gravity installations from active pumped configurations requiring electrical infrastructure.
- Gravity Systems:Passive collection and distribution relying solely on elevation differentials eliminates pumping costs and maintenance complexity. Residential demand concentrates in Indonesia's public housing developments funded through Jakarta's flood mitigation infrastructure bonds.
- Pumped Systems:Electric booster pumps overcome flat terrain and enable pressurized distribution to upper building levels. Commercial property managers in Singapore specify these for guaranteed cubic-meter delivery contracts with penalty clauses.
- Hybrid Systems:Gravity primary with pump backup for drought periods or peak demand events.
- Filtration Systems:Multi-stage treatment trains incorporating first-flush diversion, sediment removal, and UV or chlorine disinfection.
Gravity Systems retain the largest installed base. Hybrid Systems are climbing the fastest as LEED certification credit convergence drives commercial specification.
End User:
Application maturity varies sharply between established agricultural practice and emerging industrial process water substitution.
- Residential:Single-family and multi-unit dwellings employing gravity or small-pumped systems for irrigation and toilet flushing. Australia's state-level mandates create guaranteed demand channels distinct from discretionary adoption elsewhere.
- Commercial:Office, retail, and hospitality properties seeking operational cost reduction and sustainability credentials. California facility managers are shifting from component procurement to performance-guaranteed service contracts with penalty structures.
- Agricultural:Large-diameter cisterns paired with conveyance networks for irrigation supply.
- Industrial:Treated rainwater for cooling towers, process water, and vehicle washing requiring conductivity and microbiological control.
Residential captures the greatest unit volume. Industrial represents the fastest-growing trajectory as semiconductor fabs and data centers seek low-conductivity feedwater alternatives.
Component:
Supply concentration differs between commoditized storage and specialized disinfection equipment requiring certification validation.
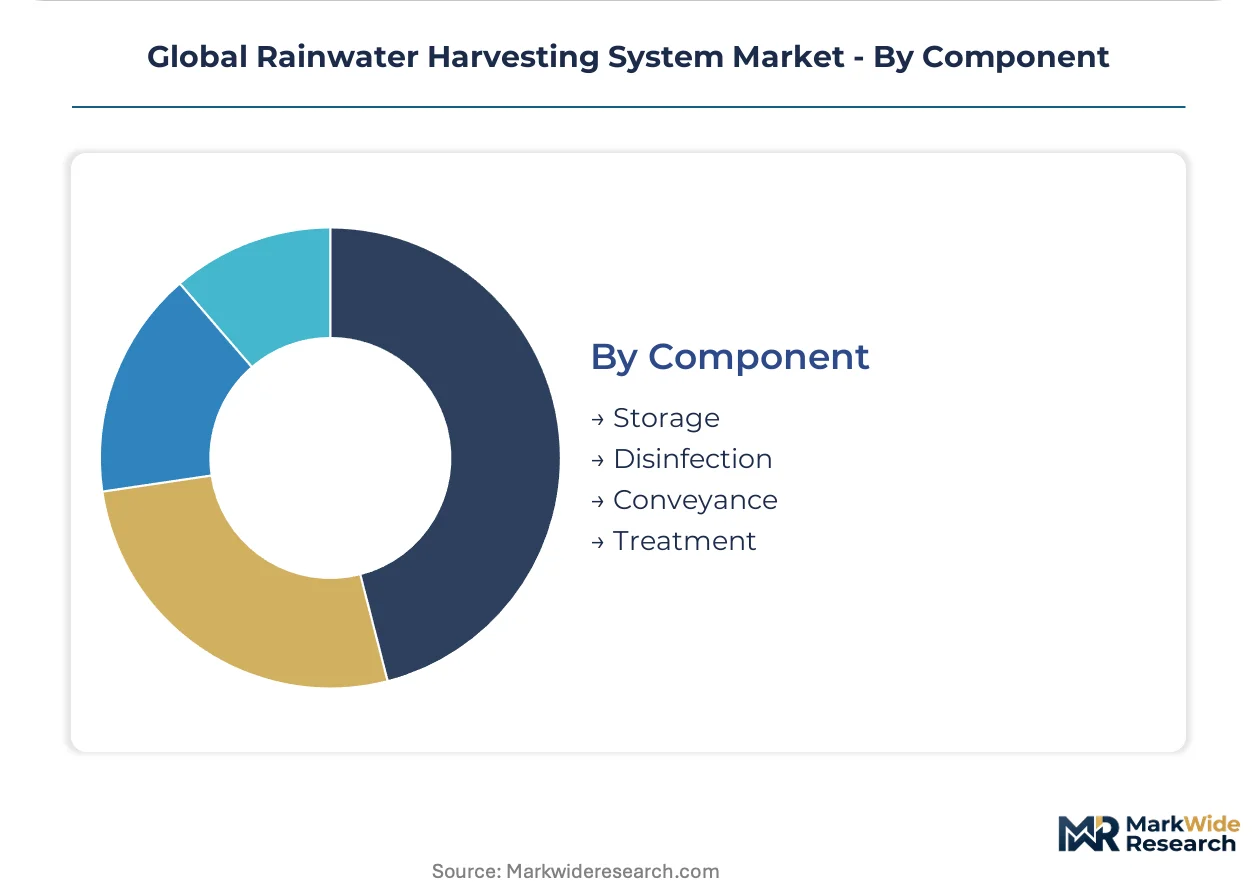
- Storage:Cisterns, tanks, and modular retention vessels representing the capital-intensive foundation of system architecture. Rotational molders like Graf Group anchor European polyethylene supply while Kingspan bundles storage with building envelope contracts.
- Disinfection:UV reactors, chlorine dosing systems, and ozone generators meeting AS/NZS 4020 and NSF/ANSI 61 potable contact standards. Certification timelines of 12-18 months create barriers for new entrants.
- Conveyance:Gutters, downpipes, and distribution piping connecting catchment surfaces to storage and end-use points.
- Treatment:Sediment filtration, activated carbon, and membrane separation upstream of disinfection stages.
Storage commands the largest capital share. Disinfection is gaining share fastest as regulatory stringency escalates across municipal plumbing codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia mandates rainwater capture in new construction while Germany enforces material specifications through the EU Water Framework Directive, revealing how regulatory stringency varies across jurisdictions. The United States concentrates commercial adoption in drought-prone states. China integrates distributed retention into sponge city pilots. Indonesia funds urban flood mitigation through infrastructure bonds. Each geography presents distinct procurement channels shaped by local water stress and policy frameworks.
Australia
New South Wales and Victoria drive residential volume through BASIX-mandated minimum capture volumes per dwelling. The state-level requirements create guaranteed demand channels distinct from discretionary adoption elsewhere. Sydney and Melbourne contractors specialize in gravity-fed installations for multi-unit developments.
Germany
Commercial property managers specify above-ground polyethylene tanks for sites where excavation costs prove prohibitive. Regulators under the EU Water Framework Directive are tightening food-grade resin formulations for CE marking compliance. Bavarian rotational molders anchor European supply capacity.
United States
California facility managers shift from component procurement to performance-guaranteed service contracts with penalty structures for shortfall. The EPA's Stormwater Pollution Prevention standards shape runoff quality specifications. Los Angeles and San Diego clusters concentrate commercial retrofit activity.
China
The Ministry of Ecology and Environment enforces distributed rainwater retention as gray-green infrastructure across 30 sponge city pilots. Municipal procurement channels favor modular retention systems in dense urban cores. Shenzhen and Shanghai construction codes incorporate mandatory retention volumes.
Indonesia
Jakarta's flood mitigation infrastructure bonds fund integrated rainwater harvesting in public housing developments. Gravity-fed residential systems capture margin pools where elevation differentials eliminate pumping costs. Urban densification in Java creates captive demand for low-maintenance installations.
Global Rainwater Harvesting System Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the rainwater harvesting value chain. The vendor base stratifies into three tiers: multinational building materials groups with bundled envelope solutions, regional rotational molders with captive polyethylene capacity, and filtration specialists integrating with broader plumbing infrastructure. Consolidation pressure concentrates among tank manufacturers facing resin price volatility. Dominant competitive moves include backward integration into resin supply contracts and geographic expansion through municipal specification capture.
Among European fabricators, Kingspan Group PLC and Graf Group occupy distinct positions within the storage tier. Kingspan exemplifies the diversified conglomerate archetype, leveraging insulated panel manufacturing to bundle cistern solutions with building envelope contracts. Graf Group represents the regional specialist model, anchoring European polyethylene cistern supply through rotational molding capacity. Watts Water Technologies sits within the filtration integration archetype, connecting rainwater systems to municipal plumbing infrastructure portfolios. Stormsaver Ltd and WISY AG exemplify mid-scale specialists competing on compliance expertise.
| Leading Market Players |
|---|
| Kingspan Group PLC |
| Graf Group |
| WISY AG |
| Watts Water Technologies |
| Stormsaver Ltd |
| Ecozi Ltd |
| Molloy Precast Products Ltd |
| Innovative Water Solutions LLC |
| Rainwater Harvesting Ltd |
| Others |
Value Chain & Pricing Dynamics
Rotational molding technicians in Bavaria command wage premiums that compress margins for polyethylene cistern producers serving economy-tier segments while elevating spreads between certified and uncertified product lines. Labor-cost differentials between German fabricators and Eastern European molders directly shape three-tier pricing stratification across the European market.
Pricing Analysis
Capacity additions in Poland and the Czech Republic are reshaping price floors for standard-grade polyethylene tanks. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 61-certified systems from CE-marked residential units and uncertified agricultural vessels. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because resin price volatility outpaces contract hedging. Agricultural end users exhibit highest price sensitivity, while semiconductor fabs demonstrate lowest sensitivity due to conductivity specifications.
Supply Chain Analysis
Skilled rotational molding labor availability in Germany, Poland, and the Czech Republic constrains throughput expansion for polyethylene cistern producers. Supply draws from petrochemical feedstock anchored in Rotterdam and Antwerp, with UV stabilizer and food-grade resin additive sourcing concentrated in Switzerland and the Netherlands. Single-source vulnerability in rotational molding equipment creates bottleneck risk for capacity scaling. Distribution runs through building envelope contractors in commercial segments and agricultural supply cooperatives in rural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Australia's BASIX-mandated demand premiums exceed German compliance costs, rewarding cross-border specification transfer.
For Market Incumbents: Acquire captive resin supply contracts to hedge polyethylene price volatility threatening margin pools in standard-grade tanks. Consolidate regional rotational molding capacity in Central Europe to defend against Polish and Czech cost competitors. Certification investment in AS/NZS 4020 approvals represents the critical lever for Australian market access before New South Wales construction codes tighten further. For New Entrants and Emerging Players: EU Green Deal water efficiency mandates in member states open a window for filtration-integrated system providers lacking legacy tank manufacturing overhead. Indonesia's Jakarta flood mitigation infrastructure bonds fund the most penetrable white-space for gravity-fed residential installations. Partner with municipal housing authorities as the primary go-to-market angle rather than competing for discretionary commercial procurement. For Investors and Strategic Acquirers: Building materials conglomerates with insulated panel divisions are the most active acquirer in this space, seeking rainwater harvesting capabilities to bundle with envelope contracts. Long-term viability centers on service-contract revenue streams displacing component sales in commercial verticals. Target mid-scale specialists with captive maintenance networks in Australia or California. Monitor municipal plumbing code harmonization efforts between states as the inflection signal for multi-jurisdiction scaling economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Long-term polyethylene contracts with Rotterdam petrochemical terminals stabilize margin exposure to feedstock cycles. |
| AS/NZS 4020 Certification Investment | New South Wales BASIX enforcement creates guaranteed procurement channel for potable-contact approved systems. |
| Smart Sensor Platform Integration | Cellular-connected tank level monitoring transforms hardware vendors into recurring-revenue service providers. |
| LEED Hybrid System Development | Dual-credential configurations combining rainwater reuse with solar thermal capture premium commercial specification. |
| Indonesia Municipal Partnership | Jakarta infrastructure bonds fund captive demand channels for gravity-fed public housing installations. |
Study Parameters
Bottom-up residential and commercial installation modeling reconciled against top-down rotational molding capacity tracking forms the analytical core of this study. Primary interviews with municipal water utility planners, BASIX compliance contractors, commercial facility managers, and agricultural irrigation cooperatives combined with secondary validation from EPA Stormwater Pollution Prevention filings, EU Water Framework Directive enforcement databases, Australian Bureau of Statistics construction permit records, and China MEE sponge city pilot procurement disclosures. Cross-referencing shipment data from polyethylene resin distributors against building permit volumes in mandated jurisdictions enables demand-side triangulation.
Historical trendline analysis of cistern installation rates across drought-prone regions established baseline growth trajectories. The projection framework segments by product architecture, technology configuration, end-use vertical, and component category, with geographic regulatory clusters as an additional dimension. CAGRs derive from elasticity modeling of construction code adoption timelines and municipal procurement cycle analysis. Key inputs include BASIX mandate expansion probability, EU Green Deal renovation passport rollout velocity, and China sponge city pilot scaling commitments.
Revisions become necessary when polyethylene resin price volatility exceeds hedging capacity, municipal plumbing code harmonization accelerates cross-jurisdiction certification, or groundwater substitution economics shift in Indian agricultural zones. Forecasts reflect documented assumptions about regulatory enforcement continuity and construction permit issuance patterns. Practitioners should monitor EU Water Framework Directive runoff quality standard tightening and Indonesia infrastructure bond allocation rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Dust Control Systems Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Gas Scrubber Market
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market