
 Rock Duster Market | 2026-2036
Rock Duster Market Size, Share, and Industry Trends Forecast 2026-2036
Rock Duster Market Analysis
Polyurethane is decoupling from traditional steel-housed rock duster designs as operators seek lighter, corrosion-resistant enclosures for wet mine environments. J.H. Fletcher & Co. anchors its product line through deep specialization in battery-powered and electric rock dusting equipment for underground coal applications. Clemcorp Australia dominates the Asia-Pacific supply channel with robust pneumatic systems engineered for high-humidity conditions. Stuart Group Ltd. competes through aftermarket service density across British and European quarry markets.
Rock dusters are engineered particulate-dispersion machines that apply inert limestone or dolomite dust onto coal and silica surfaces to suppress combustible and respirable dust hazards, typically operating at air pressures between 60 and 120 psi with hopper capacities ranging from 500 to 2,000 pounds. Pneumatic rock dusters occupy the largest installed base owing to proven reliability in gaseous mine atmospheres where electrical ignition risks are restricted. Electromechanical systems represent the fastest-growing technology segment as battery energy density improvements enable cord-free operation in advancing longwall faces. Mobile rock dusters command premium positioning due to autonomous tramming capabilities that reduce labor exposure in hazardous zones.
MSHA enforces 30 CFR 75.403 mandating minimum incombustible content levels in underground coal mines, directly conditioning equipment specification and maintenance cycles across US operations. Australia's state-based mine safety inspectorates, including those in Queensland and New South Wales, align with AS/NZS occupational exposure standards for respirable crystalline silica, shaping Wet Earth Pty Ltd. and Clemcorp Australia product certifications. Stakeholders must monitor evolving electrification mandates and silica exposure threshold reductions to calibrate R&D allocation between pneumatic legacy platforms and battery-electric architectures.
Market Dynamics
Electrification mandates in underground coal operations are forcing equipment manufacturers to reengineer pneumatic rock duster architectures toward battery-powered platforms, compressing development cycles and reshaping supplier qualification criteria.
Growth Catalysts
- MSHA 30 CFR 75.403 enforcement:Underground coal operators in the United States must maintain minimum incombustible content levels, mandating consistent rock dust application and sustaining equipment replacement demand.
- Battery energy density improvements:Lithium-ion cell advances enable cord-free rock duster operation in advancing longwall faces, eliminating compressed air infrastructure constraints.
- Respirable crystalline silica regulations:Australia's state-based inspectorates in Queensland and New South Wales enforce AS/NZS occupational exposure standards, expanding wet-application rock duster deployment in metalliferous mining.
Market Restraints
- Steel and aluminum price volatility:Hopper and chassis material costs fluctuate with commodity markets, squeezing margins for fixed-price contract manufacturers.
- Pneumatic component supply concentration:High-pressure valve and regulator production clusters in Germany and Japan create single-source vulnerability for tier-two assemblers.
- Electrical certification barriers:IECEx and ATEX compliance for battery systems in gaseous atmospheres extends product validation timelines by 12-18 months.
Strategic Opportunities
- India underground coal expansion:The country's national mining safety regulator is implementing stricter dust control protocols, opening import substitution potential for certified equipment suppliers.
- Autonomous tramming integration:Collision-avoidance and self-navigation technologies from surface mining are converging with mobile rock duster platforms.
- Aftermarket service unbundling:Predictive maintenance contracts and remote diagnostics create recurring revenue streams separate from equipment sales.
Industry Challenges
- Mine electrician certification shortages:Qualified personnel for battery-electric system installation and troubleshooting remain scarce in Appalachian Basin operations.
- Legacy pneumatic fleet interoperability:Hybrid mine environments require rock dusters compatible with existing compressed air networks during multi-year transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rock Duster Market |
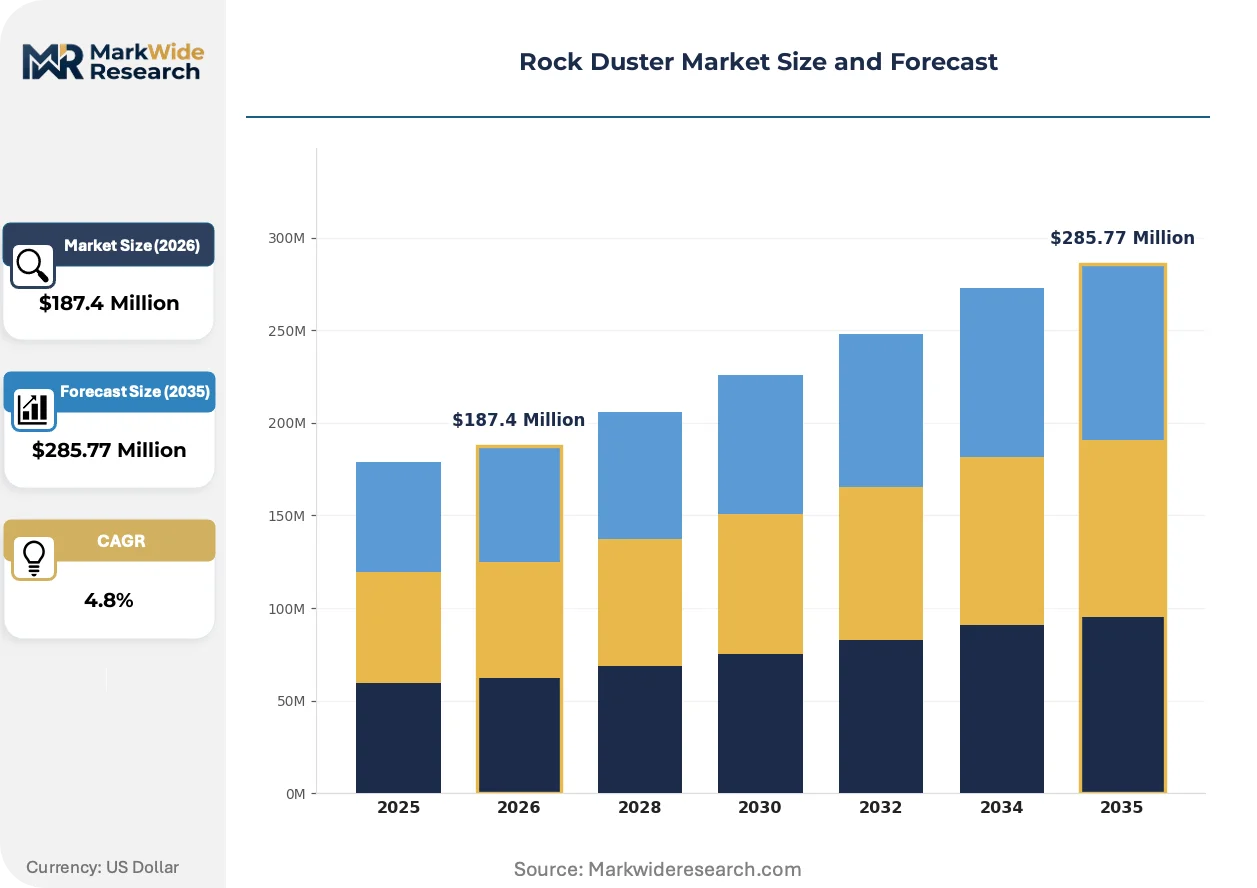
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Rock Dusters, Electric Rock Dusters, Handheld Rock Dusters, Mobile Rock Dusters End User: Mining Companies, Construction Firms, Quarry Operators, Environmental Agencies Technology: Compressed Air Technology, Electromechanical Systems, Hydraulic Systems, Manual Application Application: Coal Mining, Metal Mining, Tunneling, Road Construction |
| Companies Covered | Strata Worldwide, Irwin Car and Equipment, J.H. Fletcher & Co., Stuart Group Ltd., Clemcorp Australia, United Mining Equipment, FLSmidth, Wet Earth Pty Ltd., Saminco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rock Duster Market Emerging Trajectories
Rock duster engineering is pivoting from standalone pneumatic machines toward integrated mine safety systems that communicate dust levels, equipment status, and maintenance needs through unified digital platforms.
Closed-loop dust concentration monitoring is integrating ultrasonic and optical sensors directly into rock duster discharge nozzles, enabling real-time application rate adjustment. Longwall operators in Illinois and Pennsylvania are piloting these systems to eliminate manual sampling delays. The technology is integrating dust suppression with ventilation control, compressing the feedback loop between hazard detection and mitigation from hours to seconds.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon use in industrial equipment, pressuring manufacturers to eliminate pneumatic refrigerant-based cooling systems from high-duty-cycle rock dusters. Compressor OEMs are responding with air-cooled alternatives rated for continuous underground operation. Battery-electric architectures bypass this constraint entirely, accelerating their competitive positioning in EU member state procurement.
Buyers are consolidating maintenance spend under multi-year performance contracts that bundle equipment, consumables, and labor into cost-per-tonne metrics. Original equipment manufacturers in the United States are displacing independent service providers through captive technician networks. This shift concentrates purchasing authority at corporate mining headquarters rather than individual mine sites, favoring suppliers with national-scale service density.
Rock Duster Market Segmentation
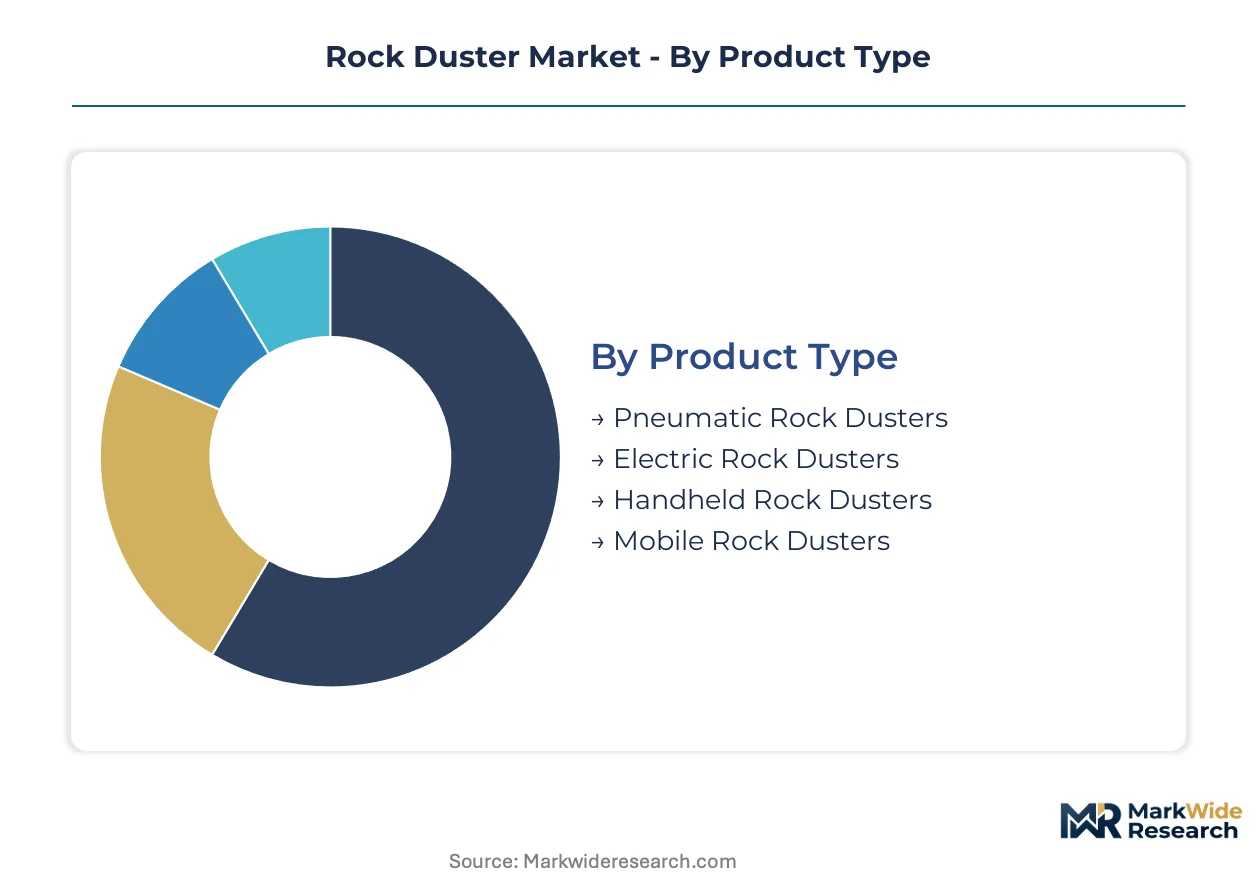
Rock duster procurement decisions hinge on mine atmosphere classification, electrical certification requirements, and labor availability. Segmentation reveals how equipment specifications diverge across gaseous versus non-gaseous operations and between established pneumatic infrastructure versus greenfield electrification projects.
Product Type:
IECEx and ATEX certifications burden battery-electric architectures with 12-18 month validation timelines, while pneumatic designs face lighter compliance loads in gaseous atmospheres.
- Pneumatic Rock Dusters:Compressed air systems operate at 60-120 psi through limestone or dolomite hoppers rated 500-2,000 pounds. Appalachian Basin coal operators favor these units for MSHA 30 CFR 75.403 compliance where electrical ignition risks restrict alternatives.
- Electric Rock Dusters:Battery-powered platforms leverage lithium-ion density improvements for cord-free operation in advancing longwall faces. IECEx certification delays constrain deployment velocity despite eliminating compressed air infrastructure.
- Handheld Rock Dusters:Portable units serve spot-application needs in tunneling and maintenance tasks where mechanized equipment cannot access.
- Mobile Rock Dusters:Autonomous tramming capabilities command premium positioning through collision-avoidance integration that reduces labor exposure in hazardous zones.
Leading the category by volume: Pneumatic Rock Dusters. Growing fastest: Electric Rock Dusters.
End User:
Procurement authority concentrates at corporate headquarters for mining multinationals while environmental agencies operate under public-sector bidding rules.
- Mining Companies:Underground coal and metalliferous operators drive replacement demand through MSHA and state-based inspectorate enforcement. Wet Earth Pty Ltd. and Clemcorp Australia anchor supply relationships with tier-one producers.
- Construction Firms:Tunneling contractors in urban infrastructure projects deploy rock dusters for silica suppression during excavation.
- Quarry Operators:Surface limestone and aggregate producers apply dusters for combustible material control in crushing and conveying operations.
- Environmental Agencies:Regulatory bodies and remediation contractors utilize equipment for abandoned mine reclamation and dust mitigation on public lands.
Highest equipment specification intensity: Mining Companies. Fastest contract velocity: Construction Firms.
Technology:
Supply concentration for high-pressure valves and regulators in Germany and Japan creates single-source vulnerability that shapes technology selection.
- Compressed Air Technology:Proven reliability in methane-rich atmospheres sustains the largest installed base. Wet Earth Pty Ltd. leverages this architecture for Australian metalliferous mines.
- Electromechanical Systems:Battery energy density advances enable fastest expansion as cord-free operation eliminates compressed air infrastructure constraints in advancing longwall faces.
- Hydraulic Systems:Fluid-power alternatives serve niche applications requiring high torque in wet mine conditions where pneumatic efficiency degrades.
- Manual Application:Labor-intensive methods persist in small-scale quarrying and developing-market operations with limited capital availability.
Dominant installed base: Compressed Air Technology. Steepest expansion trajectory: Electromechanical Systems.
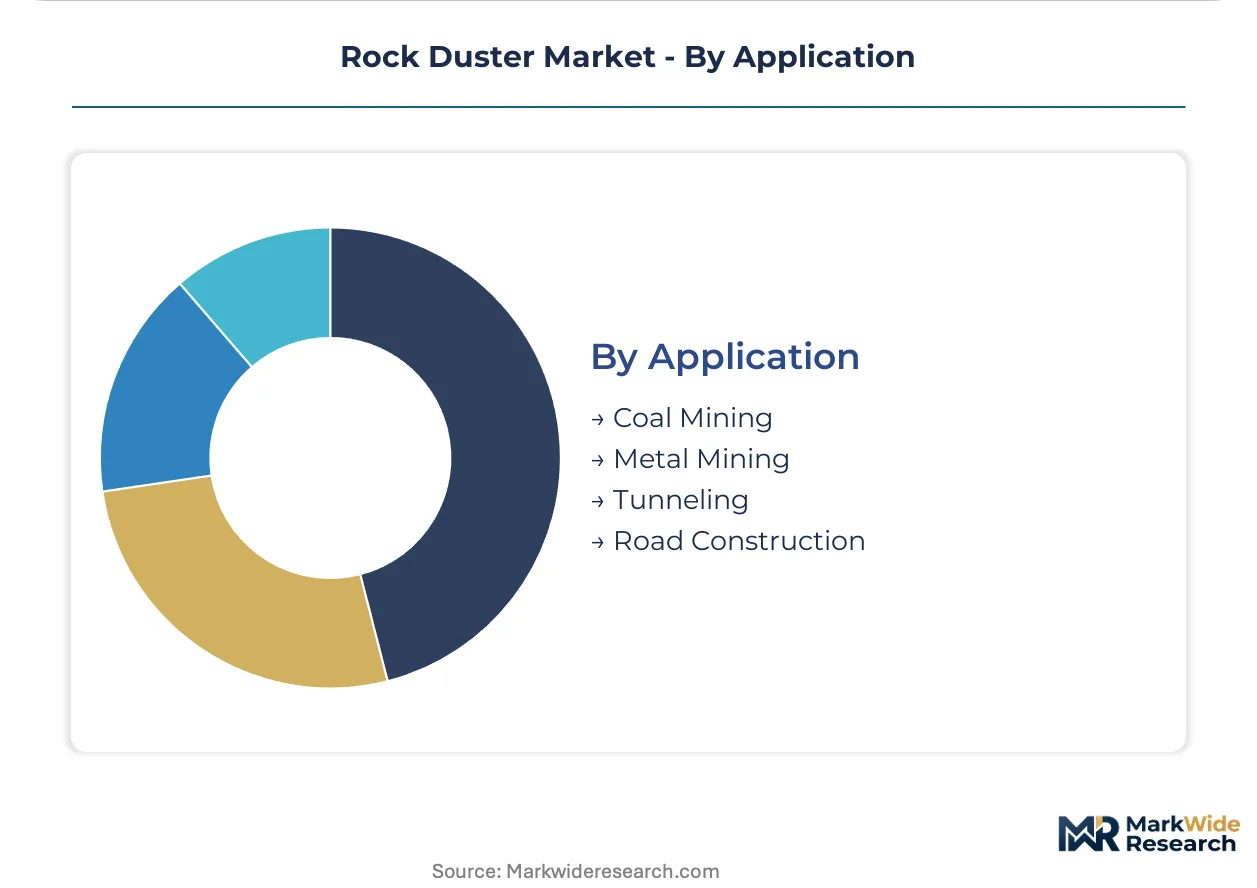
Application:
Regulatory stringency varies sharply across coal versus metal mining, with MSHA 30 CFR 75.403 mandating incombustible content only in underground coal.
- Coal Mining:Respirable dust and combustible hazard suppression drive consistent equipment replacement. Illinois and Pennsylvania longwall operators pilot closed-loop dust concentration monitoring.
- Metal Mining:Queensland and New South Wales inspectorates enforce AS/NZS silica standards, expanding wet-application deployment in Australian metalliferous operations.
- Tunneling:Urban infrastructure projects in Europe face EU F-Gas Regulation pressure to eliminate refrigerant-based cooling from high-duty-cycle equipment.
- Road Construction:Surface aggregate processing and tunnel portal work generate episodic demand with lower specification intensity than underground mining.
Strictest compliance environment: Coal Mining. Fastest regulatory expansion: Metal Mining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Underground coal operations in the Appalachian Basin concentrate replacement demand, while Australian metalliferous expansion and European tunneling projects reshape procurement patterns across three continents.
United States
Appalachian Basin coal operators in West Virginia and Kentucky drive equipment turnover through MSHA 30 CFR 75.403 enforcement mandating minimum incombustible content levels. Illinois and Pennsylvania longwall mines pilot closed-loop dust concentration monitoring with ultrasonic sensors integrated into discharge nozzles. Pittsburgh anchors supplier engineering centers serving domestic underground operations.
Australia
Queensland and New South Wales metalliferous mines expand wet-application rock duster deployment under state inspectorate enforcement of AS/NZS respirable crystalline silica standards. Wet Earth Pty Ltd. leverages compressed air technology from Brisbane to serve high-humidity underground conditions. Bowen Basin coal operations sustain pneumatic equipment demand alongside hard-rock base metal expansion.
Germany
Ruhr Valley coal regions transition legacy pneumatic fleets toward battery-electric architectures under EU F-Gas Regulation pressure to eliminate hydrofluorocarbon-based cooling systems. High-pressure valve and regulator manufacturing clusters in Stuttgart and Munich create supply concentration for tier-two assemblers. Saxony-Anhalt hosts testing facilities for IECEx-certified battery systems.
China
Shanxi and Inner Mongolia underground coal basins implement stricter national dust control protocols, opening import substitution potential for certified equipment suppliers. State-owned mining conglomerates consolidate procurement authority at corporate headquarters in Beijing. Yangtze River Delta fabrication centers produce pneumatic chassis components for domestic and export markets.
India
Jharkhand and Odisha underground coal expansion accelerates under Directorate General of Mines Safety enforcement of revised respirable dust standards. Singareni Collieries in Telangana pilot mechanized rock dusting to replace manual application in advancing longwall faces. Dhanbad hosts technical training institutes addressing mine electrician certification shortages for battery-electric system installation.
Rock Duster Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated safety system providers commanding premium positioning in North American coal operations while regional fabricators dominate aftermarket service density. The vendor base arranges into three strategic archetypes: pneumatic technology specialists, battery-electric platform developers, and diversified mining equipment conglomerates. M&A activity concentrates on autonomous tramming capabilities and predictive maintenance software assets. Geographic expansion into India's underground coal sector represents the dominant competitive move.
Among North American integrated safety system providers, Strata Worldwide exemplifies the convergence of rock dusting equipment with unified digital platforms for dust level monitoring and ventilation control. J.H. Fletcher & Co. anchors the battery-electric specialization tier through deep engineering focus on underground coal applications. Clemcorp Australia occupies a position within the Asia-Pacific pneumatic supply channel, serving high-humidity metalliferous operations from Australian manufacturing bases. These three represent distinct competitive vectors: integrated systems, electrification specialization, and regional pneumatic dominance.
| Leading Market Players |
|---|
| Strata Worldwide |
| Irwin Car and Equipment |
| J.H. Fletcher & Co. |
| Stuart Group Ltd. |
| Clemcorp Australia |
| United Mining Equipment |
| FLSmidth |
| Wet Earth Pty Ltd. |
| Saminco Inc. |
| Others |
Supply Flow & Price Mechanics
Mine electrician certification shortages in the Appalachian Basin and Jharkhand create labor-cost differentials that widen pricing spreads between pneumatic legacy systems and battery-electric platforms. Tier-one mining multinationals absorb premium pricing for IECEx-certified electromechanical units while regional quarry operators in developing markets gravitate toward standardized pneumatic equipment with lighter compliance burdens.
Pricing Analysis
Volume concentrates in pneumatic rock dusters serving MSHA-compliant coal operations while margins accrue to battery-electric architectures with autonomous tramming capabilities. Three-tier pricing structure separates IECEx-certified premium platforms from standard pneumatic units and economy-grade handheld applicators. Pricing pressure stems from steel and aluminum commodity volatility squeezing fixed-price contract manufacturers. Construction firms exhibit highest price sensitivity due to episodic project demand, whereas underground coal operators prioritize certification compliance over unit economics.
Supply Chain Analysis
IECEx and ATEX certification requirements gate battery-electric component sourcing, extending validation timelines and concentrating qualified supplier relationships. High-pressure valve and regulator production clusters in Germany and Japan, with pneumatic chassis fabrication centers in China's Yangtze River Delta. Supply chains draw from lithium-ion cell suppliers in South Korea and Japan, limestone hopper steel from domestic mills, and pneumatic compressors from European OEMs. Single-source vulnerability in German-Japanese valve manufacturing creates procurement risk for tier-two assemblers. Distribution runs through OEM captive technician networks and mining equipment distributors with aftermarket service density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rock duster market is becoming a vertical-integration race as manufacturers pursue captive control over high-pressure pneumatic component supply and predictive maintenance software stacks to defend margin erosion from commodity volatility.
For Market Incumbents: Lock in aftermarket service density through multi-year performance contracts bundling equipment, consumables, and labor into cost-per-tonne metrics. Secure backward integration into high-pressure valve manufacturing to offset German-Japanese supply concentration vulnerability. Battery-electric platform developers threaten pneumatic specialists with faster replacement cycles in advancing longwall faces. For New Entrants and Emerging Players: Capture import substitution opportunity in India's Jharkhand and Odisha underground coal expansion where Directorate General of Mines Safety enforcement is accelerating mechanized dust control adoption. Target construction firm segments with rental-based pricing models for tunneling projects in European urban infrastructure. Partner with regional fabrication centers in Dhanbad or Telangana to bypass incumbent distribution networks. For Investors and Strategic Acquirers: Re-rating potential sits with electromechanical platform specialists given battery energy density improvements and EU F-Gas Regulation pressure eliminating refrigerant-based pneumatic cooling systems. Long-term viability favors manufacturers with IECEx certification capabilities and autonomous tramming software assets. Watch for inflection in Indian coal sector procurement consolidation toward corporate headquarters in Beijing-style centralized purchasing authority.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pneumatic Components | Captive valve manufacturing reduces German-Japanese supply concentration vulnerability for tier-one assemblers. |
| Battery-Electric Platform Certification | IECEx compliance enables penetration of methane-rich gaseous atmospheres previously restricted to pneumatic systems. |
| Autonomous Tramming Technology Acquisition | Collision-avoidance integration commands premium positioning through reduced labor exposure in hazardous zones. |
| Multi-Year Performance Contract Expansion | Cost-per-tonne bundling concentrates purchasing authority at corporate headquarters and displaces independent service providers. |
| Predictive Maintenance Software Development | Remote diagnostics and aftermarket service unbundling create recurring revenue streams separate from equipment sales cycles. |
Methodological Framework
MSHA enforcement records, Australian state inspectorate filings, and SEC 10-K disclosures from mining equipment manufacturers formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with maintenance directors at Appalachian Basin coal operations, procurement leads at Queensland metalliferous mines, and aftermarket service heads at European quarry operators validated equipment replacement cycles and pricing dynamics. Bottom-up triangulation across pneumatic and electromechanical unit shipments combined with top-down validation against mining sector capital expenditure disclosures.
Historical trendline analysis of MSHA compliance-driven replacement demand and battery energy density improvement curves anchored the projection framework. Segmentation modeling spanned product type, technology architecture, end-user industry, and regional regulatory cluster across the analysis window. CAGRs derived from equipment shipment trajectories weighted by mine atmosphere classification and electrical certification requirements. Forecast inputs incorporated lithium-ion cell cost decline assumptions and evolving respirable crystalline silica exposure thresholds.
The model holds under sustained MSHA 30 CFR 75.403 enforcement and stable commodity pricing for steel and aluminum inputs; deviation in electrification mandate acceleration or pneumatic component supply disruption would shift equipment mix assumptions. Forecasts reflect documented regulatory compliance drivers and technology substitution elasticities. A model refresh is warranted upon material change in India's Directorate General of Mines Safety enforcement posture or EU F-Gas Regulation phase-down timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Smart Mining Market
Mining Equipment
Logging Cable Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Underground Mining Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Surface Mining Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Mining Remanufacturing Components Market