
 Cosmetic Surgery Market | 2026-2036
Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Surgery Market Intelligence
The substitution of traditional collagen with advanced hyaluronic acid-based dermal fillers is consolidating the non-surgical aesthetic treatment landscape. This shift favors firms with strong R&D in biocompatible materials. AbbVie Inc. leverages its dominant brand portfolio in neurotoxins and fillers to command premium pricing. Galderma competes through a broad range of aesthetic solutions, while Merz Pharma specializes in a differentiated portfolio of injectables and energy-based devices.
Cosmetic surgery encompasses elective medical procedures designed to reshape or enhance bodily structures for aesthetic improvement. These interventions are categorized as either invasive surgical procedures, such as rhinoplasty, or minimally invasive non-surgical treatments. While surgical procedures like abdominoplasty remain a significant revenue source, non-surgical options including injectable fillers represent the fastest-growing category. Demand is increasingly serviced by specialized end-user settings like private clinics and medical spas, which offer greater patient discretion and convenience.
Market access and product safety are governed by stringent regulatory frameworks. In the United States, the FDA approves medical devices and injectable substances, while CE marking is mandatory for products sold in Europe, and Brazil's ANVISA enforces its own specific requirements. These regulations dictate material composition, clinical trial evidence, and marketing claims for all aesthetic products. Navigating the evolving standards for novel energy-based devices and biocompatible materials remains a critical task for all manufacturers.
Market Dynamics
The fundamental market dynamic is the consumer-driven shift from invasive surgical interventions to minimally invasive, non-surgical treatments. This pivot, enabled by technological advances in injectables and energy-based devices, expands the addressable market to new demographic and economic segments.
Growth Catalysts
- Advanced Technologies:The development of next-generation cryolipolysis and radiofrequency systems expands the range of non-invasive body contouring and skin tightening procedures, attracting a broader consumer base seeking results with minimal downtime.
- Cultural Normalization:In key markets like Brazil and South Korea, strong cultural acceptance and media portrayal of aesthetic procedures create sustained, concentrated demand, supporting a sophisticated clinical infrastructure and high procedural volumes.
- Medical Spa Expansion:The proliferation of medical spas as an end-user setting increases geographic accessibility and offers a more discreet, convenient service model than traditional hospital environments, particularly for injectable treatments.
Market Restraints
- Regulatory Fragmentation:Divergent and stringent approval processes, such as FDA requirements in the United States, CE marking in Europe, and ANVISA standards in Brazil, create significant compliance costs and time-to-market delays for manufacturers.
- High Device Costs:The substantial capital investment required for sophisticated energy-based devices, such as advanced lasers and radiofrequency machines, limits their adoption by smaller, independent clinics and practitioners, constraining market access.
- Treatment Permanence:The temporary effect of popular non-surgical treatments like neurotoxins and most dermal fillers necessitates repeat procedures, which can pose a long-term cost and commitment barrier for a segment of consumers.
Strategic Opportunities
- Geographic Expansion:Untapped demand in markets across Southeast Asia and the Middle East, where rising disposable incomes and social media influence are fostering new interest in aesthetic enhancements, presents a significant growth frontier.
- AI-Powered Personalization:Integrating artificial intelligence tools for facial analysis and treatment simulation offers a path to highly personalized aesthetic plans, improving patient satisfaction and differentiating premium clinical providers.
- Teledermatology Integration:The development of teledermatology platforms for initial aesthetic consultations can streamline the patient journey, improve clinic efficiency, and broaden a provider's reach beyond its immediate geographic location.
Industry Challenges
- Practitioner Skill Gaps:A shortage of highly trained and certified practitioners to operate complex energy-based devices and administer injectables with precision creates a bottleneck that constrains service capacity and geographic expansion.
- Marketing Compliance:Adhering to evolving regulations on advertising and marketing claims, such as those enforced by the FTC in the U.S., presents a constant challenge for clinics and manufacturers promoting treatment outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Surgery Market |
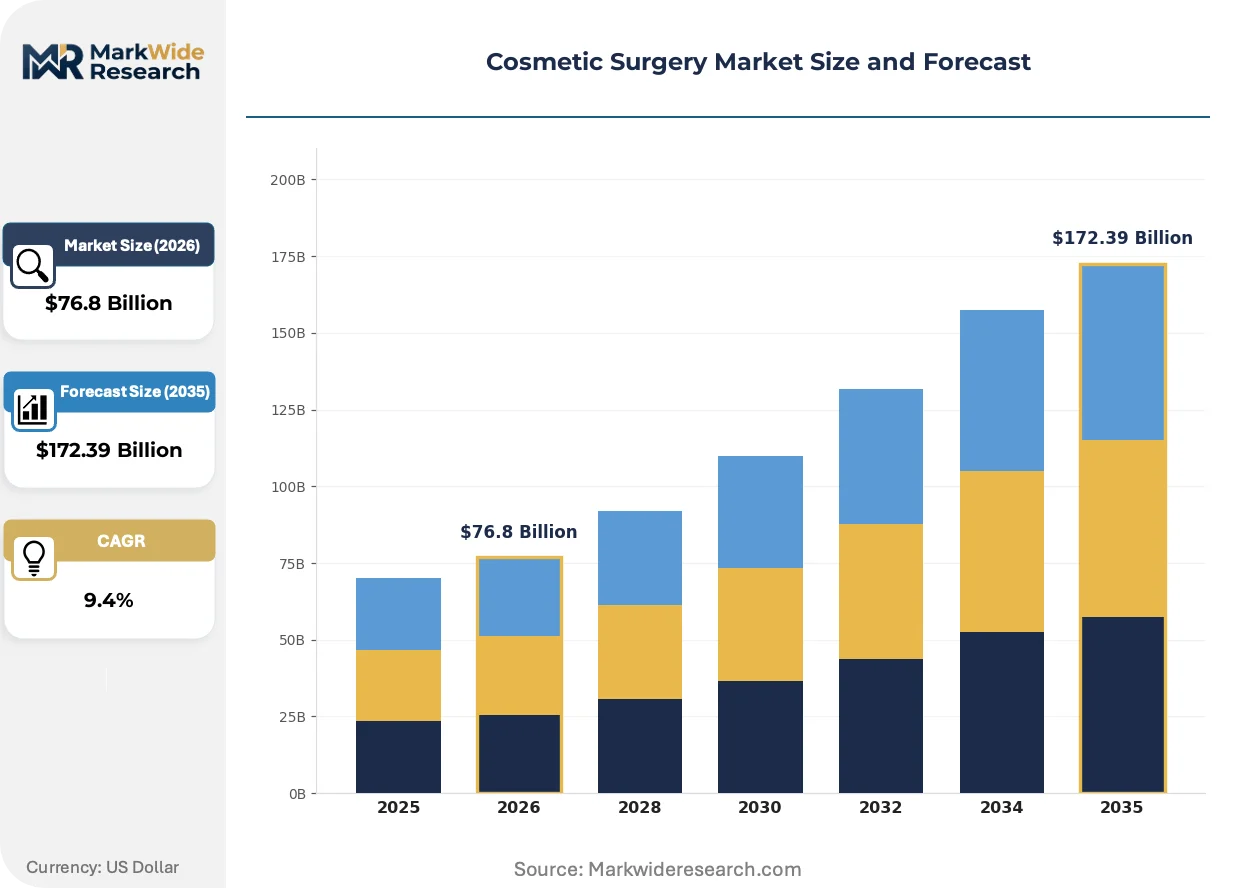
| Market Size in 2026 | $76.8 Billion |
| Market Size in 2035 | $172.39 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Facelift, Rhinoplasty, Liposuction, Blepharoplasty, Abdominoplasty, Others Technology: Laser Surgery, Ultrasound-Assisted, Radiofrequency, Cryolipolysis, Injectable Fillers, Thread Lift End User: Private Clinics, Specialty Centers, Dermatology Clinics, Plastic Surgery Hospitals, Medical Spas Distribution Channel: Direct Sales, Online Medical Platforms, Medical Tourism Facilitators, Referral Networks, Third-Party Providers |
| Companies Covered | AbbVie Inc., Bausch Health Companies Inc., Galderma, Cynosure, Johnson & Johnson Services, Inc. (MENTOR), Merz Pharma, Cutera Inc., Lumenis, Sientra Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Surgery Market Strategic Shifts & Innovations
Personalization and accessibility are the defining themes in product innovation and service delivery. The convergence of material science in injectables and digital tools for patient engagement is creating a more customized and approachable aesthetic medicine experience for a wider audience.
Hyaluronic acid-based dermal fillers provide biocompatible solutions for volume restoration and facial contouring. Aesthetic clinics and medical spas are rapidly adopting these products for their predictable results and superior safety profiles compared to older materials. This class of advanced, cross-linked injectables is overtaking traditional collagen and less-sophisticated fillers within the non-surgical treatment landscape.
The European Union's Medical Device Regulation (MDR) elevates the classification and scrutiny of many aesthetic products, including dermal fillers and some energy-based equipment. This forces manufacturers to provide more extensive clinical evidence and enhance post-market surveillance to maintain CE marking. The injectable filler and body contouring device segments are most affected, facing increased R&D and compliance expenditures.
Consumer behavior is shifting toward digital-first research and provider discovery, heavily influenced by social media platforms. This trend disrupts traditional patient referral networks and compels clinics to invest in online reputation management and visual-centric content marketing. This dynamic is most pronounced in markets with high social media usage, including the United States and South Korea.
Cosmetic Surgery Market Segmentation
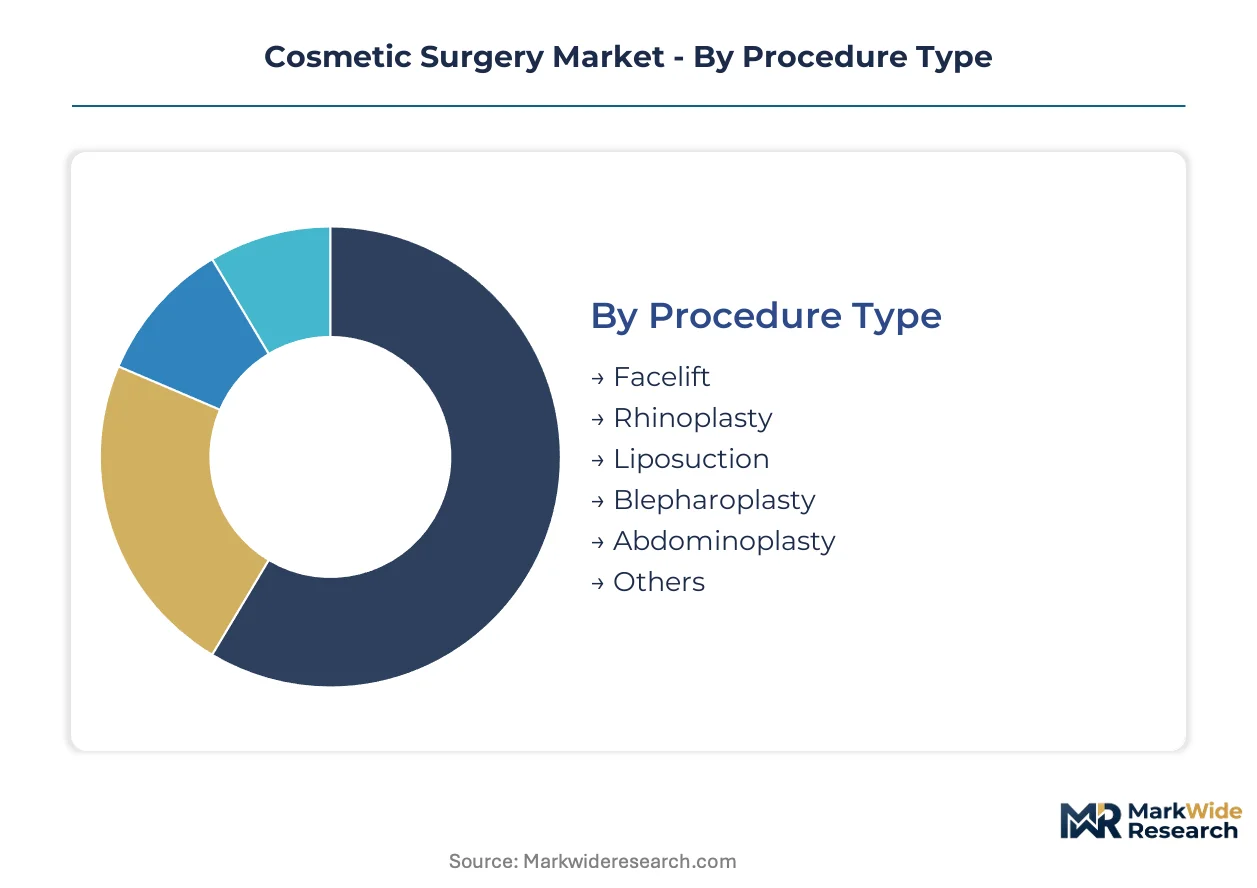
The Cosmetic Surgery Market segments delineate varying levels of procedural complexity, technological integration, and patient access points. Understanding these divisions is crucial for manufacturers and service providers to target investments and refine product development strategies effectively. Each category reveals distinct demand patterns and operational requirements for market participants.
Procedure Type:
The capital intensity of cosmetic procedures varies significantly across types, influencing clinic investment and practitioner specialization.
- Abdominoplasty:This invasive surgical procedure involves the removal of excess skin and fat from the abdomen, often combined with muscle tightening. Demand remains concentrated in established markets like Brazil, driven by post-pregnancy or significant weight loss body contouring needs.
- Rhinoplasty:A complex surgical intervention reshaping the nose for aesthetic or functional improvement, requiring specialized surgical skills and equipment. Patient demand is high across diverse demographics, with significant interest in East Asian markets for specific aesthetic outcomes.
- Facelift:This surgical procedure tightens facial skin and underlying tissues to reduce visible signs of aging.
- Liposuction:A surgical technique that removes localized fat deposits from various body areas using suction.
- Blepharoplasty:A surgical procedure that corrects droopy eyelids by removing excess skin, muscle, and fat.
- Others:This category encompasses a range of less common or highly specialized surgical procedures, including breast augmentation, breast reduction, and otoplasty.
Most installed capacity flows through Liposuction. Expansion is steepest in Abdominoplasty.
Technology:
The application focus within cosmetic technology is shifting towards less invasive methods offering quicker recovery times for consumers.
- Injectable Fillers:These non-surgical treatments involve the injection of substances like hyaluronic acid to restore volume, smooth wrinkles, and enhance facial contours. Demand is expanding rapidly across all age groups, driven by the desire for subtle aesthetic improvements with minimal downtime.
- Radiofrequency:This technology uses controlled heat to stimulate collagen production and tighten skin, offering non-invasive solutions for facial rejuvenation and body contouring. Adoption is growing in medical spas due to its versatility and efficacy in treating various skin concerns.
- Laser Surgery:Utilizes concentrated light beams for skin resurfacing, hair removal, and tattoo removal, requiring precise calibration.
- Ultrasound-Assisted:Employs high-intensity focused ultrasound (HIFU) for non-invasive skin lifting and tightening.
- Cryolipolysis:A non-invasive method that uses controlled cooling to freeze and eliminate fat cells in targeted areas.
- Thread Lift:A minimally invasive procedure using dissolvable sutures to lift and tighten sagging skin.
Demand for Injectable Fillers is outpacing Laser Surgery due to consumer preference for non-surgical options.
End User:
The customer type accessing cosmetic procedures varies by setting, from discreet outpatient clinics to comprehensive hospital environments.
- Medical Spas:These facilities offer a blend of aesthetic treatments in a spa-like setting, focusing on non-invasive procedures and patient comfort. They attract a broader demographic seeking accessible and convenient aesthetic services.
- Private Clinics:Specialized outpatient facilities providing a wide range of surgical and non-surgical cosmetic treatments with a focus on personalized patient care. These clinics typically cater to a discerning clientele seeking expert care and discretion.
- Specialty Centers:Dedicated facilities offering focused cosmetic services, often specializing in particular procedures or body areas.
- Dermatology Clinics:Provide skin-focused aesthetic treatments, including injectables, laser therapies, and chemical peels, often integrating medical dermatology.
- Plastic Surgery Hospitals:Comprehensive medical institutions offering complex surgical procedures, often associated with reconstructive surgery and inpatient care.
Market penetration for Medical Spas is deeper than Plastic Surgery Hospitals for minimally invasive treatments.
Distribution Channel:
The volume and reach of cosmetic services are significantly influenced by how patients discover and access providers.
- Referral Networks:Established channels where patients are referred by existing clients, general practitioners, or other specialists, relying on trust and professional recommendations. This channel remains critical for high-value surgical procedures.
- Online Medical Platforms:Digital platforms that connect patients with aesthetic practitioners, offering appointment booking, virtual consultations, and provider reviews. This channel is gaining traction in markets with high digital literacy, facilitating broader patient discovery.
- Direct Sales:Clinics and practitioners directly engaging with potential patients through their own marketing efforts and in-house consultations.
- Medical Tourism Facilitators:Agencies that arrange cosmetic procedures for patients traveling internationally, handling logistics and provider selection.
- Third-Party Providers:External entities, such as aggregators or marketplaces, that list and promote cosmetic services from various clinics.
Patient engagement via Online Medical Platforms is higher than through Medical Tourism Facilitators for initial consultations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States cosmetic surgery market, characterized by advanced technological adoption and a high disposable income, drives significant innovation in non-surgical treatments. Cultural acceptance in Brazil and South Korea cultivates sophisticated clinical infrastructures and concentrated demand for both invasive and non-invasive procedures.
United States
Strong consumer demand for aesthetic enhancements and a preference for minimally invasive procedures fuel market expansion. The FDA's stringent approval processes ensure product safety and efficacy, influencing global standards for new devices and injectables. Major clinical research and development hubs in California and Massachusetts attract significant investment in advanced aesthetic technologies.
Brazil
Cultural acceptance of cosmetic procedures and a well-developed clinical infrastructure sustain high procedural volumes. ANVISA's regulatory framework dictates material composition and clinical trial evidence for all aesthetic products sold in the country. São Paulo and Rio de Janeiro represent key centers for advanced surgical techniques and medical tourism.
South Korea
High social media influence and a strong emphasis on aesthetic appearance generate concentrated demand for both surgical and non-surgical treatments. The MFDS enforces strict guidelines for medical devices and pharmaceuticals, promoting high safety standards. Seoul's Gangnam district is a global hub for plastic surgery and aesthetic innovation, attracting international patients.
Germany
A sophisticated healthcare system and an aging population seeking rejuvenation treatments contribute to steady demand for cosmetic interventions. CE marking is mandatory for aesthetic products sold in Europe, ensuring compliance with rigorous safety and performance requirements. Cities like Munich and Berlin host advanced dermatology clinics and research institutions focused on aesthetic medicine.
China
Rising disposable incomes and increasing beauty consciousness among younger demographics are expanding the addressable market for cosmetic surgery. The NMPA regulates medical devices and injectable substances, ensuring market access controls and product quality. Major urban centers like Shanghai and Beijing are witnessing rapid growth in medical spas and private aesthetic clinics.
Cosmetic Surgery Market Key Industry Players
Global majors compete with regional champions across product innovation and market access strategies within the cosmetic surgery sector. The market exhibits a tiered structure, with large pharmaceutical companies dominating the injectable segment and specialized device manufacturers focusing on energy-based solutions. Strategic partnerships and portfolio diversification are common competitive moves.
Within the neurotoxin and dermal filler segments, AbbVie Inc. and Galderma exemplify companies leveraging extensive brand portfolios and global distribution networks. Merz Pharma occupies a position as a specialist, offering a differentiated portfolio of injectables and energy-based devices. These companies anchor the premium end of the market by investing in R&D for biocompatible materials and advanced formulations.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bausch Health Companies Inc. |
| Galderma |
| Cynosure |
| Johnson & Johnson Services, Inc. (MENTOR) |
| Merz Pharma |
| Cutera Inc. |
| Lumenis |
| Sientra Inc. |
| Others |
Cost & Logistics Intelligence
Hyaluronic acid-based dermal fillers, a key technology shift, simultaneously reshape cost economics through material science innovation and concentrate supply among specialized manufacturers. This transition influences pricing power across the non-surgical aesthetic landscape.
Pricing Analysis
Input-cost pass-through remains a critical pricing factor for injectables, particularly for advanced biocompatible materials. The dominant pricing model is per-unit transactional, allowing for differentiation based on brand premium and FDA/CE certification levels. Pricing softness reflects intense competition among generic filler manufacturers. Medical spas exhibit high price sensitivity, while discerning private clinic clientele prioritize proven efficacy over cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of active pharmaceutical ingredients for neurotoxins and advanced fillers. Geographic supply concentration centers on specific facilities in Europe and the United States. Raw material dependencies include highly purified hyaluronic acid and botulinum toxin strains. Regulatory restrictions on cross-border movement of controlled substances pose a structural supply chain risk. Distribution runs through established pharmaceutical distributors and direct sales forces to clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic surgery market presents a significant margin-expansion story, driven by the increasing consumer preference for premium, non-invasive treatments and advanced biocompatible materials.
For Market Incumbents: Anchor brand loyalty through continuous R&D in next-generation injectables and energy-based devices, counteracting the threat from emerging generic alternatives. Consolidate market share by acquiring smaller, innovative technology firms specializing in AI-powered personalization tools. Leverage existing global distribution networks to expand into high-growth Southeast Asian markets. Invest in practitioner training academies to mitigate skill gaps and ensure consistent treatment outcomes.
For New Entrants and Emerging Players: Capture white-space opportunities by focusing on teledermatology integration for initial consultations, lowering patient access barriers. Target underserved geographic areas with high disposable incomes but limited specialized medical spa presence. Develop niche product offerings, such as customizable bio-stimulatory fillers, to differentiate from established portfolios. A go-to-market strategy emphasizing digital-first engagement and social media influence offers a cost-effective entry point.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized device manufacturers facing high capital investment requirements and regulatory hurdles. The market’s long-term viability is underpinned by sustained consumer demand for aesthetic enhancements across diverse demographics. Identify acquisition targets with strong intellectual property in energy-based devices or robust clinical trial data for novel injectable formulations. The signal to watch is the adoption rate of AI-powered diagnostic tools within private clinics, indicating future growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Secures FDA and CE marking for novel biocompatible materials, ensuring market access and premium positioning. |
| Geographic Expansion | Penetrates high-growth markets in Southeast Asia, leveraging rising disposable incomes and social media influence. |
| AI-Powered Personalization Integration | Differentiates premium clinical providers by offering highly customized aesthetic plans and improving patient satisfaction. |
| Practitioner Training Programs | Addresses skill gaps in complex device operation, ensuring safe and effective treatment delivery across clinics. |
| Direct-to-Consumer Marketing Shift | Captures digital-first patient discovery trends, bypassing traditional referral networks and broadening reach. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary data involved discussions with plastic surgeons, dermatologists, medical spa owners, and regulatory affairs specialists. Secondary research drew from FDA filings, CE marking documentation, ANVISA reports, and academic journals on aesthetic medicine. This approach ensured bottom-up market sizing and top-down validation.
Historical reference periods anchored the analytical framework, projecting trends across the analysis window through a proprietary quantitative model. The model segmented the market by procedure type (surgical/non-surgical), technology (injectables, energy-based devices), end-user setting (medical spas, private clinics), and regional regulatory clusters. Compound Annual Growth Rates reflected historical performance, future technological advancements, and evolving consumer preferences. Key forecast inputs included disposable income growth and social media engagement rates.
Regulatory shifts, material science breakthroughs, and evolving consumer perceptions are the dominant revision risks for market projections. Forecasts reflect assumptions documented from primary and secondary research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Germany Cosmetic Surgery Market