
 Liposuction Market | 2026-2036
Liposuction Market Size, Share, and Industry Trends Forecast 2026-2036
Liposuction Market Outlook
Project finance and equipment leasing programs is rewriting access dynamics for smaller clinic chains and independent dermatology practices seeking laser liposuction platforms. InMode Ltd. leverages its radiofrequency portfolio to sustain premium positioning across ambulatory surgical centers. Alma Lasers Ltd. anchors its competitive stance through broad geographic distribution, while Lumenis Ltd. differentiates via deep specialization in energy-based tissue interaction. Cutera, Inc. competes by controlling direct sales channels in North American metropolitan markets.
Liposuction denotes the surgical removal of adipose tissue through cannula-based aspiration, typically performed under tumescent anesthesia with infiltrate volumes ranging from subcutaneous infiltration ratios of 1:1 to 3:1 relative to aspirate. The procedure serves primary commercial purpose in body contouring and localized fat reduction where diet-resistant deposits persist. Laser-assisted liposuction now leads technology-based revenue pools due to simultaneous skin tightening claims and reduced recovery protocols. Tumescent liposuction occupies mature, high-volume positioning in hospital outpatient departments where reimbursement familiarity sustains utilization. Medical spas represent the fastest-growing end-user channel as capital-light service models attract physician extenders and non-core practitioners.
FDA 510(k) clearance requirements govern device commercialization timelines and predicate device strategies for radiofrequency and ultrasound platforms entering the United States market. The European Medical Device Regulation imposes strengthened clinical evidence standards that extend conformity assessment intervals for cryolipolysis and vacuum-assisted systems. State-level medical board scope-of-practice determinations in California, Texas, and Florida shape whether nurse practitioners and physician assistants may independently operate energy-based lipolysis equipment. Stakeholders must monitor evolving FDA guidance on fat-grafting adjunct claims and emerging state legislation on office-based surgery accreditation standards.
Market Dynamics
Energy-based device platforms are compressing procedure recovery timelines and expanding the addressable patient base beyond traditional surgical candidates, fundamentally restructuring competitive advantage toward technology ownership rather than surgeon reputation alone.
Growth Catalysts
- Medical spa channel expansion:Capital-light service models enable rapid geographic coverage without hospital affiliation requirements, drawing physician extenders into outpatient body contouring services.
- FDA 510(k) pathway efficiency:Predicate device strategies for radiofrequency and ultrasound platforms accelerate commercialization timelines compared to de novo review processes, compressing competitive entry cycles.
- Younger demographic engagement:Non-invasive body contouring preference among patients aged 25-40 drives procedural volume outside traditional aesthetic surgery segments.
Market Restraints
- European MDR compliance burden:Strengthened clinical evidence standards for cryolipolysis and vacuum-assisted systems extend conformity assessment intervals, delaying revenue recognition for manufacturers.
- Capital equipment intensity:Laser liposuction platforms require substantial upfront investment, constraining independent dermatology practice participation relative to hospital outpatient departments.
- Substitution from non-invasive alternatives:Cryolipolysis and injectable adipolytic therapies capture patients seeking fat reduction without operative intervention, compressing addressable surgical volume.
Strategic Opportunities
- Project finance and equipment leasing:Structured access programs for smaller clinic chains unlock laser platform adoption without balance-sheet strain, expanding manufacturer addressable market.
- State-level scope-of-practice expansion:California, Texas, and Florida medical board determinations permitting nurse practitioner and physician assistant independent operation of energy-based lipolysis equipment broaden provider pool.
- Fat-grafting adjunct claims:Evolving FDA guidance on autologous fat transfer applications creates pathway for combined liposuction-reinjection procedure bundling in reconstructive and aesthetic segments.
Industry Challenges
- Energy-based tissue interaction expertise gap:Safe operation of radiofrequency and laser platforms requires specific training in thermal injury prevention, creating bottleneck in qualified provider supply.
- Office-based surgery accreditation complexity:Emerging state legislation on ambulatory procedure facility standards imposes compliance overhead on medical spa operators without hospital infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liposuction Market |
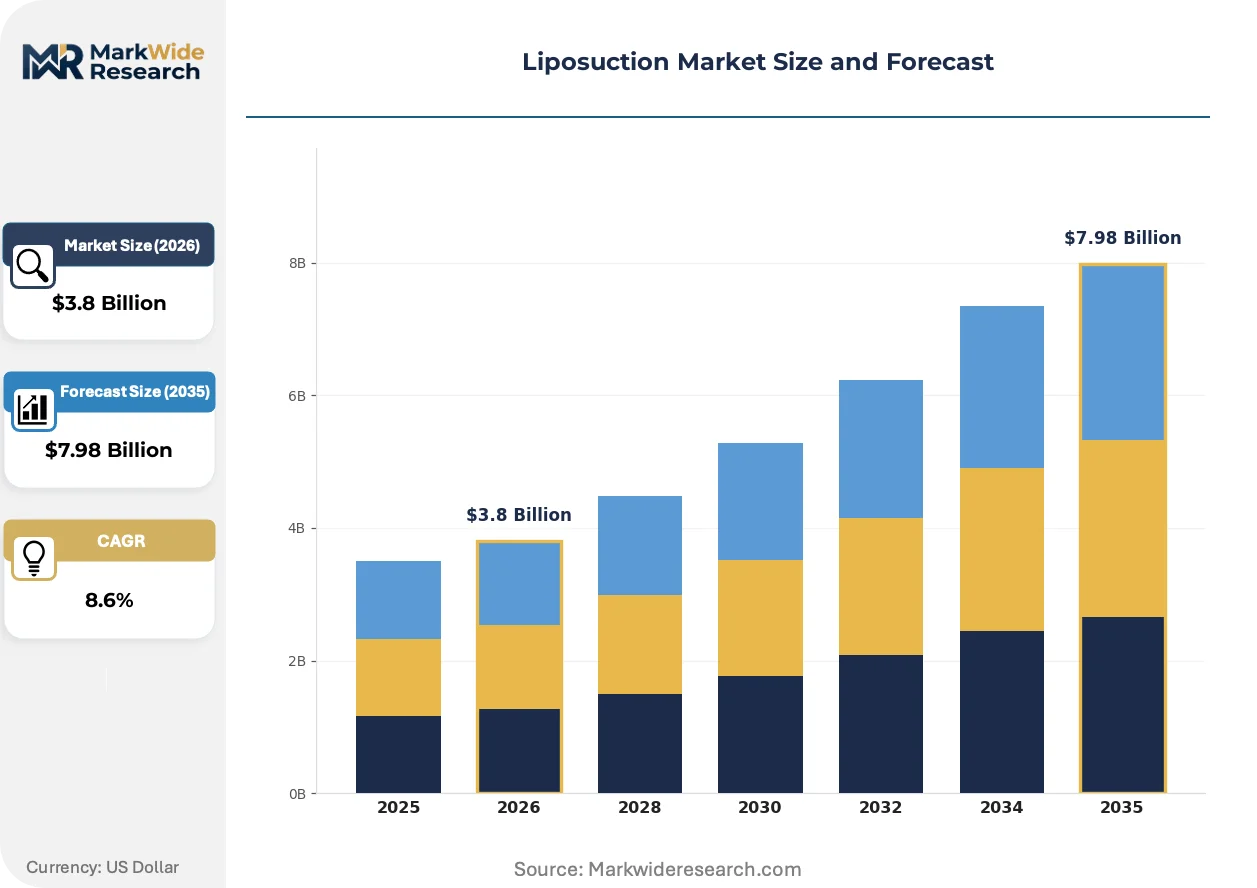
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Tumescent Liposuction, Laser-Assisted Liposuction, Power-Assisted Liposuction, Traditional Liposuction Technology: Ultrasound, Radiofrequency, Cryolipolysis, Vacuum-Assisted Technology End User: Clinics, Hospitals, Medical Spas, Dermatology Centers Body Area: Abdomen, Thighs, Arms, Neck |
| Companies Covered | Lumenis Ltd., Cutera, Inc., InMode Ltd., Candela Corporation, Sciton, Inc., Hologic, Inc., Solta Medical, Lutronic Co., Ltd., Alma Lasers Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liposuction Market Strategic Shifts
Technology convergence between aspiration-based fat removal and simultaneous skin tightening is redefining procedure economics and patient selection criteria across outpatient settings.
Radiofrequency-assisted lipolysis is migrating from premium positioning in metropolitan ambulatory surgical centers toward mid-tier dermatology practices seeking competitive differentiation. The technology delivers thermal energy through cannula-based delivery systems to achieve adipocyte disruption with concurrent dermal collagen remodeling. Adoption velocity accelerates among practices with existing laser infrastructure seeking platform expansion rather than replacement. This migration is compressing pricing premiums historically commanded by standalone skin tightening procedures.
The European Medical Device Regulation imposes post-market surveillance obligations and clinical follow-up requirements that extend technical documentation burdens for cryolipolysis system manufacturers. Device re-certification cycles now demand real-world performance data collection across broader patient populations than pre-MDR requirements. Manufacturers with established European notified body relationships and robust quality management systems capture competitive position as smaller competitors exit due to compliance cost concentration.
Patients increasingly prioritize recovery timeline and return-to-activity metrics over absolute fat volume reduction in procedure selection. Medical spa marketing emphasizes social downtime minimization rather than aspirate volume claims, displacing traditional hospital outpatient department value propositions centered on surgical comprehensiveness. This preference shift concentrates volume in settings offering discrete, limited-intervention service packaging rather than full surgical facility capabilities.
Liposuction Market Segmentation
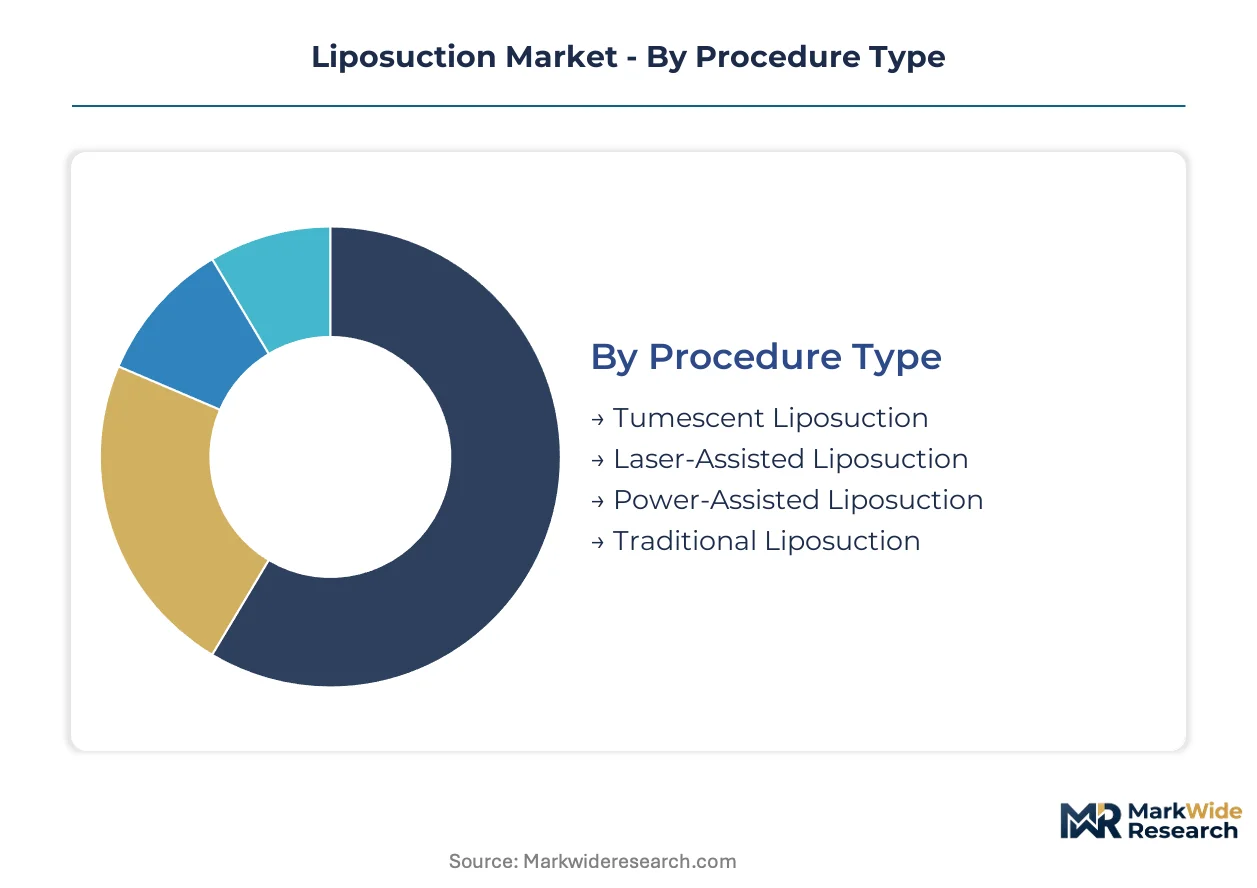
Segmentation in the liposuction market reveals how technology ownership, procedure setting, and anatomical application reshape competitive boundaries. Each dimension carries distinct capital requirements, regulatory exposure, and margin profiles that determine manufacturer go-to-market strategy.
Procedure Type:
Cost tier stratification across procedure types determines equipment investment thresholds and reimbursement positioning in outpatient settings.
- Laser-Assisted Liposuction:Thermal energy delivery through fiber-optic cannulas enables simultaneous adipose aspiration and dermal collagen contraction. Demand concentrates in ambulatory surgical centers across Texas and Florida where premium pricing supports capital recovery. FDA 510(k) predicate pathways for radiofrequency platforms accelerate competitive entry timelines for manufacturers with established energy-based portfolios.
- Tumescent Liposuction:Infiltration of dilute local anesthetic solution precedes suction-assisted fat removal through small-diameter cannulas. Hospital outpatient departments in California sustain mature utilization through reimbursement familiarity and established surgeon training pathways. Volume concentration reflects lower equipment barriers and broad payer acceptance.
- Power-Assisted Liposuction:Motorized cannula movement reduces operator fatigue during high-volume aspiration procedures.
- Traditional Liposuction:Manual suction without energy adjuncts occupies declining positioning as device-based alternatives compress addressable volume.
Tumescent Liposuction commands the established base. The steepest expansion runs through Laser-Assisted Liposuction.
Technology:
Application focus varies by energy modality, with thermal platforms targeting skin tightening adjacency and cryogenic systems pursuing non-invasive positioning.
- Radiofrequency:Electromagnetic energy generates controlled thermal injury within adipose tissue and superficial dermis for concurrent fat reduction and skin contraction. Metropolitan dermatology practices in New York and Los Angeles deploy these platforms as competitive differentiators against traditional surgical offerings. Post-procedure recovery metrics drive patient selection toward settings emphasizing return-to-activity timelines.
- Cryolipolysis:Controlled cooling induces adipocyte apoptosis without cannula insertion or anesthesia requirements. Medical spas in Miami and Dallas capture younger demographic segments seeking fat reduction without operative intervention. The non-invasive positioning expands addressable patient base beyond traditional surgical candidates.
- Ultrasound:Acoustic energy emulsifies adipose tissue prior to aspiration, reducing manual extraction force requirements.
- Vacuum-Assisted Technology:Automated suction cycling enhances extraction efficiency in high-volume body contouring procedures.
Cryolipolysis is climbing the fastest among technology segments. Radiofrequency retains premium pricing power in surgical-adjacent positioning.
End User:
Customer type determines capital intensity, staffing models, and regulatory compliance burdens across the service delivery spectrum.
- Medical Spas:Capital-light service models with physician extender staffing enable rapid geographic expansion without hospital affiliation. State-level scope-of-practice determinations in California, Texas, and Florida permit nurse practitioner and physician assistant independent operation of energy-based lipolysis equipment, broadening provider supply.
- Hospitals:Integrated surgical infrastructure supports complex cases and complication management with established accreditation frameworks.
- Clinics:Independent practice settings balance equipment access with procedure volume concentration in suburban markets.
- Dermatology Centers:Specialty positioning leverages existing laser infrastructure for platform expansion into body contouring services.
Hospitals anchor reimbursement-dependent volume. Medical Spas gain share fastest through demographic expansion and service model innovation.
Body Area:
Anatomical targeting shapes cannula design specifications, anesthesia requirements, and marketing emphasis across consumer segments.
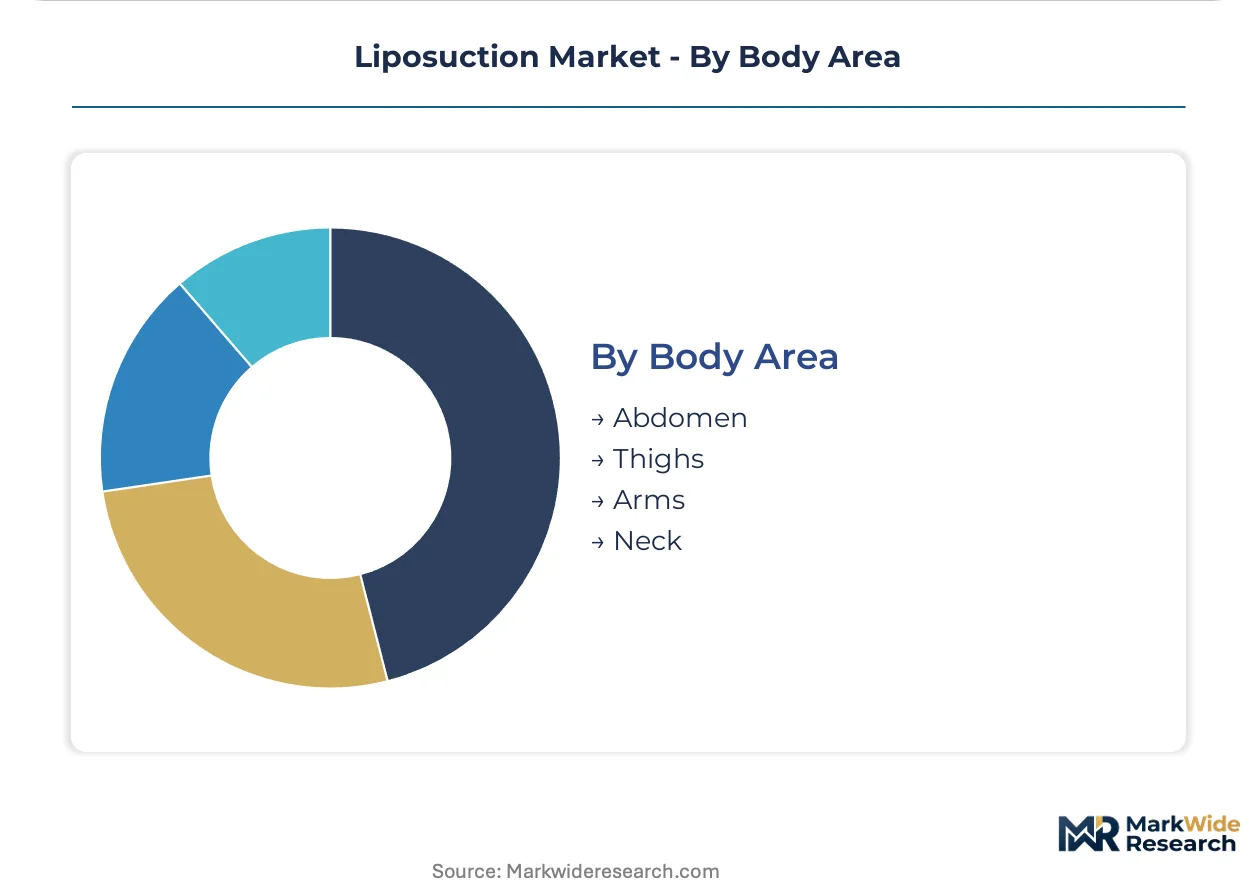
- Abdomen:Central trunk adiposity represents the highest-volume anatomical indication with established surgical pathways and broad patient candidacy.
- Thighs:Circumferential contouring demands specialized cannula curvature and positioning protocols for symmetric outcomes.
- Arms:Brachial sculpting carries elevated skin laxity considerations that favor energy-assisted platforms with thermal tightening claims.
- Neck:Submental fat reduction requires precision instrumentation and carries higher complication visibility, concentrating demand in specialized surgical settings.
Abdomen procedures anchor commercial volume. Neck applications concentrate in premium-tier positioning with elevated technical requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of energy-based liposuction devices concentrate in markets with established aesthetic medicine infrastructure, while export competitiveness clusters around manufacturers with deep regulatory expertise in major jurisdictions. Trade patterns reflect divergent compliance burdens and reimbursement environments across developed economies.
United States
Medical spa channel expansion in Texas and Florida drives device procurement volume, with ambulatory surgical centers in California and New York sustaining premium-tier utilization. FDA 510(k) clearance pathways for radiofrequency and laser platforms govern commercialization timelines, compressing competitive entry cycles for predicate device strategies. Metropolitan clusters in Miami, Dallas, and Los Angeles concentrate procedure volume and equipment deployment.
Germany
Hospital outpatient departments in Bavaria and North Rhine-Westphalia anchor reimbursement-dependent tumescent liposuction volume. The European Medical Device Regulation imposes strengthened clinical evidence standards and extended conformity assessment intervals for energy-based systems. Medical technology clusters around Munich and Stuttgart host distributors serving Central European aesthetic medicine practices.
Brazil
High procedural density in São Paulo and Rio de Janeiro supports import demand for laser-assisted and ultrasound platforms. ANVISA registration requirements shape device commercialization timelines, favoring manufacturers with established Latin American regulatory affairs capabilities. Independent clinic chains in southeastern states drive capital equipment procurement outside hospital systems.
South Korea
Seoul Capital Area aesthetic medicine practices deploy advanced energy-based platforms at density rates exceeding regional peers. MFDS approval pathways for novel lipolysis technologies accelerate market access for domestic and imported devices. Busan-Ulsan medical tourism corridors concentrate international patient volume seeking combination body contouring procedures.
Australia
Sydney and Melbourne dermatology centers adopt radiofrequency-assisted platforms as competitive differentiators against traditional surgical offerings. TGA inclusion requirements for energy-based medical devices impose documentation burdens that extend market entry timelines. Medical spa expansion in Queensland broadens addressable end-user base beyond hospital-affiliated settings.
Liposuction Market Competitive Environment
On the supply side, the industry is moderately consolidated around energy-based device specialists with established regulatory affairs capabilities and geographic distribution infrastructure. Three strategic archetypes dominate: full-platform manufacturers spanning multiple energy modalities, focused radiofrequency or laser specialists, and diversified aesthetic device portfolios with liposuction as a segment component. Competitive moves concentrate on technology licensing arrangements and direct sales channel control in metropolitan markets.
Within the full-platform tier, Lumenis Ltd. and Alma Lasers Ltd. exemplify manufacturers with broad energy-based portfolios spanning surgical and non-invasive applications. InMode Ltd. occupies a position among radiofrequency-focused specialists with premium-tier positioning in ambulatory settings. Cutera, Inc. represents North American direct sales channel control as a competitive archetype. These anchors illustrate how technology ownership and geographic distribution shape sustainable positioning.
| Leading Market Players |
|---|
| Lumenis Ltd. |
| Cutera, Inc. |
| InMode Ltd. |
| Candela Corporation |
| Sciton, Inc. |
| Hologic, Inc. |
| Solta Medical |
| Lutronic Co., Ltd. |
| Alma Lasers Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's concentrated manufacturing base for energy-based medical devices shapes downstream pricing power across global aesthetic medicine markets. Component sourcing from this cluster feeds into laser liposuction platform assembly, with capacity utilization fluctuations transmitting directly into equipment lease rates and service pricing tiers for ambulatory surgical centers.
Pricing Analysis
Hospital purchasing committees anchor pricing negotiations for capital-intensive laser liposuction platforms, extracting volume discounts through GPO contracts and bundled service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, after-sales training intensity, and geographic service coverage radius. Cost compression in mid-tier radiofrequency systems is intensifying because manufacturers compete for medical spa channel entry with reduced upfront capital requirements. Independent dermatology practices exhibit highest price sensitivity due to constrained balance sheets, while integrated hospital systems leverage scale for preferential terms.
Supply Chain Analysis
Export control regimes limiting semiconductor laser diode shipments constrain production scheduling for fiber-optic delivery systems in energy-based lipolysis devices. Manufacturing concentrates in China, Israel, and the United States, with each hub specializing in distinct energy modalities—radiofrequency assemblies, laser sources, and ultrasound transducers respectively. Supply chains draw from gallium arsenide substrates, precision optical fibers, and medical-grade cooling systems, with single-source vulnerability concentrated in specialized laser diode foundries. Distribution runs through manufacturer-direct sales teams in metropolitan medical device corridors, supplemented by regional distributors serving secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated medical spa chains negotiating enterprise-wide equipment leases, fragmenting the historically hospital-centric procurement landscape. This consolidation enables volume-based pricing pressure on manufacturers while creating preferred vendor relationships that disadvantage smaller competitors.
For Market Incumbents: Pre-empt cryolipolysis substitution by accelerating radiofrequency platform refresh cycles and embedding software companion tools that lock in provider workflow dependency. Defensive patent filings around simultaneous skin tightening claims create barriers against emerging ultrasound competitors. Capacity addition in Texas and Florida medical spa corridors captures demographic expansion before regional saturation. Certification investment in European MDR technical documentation preserves market access as smaller competitors exit due to compliance cost concentration. For New Entrants and Emerging Players: Secondary-tier cities in Brazil's southeastern states present underpenetrated demand for ultrasound-assisted platforms outside São Paulo's saturated core. White-space exists in project finance structuring for independent dermatology practices seeking laser platform access without balance-sheet strain. The most penetrable segment spans nurse practitioner-staffed medical spas in California, Texas, and Florida where scope-of-practice expansion permits independent energy-based device operation. Go-to-market execution through equipment leasing partnerships with aesthetic medicine distributors bypasses direct sales infrastructure requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because FDA 510(k) predicate device strategies and European MDR conformity assessment capabilities concentrate competitive advantage among established manufacturers with deep quality management systems. Acquisition targets should display robust notified body relationships and established clinical evidence portfolios rather than novel technology differentiation. The signal to watch is medical board scope-of-practice liberalization in additional states, which would expand addressable provider base and equipment deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device pathways accelerate commercialization timelines for radiofrequency platforms entering United States markets. |
| CE Marking Pathway | European MDR conformity assessment capabilities preserve market access as compliance costs concentrate competitive field. |
| Hospital System Partnership | GPO contract penetration locks in ambulatory surgical center volume through integrated procurement frameworks. |
| Software Companion Development | Workflow integration tools create provider switching costs beyond hardware specifications alone. |
| Reimbursement Strategy | Coding alignment with hospital outpatient department billing sustains tumescent liposuction utilization against medical spa competition. |
Study Parameters
Operator-level perspectives from aesthetic surgeons, medical spa medical directors, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation databases, hospital procurement records, and customs trade data for energy-based device imports. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Scenario-bracketing framed volume and value outputs across procedure type, technology modality, end-user setting, and regional regulatory cluster segmentation. CAGRs derived from weighted regression across historical utilization patterns and projected demographic penetration rates. Forecast inputs incorporated medical spa channel expansion velocity, state-level scope-of-practice determinations, and energy-based device approval timelines through major regulatory pathways.
The forecast holds incumbent behavior within observed patterns; aggressive moves by capital-flush private equity-backed medical spa chains would shift outcomes through accelerated equipment deployment and pricing disruption. Material shifts in FDA guidance on fat-grafting adjunct claims or European MDR post-market surveillance requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
Reconstructive Surgery Market