
 UK Cosmetic Surgery Market | 2026-2036
UK Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
UK Cosmetic Surgery Market Insights
Patient demand is expanding across younger demographic cohorts as social media visibility and workplace aesthetic expectations reshape buyer profiles. The Harley Medical Group leverages its London-centric clinic network to sustain premium positioning among urban professionals. Cadogan Clinic anchors its reputation on consultant-led surgical protocols, while Signature Clinic competes through competitive pricing on high-volume procedures such as breast augmentation and liposuction.
UK cosmetic surgery encompasses surgical and non-surgical interventions modifying physical appearance through incision-based reconstruction, tissue manipulation, or energy-based dermal treatments performed in CQC-registered facilities. Procedures typically employ silicone or saline implants, tumescent fluid systems, or fractional laser wavelengths measured in nanometres to achieve structural or superficial corrections. Injectable fillers and laser technologies command expanding margin pools as patients prioritise minimal downtime, while invasive segments such as rhinoplasty retain higher per-procedure revenue despite slower volume growth. Breast augmentation occupies the largest share of surgical bookings among women aged 31-45, a demographic that also drives demand for combined facelift and eyelid procedures.
The Care Quality Commission mandates registration and inspection cycles that filter out substandard operators and elevate facility infrastructure costs across England, Wales, and Scotland. MHRA oversight of implantable devices and dermal fillers tightens product traceability requirements, compelling clinics to document batch numbers and adverse event reporting. Stakeholders must monitor pending UK-specific aesthetic practitioner licensing legislation that could restrict who may administer botulinum toxin and hyaluronic acid injections.
Market Dynamics
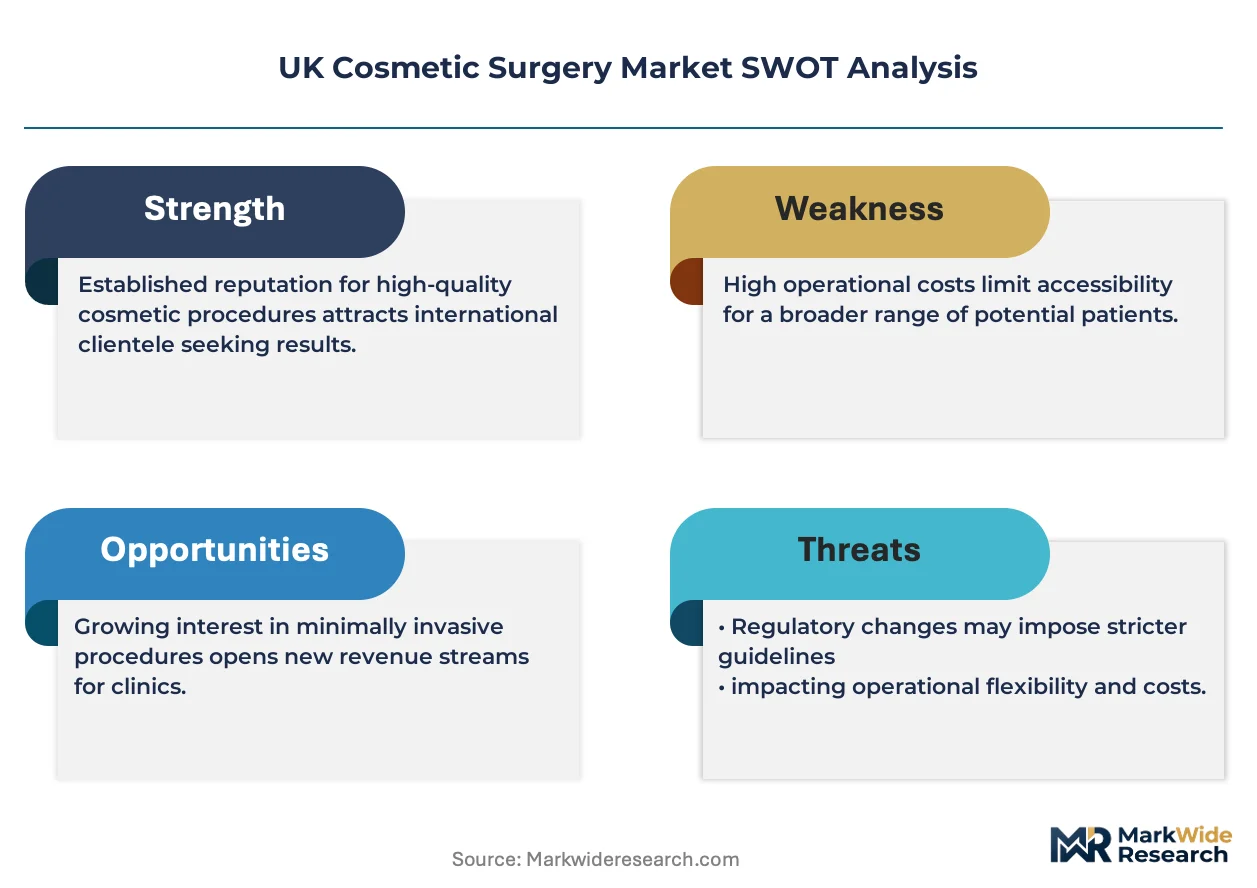
The Care Quality Commission's tightened accreditation protocols are compressing operator margins while simultaneously elevating patient safety benchmarks across England, Wales, and Scotland. This regulatory recalibration forces independent clinics to absorb facility upgrade costs or exit the market entirely.
Growth Catalysts
- Social media visibility norms:Millennial and Gen Z patients in London and Manchester now view aesthetic procedures as routine self-care rather than luxury interventions. Instagram and TikTok content normalises treatment transparency.
- CQC registration mandates:The Commission's inspection cycles filter substandard operators from the market, redirecting patient volume toward compliant facilities with demonstrable safety records.
- Energy-based dermal technologies:Fractional laser systems and radiofrequency devices reduce downtime from weeks to days, expanding addressable demand among working professionals.
Market Restraints
- Implant traceability costs:MHRA batch documentation requirements for silicone and saline implants add administrative overhead that small independent clinics struggle to absorb.
- Practitioner supply concentration:Consultant-grade surgeons cluster disproportionately in London's Harley Street corridor, limiting procedural access in Northern England and Scotland.
- Hyaluronic acid price volatility:Cross-linked filler raw material costs fluctuate with pharmaceutical-grade sodium hyaluronate availability from European suppliers.
Strategic Opportunities
- Telemedicine consultation channels:Virtual pre-assessment protocols reduce initial patient friction, particularly for younger cohorts in Birmingham and Leeds seeking information before clinic visits.
- Combined procedure packages:Facelift-eyelid bundling for women aged 31-45 captures higher per-visit revenue while optimising surgical theatre utilisation.
- Pending practitioner licensing legislation:Restricted administration rights for botulinum toxin and fillers would advantage CQC-registered facilities with existing compliance infrastructure.
Industry Challenges
- Consultant surgeon recruitment:NHS retention pressures limit private sector access to specialist registrars with reconstructive and aesthetic fellowship training.
- Adverse event reporting complexity:MHRA vigilance documentation for dermal filler complications demands dedicated clinical governance staff that smaller operators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Cosmetic Surgery Market |
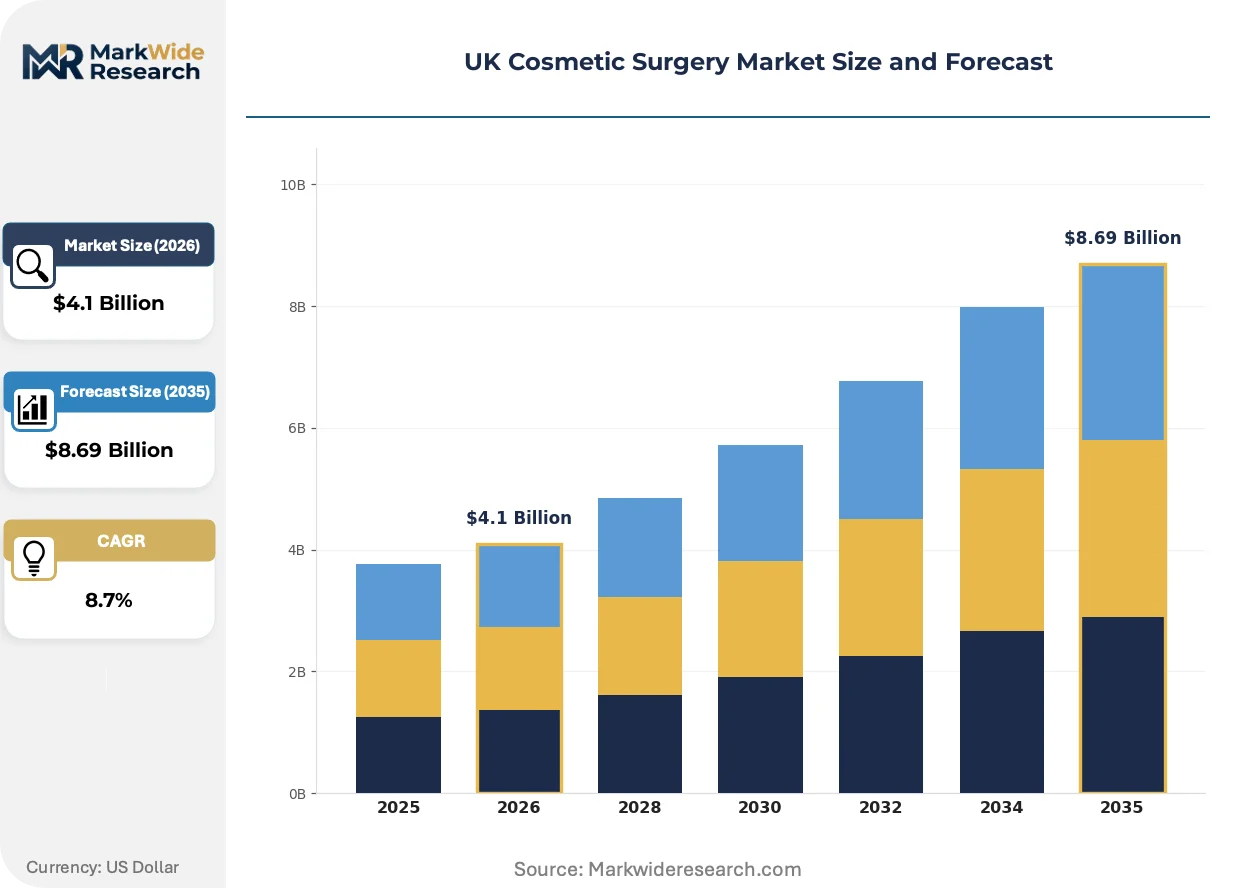
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Liposuction, Rhinoplasty, Facelift Patient Demographic: Women, Men, Age 18-30, Age 31-45 Service Type: Invasive, Non-Invasive, Minimally Invasive, Cosmetic Technology: Laser, Ultrasound, Radiofrequency, Injectable Fillers |
| Companies Covered | The Aesthetics Room, The Cosmetic Skin Clinic, The Harley Medical Group, Staiano Plastic Surgery, Dr Rasha Clinic, Cadogan Clinic, Dr MediSpa, Signature Clinic, Delta Clinics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Cosmetic Surgery Market Trends and Innovations
Digital diagnostic platforms and AI-assisted treatment planning are compressing consultation-to-procedure timelines while elevating outcome predictability. These technologies reshape how clinics qualify candidates and manage post-operative expectations.
3D facial imaging systems is automating pre-surgical simulation and consent documentation. Harley Street and Manchester clinics deploy this technology to reduce revision rates and accelerate patient decision-making. The systems compress consultation duration from ninety minutes to forty-five minutes without sacrificing informed consent integrity.
The Care Quality Commission's 2024 inspection framework intensifies scrutiny of anaesthetic protocols and emergency response capabilities. Clinics must now demonstrate consultant anaesthetist presence for all sedation procedures rather than remote supervision arrangements. Surgical facilities in England are responding by consolidating overnight recovery capabilities or restricting case complexity.
Subscription-based maintenance models for injectable treatments are displacing single-session bookings among urban professional women. Harley Medical Group and similar operators package quarterly toxin and filler top-ups with priority scheduling privileges. This shift is most visible in London's Zone 1-2 postcodes where patient lifetime value calculations now dominate acquisition strategy.
UK Cosmetic Surgery Market Segmentation
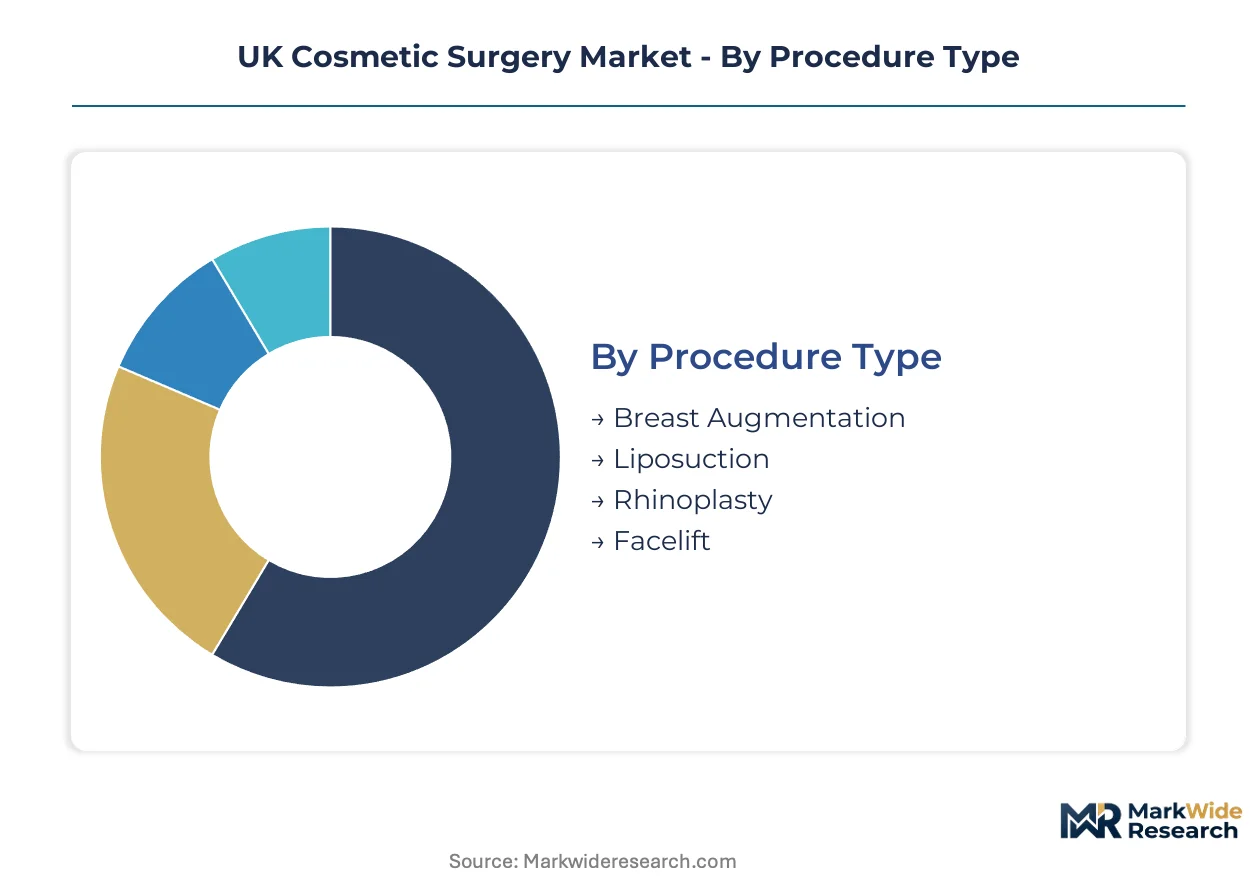
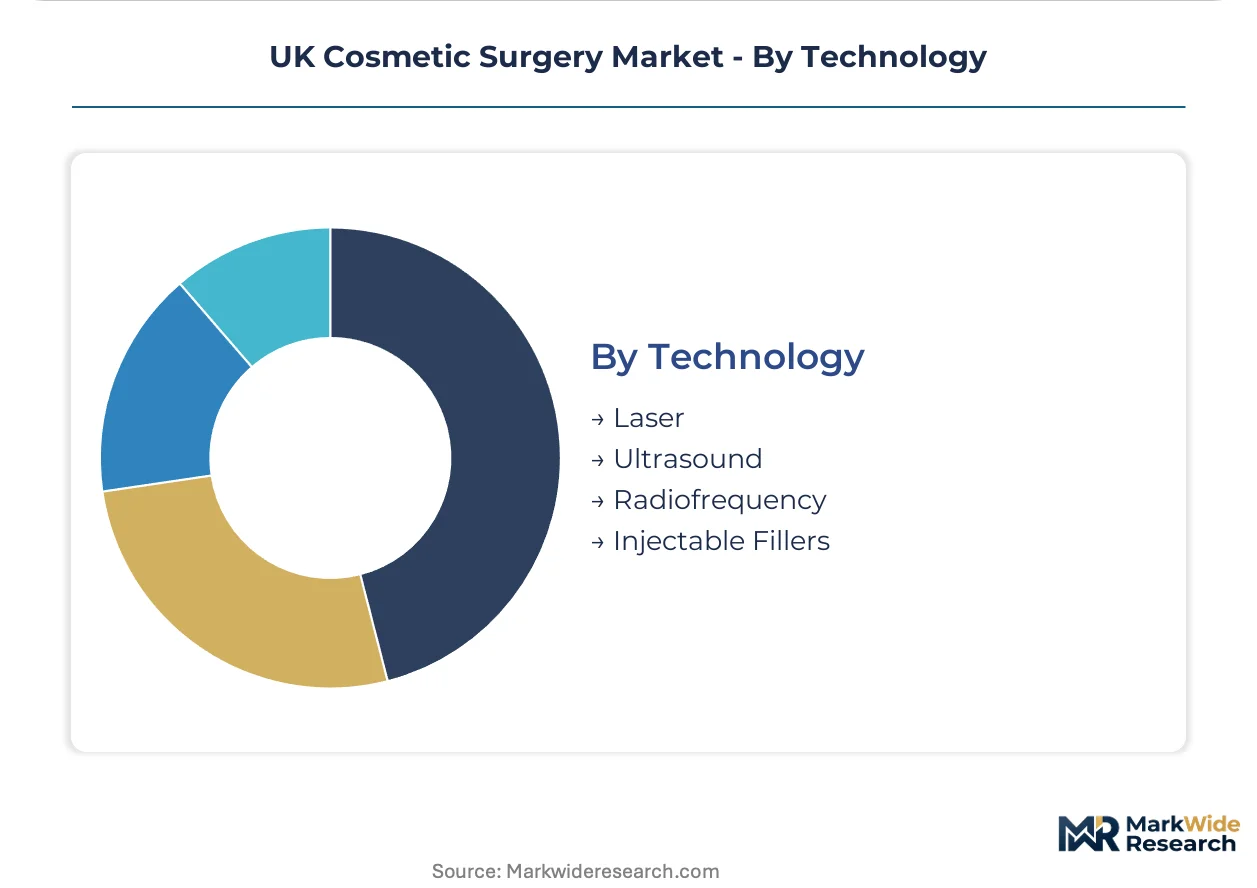
UK cosmetic surgery segmentation reveals distinct operational profiles across procedure complexity, patient lifecycle stages, and technology deployment. Understanding these divides clarifies where capital investment concentrates versus where patient acquisition costs dominate.
Procedure Type:
Standalone surgical procedures command dedicated theatre time and anaesthetic protocols, while combined interventions embed multiple corrections within single operative episodes.
- Breast Augmentation:Silicone or saline implant insertion via inframammary or periareolar incisions. Demand concentrates among women aged 31-45 in London and Manchester, driven by post-pregnancy body restoration preferences.
- Liposuction:Tumescent fluid-assisted fat extraction using cannula suction systems. Harley Street clinics report strongest volume for abdominal and flank contouring among male professionals in finance and technology sectors.
- Rhinoplasty:Nasal bone and cartilage restructuring for functional or aesthetic correction.
- Facelift:SMAS layer elevation and skin redraping procedures targeting midface and neck laxity.
Volume placements concentrate in Breast Augmentation; the faster expansion belongs to combined facelift-eyelid bundling.
Patient Demographic:
Cost tier stratification separates premium self-pay segments from emerging financed-entry cohorts reshaping clinic marketing spend allocation.
- Women:Represent the dominant patient base across surgical and non-surgical categories. Birmingham and Leeds clinics observe rising demand for preventive toxin treatments starting in late twenties.
- Men:Fastest-growing patient segment with concentrated interest in gynecomastia correction and jawline definition procedures. London's Zone 1-2 postcodes show earliest adoption curves.
- Age 18-30:Social media visibility pressures drive non-invasive first treatments.
- Age 31-45:Surgical intervention threshold drops as disposable income peaks and aesthetic concerns compound.
Volume placements concentrate in Women; the steepest expansion trajectory belongs to Men.
Service Type:
Application context distinguishes medically necessary reconstructions from purely elective enhancements with divergent consent and financing protocols.
- Invasive:Incision-based procedures requiring general anaesthesia and overnight recovery capabilities. CQC's 2024 framework mandates consultant anaesthetist presence, elevating facility compliance costs.
- Non-Invasive:Energy-based or topical treatments without epidermal breach. Radiofrequency and laser platforms dominate Manchester clinic investment cycles due to lower staff credentialing barriers.
- Minimally Invasive:Needle-entry procedures including thread lifts and micro-fat grafting.
- Cosmetic:Elective aesthetic interventions outside medical necessity definitions.
Revenue concentration sits with Invasive procedures; patient visit frequency expansion belongs to Non-Invasive.
Technology:
Supply concentration for device procurement shapes regional clinic capabilities and maintenance cost structures.
- Laser:Fractional and ablative wavelength systems for resurfacing and pigment correction. Scottish clinics lag English adoption due to distributor network gaps.
- Ultrasound:High-intensity focused ultrasound for non-surgical fat reduction and skin tightening. Northern England shows strongest per-capita demand among postpartum demographics.
- Radiofrequency:Thermal collagen remodeling devices with minimal downtime profiles.
- Injectable Fillers:Cross-linked hyaluronic acid and botulinum toxin formulations. MHRA batch traceability requirements filter smaller operators from this segment.
Capital deployment concentrates in Laser platforms; margin expansion belongs to Injectable Fillers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient demand concentrates in England's metropolitan corridors where disposable income and clinic density intersect, while regulatory harmonization across the four nations creates divergent compliance cost structures.
London and the Southeast
Harley Street and Zone 1-2 postcodes host the highest concentration of consultant-led surgical facilities, with breast augmentation and rhinoplasty commanding premium pricing among finance and technology professionals. The Care Quality Commission's 2024 inspection framework mandates consultant anaesthetist presence for all sedation procedures, forcing facility upgrades or case complexity restrictions. Cadogan Clinic anchors its reputation on surgical protocols in this corridor.
Midlands
Birmingham and Leeds clinics observe rising demand for preventive toxin treatments among patients in their late twenties, with telemedicine consultation channels reducing initial patient friction. The CQC registration mandate filters substandard operators, redirecting volume toward compliant facilities with demonstrable safety records. Signature Clinic competes through competitive pricing on high-volume procedures in this region.
North England
Manchester clinics report strongest volume for abdominal and flank liposuction among male professionals, while radiofrequency and laser platform investment cycles dominate due to lower staff credentialing barriers. MHRA batch documentation requirements for implants add administrative overhead that smaller independent clinics struggle to absorb. The Harley Medical Group leverages its network to sustain premium positioning here.
Scotland
Edinburgh and Glasgow facilities lag English adoption of fractional laser systems due to distributor network gaps, though ultrasound-based fat reduction shows strongest per-capita demand among postpartum demographics. The country's health regulator enforces CQC-equivalent standards with inspection cycles that elevate facility infrastructure costs. Consultant-grade surgeon supply constraints limit procedural access relative to southern England.
Wales
Cardiff and Swansea clinics operate under Welsh Government health standards that mirror CQC protocols, with non-invasive energy-based treatments expanding fastest due to lower capital requirements. Cross-linked filler raw material cost volatility from European suppliers pressures margin pools. Telemedicine channels capture younger cohorts seeking information before committing to clinic visits.
UK Cosmetic Surgery Market Competitive Landscape
London-centric operators anchor the premium tier; regional specialists hold volume-driven positions through pricing differentiation. The vendor base stratifies across consultant-led surgical facilities, medical spa chains, and independent aesthetic clinics. Three archetypes dominate: heritage brands with Harley Street lineage, scale-oriented groups with multi-city footprints, and digitally native entrants leveraging subscription maintenance models. Consolidation pressures favor acquisition of CQC-registered facilities with compliant infrastructure, while technology licensing agreements for energy-based devices reshape capital deployment patterns.
Within the heritage tier, Cadogan Clinic and The Harley Medical Group exemplify consultant-led positioning, with the former emphasizing surgical protocols and the latter leveraging network density for premium capture. Among digitally integrated operators, Dr Rasha Clinic and The Cosmetic Skin Clinic occupy positions that blend injectable maintenance subscriptions with social media-native patient acquisition. These three entities represent distinct competitive vectors: surgical authority, geographic scale, and digital-first engagement architecture.
| Leading Market Players |
|---|
| The Aesthetics Room |
| The Cosmetic Skin Clinic |
| The Harley Medical Group |
| Staiano Plastic Surgery |
| Dr Rasha Clinic |
| Cadogan Clinic |
| Dr MediSpa |
| Signature Clinic |
| Delta Clinics |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade sodium hyaluronate from European suppliers flows through three distinct pricing tiers before reaching UK patients, with batch-traceability compliance costs embedding premium differentials at each downstream stage.
Pricing Analysis
Volume placements concentrate in high-frequency injectable maintenance subscriptions while margin pools accrue to complex surgical bundles. Three-tier pricing structure across premium, standard, and economy levels separates Harley Street consultant-led facilities from regional chains and independent operators. Cost compression in the standard tier is intensifying because MHRA documentation requirements filter smaller clinics from implantable device segments. Price sensitivity peaks among patients aged 18-30 seeking first-time toxin treatments, while women aged 31-45 demonstrate lowest elasticity for combined facelift-eyelid procedures.
Supply Chain Analysis
Dual-sourcing requirements for silicone implants mandate qualification of both US and European manufacturers to mitigate single-source vulnerability from regulatory disruption. Raw material flows draw from Germany for precision laser systems, South Korea for radiofrequency platforms, and Switzerland for cross-linked filler formulations. Supply chain risk centers on hyaluronic acid price volatility from pharmaceutical-grade sodium hyaluronate availability constraints. Distribution runs through CQC-registered facility networks with direct-to-clinic device deployment and centralized implant procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK cosmetic surgery market is becoming a vertical-integration race where control over compliant infrastructure and captive patient acquisition channels determines survival.
For Market Incumbents: Deepen backward integration into CQC-registered facility ownership to lock out emerging competitors before pending practitioner licensing legislation restricts administration rights. Prioritize acquisition of Manchester and Birmingham clinics with established telemedicine channels to preempt regional consolidation. Cadogan Clinic's consultant-led model demonstrates how surgical authority defends margin position against price-competing chains.
For New Entrants and Emerging Players: Capture the men-specific procedural segment in Northern England where gynecomastia correction and jawline definition show fastest expansion with lowest competitive density. Target subscription-based maintenance models for urban professional women in Leeds and Birmingham where incumbent presence remains thinner than London. Deploy social media-native acquisition architecture to reduce patient friction before clinic commitment.
For Investors and Strategic Acquirers: CQC registration application volume acceleration is the leading indicator that regulatory compliance is becoming a scarce, monetizable asset. Five-to-ten-year viability favors platforms with multi-city footprints and existing inspection infrastructure over single-site operators facing upgrade costs. Acquisition target archetype: CQC-registered facilities with overnight recovery capabilities and consultant anaesthetist relationships in underserved Northern England and Scotland markets.
| Strategic Initiative | Industry Significance |
|---|---|
| CQC Compliance Infrastructure Investment | Registration and inspection capabilities become scarce assets that filter competitors under tightened 2024 frameworks. |
| Subscription Maintenance Model Deployment | Quarterly toxin and filler packages with priority scheduling capture patient lifetime value in London Zone 1-2 postcodes. |
| Telemedicine Consultation Channel Buildout | Virtual pre-assessment protocols reduce friction for Millennial and Gen Z cohorts in Birmingham and Leeds. |
| Combined Procedure Package Development | Facelift-eyelid bundling optimizes surgical theatre utilization while elevating per-visit revenue from women aged 31-45. |
| Consultant Anaesthetist Network Expansion | Mandated presence for all sedation procedures under CQC 2024 requirements limits case complexity at non-compliant facilities. |
Research Methodology
Multi-period observation of CQC inspection outcomes, MHRA adverse event filings, and clinic registration patterns anchored the trend analysis, supplemented by interviews with clinic operations directors, consultant surgeons, biomedical device procurement managers, and aesthetic practitioner training program leads. Secondary validation drew from Care Quality Commission inspection reports, MHRA vigilance databases, NHS workforce statistics, and private healthcare facility licensing records. Bottom-up procedure volume estimates and top-down market sizing triangulated through cross-reference against energy-based device import data and hyaluronic acid pharmaceutical-grade supply disclosures.
Input-output matrix framing connected demographic demand drivers to technology deployment cycles and regulatory compliance cost structures across the projection horizon. Segmentation dimensions modeled encompassed procedure complexity tier, patient lifecycle stage, service delivery mode, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation with elasticity adjustments for disposable income and social media influence penetration. Industry-specific forecast inputs included CQC inspection cycle timing and pending practitioner licensing legislation progression.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory implementation timing and European supply chain disruption. Deviation in CQC enforcement intensity or MHRA batch-traceability mandate scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market