
 Cosmetic Surgery Products Market | 2026-2036
Cosmetic Surgery Products Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Surgery Products Market Intelligence
A clear divergence between high-efficacy, clinically-validated systems and lower-cost aesthetic devices is rebalancing the competitive landscape. This split separates premium segments, where brand reputation and long-term clinical data are paramount, from the volume-driven commodity tier. AbbVie Inc. leverages its established brand portfolio in injectables to command premium pricing. In contrast, Cynosure LLC competes on the basis of its specialized laser and energy-based device technology.
Cosmetic surgery products encompass a range of medical devices, implants, and injectable formulations used for aesthetic enhancement or reconstruction. These products, such as silicone or saline breast implants and hyaluronic acid-based fillers, are designed to alter appearance and require sterile manufacturing processes. Among product types, dermal fillers and energy-based devices like laser equipment show significant growth. The end-user base is diversifying from plastic surgeons to include a growing number of dermatologists and medical spas.
Regulatory oversight from bodies like the US FDA, the European Union's EMA under MDR, and Brazil's ANVISA dictates market access and product safety standards. These agencies mandate stringent clinical trials and post-market surveillance for high-risk devices such as implants and injectables. Consequently, navigating the evolving requirements for material biocompatibility and device efficacy remains a central strategic challenge for all manufacturers.
Market Dynamics
The primary force shaping the cosmetic surgery products market is the bifurcation of demand, splitting between clinically-validated, high-risk medical devices and more accessible, lower-risk aesthetic systems. This divergence extends the end-user base beyond surgeons to dermatologists and medical spas.
Growth Catalysts
- Minimally Invasive Technologies:The development of advanced, non-surgical technologies, including fractional laser systems and radiofrequency devices, provides effective alternatives to traditional surgery, attracting a broader consumer base seeking minimal downtime.
- Demographic Expansion:A rising male demographic seeking aesthetic treatments and the normalization of cosmetic procedures across different age groups are expanding the addressable market, particularly for facial rejuvenation and body contouring products.
- Geographic Concentration:High per-capita procedure volumes in countries like Brazil create concentrated hubs of demand, spurring localized investment in distribution networks and training centers for both injectables and energy-based devices.
Market Restraints
- Regulatory Scrutiny:Stringent pre-market approval and post-market surveillance requirements, such as the European Union's MDR, create significant compliance costs and extend development timelines for high-risk implants and injectables.
- High System Costs:The substantial capital investment required for premium, clinically-proven laser and energy-based platforms limits adoption among smaller practices and medical spas, constraining market access in the volume-driven tier.
- Adverse Event Publicity:Negative media coverage and social discourse surrounding procedural complications or unsatisfactory outcomes for products like dermal fillers can rapidly erode consumer confidence and trigger regulatory investigations.
Strategic Opportunities
- Emerging Market Penetration:Untapped demand in Southeast Asian and Middle Eastern countries with rising disposable incomes presents a significant growth vector for manufacturers able to navigate local regulatory frameworks and cultural preferences.
- Combination Therapy Protocols:Developing and validating protocols that combine different modalities, such as using energy-based devices to enhance the efficacy of injectable fillers, opens new revenue streams and creates higher-value treatment packages.
- Personalized Formulations:Advances in material science offer the potential for customized injectable formulations and patient-specific implants, addressing niche anatomical needs and improving aesthetic outcomes for diverse patient populations.
Industry Challenges
- Material Biocompatibility Compliance:Manufacturers face an ongoing challenge to meet evolving standards for material safety and biocompatibility, especially for long-term implantable devices, which requires continuous investment in research and testing.
- Specialized Training Gap:The proliferation of complex energy-based devices into non-surgical settings like medical spas creates a training deficit, increasing the risk of improper use and suboptimal patient outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Surgery Products Market |
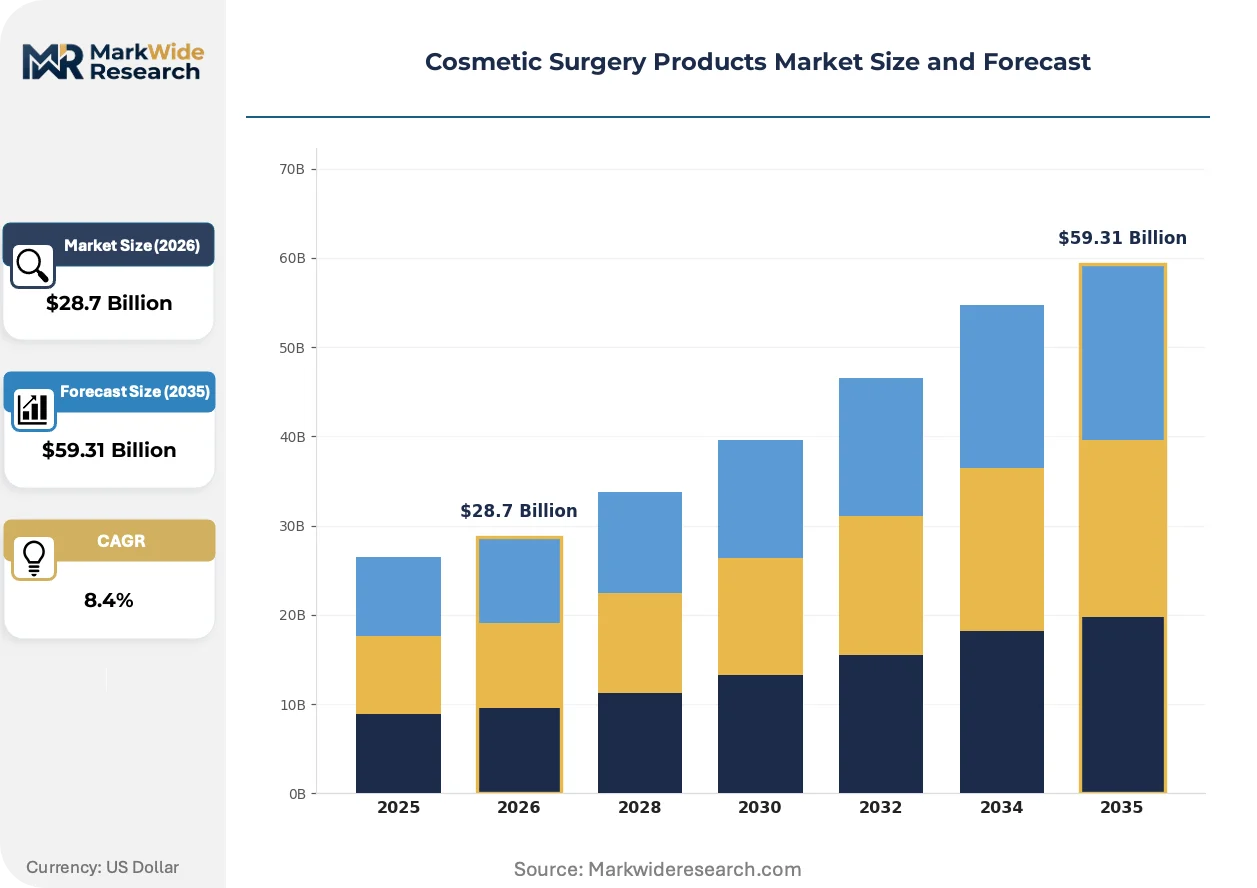
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breast Implants, Dermal Fillers, Liposuction Devices, Laser Equipment, Thread Lifts Technology: Radiofrequency, Ultrasound, Cryolipolysis, Electromagnetic, Fractional Laser Application: Facial Rejuvenation, Body Contouring, Scar Revision, Hair Restoration, Skin Tightening End User: Plastic Surgeons, Dermatologists, Medical Spas, Aesthetic Clinics, Ambulatory Centers |
| Companies Covered | AbbVie Inc., Cynosure LLC, Cutera Inc., Alma Lasers Ltd, Galderma, Johnson & Johnson Services, Inc., Merz Aesthetics Inc, Stryker, Lumenis Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Surgery Products Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of medical-grade science with consumer-driven demand for accessibility and personalization. This creates new product categories and reshapes the competitive dynamics between device manufacturers and pharmaceutical companies specializing in injectables.
Advanced energy-based devices, including fractional laser and intense pulsed light systems, deliver targeted thermal energy to stimulate collagen production and skin resurfacing. Dermatologists and aesthetic clinics are rapidly adopting these platforms for non-invasive facial rejuvenation and pigment correction. This technology is absorbing a significant portion of the patient population that previously would have considered more invasive surgical facelifts or chemical peels.
Regulatory frameworks are intensifying their focus on patient safety for aesthetic products, particularly high-risk devices. The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence, risk management, and post-market surveillance. Implantable devices and dermal fillers are most impacted, compelling manufacturers to generate more robust long-term data to maintain market access in Europe.
A distinct shift in service delivery is decentralizing procedures away from hospital-based plastic surgery departments. Stand-alone medical spas and specialized dermatology practices are capturing a growing volume of non-surgical treatments, especially injectables and laser-based therapies. This trend is most advanced in urban centers across North America and Western Europe, driven by consumer demand for convenience and specialized expertise.
Cosmetic Surgery Products Market Segmentation
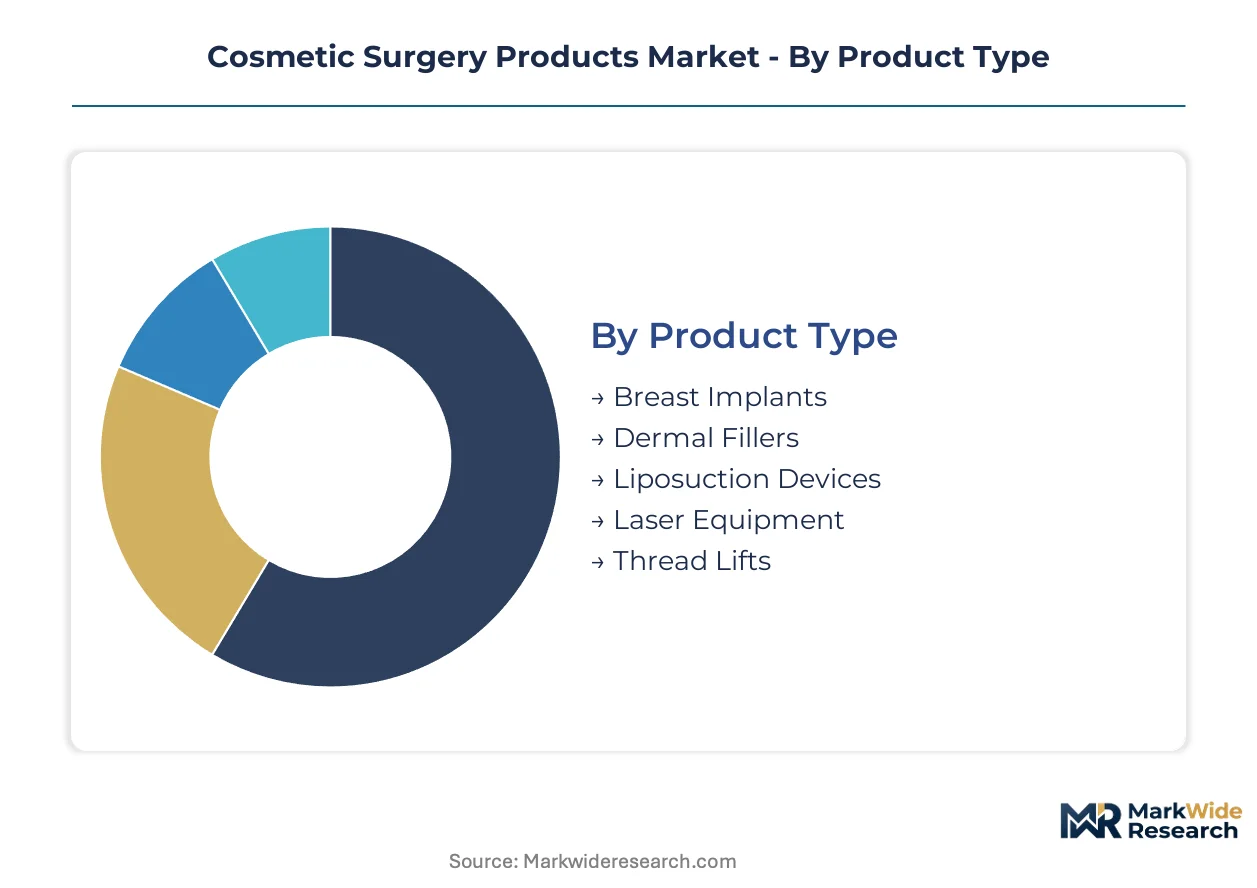
The cosmetic surgery products market exhibits significant diversity across its offerings and end-user base. Understanding these distinct segments is crucial for manufacturers to tailor product development and market strategies effectively. This segmentation highlights the various technologies, applications, and professional channels driving demand for aesthetic enhancements.
Product Type:
The market's product offerings are defined by their functional mechanisms and material compositions, addressing a wide range of aesthetic concerns.
- Dermal Fillers:These injectable formulations, primarily based on hyaluronic acid or calcium hydroxylapatite, restore facial volume, smooth wrinkles, and enhance contours. Demand for these minimally invasive products is expanding significantly in urban centers across North America, driven by consumer preference for immediate, non-surgical results.
- Laser Equipment:Advanced laser systems, including fractional and pulsed light devices, deliver targeted energy for skin resurfacing, pigment correction, and collagen stimulation. Dermatologists and aesthetic clinics in Europe are rapidly adopting these platforms for non-invasive facial rejuvenation treatments.
- Breast Implants:Medical devices, typically made of silicone or saline, are surgically inserted to augment or reconstruct breast tissue. These products require stringent regulatory approval from bodies like the US FDA and European Union's EMA.
- Liposuction Devices:These devices employ suction-assisted techniques to remove localized fat deposits from various body areas. New technologies focus on improving patient comfort and recovery times.
- Thread Lifts:Minimally invasive procedures use dissolvable sutures to lift and reposition sagging facial tissues. These offer an alternative for patients seeking subtle lifting without extensive surgery.
Breast Implants lead on scale; Dermal Fillers lead on momentum.
Technology:
The underlying technological platforms dictate treatment efficacy and patient comfort, influencing the adoption rates across different clinical settings.
- Fractional Laser:This technology uses microscopic laser beams to create controlled thermal injury zones, stimulating collagen production and skin regeneration. It shows the steepest expansion trajectory for treating sun damage and fine lines.
- Radiofrequency:Devices employing radiofrequency energy generate heat to tighten skin and improve contours by promoting collagen and elastin production. These non-invasive systems are widely used in medical spas for facial and body treatments.
- Ultrasound:High-intensity focused ultrasound (HIFU) delivers thermal energy to deeper skin layers, causing tissue contraction and lifting effects. This technology provides a non-surgical option for skin laxity.
- Cryolipolysis:This non-invasive procedure selectively freezes and eliminates fat cells, offering body contouring without surgery. Demand for fat reduction procedures drives its market presence.
- Electromagnetic:Devices using high-intensity focused electromagnetic (HIFEM) technology stimulate muscle contractions for toning and strengthening. This innovation targets muscle definition in aesthetic applications.
Fractional Laser technology shows the steepest expansion trajectory, driven by demand for non-invasive skin resurfacing.
Application:
Procedural applications define the specific aesthetic concerns addressed by cosmetic products, reflecting evolving consumer preferences and demographic shifts.
- Facial Rejuvenation:This broad application includes treatments for wrinkles, fine lines, volume loss, and skin texture improvement using injectables, lasers, and energy-based devices. Facial rejuvenation procedures capture the largest volume of treatments across North America and Europe.
- Body Contouring:Procedures aimed at reshaping and improving the appearance of the body, such as fat reduction, skin tightening, and muscle toning, fall under this category. Body contouring solutions gain share across diverse demographics, including a rising male demographic.
- Skin Tightening:Treatments specifically designed to improve skin laxity and firmness, often utilizing radiofrequency or ultrasound technologies. These procedures are gaining popularity as alternatives to surgical lifts.
- Scar Revision:Techniques and products used to minimize the appearance of scars resulting from injuries, surgeries, or acne. Laser therapies and specialized fillers are common in this segment.
- Hair Restoration:Procedures and products addressing hair loss, including surgical transplants and non-invasive treatments like PRP therapy. This application serves a growing patient population seeking solutions for thinning hair.
Facial Rejuvenation procedures capture the largest volume of treatments, while Body Contouring solutions gain share across diverse demographics.
End User:
The diverse end-user landscape reflects varying levels of specialization and facility types, influencing product distribution and service delivery models.
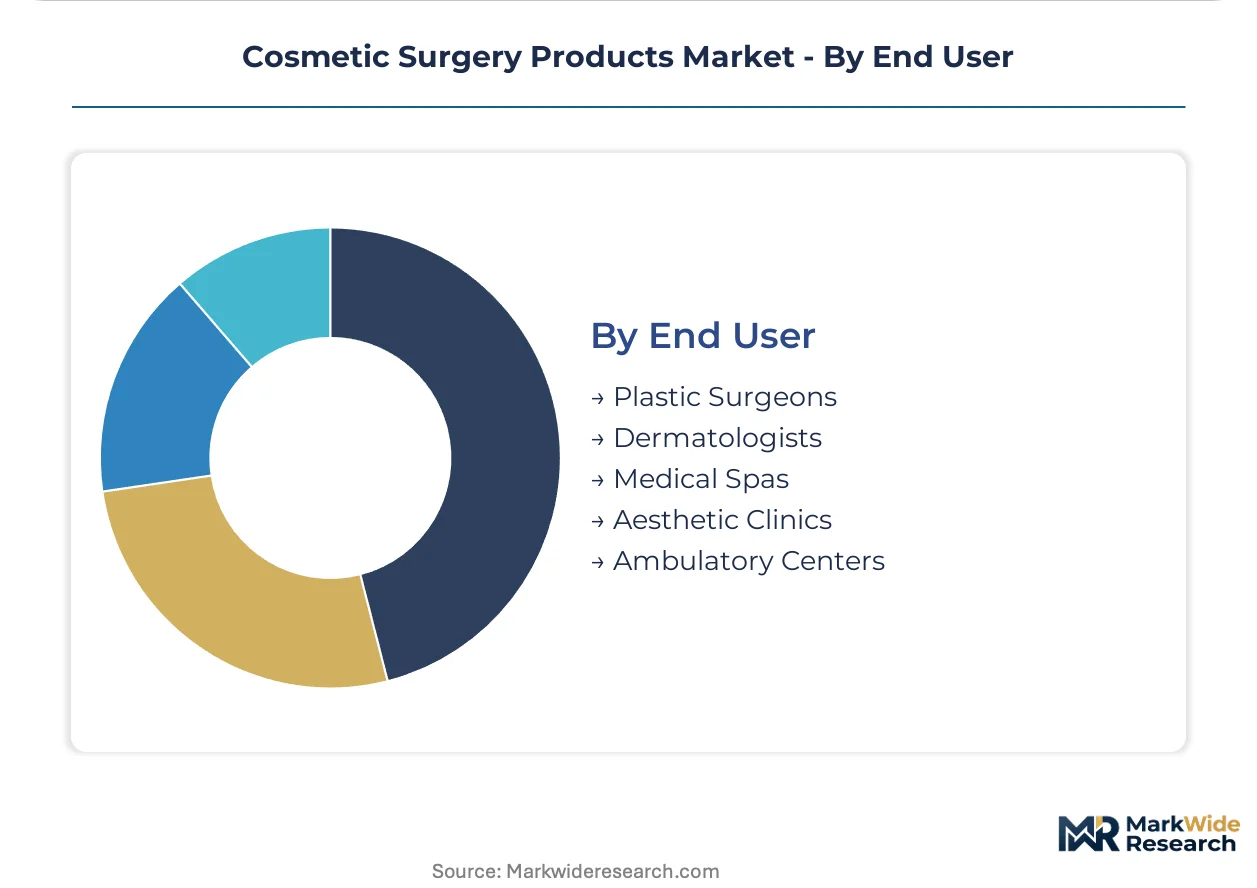
- Plastic Surgeons:These medical professionals perform a wide range of surgical and non-surgical cosmetic procedures, often handling complex cases and implant placements. Plastic surgeons remain central for high-risk implantable devices and advanced surgical interventions.
- Medical Spas:Facilities offering non-surgical aesthetic treatments in a spa-like environment, including injectables, laser therapies, and skin treatments. Medical spas are expanding their reach for non-invasive treatments, driven by consumer demand for accessibility.
- Dermatologists:Physicians specializing in skin health who increasingly incorporate aesthetic procedures, such as laser treatments, chemical peels, and dermal fillers, into their practices. Dermatologists are expanding their role in non-invasive aesthetic procedures.
- Aesthetic Clinics:Specialized clinics focused exclusively on cosmetic procedures, offering a blend of surgical and non-surgical options. These clinics provide dedicated environments for aesthetic enhancements.
- Ambulatory Centers:Outpatient surgical facilities where minor cosmetic surgeries and more extensive non-surgical procedures are performed. These centers provide a convenient setting for procedures not requiring overnight hospitalization.
Plastic Surgeons remain central for complex procedures, with Medical Spas expanding their reach for non-invasive treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized talent concentrations in research and development anchor regional demand for cosmetic surgery products, influencing both technological innovation and market penetration. These hubs attract investment and foster a skilled workforce capable of delivering advanced aesthetic treatments.
United States
Demand for non-invasive facial rejuvenation treatments and advanced body contouring solutions drives market activity in the United States. The US FDA maintains stringent oversight for medical devices and injectable formulations, ensuring product safety and efficacy. Major metropolitan areas like Los Angeles and New York City concentrate specialized medical spas and aesthetic clinics, offering a wide array of procedures.
Brazil
High per-capita procedure rates and a strong cultural acceptance of aesthetic enhancements characterize the Brazilian market for cosmetic surgery products. ANVISA, Brazil's health surveillance agency, regulates the import and sale of these products, impacting market access. Cities such as São Paulo and Rio de Janeiro serve as significant hubs for plastic surgeons and cosmetic dermatologists.
Germany
The German market exhibits strong demand for high-efficacy, clinically validated energy-based devices and premium injectable products. European Union's MDR mandates rigorous clinical evidence and post-market surveillance for devices sold within its member states. Medical technology clusters in regions like Bavaria drive innovation and specialized training for aesthetic practitioners.
China
Rising disposable incomes and evolving beauty standards are fueling demand for cosmetic surgery products across China, particularly for dermal fillers and laser equipment. The NMPA (National Medical Products Administration) oversees the approval and regulation of aesthetic medical devices and drugs. Coastal megacities such as Shanghai and Beijing are centers for aesthetic clinics and advanced treatment adoption.
United Arab Emirates
Untapped demand in the Middle East, coupled with a preference for luxury aesthetic services, positions the UAE as a growing market for cosmetic surgery products. The Ministry of Health and Prevention (MOHAP) regulates health products and services, ensuring compliance with national standards. Dubai has emerged as a prominent destination for medical tourism and high-end cosmetic procedures.
Cosmetic Surgery Products Market Key Industry Players
Capital-heavy producers of advanced medical devices compete with asset-light formulators of injectable products, creating a tiered competitive environment. This market bifurcates between companies offering premium, clinically-validated systems and those providing more accessible, volume-driven aesthetic solutions. Strategic archetypes include specialized device manufacturers, pharmaceutical companies with injectable portfolios, and diversified healthcare conglomerates. Dominant competitive moves involve continuous R&D investment in new technologies and strategic partnerships to expand distribution networks.
Companies such as AbbVie Inc. exemplify the pharmaceutical archetype, leveraging established injectable brands to command premium pricing in the market. Cynosure LLC occupies a position among specialized laser and energy-based device manufacturers, focusing on technology-driven solutions. Galderma, another significant player, anchors the dermal filler segment with its extensive portfolio of hyaluronic acid-based products.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Cynosure LLC |
| Cutera Inc. |
| Alma Lasers Ltd |
| Galderma |
| Johnson & Johnson Services, Inc. |
| Merz Aesthetics Inc |
| Stryker |
| Lumenis Inc |
| Others |
Cost & Logistics Intelligence
Vertical integration into specialized material manufacturing anchors both the supply position and pricing power for high-efficacy cosmetic surgery products. This strategic control over critical inputs ensures consistent quality and enables manufacturers to command premium pricing in a highly regulated market.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing for cosmetic surgery products. Transactional pricing dominates for individual devices and injectable units, while value-based pricing emerges for advanced treatment protocols. Brand premium and certification level from bodies like the US FDA differentiate product tiers. Pricing pressure stems from the proliferation of lower-cost aesthetic alternatives, particularly impacting the volume-driven segment. Medical spas exhibit higher price sensitivity compared to specialized plastic surgeons.
Supply Chain Analysis
Specialized distributor networks efficiently deliver cosmetic surgery products to clinics and medical spas. Geographic supply for high-risk injectables and implants concentrates in the United States and Europe, driven by stringent regulatory environments. Raw material dependencies center on medical-grade silicones for implants and hyaluronic acid for dermal fillers. Regulatory restrictions, such as those from the European Union's MDR, represent a significant structural risk for market access and product availability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cosmetic surgery products market functions as a regulatory compounder, with the European Union's MDR driving demand for robust clinical evidence and product safety.
For Market Incumbents:Lock in long-term clinical data for existing premium injectable and implant portfolios to counter emerging lower-cost aesthetic devices. Invest in next-generation minimally invasive technologies to maintain a competitive edge against new entrants. Strengthen regulatory affairs capabilities to navigate evolving compliance requirements, especially for material biocompatibility. Expand R&D into personalized formulations to address niche anatomical needs.
For New Entrants and Emerging Players:Launch via specialized training programs targeting dermatologists and medical spas to address the training gap for complex energy-based devices. Penetrate underserved geographic markets in Southeast Asia and the Middle East with accessible, lower-risk aesthetic systems. Focus on combination therapy protocols to offer higher-value treatment packages. Leverage digital platforms for consumer education and direct-to-consumer engagement strategies.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory compliance costs for high-risk products become prohibitive for smaller players. The market offers long-term viability, driven by demographic expansion and continuous technological innovation. Target niche technology developers specializing in personalized injectables or advanced energy-based platforms. A key signal to watch is the pace of regulatory approvals for novel high-efficacy devices.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Secures long-term data for high-risk implantable devices under EU MDR. |
| Product Launch | Introduces fractional laser systems for non-invasive facial rejuvenation treatments. |
| Strategic Partnership | Expands distribution networks for dermal fillers in emerging markets like Brazil. |
| Manufacturing Scale-Up | Addresses the demand for hyaluronic acid-based injectable formulations. |
| Regulatory Approval Pathway | Ensures market access for breast implants with US FDA and EMA compliance. |
Research Approach
Bottom-up end-user modeling reconciled against top-down manufacturer tracking forms the analytical core of this study. Primary interviews with plastic surgeons, dermatologists, device R&D leads, and regulatory specialists provided qualitative insights. Secondary validation drew from US FDA filings, EMA MDR compliance documents, ANVISA market reports, and industry association publications.
Historical trendline analysis established the baseline for future projections across the analysis window. The forecast framework modeled segmentation dimensions including product type, technology, application, end-user, and geographic region. Compound annual growth rates were derived from historical performance and projected procedure volumes by application, alongside regulatory approval timelines for new devices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological shifts or unforeseen regulatory interventions. These forecasts reflect assumptions regarding market dynamics and regulatory stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market