
 Plastic Blood Bags Market | 2026-2036
Plastic Blood Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Blood Bags Market Analytics
India is tilting toward expanded domestic production of transfusion devices as government tenders for blood safety equipment multiply. Terumo Corporation leverages its integrated polymer compounding operations to sustain cost advantages in single and double bag configurations. Fresenius Kabi anchors European supply through specialized extrusion lines that meet MDR migration limits. Weigao competes aggressively on tender pricing across provincial blood center networks.
Plastic blood bags are sterile, single-use containers fabricated from medical-grade PVC, polyolefin, or coextruded films, designed for anticoagulant storage, component separation, and gravity-fed transfusion at controlled flow rates. Manufacturing relies on radio-frequency sealing of multi-chamber geometries with integrated donor tubing and needle ports, followed by ethylene oxide or gamma sterilization to preserve hemocompatibility. Triple and quadruple bag configurations command premium positioning due to their necessity in platelet and plasma apheresis workflows, while single bags retain volume dominance in routine whole blood collection. Polyolefin and coex materials represent the fastest-growing material category as hospitals and blood banks phase out diethylhexyl phthalate plasticizers under toxicology scrutiny.
FDA 21 CFR requirements for biocompatibility and EMA MDR technical documentation govern material approval pathways, while India's CDSCO and BIS standards shape import substitution incentives for local manufacturers. ISO 3826 specifications for blood bag integrity and WHO prequalification protocols further constrain supplier eligibility in emerging markets. Stakeholders must monitor regulatory divergence between phthalate-restrictive jurisdictions and cost-sensitive procurement environments to align capacity investments with compliant material platforms.
Market Dynamics
Phthalate-free material transitions are forcing parallel reformulation of extrusion lines and sterilization protocols across blood bag manufacturing networks. This single technical mandate cascades through polymer sourcing, RF sealing parameters, and biocompatibility testing cycles.
Growth Catalysts
- EMA MDR migration limits:European technical documentation requirements for diethylhexyl phthalate alternatives are accelerating polyolefin and coextruded film adoption in component separation workflows.
- Apheresis volume expansion:Triple and quadruple bag configurations are seeing concentrated demand from hospital-based platelet collection programs scaling automated separation infrastructure.
- India:National blood program tenders for safety equipment are multiplying collection requirements across provincial blood center networks, redirecting procurement toward domestic manufacturing capacity.
Market Restraints
- Medical-grade PVC supply concentration:Specialized resin compounding for hemocompatible formulations depends on a narrow supplier base concentrated in Western European and Northeast Asian chemical clusters.
- Gamma sterilization capacity:Ethylene oxide alternatives face bottlenecks in cobalt-60 source availability and irradiation facility certification timelines.
- ISO 3826 testing burden:Integrity validation protocols for multi-chamber geometries extend product development cycles and constrain rapid material platform switches.
Strategic Opportunities
- China:Provincial blood bank consolidation under national health reform is creating tender aggregation effects favoring suppliers with integrated polymer compounding and extrusion capabilities.
- Radio-frequency sealing automation:Convergence of precision servo controls with real-time seam monitoring is digitizing quality assurance and reducing manual inspection labor in high-volume lines.
- PLI scheme incentives:India's production-linked incentive framework for medical devices is offsetting capital equipment costs for local manufacturers expanding into blood safety equipment categories.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise spanning PVC plasticizer alternatives, polyolefin rheology, and coextrusion layer adhesion sits concentrated within a small cohort of medical packaging specialists.
- Dual validation requirements:Blood banks must maintain parallel inventory of phthalate-containing and phthalate-free bag systems during transition periods, complicating logistics and expiration management.
- MDR technical documentation:European notified body capacity constraints are extending certification timelines for novel material platforms beyond typical product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Blood Bags Market |
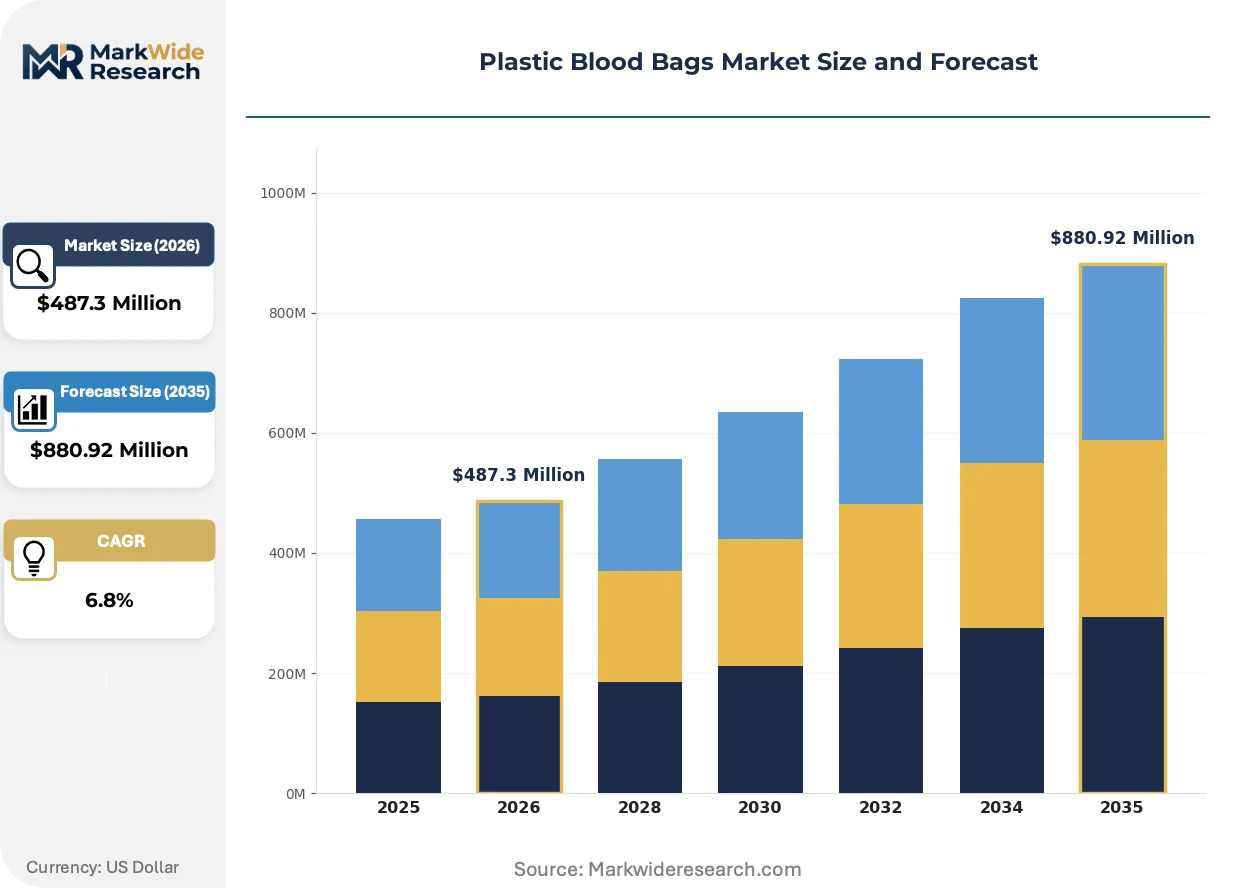
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Bags, Double Bags, Triple Bags, Quadruple Bags Material: PVC, Polyolefin, Coex, Others Application: Blood Storage, Blood Transfusion, Blood Component Separation, Plasma Collection End User: Hospitals, Blood Banks, Diagnostic Centers, Research Laboratories |
| Companies Covered | Terumo Corporation, Fresenius Kabi, Grifols S.A., Haemonetics Corporation, Macopharma, Weigao, HLL Lifecare Limited, Poly Medicure Limited, Kawasumi Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Blood Bags Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape blood bag construction, sterilization methods, and procurement specifications simultaneously. Three developments are restructuring competitive requirements.
Coextruded film architectures combining ethylene vinyl acetate barrier layers with linear low-density polyethylene sealants are digitizing manufacturing quality control through embedded RFID traceability tags. Blood banks in tertiary hospital networks are piloting these smart bag systems for cold chain monitoring. The technology is compressing manual documentation labor while enabling real-time inventory positioning across distributed collection sites.
FDA 21 CFR biocompatibility updates are tightening extractables testing protocols for plasticizers and stabilizers in extended blood storage applications. Manufacturers must now submit comprehensive chemistry profiles for all polymer additives under revised guidance. Single-use device suppliers serving US hospital systems are responding by accelerating DEHP-free platform transitions ahead of formal mandate timelines.
Consolidated tendering by national blood services is compressing supplier qualification cycles and favoring integrated manufacturers over component assemblers. China's provincial blood center networks are aggregating procurement through centralized e-platforms, displacing fragmented distributor relationships. India exhibits similar concentration as state-level blood transfusion councils unify specifications under CDSCO-aligned technical standards.
Plastic Blood Bags Market Segmentation
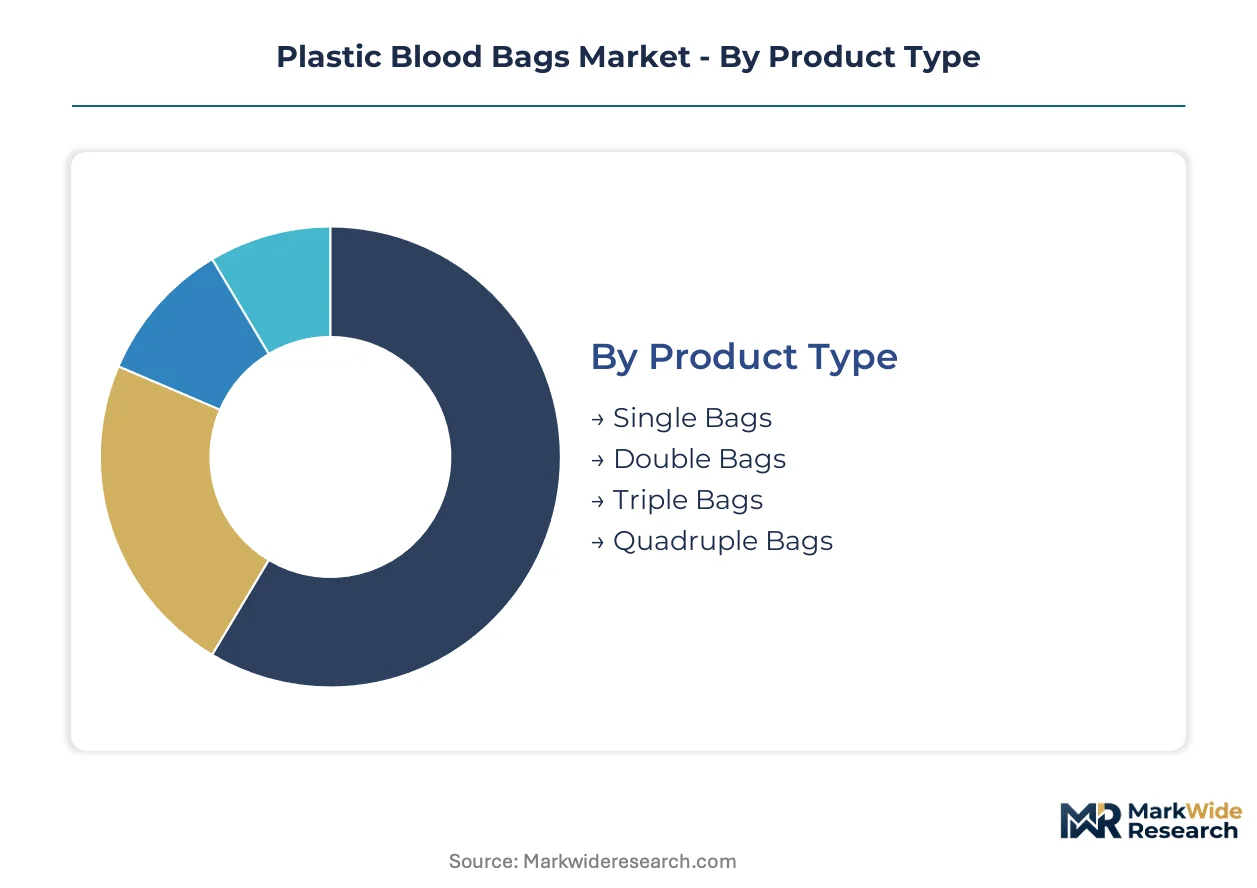
Segmentation in plastic blood bags reveals how regulatory chemistry mandates and apheresis automation are bifurcating procurement patterns. Material platforms and bag configurations now carry divergent compliance timelines and capital intensity profiles.
Product Type:
Mature configurations dominate routine collection workflows while multi-chamber systems capture automated separation demand.
- Single Bags:These units employ a single chamber with integrated donor tubing for whole blood collection and primary anticoagulant storage. Blood banks in India and China deploy single bags for mass donor drives where component separation occurs downstream at centralized processing facilities.
- Double Bags:Dual-chamber geometries enable immediate plasma separation through satellite bag transfer, reducing processing time in high-volume hospital settings. European blood centers favor double bags for emergency transfusion preparedness where rapid component availability matters.
- Triple Bags:Three-chamber systems support platelet concentrate preparation alongside red cell and plasma fractions. These configurations command premium positioning in tertiary hospital networks scaling apheresis programs.
- Quadruple Bags:Maximum chamber count enables concurrent platelet, plasma, cryoprecipitate, and red cell harvesting from single donations. Quadruple systems concentrate in specialized transfusion medicine centers with automated separation infrastructure.
Single bags retain volume leadership; quadruple bags hold the steepest expansion curve.
Material:
Cost tiers stratify between legacy PVC formulations and emerging phthalate-free alternatives with divergent sterilization compatibility.
- PVC:Plasticized polyvinyl chloride remains the incumbent platform with established RF sealing parameters and gamma sterilization tolerance. Blood banks in cost-sensitive procurement environments continue specifying PVC despite EMA MDR migration scrutiny.
- Polyolefin:Linear low-density polyethylene and polypropylene blends eliminate diethylhexyl phthalate plasticizers entirely. Japanese hospital systems and European university hospitals are accelerating polyolefin transitions ahead of formal mandate timelines.
- Coex:Coextruded multilayer films combine ethylene vinyl acetate barrier properties with polyethylene sealant layers. These architectures are gaining share fastest in smart bag deployments with embedded RFID traceability.
- Others:Experimental platforms including thermoplastic elastomers and biodegradable polymers occupy niche research applications. Regulatory validation timelines constrain commercial scale for these materials.
PVC retains volume leadership; coex materials hold the steepest expansion curve.
Application:
Volume concentration follows hospital infrastructure while margin concentration tracks specialized therapeutic workflows.
- Blood Storage:Anticoagulant preservation systems for whole blood maintain baseline demand across all geographies. Cold chain requirements favor materials with demonstrated stability at 1-6°C over extended durations.
- Blood Transfusion:Gravity-fed delivery systems with controlled flow rate ports serve emergency and surgical applications. These configurations emphasize needle port integrity and tubing kink resistance.
- Blood Component Separation:Centrifugation-compatible geometries enable mechanical fractionation of plasma, platelets, and red cells. Automated separation infrastructure in Chinese provincial blood centers is expanding this segment most quickly.
- Plasma Collection:Source plasma harvesting for fractionation into immunoglobulins and albumin requires specialized anticoagulant formulations. Plasma collection applications concentrate in dedicated donor centers with apheresis equipment.
Blood storage retains volume leadership; blood component separation holds the steepest expansion curve.
End User:
Customer type determines specification stringency, with hospitals demanding the highest material compliance and blood banks optimizing for collection economics.
- Hospitals:Surgical and emergency departments require immediate availability of multiple blood components with full FDA or EMA documentation. Tertiary hospitals in Germany and France are phasing out DEHP-containing bags ahead of schedule.
- Blood Banks:Collection-focused operations prioritize donor throughput and cold chain efficiency over component complexity. India's state-level blood transfusion councils aggregate procurement through centralized tender platforms.
- Diagnostic Centers:Limited transfusion activity restricts these facilities to single-bag configurations for occasional emergency use. Specification requirements remain minimal compared to hospital settings.
- Research Laboratories:Cell therapy and regenerative medicine applications drive demand for specialized gas-permeable materials. Academic medical centers in the US and Switzerland pilot novel bag architectures for ex vivo cell expansion.
Blood banks retain volume leadership; research laboratories hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridor underwrites European distribution capacity for sterile medical devices, while Mumbai's JNPT container terminal anchors Indian import substitution for blood safety equipment.
United States
Tertiary hospital networks in Massachusetts and North Carolina are phasing out DEHP-containing bags ahead of formal FDA timelines. The 21 CFR biocompatibility updates are tightening extractables testing protocols for extended blood storage applications. Boston's medical device cluster hosts specialized polymer compounding operations serving apheresis equipment manufacturers.
Germany
University hospitals in Bavaria and Baden-Württemberg are accelerating polyolefin transitions under EMA MDR migration limits for diethylhexyl phthalate alternatives. The MDR technical documentation requirements are extending certification timelines for novel material platforms. Freiburg's medical technology corridor concentrates extrusion line operations meeting hemocompatibility specifications.
China
Provincial blood center networks in Jiangsu and Zhejiang are consolidating procurement through centralized e-platforms under national health reform. The NMPA's alignment with ISO 3826 specifications is shaping tender aggregation effects. Suzhou's industrial park hosts integrated polymer compounding and RF sealing operations for domestic manufacturers.
India
State-level blood transfusion councils in Maharashtra and Karnataka are unifying specifications under CDSCO-aligned technical standards. The PLI scheme for medical devices is offsetting capital equipment costs for local manufacturers expanding into blood safety categories. Hyderabad's medical device cluster is scaling domestic production of transfusion devices for government tenders.
Japan
Hospital systems in Tokyo and Osaka are accelerating DEHP-free platform transitions ahead of formal mandate timelines under PMDA guidance. The METI standards for medical-grade polymer formulations are redirecting material procurement toward polyolefin alternatives. Kobe's biomedical cluster concentrates formulation expertise for coextruded film architectures.
Plastic Blood Bags Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in polymer compounding and precision extrusion. The market structure tilts toward consolidated procurement relationships with national blood services, compressing supplier qualification cycles. Three archetypes dominate: integrated polymer-to-device manufacturers, specialized RF sealing equipment suppliers, and regional tender-focused assemblers. Capacity expansion and backward integration into captive resin compounding represent the dominant competitive moves.
Within the integrated manufacturing tier, Terumo Corporation and Fresenius Kabi occupy positions exemplifying polymer-to-device platform control. Among Asia-Pacific fabricators, Weigao represents the tender-optimized archetype competing on provincial blood center network pricing. These three companies anchor the competitive structure across phthalate-free material transitions and apheresis automation demand.
| Leading Market Players |
|---|
| Terumo Corporation |
| Fresenius Kabi |
| Grifols S.A. |
| Haemonetics Corporation |
| Macopharma |
| Weigao |
| HLL Lifecare Limited |
| Poly Medicure Limited |
| Kawasumi Laboratories |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's pharmaceutical logistics corridor anchors European distribution capacity for sterile medical devices, with its cold-chain handling costs feeding directly into premium-tier pricing for phthalate-free bag configurations while compressing margins on standard PVC units procured by cost-sensitive blood banks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with premium tiers capturing polyolefin and coextruded film configurations certified under EMA MDR migration limits. Standard tiers retain DEHP-plasticized PVC for blood banks in emerging markets, while economy tiers serve diagnostic centers with minimal specification requirements. Price differentiation hinges on certification grade and volume scale, with national tender aggregation in China and India intensifying cost compression in the standard tier. Hospital systems in Germany and Japan exhibit lowest price sensitivity, prioritizing material compliance over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for blood bag manufacturers supplying European hospital networks, straining working capital for regional assemblers without captive resin operations. Medical-grade PVC compounding concentrates in Germany, Japan, and the United States, while gamma sterilization capacity clusters around cobalt-60 source availability in Canada and Russia. Raw material dependencies span specialized hemocompatible resins, RF sealing equipment, and ethylene oxide or gamma sterilization services. Single-source vulnerability in polymer chemist expertise constrains rapid material platform switches. Distribution runs through national blood service tender platforms and GPO contracts in tertiary hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise spanning PVC plasticizer alternatives and polyolefin rheology sits concentrated within a narrow cohort of medical packaging specialists, creating acquisition premiums for integrated manufacturers and entry barriers for component assemblers.
For Market Incumbents: Harden polymer-to-device platform control through backward integration into captive resin compounding operations, particularly for phthalate-free alternatives facing EMA MDR migration scrutiny. Expand RF sealing automation capacity in Suzhou and Hyderabad to capture tender aggregation effects from China's provincial blood bank consolidation and India's PLI scheme incentives. Prioritize certification investment ahead of FDA 21 CFR biocompatibility updates tightening extractables testing protocols. For New Entrants and Emerging Players: Mid-tier blood banks in Southeast Asia represent the most penetrable entry point, where specification requirements remain less stringent than European university hospitals but procurement volumes are scaling with national blood program expansion. Source plasma collection workflows for fractionation into immunoglobulins offer specialized application entry with higher margin tolerance than routine whole blood collection. Pursue co-development partnerships with apheresis equipment manufacturers to secure downstream pull-through demand. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized medical-grade polymer compounding assets and dormant extrusion line capacity. Long-term viability favors integrated manufacturers with demonstrated hemocompatibility validation and established relationships with national blood services. Watch FDA guidance timeline on DEHP-free mandate formalization as inflection indicator for material platform transition velocity and stranded asset risk in legacy PVC capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin production secures margin control amid phthalate-free transition costs and EMA MDR compliance timelines. |
| RF Sealing Automation Deployment | Precision servo controls with real-time seam monitoring reduce manual inspection labor in high-volume Chinese and Indian lines. |
| CE Marking Pathway Acceleration | Early EMA technical documentation submission offsets notified body capacity constraints extending certification cycles. |
| Hospital System Partnership | Direct relationships with German and French tertiary networks secure premium positioning ahead of DEHP phase-out mandates. |
| Smart Bag Architecture Development | Embedded RFID traceability tags enable cold chain monitoring pilots and differentiate coextruded film offerings in tender evaluations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blood bank procurement directors, hospital biomedical engineers, polymer compounding technical leads, and regulatory affairs specialists at notified bodies. Secondary validation drew from FDA 21 CFR guidance documents, EMA MDR technical documentation requirements, ISO 3826 specifications, CDSCO tender records, and customs trade data for medical-grade resin imports. Bottom-up modeling of bag configuration demand across single through quadruple systems was triangulated against top-down national blood program collection targets.
Calibration against historical capacity expansion announcements and regulatory mandate implementation timelines anchored projection assumptions across the analysis window. Segmentation dimensions encompassed product type, material platform, application workflow, and end-user procurement archetype. CAGRs were derived from elasticity-adjusted demand curves incorporating apheresis automation adoption rates and phthalate-free material substitution schedules. Industry-specific inputs included gamma sterilization facility certification backlogs and polymer chemist labor market tightness.
Practitioners should monitor EMA notified body capacity utilization, FDA DEHP guidance formalization, and cobalt-60 source availability for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Italy Hospital Supplies Market
Medical Supplies
Global Swab and Viral Transport Medium Market
Medical Supplies
North America Ostomy Drainage Bags Market
Medical Supplies
Global Disposable Syringes Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Cryogenic Vials Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
IV Infusion Gravity Bags Market
Medical Supplies
Plasma Expanders Market
Medical Supplies
Endoscope Tip Protectors Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Global Disposable and Reusable Masks Market