
 Italy Cosmetic Surgery Market | 2026-2036
Italy Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Cosmetic Surgery Market Insights
Aftermarket service revenue from laser device maintenance and consumable replenishment is tilting toward manufacturers with captive service networks. Alma Lasers leverages its direct field engineering presence across northern Italy to lock in multi-year service contracts. El.En. sustains aftermarket margins through proprietary fiber-optic handpiece replacements that limit third-party servicing. Candela Medical competes by bundling preventive maintenance into initial capital sales, reducing customer churn.
Cosmetic surgery encompasses surgical and non-surgical procedures that reshape or enhance normal body structures for aesthetic purposes, utilizing energy-based devices operating at wavelengths between 532 nm and 10,600 nm for tissue ablation, coagulation, or lipolysis. The primary commercial purpose centers on elective aesthetic improvement, distinct from reconstructive surgery addressing congenital defects or trauma. Non-invasive service types now command the fastest expansion as radiofrequency and ultrasound technologies displace traditional liposuction in patient preference, while invasive breast augmentation retains the deepest margin pools due to implant bundling and anesthesia fees. Laser technology dominates capital equipment sales, though filler-based minimally invasive procedures accelerate in outpatient clinic volume.
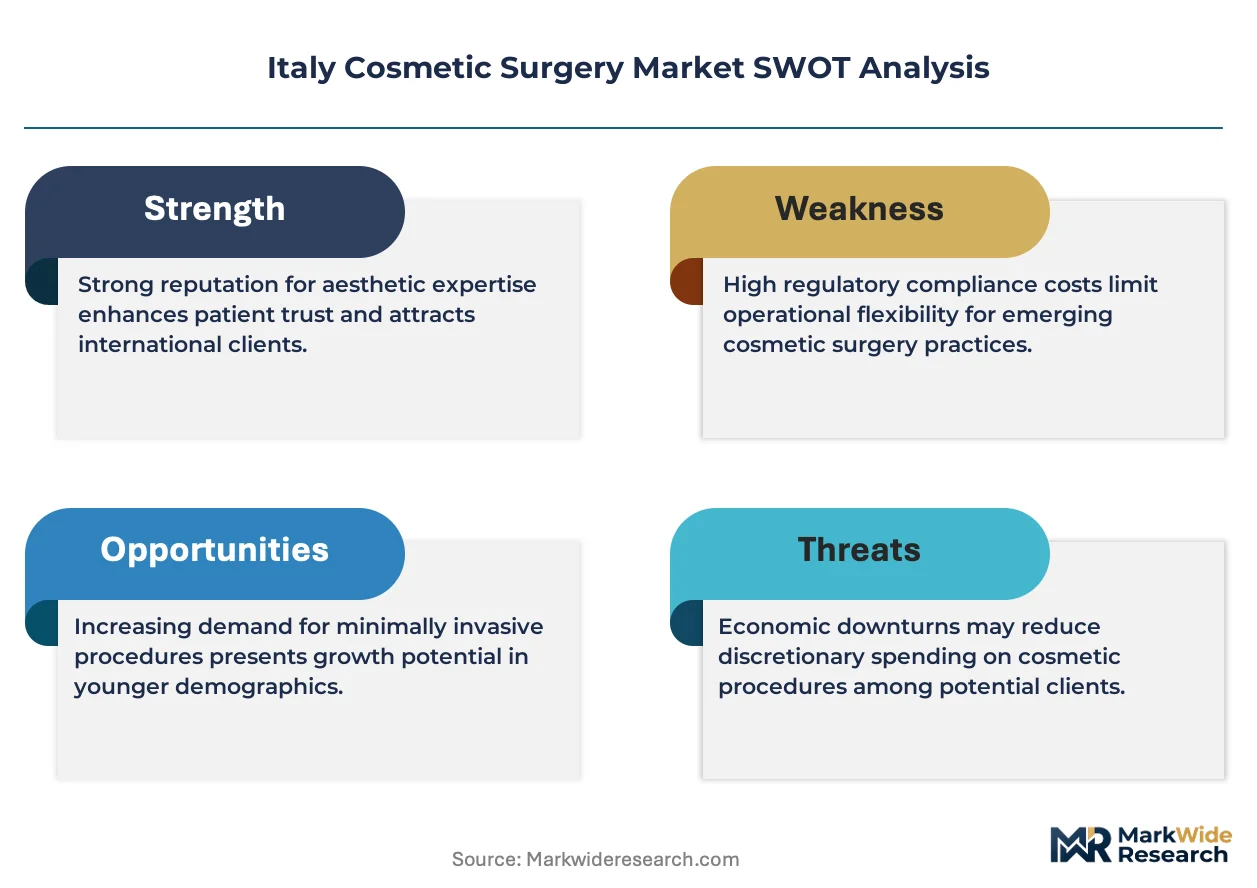
Italy's Ministry of Health enforces EU MDR compliance timelines for all marketed aesthetic devices, extending pre-market clinical evaluation requirements that delay new product introductions by 12-18 months. The Italian Medicines Agency coordinates with notified bodies to inspect manufacturing quality management systems, raising barriers for non-EU device entrants lacking ISO 13485 certification. Stakeholders must monitor how Italy's transposition of the EU AI Act into national law affects algorithmic diagnostic tools in pre-operative planning software.
Market Dynamics
Radiofrequency and ultrasound technologies are compressing traditional liposuction volumes as Milan and Rome clinics report surging male demand for non-invasive body contouring. This shift redistributes margin pools from surgical suites toward outpatient energy-based device operators.
Growth Catalysts
- EU MDR compliance timelines:Italy's Ministry of Health oversight of medical device classifications creates standardized registration pathways that reward early-certified manufacturers with faster market access.
- Male patient demographic expansion:Aesthetic clinics in Lombardy report rising demand from male patients for non-invasive body contouring procedures, opening incremental service line revenue.
- Energy-based wavelength innovation:Devices operating between 532 nm and 10,600 nm enable tissue ablation and lipolysis with reduced anesthesia requirements, expanding outpatient eligibility.
Market Restraints
- Pre-market clinical evaluation delays:EU MDR compliance extends new product introduction timelines by 12-18 months, trapping R&D capital in regulatory queues.
- ISO 13485 certification barriers:The Italian Medicines Agency's quality management system inspections raise entry costs for non-EU device manufacturers lacking established certification.
- Implant bundling margin concentration:Invasive breast augmentation retains deepest margin pools due to anesthesia fees and implant markups, limiting price flexibility for standalone device procedures.
Strategic Opportunities
- Captive aftermarket service networks:Multi-year maintenance contracts for laser device consumables and field engineering lock in recurring revenue streams.
- AI Act algorithmic tool adaptation:Italy's transposition of EU AI Act into national law creates first-mover advantage for pre-operative planning software with compliant diagnostic algorithms.
- Porta Romana medical district clustering:Private dermatology chain concentration around Milan's established hub enables shared infrastructure and referral network efficiencies.
Industry Challenges
- Notified body inspection queues:Manufacturing quality management system reviews by Italian regulators create certification bottlenecks that delay product launches.
- Proprietary handpiece replacement cycles:Fiber-optic component obsolescence forces clinic capital planning around manufacturer-controlled spare part availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Cosmetic Surgery Market |
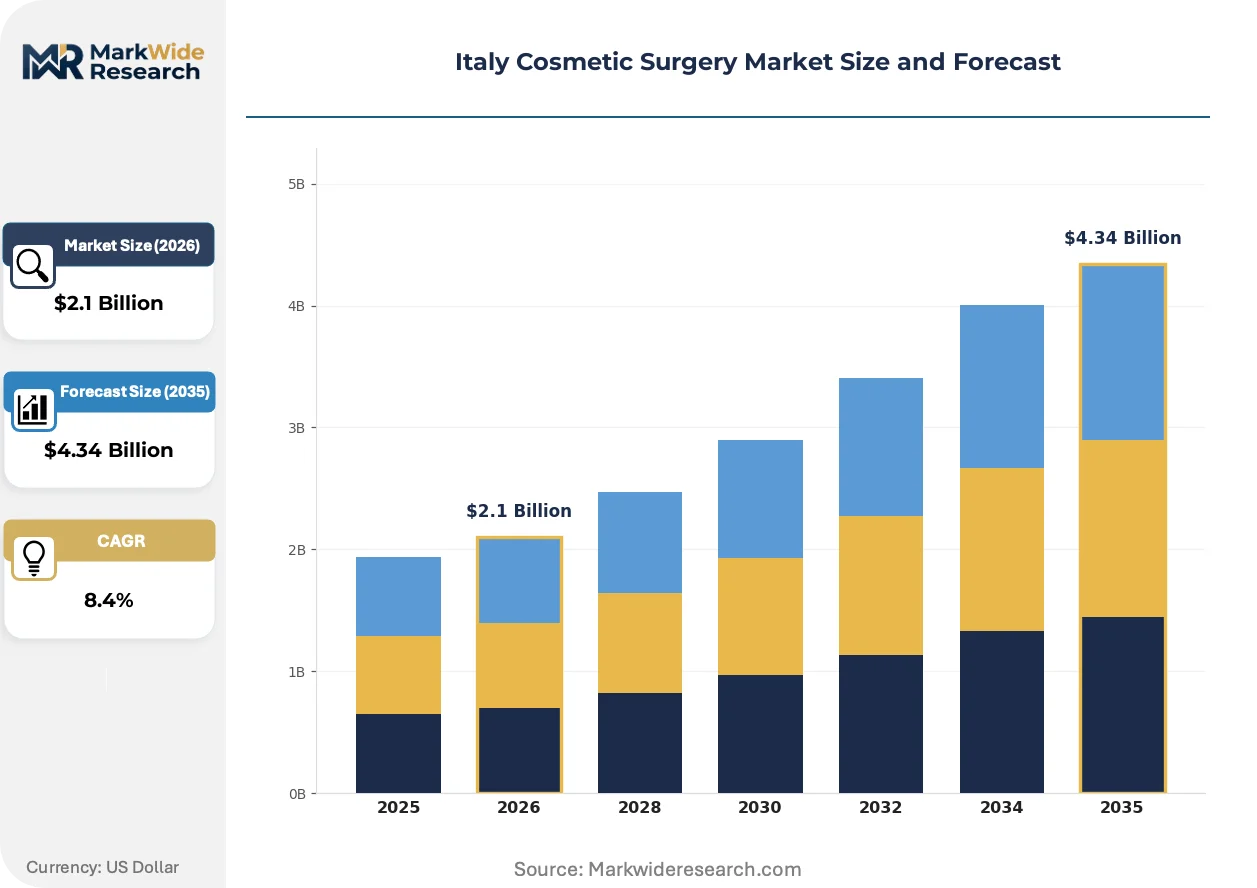
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Liposuction, Rhinoplasty, Facelift Patient Demographic: Women, Men, Teens, Seniors Service Type: Invasive, Non-Invasive, Minimally Invasive, Reconstructive Technology: Laser, Radiofrequency, Ultrasound, Fillers |
| Companies Covered | AbbVie Inc, Alma Lasers, Lumenis, El.En., Hologic Inc, Cynosure, Bausch Health Companies Inc, Candela Medical, Revance Therapeutics Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Cosmetic Surgery Market Trends and Innovations
Device functionality is fragmenting across wavelength-specific applications as clinics unbundle service lines to capture distinct patient segments. This specialization demands targeted capital deployment rather than generalist platform purchases.
Radiofrequency-assisted lipolysis is migrating from high-volume surgical centers toward boutique outpatient dermatology suites in Milan's Porta Romana district. Mid-tier clinic operators adopt these systems at twelve-month replacement cycles to maintain competitive positioning. The technology is migrating from capital-intensive hospital settings toward lower-overhead strip-mall locations, compressing per-procedure facility costs while expanding geographic accessibility.
Italy's Ministry of Health enforcement of EU MDR compliance timelines reshapes competitive entry sequencing for energy-based aesthetic devices. Pre-market clinical evaluation requirements now demand biometric outcome documentation that smaller manufacturers lack resources to generate. Northern Italian notified bodies prioritize reviews for manufacturers with existing ISO 13485 certification, advantaging established EU operators over Asian entrants.
Service contract unbundling from initial capital sales now dominates procurement negotiations between clinic chains and device vendors. Large dermatology groups in Lombardy demand separate pricing for preventive maintenance versus corrective repairs, forcing manufacturers to disclose component-level cost structures. This transparency pressure concentrates in multi-site operators with centralized procurement functions, while independent single-location practices retain bundled legacy arrangements.
Italy Cosmetic Surgery Market Segmentation
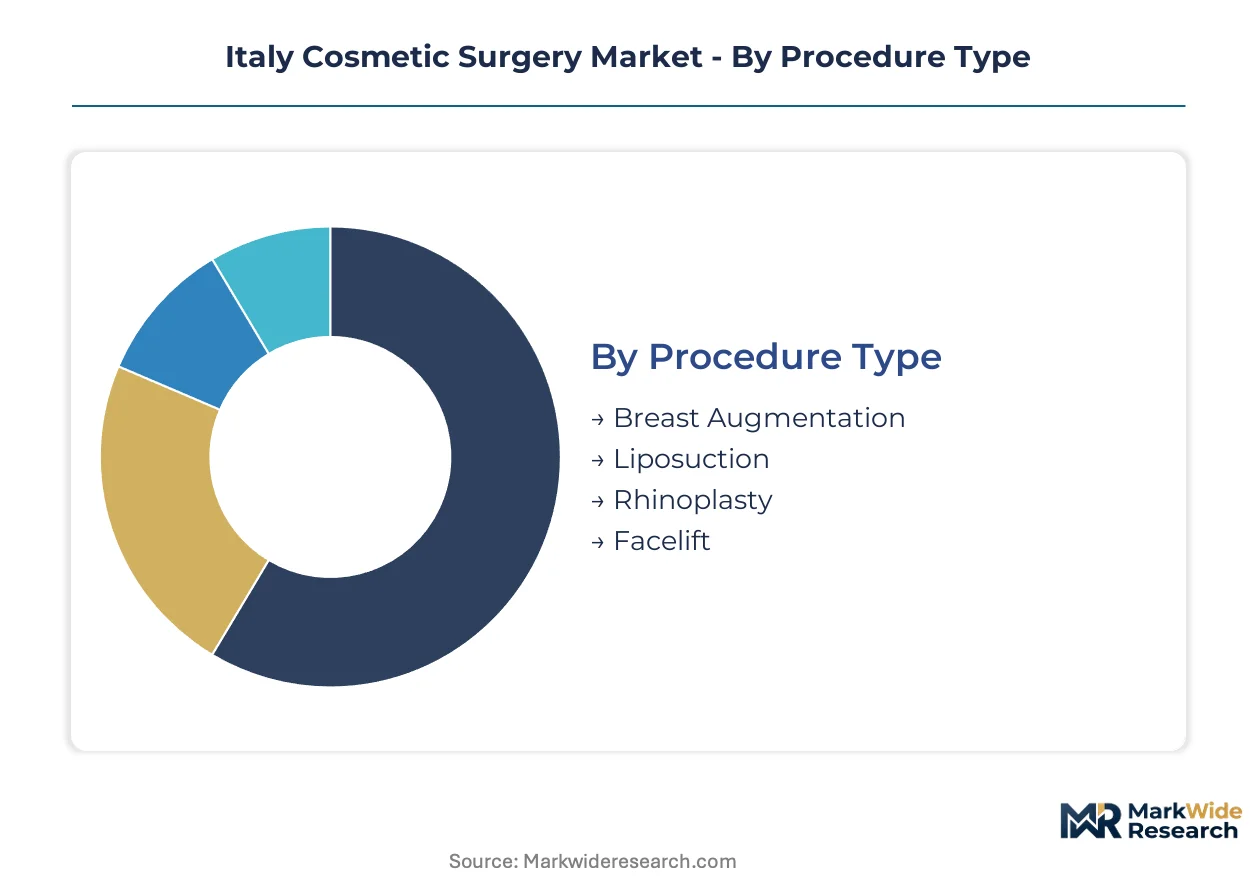
Italy's cosmetic surgery market fragments across procedure maturity, patient demographics, and technology platforms. Each segmentation axis reveals distinct margin structures, regulatory exposure, and geographic concentration patterns that reshape competitive positioning.
Procedure Type:
Mature surgical interventions anchor revenue while emerging techniques reshape volume distribution across Lombardy and Lazio.
- Breast Augmentation:Silicone and saline implant procedures command premium anesthesia fees and implant bundling margins. Demand concentrates in Milan's private surgical suites where multi-procedure packages drive patient lifetime value.
- Liposuction:Traditional suction-assisted lipectomy faces compression from energy-based alternatives. Rome clinics report declining surgical volumes as radiofrequency-assisted technologies capture body contouring preference.
- Rhinoplasty:Structural nasal reshaping retains strong demand among younger demographics seeking profile refinement.
- Facelift:Surgical facial rejuvenation maintains steady uptake among senior patient segments in northern Italy's affluent provinces.
Breast augmentation handles the majority of throughput; liposuction is the fastest mover on share as non-invasive alternatives displace surgical volumes.
Patient Demographic:
Cost tier stratification separates high-frequency maintenance patients from capital-intensive surgical candidates across Italy's regional wealth gradients.
- Women:Elective aesthetic procedures constitute the foundational revenue base. Milan and Rome clinics report sustained demand for combination treatments spanning facial and body contouring services.
- Men:Non-invasive body contouring and hair restoration are expanding most quickly. Aesthetic chains in Lombardy now dedicate dedicated consultation pathways for male patients.
- Teens:Otoplasty and rhinoplasty dominate medically supervised interventions with parental consent requirements.
- Seniors:Blepharoplasty and skin laxity treatments align with longer recovery tolerance and disposable income concentration.
Women sustain the volume base; men are climbing the fastest as stigma reduction and targeted marketing expand addressable demand.
Service Type:
Application intensity varies from capital-intensive surgical suites to high-turnover outpatient energy-device stations.
- Invasive:Surgical procedures requiring general anesthesia and hospital-grade facilities. Breast augmentation and abdominoplasty generate deepest margin pools through implant and facility fee bundling.
- Non-Invasive:Energy-based treatments without incision or anesthesia. Radiofrequency and ultrasound devices in Milan's Porta Romana district operate at twelve-month replacement cycles.
- Minimally Invasive:Injectable fillers and thread lifts bridge surgical and non-invasive categories. Outpatient dermatology chains favor these for rapid room turnover.
- Reconstructive:Post-trauma and congenital defect correction falls outside elective aesthetic margins but sustains hospital-based plastic surgery departments.
Invasive services retain margin concentration; non-invasive is gaining share fastest as device technology compresses recovery requirements.
Technology:
Supply concentration clusters around wavelength-specific device manufacturers with captive service networks.
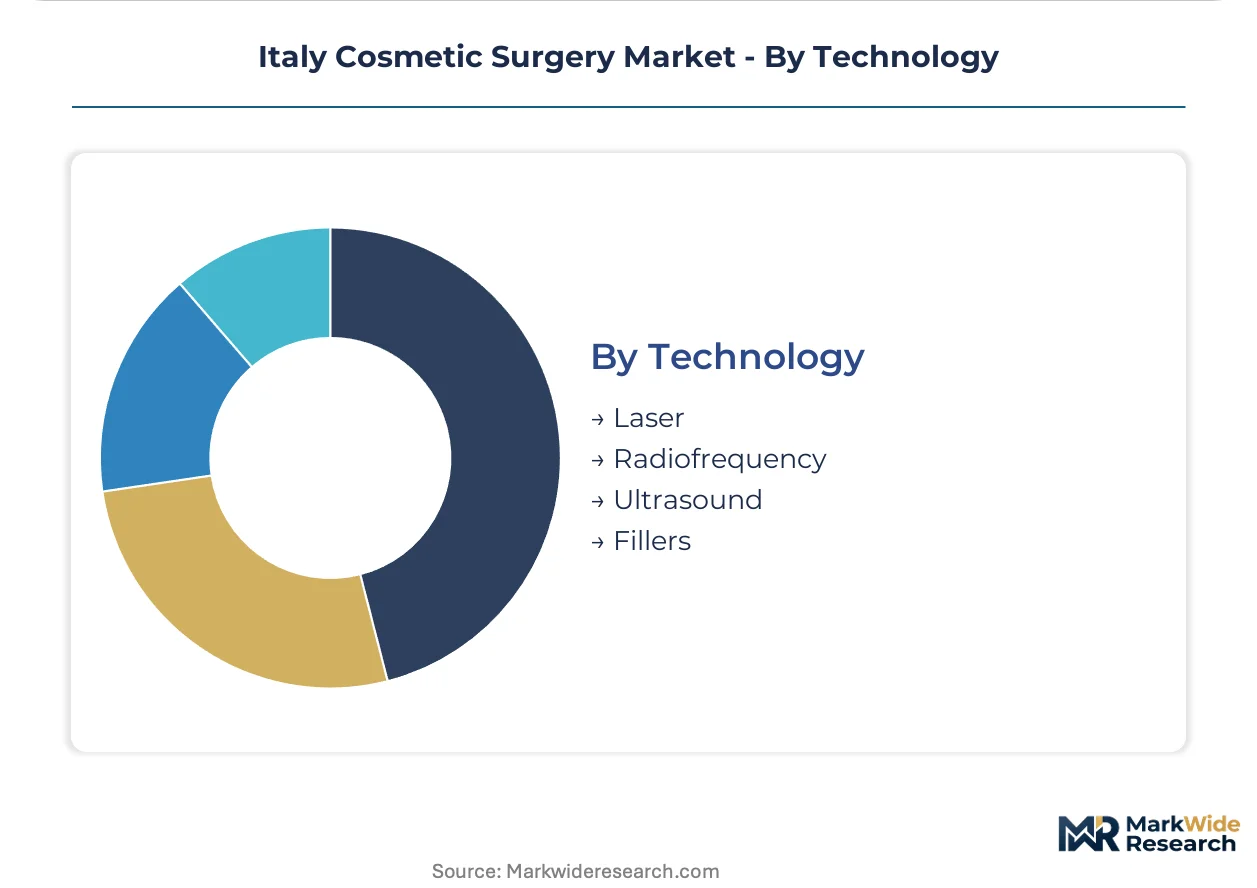
- Laser:Devices operating 532 nm to 10,600 nm enable tissue ablation and hair removal. Northern Italian clinics prioritize platforms with direct field engineering support.
- Radiofrequency:Thermal energy delivery for skin tightening and lipolysis. Rome outpatient suites adopt these systems for lower overhead operations.
- Ultrasound:Focused acoustic energy for non-invasive fat reduction. Lombardy dermatology chains report strong male patient uptake.
- Fillers:Hyaluronic acid and biostimulant injectables dominate minimally invasive volume. Italian Medicines Agency oversight of product registration shapes competitive entry sequencing.
Laser platforms anchor capital equipment sales; radiofrequency shows steepest expansion trajectory as body contouring preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity sharpens in southern provinces where disposable income lags Milan's affluent corridors, while Lombardy patients absorb premium surgical fees with minimal volume elasticity.
Lombardy
Milan's Porta Romana medical district concentrates private dermatology chains serving high-frequency aesthetic maintenance patients. Italy's Ministry of Health enforces EU MDR compliance timelines that extend device registration pathways for energy-based platforms. Alma Lasers maintains direct field engineering presence across northern Italy to secure multi-year service contracts with clinic operators.
Lazio
Rome outpatient suites report surging male demand for non-invasive body contouring as radiofrequency technologies displace traditional liposuction volumes. The Italian Medicines Agency coordinates with notified bodies to inspect manufacturing quality management systems, raising certification barriers for non-EU device entrants. Central Italy's capital city anchors reconstructive surgery departments in hospital-based plastic surgery networks.
Veneto
Padua and Verona clinics specialize in laser-based hair removal and skin resurfacing procedures targeting younger demographic segments. EU MDR pre-market clinical evaluation requirements demand biometric outcome documentation that delays new product introductions by 12-18 months. The Veneto region's medical device distribution networks prioritize platforms with established ISO 13485 certification from northern European manufacturers.
Piedmont
Turin aesthetic practices focus on minimally invasive filler injections and thread lifts for rapid room turnover in outpatient settings. Italy's transposition of the EU AI Act into national law reshapes algorithmic diagnostic tools in pre-operative planning software. The Alpine-adjacent province sustains steady demand for surgical facial rejuvenation among senior patient segments with longer recovery tolerance.
Emilia-Romagna
Bologna's university-affiliated medical centers bridge elective aesthetic services with post-trauma reconstructive procedures. The country's national pharmaceutical regulator oversees hyaluronic acid and biostimulant product registration, shaping competitive entry sequencing for injectable manufacturers. This north-central region's mixed urban-rural patient base drives pricing stratification across premium surgical suites and economy-tier dermatology clinics.
Italy Cosmetic Surgery Market Competitive Landscape
Integrated device manufacturers and specialized energy-platform vendors split the market between captive aftermarket revenue streams and flexible procurement relationships. The vendor base clusters around wavelength-specific technology portfolios with divergent service contract strategies. Three archetypes dominate: laser-platform incumbents with direct field engineering networks, radiofrequency specialists bundling preventive maintenance into capital sales, and filler-product houses leveraging pharmaceutical distribution channels. Competitive moves concentrate on multi-year service contract lock-in and ISO 13485 certification acceleration to exploit EU MDR compliance bottlenecks.
Among Israel-based laser manufacturers, Alma Lasers and Lumenis occupy positions exemplifying the integrated-platform archetype with northern Italian service presence. El.En., the Florence-listed industrial group, represents European-origin energy-device fabrication with proprietary component replacement cycles. Candela Medical anchors the US-origin tier competing through bundled maintenance offerings. These three entities illustrate the geographic and strategic segmentation pressuring mid-tier operators without captive aftermarket networks.
| Leading Market Players |
|---|
| AbbVie Inc |
| Alma Lasers |
| Lumenis |
| El.En. |
| Hologic Inc |
| Cynosure |
| Bausch Health Companies Inc |
| Candela Medical |
| Revance Therapeutics Inc |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in ISO 13485-certified manufacturing facilities across northern Italy tightens supplier leverage while compressing procurement timelines for energy-based aesthetic device operators. This utilization squeeze forces clinic chains to accept longer lead times for fiber-optic handpiece replacements and lock in multi-year service contracts to secure aftermarket priority.
Pricing Analysis
Aftermarket service revenue tiers—spanning preventive maintenance contracts, corrective repair dispatch, and consumable replenishment—drive lifetime value capture for laser and radiofrequency device manufacturers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and field engineering proximity, with Milan's Porta Romana clinics absorbing premium rates for same-day technician response. Cost compression in mid-tier device segments intensifies as Asian manufacturers without EU MDR certification compete on capital equipment list prices, though they cannot match captive service network coverage. Independent single-location practices exhibit highest price sensitivity, while multi-site dermatology chains leverage centralized procurement to demand unbundled component-level cost disclosure.
Supply Chain Analysis
Upstream feedstock for solid-state laser resonators and radiofrequency generators draws from specialized semiconductor fabrication in Germany, Israel, and the United States. Optical-grade sapphire crystals, fiber-optic cables, and precision-machined handpiece housings constitute critical component dependencies. Single-source vulnerability concentrates in erbium-doped fiber suppliers serving aesthetic laser manufacturers, with regulatory restriction risk escalating as EU MDR clinical evaluation documentation requirements delay alternative vendor qualification. Distribution runs through authorized medical device distributors maintaining temperature-controlled logistics networks and notified body audit trails for traceability compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in Italy's cosmetic surgery market are inflecting toward interoperability between energy-based devices and pre-operative planning software, as EU AI Act compliance creates ecosystem lock-in opportunities for integrated vendors.
For Market Incumbents: Entrench captive aftermarket revenue by extending proprietary handpiece replacement cycles and embedding preventive maintenance into multi-year capital leases. ISO 13485 certification acceleration at northern Italian notified bodies creates regulatory moats against emerging Asian device entrants lacking clinical evaluation resources. Direct field engineering presence across Lombardy reinforces service contract renewal rates.
For New Entrants and Emerging Players: Establish a beachhead in male-focused non-invasive body contouring segments where stigma reduction and targeted marketing have expanded addressable demand faster than incumbent service line adaptation. Rome outpatient suites and secondary cities in Emilia-Romagna present penetrable geography with less concentration of established dermatology chains. Go-to-market through independent clinic partnerships avoids head-to-head procurement battles with centralized Lombardy purchasing committees.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across radiofrequency and ultrasound device manufacturing as modular platform architectures reduce per-SKU tooling requirements. Long-term viability favors acquirers of mid-tier operators with established ISO 13485 quality systems and existing notified body relationships, positioned to exploit EU MDR compliance bottlenecks. Signal to watch: notified body inspection queue lengths for new product introductions, which indicate regulatory capacity constraints and first-mover advantage windows.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Early-certified manufacturers gain 12-18 month market access advantages over competitors trapped in clinical evaluation queues. |
| Captive Aftermarket Service Network Expansion | Multi-year maintenance contracts for laser consumables lock in recurring revenue streams that exceed initial capital equipment margins. |
| AI Act Compliant Pre-Operative Software Development | Algorithmic diagnostic tools with embedded regulatory compliance create ecosystem stickiness and platform switching costs. |
| ISO 13485 Quality System Investment | Manufacturers with established certification receive priority review from northern Italian notified bodies, accelerating product launches. |
| Male Patient Consultation Pathway Creation | Dedicated service lines for non-invasive body contouring capture fastest-expanding demographic segment with minimal competitive saturation. |
Research Methodology
A standing panel of aesthetic clinic operators, biomedical equipment procurement managers, notified body auditors, and energy-device field engineers provided ongoing calibration across primary interview rounds. Secondary validation drew from EU MDR submission databases, Italian Medicines Agency inspection records, hospital procurement contract registries, and medical device trade flow statistics. Bottom-up procedure volume estimates from Lombardy and Lazio clinic networks triangulated against top-down capital equipment shipment data from northern Italian distributors.
Scenario-bracketing framed analytical projections across the analysis window, with segmentation dimensions spanning procedure type, patient demographic, service intensity, and technology platform. CAGRs derived from weighted average of historical procedure volume trajectories, replacement cycle acceleration patterns, and regulatory timeline elasticity factors. Forecast inputs incorporated EU AI Act transposition timing uncertainty and notified body inspection capacity constraints specific to aesthetic device categories.
Sensitivities concentrate around EU MDR compliance timeline extensions, notified body inspection queue bottlenecks, and algorithmic diagnostic tool regulatory classification shifts. Cross-checking against Italian Medicines Agency published guidance documents and EUDAMED database entry rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market