
 Mexico Cosmetic Surgery Market | 2026-2036
Mexico Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Cosmetic Surgery Market Insights
COFEPRIS sanitary registration for silicone breast implants is collapsing the field of authorized suppliers, forcing clinics to consolidate procurement around validated manufacturers. VIDA Wellness and Beauty leverages its Tijuana location to sustain cross-border patient volumes from California. Mexico Cosmetic Center anchors its model on package pricing that bundles lodging, surgery, and aftercare. Dr. Miguel Rodríguez Salinas competes through subspecialty focus in body contouring procedures.
Cosmetic surgery encompasses elective procedures that modify aesthetic appearance through surgical incision, tissue manipulation, or injectable augmentation, typically performed under local or general anesthesia with recovery protocols spanning days to weeks. The discipline serves both reconstructive correction and purely aesthetic enhancement objectives, with outcomes measured by symmetry restoration, proportion improvement, or age-related change reversal. Breast augmentation and liposuction dominate procedure volume, while non-invasive categories including laser treatments and injection techniques capture expanding margin pools as downtime-averse patients shift preferences. Medical tourism as an end-user channel outpaces domestic aesthetic clinic growth, driven by cost differentials that attract North American patients seeking accredited outcomes at reduced expenditure.
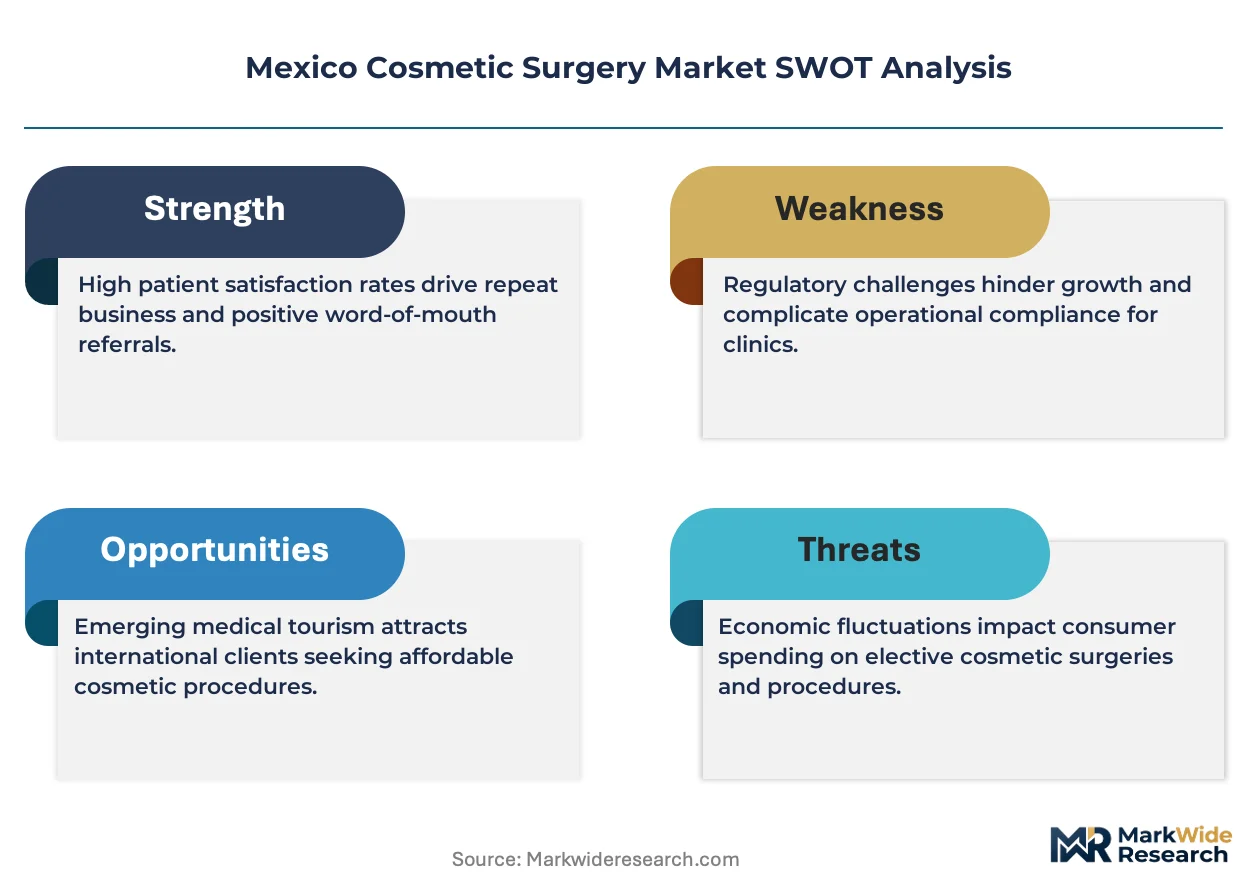
COFEPRIS maintains device safety oversight through premarket approval pathways for implants and dermal fillers, while the Mexican Ministry of Health enforces clinic licensing standards that differentiate legal operators from informal providers. State-level health secretariats in Baja California and Jalisco supplement federal rules with facility inspection regimes that affect market access in high-volume corridors. Stakeholders must monitor whether COFEPRIS accelerates equivalence agreements with FDA or Health Canada to streamline device approvals, as this regulatory alignment would reshape competitive dynamics for imported materials and clinic certification costs.
Market Dynamics
COFEPRIS sanitary registration requirements for silicone breast implants are compressing the supplier base, forcing clinics to consolidate procurement around validated manufacturers and reshaping competitive positioning across Tijuana, Guadalajara, and Mexico City corridors.
Growth Catalysts
- Medical tourism flows:Cost differentials attract North American patients from California and Texas seeking accredited outcomes at reduced expenditure, anchoring patient volume growth in Baja California border clinics.
- COFEPRIS equivalence pathway:Potential alignment with FDA or Health Canada approval standards would streamline device import timelines and reduce clinic certification burdens for imported materials.
- Non-invasive category expansion:Laser treatments and injection techniques capture margin pools as downtime-averse patients shift preferences away from surgical recovery protocols.
Market Restraints
- Implant supply concentration:Collapsing field of COFEPRIS-authorized silicone breast implant suppliers limits procurement flexibility and creates dependency risk on validated manufacturers.
- State-level inspection regimes:Baja California and Jalisco health secretariats impose facility inspection standards that increase compliance costs and filter market access in high-volume corridors.
- Informal provider competition:Unlicensed operators undercut accredited clinic pricing, eroding patient trust and complicating quality differentiation efforts.
Strategic Opportunities
- Package pricing innovation:Bundled offerings combining lodging, surgery, and aftercare create service differentiation and capture extended patient value chains.
- Subspecialty body contouring:Focused expertise in high-complexity procedures builds referral networks and defends margin position against generalist competitors.
- Cross-border logistics integration:Dedicated patient transport and accommodation infrastructure strengthens California corridor capture and reduces friction in international patient onboarding.
Industry Challenges
- COFEPRIS registration timelines:Premarket approval pathways for dermal fillers and implantable devices extend product launch cycles and tie up working capital.
- Accreditation maintenance costs:Federal clinic licensing standards and state-level inspection requirements demand continuous facility investment and administrative overhead.
- Aftercare coordination complexity:International patient recovery monitoring across jurisdictions strains follow-up protocols and liability management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Cosmetic Surgery Market |
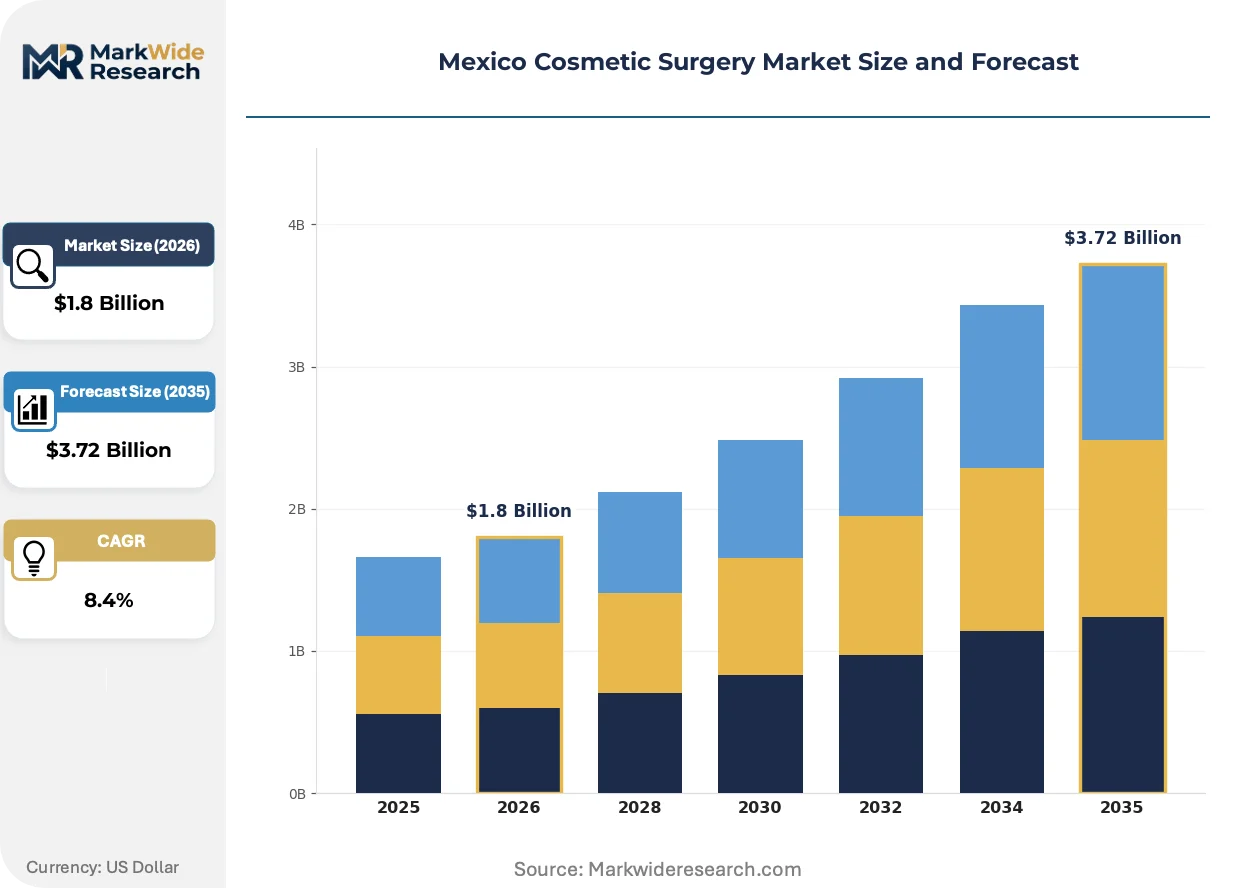
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Liposuction, Rhinoplasty, Tummy Tuck End User: Aesthetic Clinics, Hospitals, Private Practices, Medical Tourism Service Type: Invasive Surgery, Non-Invasive Procedures, Consultations, Aftercare Technique: Open Surgery, Endoscopic, Injection Techniques, Laser Treatments |
| Companies Covered | My Best Body Ever, VIDA Wellness and Beauty, Mexico Cosmetic Center, Dr. Miguel Rodríguez Salinas, Vive Plastic Surgery, Dr. Christian Morales Clinic, Plastica Tijuana, Blackstones Plastic Surgery, Plastic Surgery Riviera, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Cosmetic Surgery Market Trends and Innovations
Technological convergence in aesthetic devices, evolving COFEPRIS oversight frameworks, and shifting patient preferences toward minimal-downtime procedures are restructuring how value is created and captured across Mexican cosmetic surgery markets.
Radiofrequency-assisted lipolysis systems are fragmenting traditional liposuction market share by enabling tissue tightening concurrent with fat reduction. High-volume Tijuana clinics adopt these platforms to differentiate body contouring offerings and reduce patient recovery timelines. The technology is fragmenting procedure economics by compressing operative time while expanding treatable patient segments previously excluded from surgical candidacy.
COFEPRIS maintains premarket approval pathways for implantable devices that exceed FDA 510(k) equivalence thresholds in documentation requirements. This regulatory friction delays market entry for novel implant technologies and advantages incumbent suppliers with established registration portfolios. Baja California clinics respond by deepening relationships with validated manufacturers rather than diversifying supplier bases.
Patient research behavior has migrated to social media validation and direct-to-clinic digital inquiry, displacing traditional medical tourism broker intermediaries. California-based prospective patients now initiate contact through Instagram and TikTok discovery before engaging formal consultation channels. This channel shift concentrates marketing investment requirements on content production and influencer partnerships rather than broker commission structures.
Mexico Cosmetic Surgery Market Segmentation
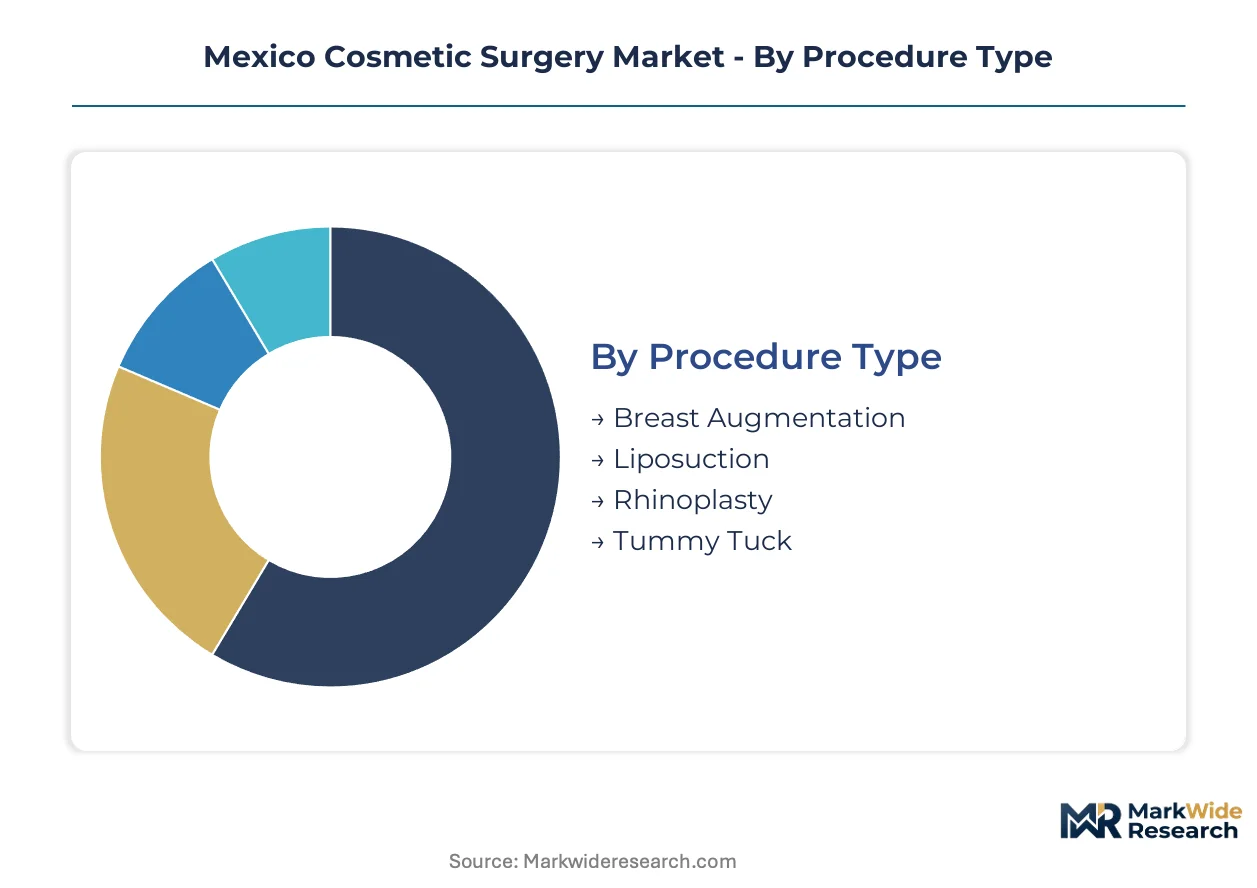
COFEPRIS regulatory pathways differentiate how each segment accesses device approvals and clinic licensing, creating divergent competitive barriers across procedure categories. Segmentation reveals where cost arbitrage, technology substitution, and patient acquisition channels concentrate value capture.
Procedure Type:
COFEPRIS sanitary registration requirements for silicone implants create asymmetric compliance burdens that reshape competitive positioning across surgical categories.
- Breast Augmentation:Silicone and saline implant procedures dominate revenue concentration in Tijuana and Guadalajara corridors. COFEPRIS-authorized supplier consolidation forces clinics into exclusive procurement relationships with validated manufacturers, compressing margin flexibility.
- Liposuction:Fat removal techniques span traditional suction-assisted methods through radiofrequency-assisted platforms. Baja California clinics adopt energy-based systems to reduce operative time and expand treatable patient segments previously excluded from surgical candidacy.
- Rhinoplasty:Nasal reshaping procedures command premium pricing in Mexico City aesthetic practices.
- Tummy Tuck:Abdominoplasty addresses post-weight loss skin laxity, with demand concentrated among medical tourism patients from Texas and California.
Established volume favors breast augmentation; emerging adoption favors liposuction as energy-based platforms expand treatable populations.
End User:
Patient acquisition economics vary sharply across institutional settings, with cross-border logistics integration determining competitive viability in the California corridor.
- Aesthetic Clinics:Dedicated cosmetic facilities anchor procedure volume in Tijuana, Guadalajara, and Mexico City. These operators leverage package pricing bundling lodging, surgery, and aftercare to capture extended patient value chains and differentiate against hospital competitors.
- Medical Tourism:International patient channels outpace domestic clinic growth, driven by cost differentials attracting North American patients seeking accredited outcomes at reduced expenditure. California-based prospective patients now initiate contact through social media discovery before engaging formal consultation channels.
- Hospitals:General medical institutions with cosmetic surgery departments compete on emergency backup capacity.
- Private Practices:Solo practitioner models concentrate in Mexico City and Monterrey metropolitan areas.
Patient flow concentrates in aesthetic clinics; margin expansion concentrates in medical tourism channels with integrated cross-border logistics.
Service Type:
Recovery timeline preferences are displacing surgical volume toward minimal-downtime alternatives, restructuring how value is created across service categories.
- Invasive Surgery:Procedures requiring general anesthesia and incision-based tissue manipulation deliver durable structural outcomes. These services face margin pressure as downtime-averse patients shift preferences toward alternatives with abbreviated recovery protocols.
- Non-Invasive Procedures:Laser treatments and injection techniques capture expanding margin pools as patient preferences migrate away from surgical recovery. Radiofrequency platforms and dermal filler applications enable repeat visit economics and lower liability exposure.
- Consultations:Digital inquiry and remote assessment protocols now precede in-person surgical evaluation.
- Aftercare:Recovery monitoring services strain operational capacity for international patient cohorts.
Revenue concentration remains with invasive surgery; steepest expansion trajectory belongs to non-invasive procedures capturing preference shifts.
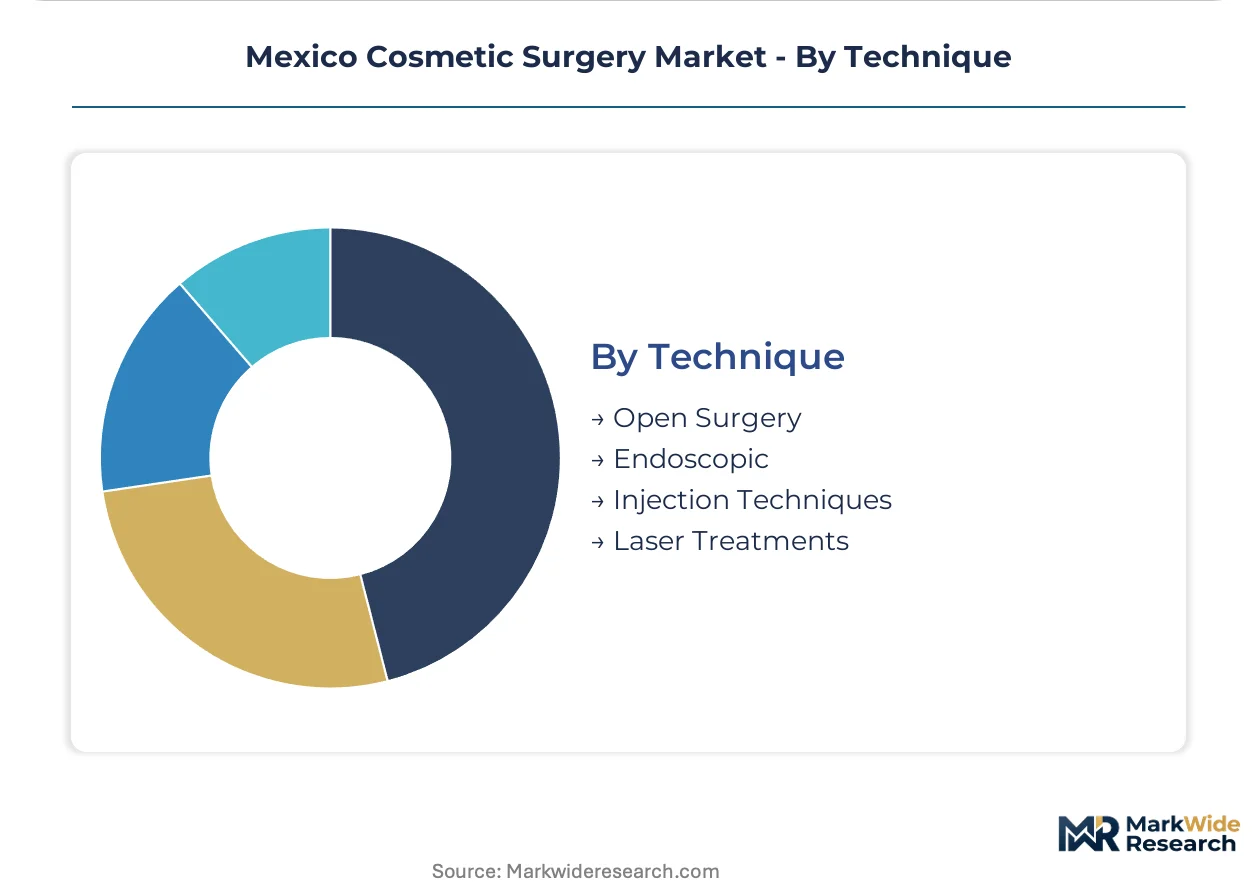
Technique:
Technology adoption patterns fragment competitive positioning, with platform investment requirements filtering market access in high-volume corridors.
- Injection Techniques:Dermal filler and neurotoxin applications deliver volume augmentation without operative intervention. COFEPRIS premarket approval pathways for these devices exceed FDA equivalence thresholds, delaying market entry for novel formulations and advantaging incumbent suppliers.
- Laser Treatments:Energy-based platforms address skin resurfacing, hair removal, and pigment correction with minimal recovery requirements. Jalisco and Baja California clinics deploy these systems to differentiate service menus and capture repeat visit revenue.
- Open Surgery:Traditional incision-based methods persist for complex reconstructive cases.
- Endoscopic:Minimally invasive camera-assisted techniques reduce scarring in select applications.
Clinical investment concentrates on laser platforms; patient preference migration favors injection techniques for maintenance-oriented aesthetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Ysidro Port of Entry processes thousands of daily northbound crossings, anchoring Tijuana's medical tourism corridor to Southern California's insured patient base. This infrastructure underwrites Mexico's position as the dominant destination for cost-sensitive cosmetic surgery demand from the United States.
Mexico City Metro
Domestic aesthetic demand concentrates in the capital's affluent neighborhoods, driven by upper-middle-class professionals seeking rhinoplasty and facial rejuvenation. COFEPRIS federal oversight operates from headquarters here, streamlining device registration for clinics in the metropolitan zone. Polanco and Santa Fe districts host premium practices that command pricing multiples above border competitors.
Baja California
Cross-border patient flows from California and Arizona sustain procedure volume in Tijuana and Mexicali clinics. The state health secretariat imposes facility inspection standards that filter informal operators from accredited providers. Zona Río medical complexes integrate with San Diego airport logistics, reducing friction for international patient onboarding.
Jalisco
Guadalajara anchors central Mexico's cosmetic surgery cluster, drawing domestic patients from Michoacán and Colima. State-level accreditation requirements supplement federal COFEPRIS licensing, elevating compliance costs for new market entrants. Providencia and Chapultepec corridors concentrate high-volume aesthetic clinics with package pricing models.
Nuevo León
Monterrey's industrial wealth generates robust domestic demand for body contouring and breast procedures. The state's health secretariat enforces clinic infrastructure standards that exceed federal minimums, creating quality differentiation against informal competitors. San Pedro Garza García hosts subspecialty practices serving Mexico's highest-income households.
Mexico Cosmetic Surgery Market Competitive Landscape
Listed leaders compete with private specialists across accreditation tiers, producing a bifurcated structure where COFEPRIS-certified chains capture medical tourism flows while solo practitioners serve domestic niches. The market fragments across three archetypes: border-integrated package providers, metropolitan subspecialty clinics, and informal operators competing on price. Consolidation pressure favors entities with cross-border logistics infrastructure and validated device procurement relationships. Competitive moves concentrate on package pricing innovation and California corridor patient acquisition systems.
Among border-integrated providers, VIDA Wellness and Beauty exemplifies the Tijuana-based model leveraging proximity to San Diego for patient volume capture. Mexico Cosmetic Center occupies a position within the package-pricing archetype, bundling lodging and surgical services for international cohorts. Dr. Miguel Rodríguez Salinas represents the subspecialty tier, anchoring competitive positioning in body contouring expertise rather than geographic arbitrage.
| Leading Market Players |
|---|
| My Best Body Ever |
| VIDA Wellness and Beauty |
| Mexico Cosmetic Center |
| Dr. Miguel Rodríguez Salinas |
| Vive Plastic Surgery |
| Dr. Christian Morales Clinic |
| Plastica Tijuana |
| Blackstones Plastic Surgery |
| Plastic Surgery Riviera |
| Others |
Pricing and Supply Chain Analysis
Package pricing contracts for medical tourism patients lock in bundled surgery, lodging, and aftercare costs while securing clinic occupancy and device procurement commitments across COFEPRIS-authorized supply channels. These arrangements anchor price visibility for Tijuana and Guadalajara operators serving California corridor demand.
Pricing Analysis
Certification level (COFEPRIS/FDA-grade) creates the primary spread between premium metropolitan practices and border package providers. Three-tier pricing structure across premium, standard, and economy levels segments patients by aftercare inclusion and implant manufacturer tier. Cost compression in economy-tier breast augmentation intensifies because informal competitors undercut accredited clinic pricing. Medical tourism channels show highest price sensitivity; domestic Mexico City patients demonstrate lowest sensitivity to premium positioning.
Supply Chain Analysis
Port congestion at Long Beach and container availability constraints on Asia-Pacific trade lanes extend lead times for Korean-manufactured radiofrequency lipolysis platforms and German laser systems. Device procurement draws from the United States, South Korea, and Germany for energy-based platforms; silicone implant supply rests on validated COFEPRIS-registered manufacturers in the United States and Brazil. Single-source vulnerability concentrates in FDA-approved implant suppliers pending equivalence pathway acceleration. Distribution runs through manufacturer-direct relationships with high-volume Tijuana and Guadalajara clinic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward medical tourism aggregators and social media-influenced patient decision-making, fragmenting traditional broker intermediaries and compressing clinic commission structures.
For Market Incumbents: Fortify cross-border logistics infrastructure with dedicated San Diego airport transport and recovery housing to defend patient capture against emerging package providers. Deepen backward integration into COFEPRIS-authorized implant procurement through exclusive manufacturer relationships, reducing substitution risk from radiofrequency-assisted lipolysis platforms. For New Entrants and Emerging Players: Aftercare coordination gaps for international patients present entry points for specialized recovery monitoring services and liability management platforms. Monterrey and Guadalajara domestic segments offer most penetrable white space with lower compliance intensity than Baja California corridors. Digital-first patient acquisition through TikTok and Instagram content partnerships bypasses traditional broker economics. For Investors and Strategic Acquirers: Subspecialty body contouring practices with established referral networks and validated COFEPRIS device portfolios represent priority acquisition targets for platform consolidation plays. Long-term viability hinges on regulatory alignment between COFEPRIS and FDA accelerating device approval timelines. Watch for equivalence pathway announcements as inflection signals for implant supplier valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS-FDA Equivalence Pathway Pursuit | Streamlines silicone implant import timelines and reduces clinic certification burdens for cross-border device procurement. |
| Package Pricing Model Expansion | Bundles Tijuana lodging, surgery, and aftercare to capture extended patient value chains and differentiate against hospital competitors. |
| Social Media Patient Acquisition Infrastructure | Replaces traditional medical tourism broker intermediaries with Instagram and TikTok content production and influencer partnerships. |
| Radiofrequency Platform Adoption | Reduces operative time and expands treatable patient segments previously excluded from traditional liposuction candidacy. |
| Subspecialty Body Contouring Focus | Builds referral networks and defends margin position against generalist competitors through high-complexity procedure expertise. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with clinic operators, COFEPRIS regulatory consultants, medical tourism coordinators, and implant manufacturer distribution managers; and secondary validation through COFEPRIS registration databases, Baja California and Jalisco health secretariat inspection records, and cross-border patient flow estimates. Bottom-up clinic capacity modeling and top-down medical tourism expenditure triangulation anchored market sizing.
Across the analysis window, projections incorporate procedure volume trends by technique category, patient origin segmentation, and service type mix shifts. CAGRs derive from regression analysis of historical clinic expansion rates and medical tourism flow correlations with California healthcare cost indices. Modeled inputs include COFEPRIS approval timeline assumptions and social media channel migration effects on patient acquisition costs.
Underlying assumptions cover regulatory stability in COFEPRIS oversight frameworks and sustained cost differentials attracting North American patients, with deviation risk concentrated in equivalence pathway delays and informal provider quality incidents eroding destination trust. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
France Cosmetic Surgery Market