
 Global Dental Lasers Market | 2026-2036
Global Dental Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dental Lasers Market Analysis
Germany is rewriting the competitive map for precision dental equipment as Bavarian manufacturing clusters attract laser subsystem suppliers. BIOLASE, Inc. leverages its diode platform specialization to anchor North American clinic penetration. Fotona sustains European market presence through Er:YAG and Nd:YAG dual-wavelength architectures. Dentsply Sirona Inc. dominates chairside integration by bundling laser modules with digital imaging workflows.
Dental lasers are solid-state or gas-based electromagnetic devices emitting coherent light at specific wavelengths—typically 2940 nm for Er:YAG or 1064 nm for Nd:YAG—to enable tissue ablation with minimal thermal collateral damage. These instruments serve periodontal debridement, caries removal, and soft-tissue contouring with micron-level precision. Diode lasers occupy the highest volume tier due to compact footprint and cost accessibility for general practitioners. Er:YAG platforms command premium positioning in hard-tissue applications where water-cooled interaction minimizes patient trauma. Application segmentation shows soft tissue surgery generating recurring consumable revenue while teeth whitening drives patient-facing cosmetic demand.
FDA 510(k) clearance pathways govern US commercialization timelines for new laser wavelengths, while EU MDR technical documentation requirements extend certification cycles for imported devices. Japan's PMDA enforces JIS-compatible electromagnetic compatibility standards that filter non-compliant entrants from its clinic procurement channels. Stakeholders must track harmonization gaps between FDA predicate device rules and EU clinical evidence expectations as dual-market registration costs reshape vendor prioritization.
Market Dynamics
Dual-wavelength Er:YAG and Nd:YAG architectures are compressing treatment times while EU MDR technical documentation requirements extend certification cycles for subsystem suppliers. Bavarian manufacturing clusters concentrate precision optics sourcing, reshaping vendor prioritization across clinic procurement channels.
Growth Catalysts
- EU MDR compliance mandates:Orthodontic clinics in Germany drive replacement demand for predicate-certified devices, accelerating platform upgrades across Bavaria's dental corridor.
- Japan's precision manufacturing ecosystem:Er:YAG wavelength platforms concentrate demand in Osaka-Tokyo corridor clinics, filtering non-JIS-compliant entrants from procurement channels.
- Diode laser miniaturization:Compact footprint specifications enable general practitioner adoption in North American solo practices previously excluded from laser-assisted procedures.
Market Restraints
- Ytterbium-doped fiber input concentration:German and Japanese suppliers dominate rare-earth dopant refining, exposing device manufacturers to supply interruption risks.
- FDA 510(k) predicate pathway rigidity:Novel wavelength submissions without established predicates face extended review timelines, delaying US commercialization.
- Conventional mechanical instrumentation substitution:High-speed handpieces retain cost advantage in emerging-market price-sensitive procurement segments.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract laser subsystem assembly investments targeting price-accessible diode platforms.
- Tele-dentistry workflow integration:Remote consultation platforms create demand for portable laser units with cloud-connected treatment logging capabilities.
- Hard-tissue application expansion:Caries removal protocols in pediatric dentistry open volume tiers beyond traditional soft-tissue contouring revenue pools.
Industry Challenges
- Laser safety officer certification scarcity:Clinic staff require ANSI Z136.3-compliant training programs, constraining rollout velocity in multi-site dental service organizations.
- Legacy digital imaging incompatibility:Chairside integration demands API development between proprietary laser control software and existing practice management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dental Lasers Market |
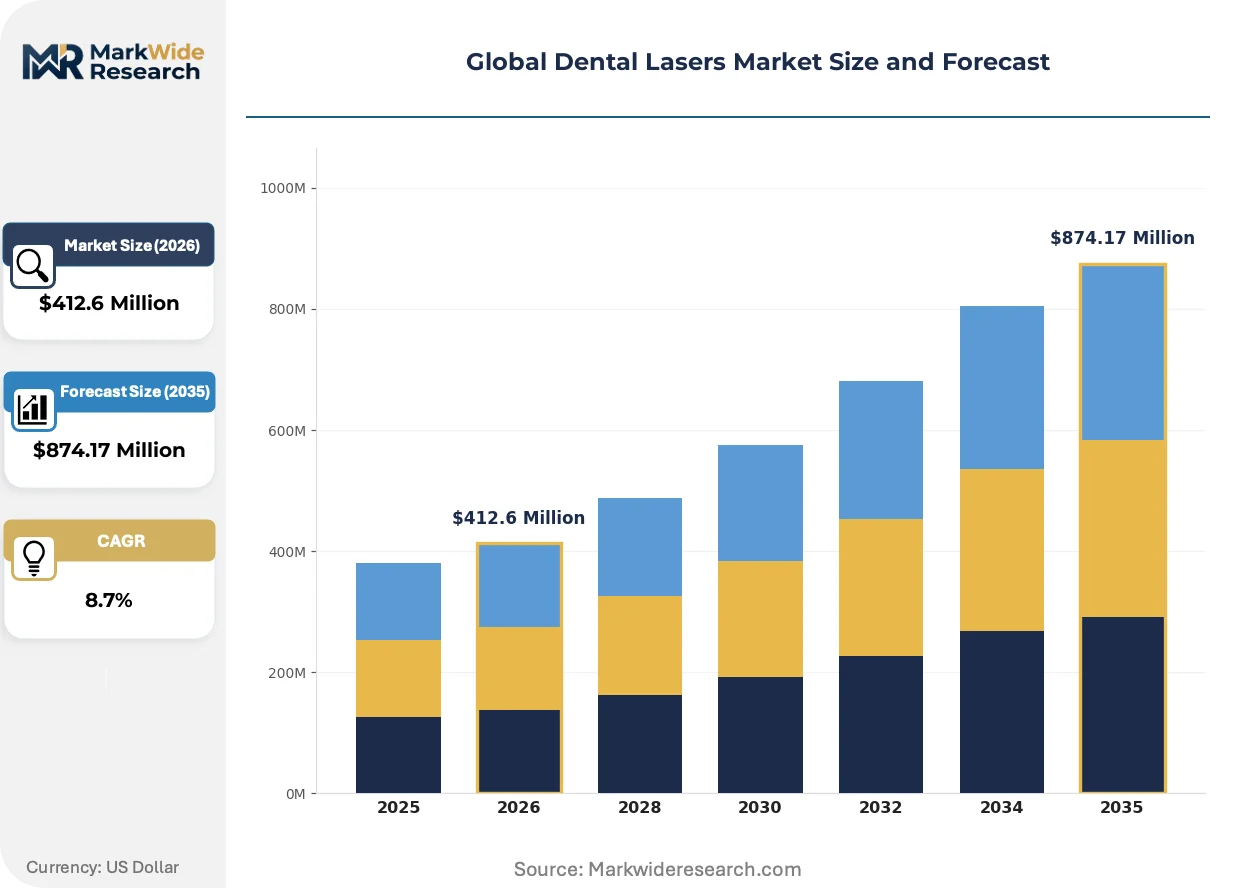
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dioded Lasers, Nd:YAG Lasers, Er:YAG Lasers, CO2 Lasers Application: Periodontal Treatment, Teeth Whitening, Oral Surgery, Soft Tissue Surgery End User: Dental Clinics, Hospitals, Academic Institutions, Research Laboratories Technology: Solid State, Fiber Optic, Diode, Gas |
| Companies Covered | BIOLASE, Inc., Fotona, Dentsply Sirona Inc., Convergent Dental, AMD Lasers, CAO Group, Inc., Gigaalaser Group, IPG Photonics Corp., J. Morita Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dental Lasers Market Emerging Trajectories
Photonic integration and regulatory harmonization pressures are compressing product development cycles while fragmenting procurement authority across clinic networks. These forces reshape competitive positioning through technical differentiation rather than geographic expansion alone.
Supercontinuum fiber laser sources are collapsing the distinction between soft-tissue and hard-tissue platforms by delivering tunable wavelength output from single resonator cavities. Multi-specialty dental service organizations in the United States pilot these systems to consolidate capital expenditure across periodontal and restorative departments. The technology is collapsing premium pricing tiers previously separated by dedicated Er:YAG versus diode product lines.
EU MDR Annex I general safety and performance requirements now mandate clinical evidence documentation for laser-tissue interaction parameters that 510(k) predicate rules historically treated as substantially equivalent. German notified bodies enforce stricter biocompatibility testing for fiber optic delivery handpieces, extending certification timelines for Asian subsystem suppliers. Hard-tissue application segments face the steepest compliance cost escalation as clinical study designs must demonstrate thermal damage thresholds.
Subscription-based equipment access models displace outright purchase arrangements in North American dental service organizations seeking to transfer obsolescence risk to manufacturers. Per-procedure consumable bundling replaces capital-heavy balance sheet commitments, particularly for cosmetic whitening applications with high patient turnover. This shift concentrates most visibly in California and Texas multi-clinic networks where equipment financing costs exceed labor expenditure ratios.
Global Dental Lasers Market Segmentation
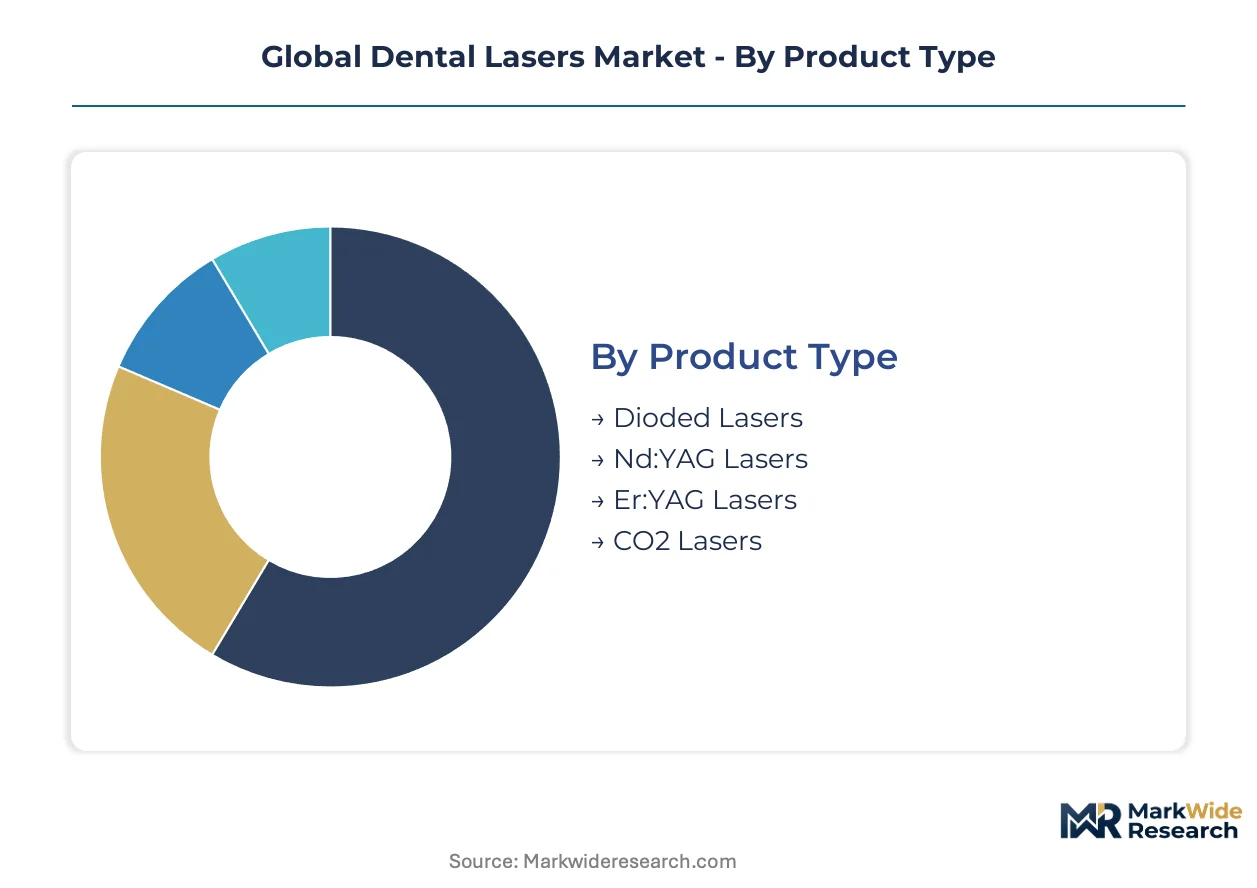
Segmentation in dental lasers separates volume tiers from premium positioning, revealing how wavelength architecture and procurement channel determine margin capture. Product type and application segmentation together explain why certain configurations dominate specific clinic workflows while others remain specialty-bound.
Product Type:
Cost tier stratification across laser platforms creates distinct adoption pathways for general practitioners versus surgical specialists.
- Diode Lasers:Compact semiconductor devices emitting at 810-980 nm wavelengths enable soft-tissue procedures with minimal thermal diffusion. Demand concentrates in North American solo practices where acquisition cost barriers previously excluded laser adoption. Diode miniaturization is accelerating general practitioner penetration.
- Er:YAG Lasers:Solid-state platforms at 2940 nm exploit water absorption peaks for hard-tissue ablation with micron-level precision. Osaka-Tokyo corridor clinics in Japan drive procurement concentration where JIS-compliant manufacturing standards filter non-domestic suppliers. Water-cooled interaction mechanics command premium positioning.
- Nd:YAG Lasers:1064 nm wavelength systems penetrate deeper tissue layers for periodontal debridement applications.
- CO2 Lasers:Gas-based 10,600 nm emission supports soft-tissue incision with excellent hemostasis in hospital settings.
Diode lasers command the established base. The steepest expansion runs through Er:YAG platforms.
Application:
Procedure reimbursement patterns and consumable attach rates determine which applications sustain equipment financing models.
- Soft Tissue Surgery:Gingivectomy and frenectomy procedures generate recurring fiber tip consumable revenue with high procedure frequency. German orthodontic clinics drive replacement demand under EU MDR compliance mandates. Subscription-based equipment access models concentrate here.
- Periodontal Treatment:Laser-assisted pocket debridement protocols reduce antibiotic dependency while improving attachment levels. Bavarian dental clusters concentrate adoption where precision manufacturing ecosystems support subsystem supplier integration. Clinical evidence requirements under EU MDR escalate fastest in this segment.
- Teeth Whitening:Diode-activated bleaching protocols drive patient-facing cosmetic demand with rapid chairside turnover.
- Oral Surgery:Implant site preparation and bone grafting applications require dual-wavelength platform flexibility.
Soft tissue surgery commands the established base. The steepest expansion runs through periodontal treatment.
End User:
Procurement authority fragmentation across clinic networks versus institutional buyers reshapes vendor sales motion and service requirements.
- Dental Clinics:Independent and multi-site practices prioritize compact footprint and chairside integration with digital imaging workflows. California and Texas dental service organizations pilot subscription-based equipment access to transfer obsolescence risk. Per-procedure consumable bundling displaces capital purchase arrangements.
- Hospitals:Academic medical centers and surgical suites demand dual-wavelength architectures supporting multi-specialty use. EU MDR clinical evidence requirements extend procurement cycles for imported devices. Hard-tissue application protocols face steepest compliance cost escalation.
- Academic Institutions:Training programs require ANSI Z136.3-compliant laser safety officer certification infrastructure.
- Research Laboratories:Photonic integration development centers pilot supercontinuum fiber laser sources for wavelength-tunable platforms.
Dental clinics command the established base. The steepest expansion runs through hospitals.
Technology:
Resonator architecture and gain medium composition determine thermal management requirements and wavelength tunability.
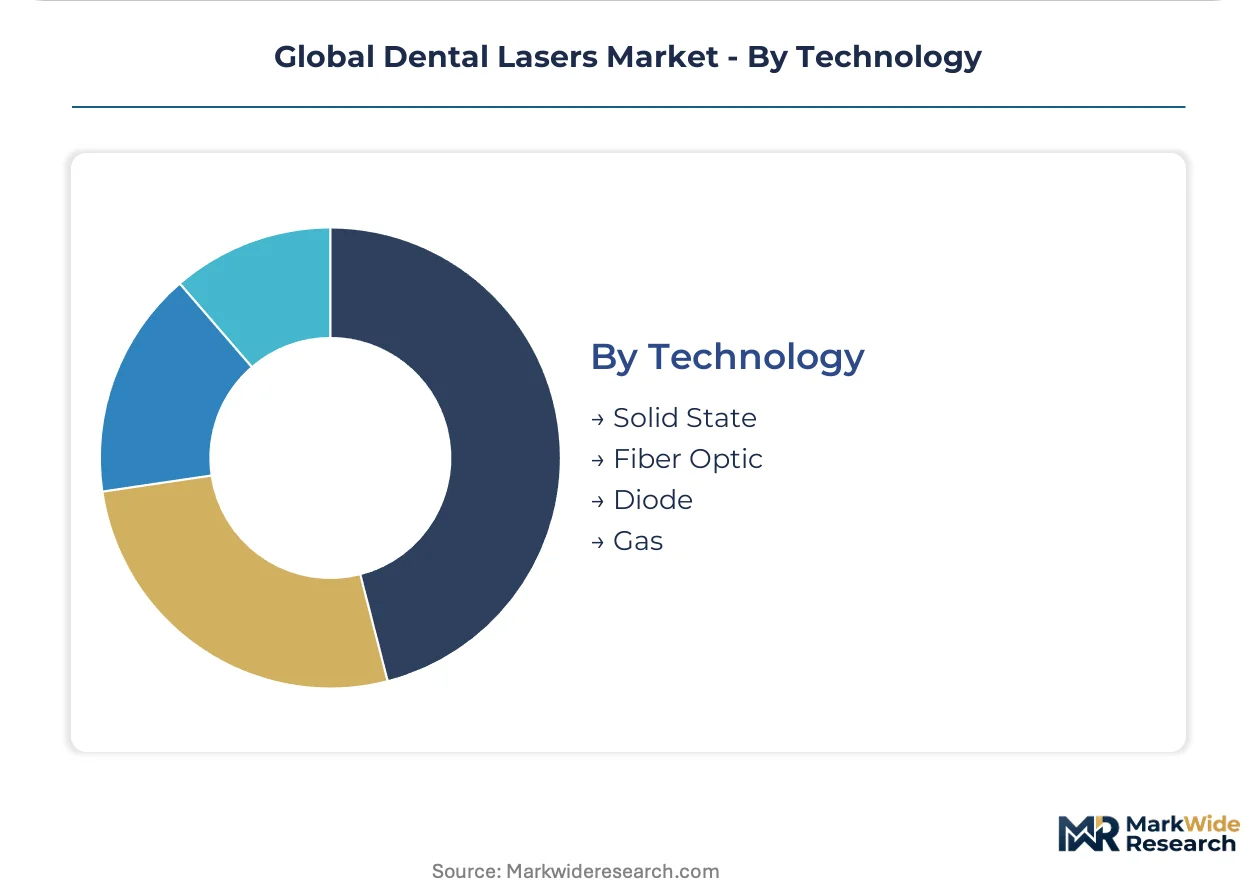
- Solid State:Crystal-based laser media including Er:YAG and Nd:YAG configurations dominate hard-tissue applications requiring high peak power density. Ytterbium-doped fiber input concentration dependencies expose manufacturers to German and Japanese rare-earth dopant supply concentration. Thermal damage threshold documentation demands escalate under EU MDR Annex I requirements.
- Diode:Semiconductor junction emission enables smallest footprint specifications for portable and tele-dentistry applications. India's PLI scheme for medical devices attracts assembly investments targeting price-accessible platforms. Cloud-connected treatment logging capabilities emerge as procurement differentiator.
- Fiber Optic:Delivery handpieces face stricter biocompatibility testing from German notified bodies.
- Gas:CO2 laser platforms retain hospital procurement preference for hemostatic soft-tissue incision.
Solid state commands the established base. The steepest expansion runs through diode platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) predicate pathways anchor North American commercialization timelines, while EU MDR technical documentation requirements extend certification cycles for imported devices. PMDA-enforced JIS standards filter non-compliant entrants from Japan's clinic procurement channels. Stakeholders track harmonization gaps between FDA rules and EU clinical evidence expectations.
United States
Diode laser miniaturization drives general practitioner adoption in solo practices previously excluded from laser-assisted procedures. FDA 510(k) clearance pathways govern commercialization timelines for new wavelengths. California and Texas multi-clinic networks pilot subscription-based equipment access models to transfer obsolescence risk.
Germany
Orthodontic clinics drive replacement demand for predicate-certified devices under EU MDR compliance mandates. German notified bodies enforce stricter biocompatibility testing for fiber optic delivery handpieces. Bavarian manufacturing clusters concentrate precision optics sourcing and attract laser subsystem suppliers.
Japan
Er:YAG wavelength platforms concentrate demand in Osaka-Tokyo corridor clinics requiring micron-level precision. PMDA enforces JIS-compatible electromagnetic compatibility standards that filter non-compliant entrants. Domestic precision dental manufacturing ecosystems support water-cooled interaction mechanics for hard-tissue applications.
India
Price-accessible diode platforms attract domestic manufacturing investments under the PLI scheme for medical devices. CDSCO regulatory pathways govern medical device commercialization. Assembly operations target general practitioner segments with compact footprint specifications for emerging clinic networks.
China
Domestic manufacturing scale supports cost-competitive diode laser production for regional export markets. NMPA registration requirements structure commercialization timelines for imported and locally manufactured devices. Yangtze River Delta industrial clusters concentrate photonics component sourcing for dental laser assembly.
Global Dental Lasers Market Vendor Landscape
Dual-wavelength specialists and diode platform generalists split the market across premium and volume tiers. Vendor concentration remains moderate, with established optical equipment manufacturers competing against dental-specific device specialists. Two strategic archetypes dominate: integrated imaging-laser workflow bundlers and wavelength-specialized component suppliers. Competitive moves center on chairside software integration partnerships and rare-earth dopant supply security arrangements.
Within the integrated workflow tier, Dentsply Sirona Inc. exemplifies the imaging-laser bundling archetype, while BIOLASE, Inc. occupies a position representing North American diode platform specialization. Fotona anchors the European dual-wavelength architecture segment. These three entities collectively illustrate how geographic origin and corporate structure shape competitive positioning across distinct procurement channel preferences.
| Leading Market Players |
|---|
| BIOLASE, Inc. |
| Fotona |
| Dentsply Sirona Inc. |
| Convergent Dental |
| AMD Lasers |
| CAO Group, Inc. |
| Gigaalaser Group |
| IPG Photonics Corp. |
| J. Morita Corp. |
| Others |
Supply Flow & Price Mechanics
Bavarian precision optics clusters concentrate laser subsystem manufacturing capacity, concentrating pricing power among German and Japanese rare-earth dopant suppliers while compressing margins for downstream device assemblers seeking JIS-compliant or EU MDR-certified configurations.
Pricing Analysis
Price spreads between Osaka-Tokyo corridor clinics and North American solo practices exceed threefold for Er:YAG platforms versus diode systems. Three-tier pricing structure across premium, standard, and economy levels separates water-cooled hard-tissue configurations from compact soft-tissue units. Cost compression in economy diode tiers is intensifying because India's PLI scheme attracts assembly investments targeting price-accessible general practitioner segments. Dental service organizations in California and Texas demonstrate least price sensitivity through subscription-based equipment access adoption.
Supply Chain Analysis
Ytterbium-doped fiber feedstock draws from German and Japanese rare-earth dopant refining operations, tethering solid-state laser manufacturers to concentrated upstream supply. Yttrium-aluminum-garnet crystal substrates and semiconductor junction materials complete critical input dependencies. Single-source vulnerability in rare-earth supply exposes device makers to geopolitical disruption risks. Distribution runs through Bavarian manufacturing clusters for precision optics and Yangtze River Delta industrial zones for photonics component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives against high-speed handpiece retention in emerging-market price-sensitive procurement segments.
For Market Incumbents: Entrench dual-wavelength platform advantages through backward integration into rare-earth dopant supply arrangements with German and Japanese refiners. Deepen ANSI Z136.3-compliant training program certification infrastructure to constrain multi-site dental service organization rollout velocity for emerging competitors. Prioritize API development between proprietary laser control software and dominant practice management systems to lock in chairside integration workflows. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized domestic manufacturing corridor for price-accessible diode platforms targeting emerging clinic networks. Target tele-dentistry workflow integration as the most penetrable application, exploiting demand for portable laser units with cloud-connected treatment logging capabilities. Pursue CDSCO regulatory pathway efficiency versus EU MDR extended certification cycles as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified photonics equipment parents with undermonetized dental-specific wavelength development programs. Long-term viability hinges on subscription-based equipment access model adoption concentration in North American multi-clinic networks. Watch supercontinuum fiber laser pilot outcomes at United States multi-specialty dental service organizations as the inflection indicator for platform consolidation technology.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerates predicate-certified device replacement demand across German orthodontic clinics. |
| Rare-Earth Supply Agreement | Secures ytterbium-doped fiber input from German and Japanese refining operations. |
| Chairside Software Integration | Enables API connectivity between laser control modules and Dentsply Sirona imaging workflows. |
| Subscription Equipment Access | Transfers obsolescence risk to manufacturers in California and Texas clinic networks. |
| JIS Compliance Program | Filters non-compliant entrants from Osaka-Tokyo corridor procurement channels. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, PMDA registration databases, EU MDR technical documentation, and customs trade records. Bottom-up and top-down triangulation cross-checked wavelength-specific demand estimates against subsystem supplier production capacity disclosures.
Forecast inputs span product type, application, end user, and technology segmentation dimensions across the analysis window. CAGRs derive from modeled procedure volume growth, replacement cycle dynamics, and regulatory approval timeline differentials. Specific inputs include EU MDR compliance-driven replacement velocity in German orthodontic clinics and JIS standard enforcement stringency in Japanese precision manufacturing corridors.
Stress conditions across rare-earth supply interruption scenarios, FDA 510(k) predicate pathway rigidity, and conventional mechanical instrumentation price competition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about harmonization gaps between FDA rules and EU clinical evidence expectations. Quarterly review of supercontinuum fiber laser pilot adoption rates and PLI scheme utilization intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Europe Dental Lab Market
Dental Devices
Sleep Apnea Oral Appliances Market
Dental Devices
Americas Acrylic Teeth Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
Dental Suction Systems Market
Dental Devices
Global Dental Bone Graft Substitutes Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Caries and Endodontic Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Dental Piezoelectric Ultrasonic Unit Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
Dental Regeneration Market
Dental Devices
Asia-Pacific Dental Aligners Market
Dental Devices
Europe CBCT Dental Imaging Market