
 Germany Cosmetic Surgery Market | 2026-2036
Germany Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Cosmetic Surgery Market Insights
Medical leasing and pay-per-procedure financing is rewriting competitive access across German aesthetic clinics, lowering capital barriers for mid-tier operators. AbbVie Inc. leverages its Allergan heritage in injectable neuromodulators to sustain premium positioning in facial aesthetics. Johnson & Johnson Services, Inc. (MENTOR) anchors breast implant supply through its established relationships with university hospitals. Merz Pharma differentiates via its integrated portfolio spanning fillers, toxins, and skin tightening devices.
Germany cosmetic surgery encompasses surgical and non-surgical procedures modifying physical appearance through tissue manipulation, laser energy application, or injectable pharmaceutical agents, with breast augmentation requiring silicone gel-filled implants meeting ISO 14607 biocompatibility standards and liposuction utilizing tumescent fluid infiltration followed by cannula-assisted adipocyte extraction. The primary commercial purpose centers on elective aesthetic enhancement and reconstructive correction. Minimally invasive techniques command expanding procedure volumes as downtime-averse patients shift from surgical rhytidectomy toward laser-based skin resurfacing and injectable treatments. Private clinics capture disproportionate margin pools relative to hospitals by bundling consultation, procedure, and aftercare into premium service packages. Target demographic segmentation reveals concentrated demand among women aged 35-50 seeking facial rejuvenation, though male patient inflows into body contouring accelerate from a smaller base.
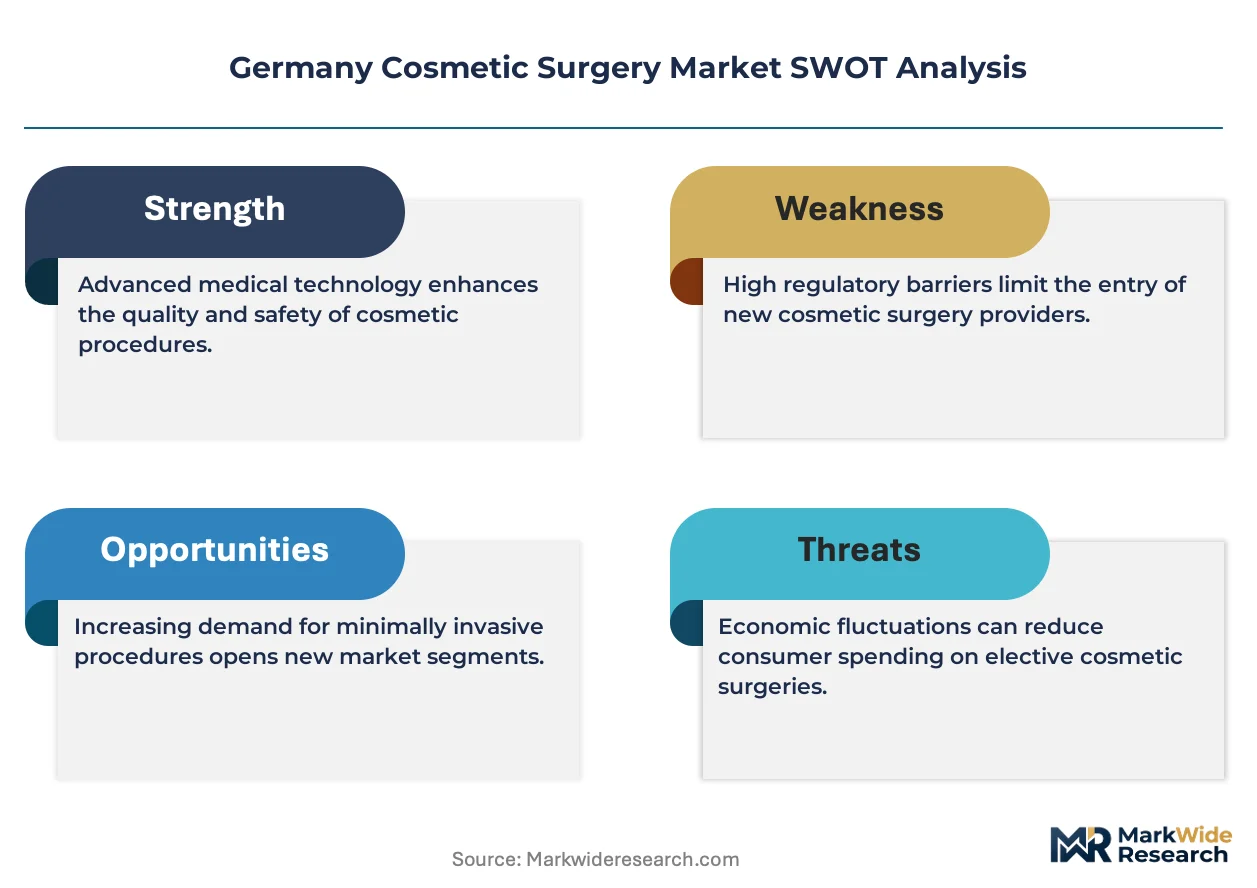
BfArM oversees medical device registration under EU MDR transitional provisions, while the German Medical Association enforces continuing education mandates for aesthetic practitioners performing invasive procedures. KBA has no direct role here; rather, the Federal Ministry of Health coordinates with EMA on pharmaceutical agent approvals for botulinum toxins and dermal fillers. These layered requirements elevate compliance costs for new market entrants but reinforce quality differentiation among established operators. Stakeholders must monitor MDR implementation timelines and reimbursement policy shifts for reconstructive indications that could reshape patient flow between facility types.
Market Dynamics
The EU Medical Device Regulation is compressing implant supply chains while accelerating clinic consolidation across German metropolitan clusters. Compliance costs for traceability systems now separate capital-rich operators from fragmented mid-tier practices.
Growth Catalysts
- MDR traceability mandates:ISO 14607-compliant implant tracking systems are forcing clinic infrastructure upgrades that favor multi-site operators with centralized procurement.
- Minimally invasive technique diffusion:Laser-assisted lipolysis and radiofrequency skin tightening are expanding addressable patient pools beyond traditional surgical candidates in North Rhine-Westphalia.
- Medical tourism corridors:Swiss and Austrian patient inflows sustain above-average utilization rates at Berlin and Munich specialty clinics during domestic demand troughs.
Market Restraints
- Silicone gel implant supply concentration:Three manufacturers control EU-compliant breast implant certification, creating single-source vulnerability for reconstructive surgery schedules.
- BfArM registration timelines:EU MDR transitional provisions extend device approval cycles to 18-24 months, freezing product portfolios for mid-tier distributors.
- Non-surgical substitute proliferation:High-efficacy botulinum toxin and hyaluronic acid filler protocols capture facial rejuvenation volumes previously directed toward rhytidectomy.
Strategic Opportunities
- Pay-per-procedure financing models:Leasing structures for laser and energy-based devices lower capital barriers for independent practitioners in secondary cities.
- Male aesthetic vertical expansion:Body contouring and hair restoration segments show underpenetrated demand relative to female-saturated facial aesthetics.
- Teleconsultation integration:Remote pre-operative assessment protocols expand catchment radii beyond traditional 50-kilometer clinic access zones.
Industry Challenges
- Specialist certification bottlenecks:German Medical Association continuing education mandates for invasive procedures outpace qualified instructor availability.
- Legacy EHR interoperability:MDR-mandated implant traceability systems require expensive integration with hospital information architectures.
- Aftercare labor intensity:Minimally invasive procedure volume growth strains nursing capacity for follow-up protocols without proportional reimbursement adjustment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Cosmetic Surgery Market |
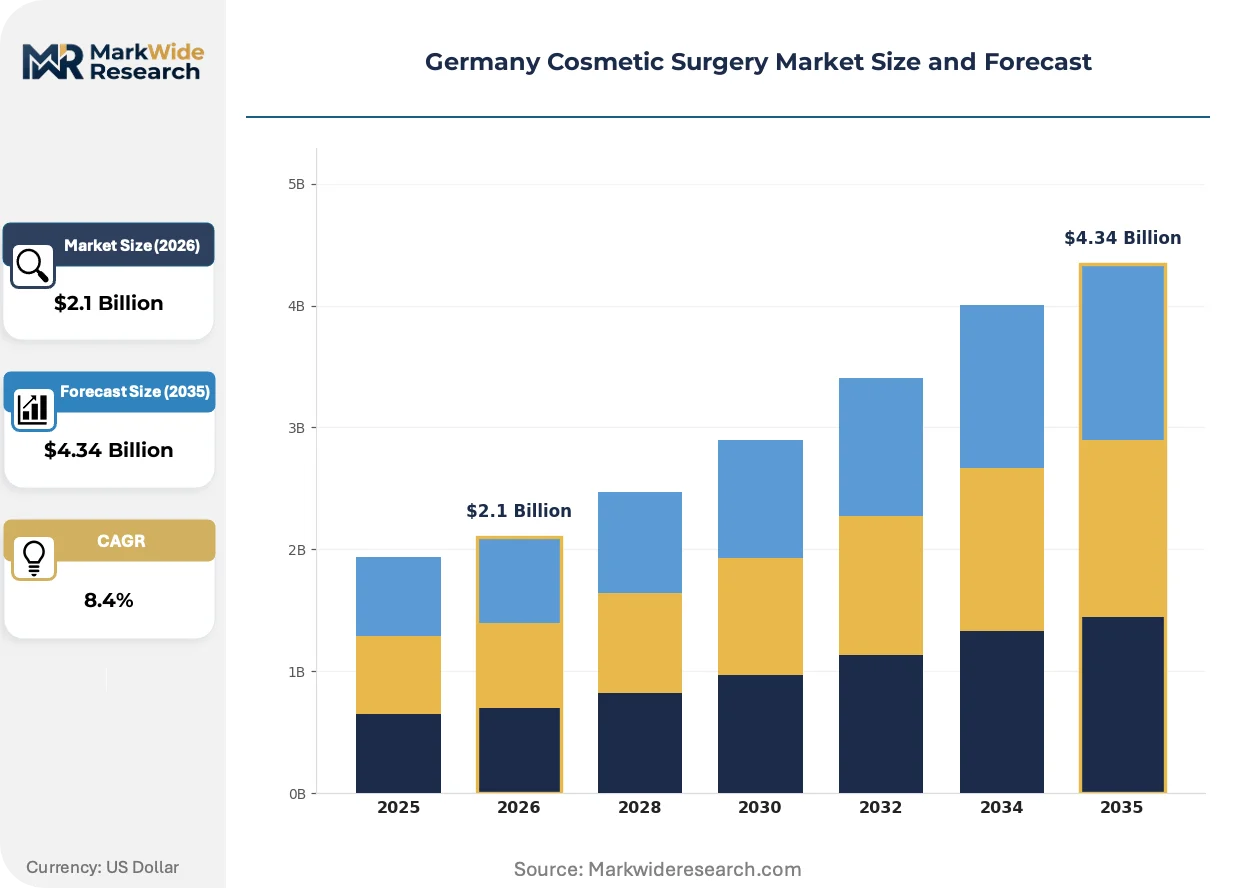
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Liposuction, Rhytidectomy, Rhinoplasty Target Demographic: Women, Men, Age 18-34, Age 35-50 Technique: Invasive, Minimally Invasive, Non-Surgical, Laser-Based Facility Type: Private Clinics, Hospitals, Medical Spas, Outpatient Centers |
| Companies Covered | AbbVie Inc., Bausch Health Companies Inc., Johnson & Johnson Services, Inc. (MENTOR), Cynosure Inc., Lumenis Inc., Alma Lasers, Merz Pharma, Evolus Inc., Syneron Medical Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Cosmetic Surgery Market Trends and Innovations
Energy-based device platforms are fragmenting procedure economics while compressing recovery timelines. Clinicians now sequence multiple modalities within single sessions rather than staging surgical interventions.
Fractional CO2 laser technology is hybridizing with radiofrequency microneedling platforms to deliver dermal remodeling at reduced thermal damage thresholds. Aesthetic practitioners in Bavaria and Baden-Württemberg are adopting these stacked protocols for periorbital rejuvenation cases. The convergence is compressing patient downtime from weeks to 48-72 hours while expanding treatable Fitzpatrick skin type ranges.
BfArM enforcement of EU MDR economic operator obligations is restructuring distributor-clinic relationships across the Federal Republic. Importers now assume full liability for post-market surveillance, forcing smaller device vendors to exit or consolidate. University hospitals in Hamburg and Cologne are responding by centralizing procurement through established manufacturer-direct contracts that bypass fragmented wholesale channels.
Subscription-based maintenance programs are displacing transactional procedure pricing in facial aesthetics. Patients in metropolitan Berlin commit to quarterly neurotoxin and filler refresh cycles through annual contracts. This model concentrates lifetime value within single-provider relationships while reducing price sensitivity for individual treatment sessions.
Germany Cosmetic Surgery Market Segmentation
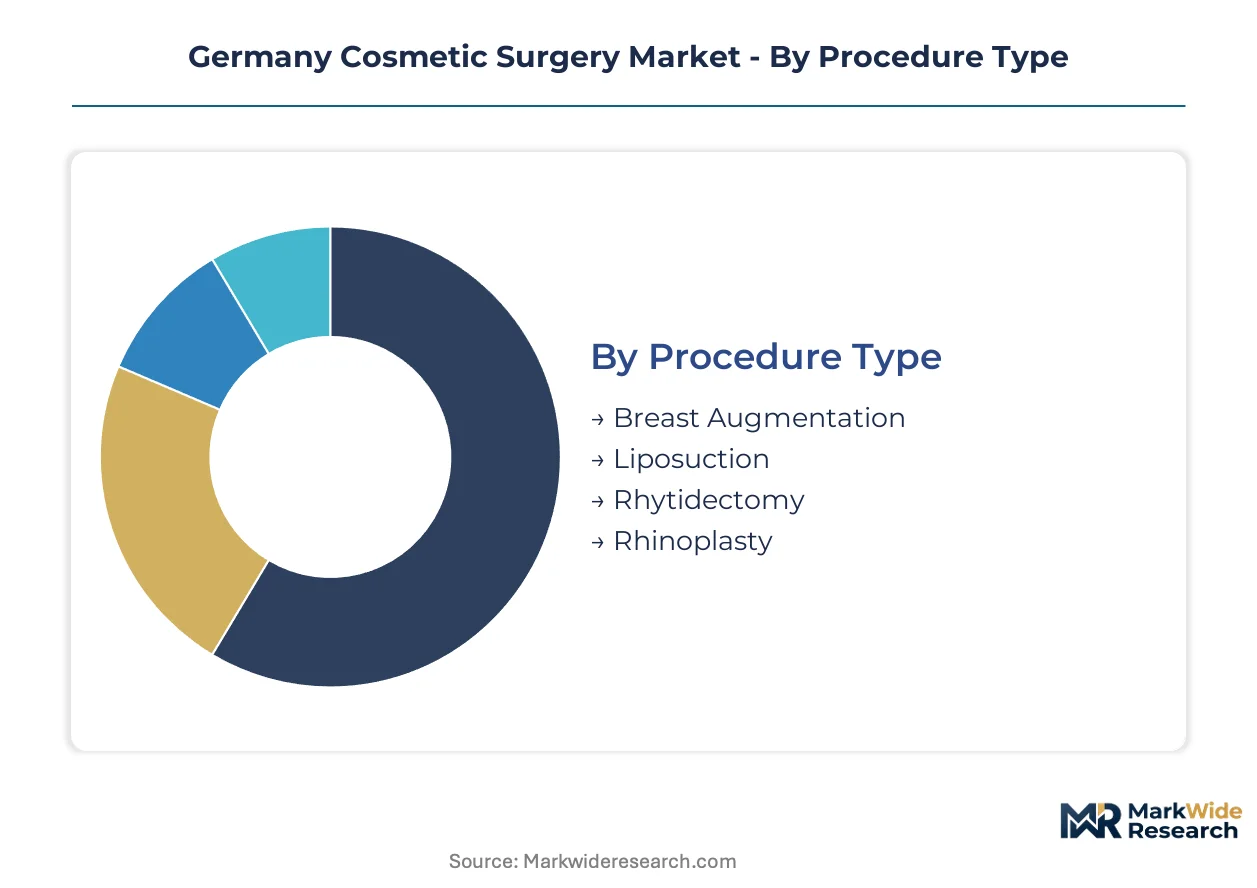
Procedure mix and facility configuration determine margin capture and capital intensity across German aesthetic services. Demographic targeting and technique selection shape competitive differentiation between metropolitan clusters and secondary cities.
Procedure Type:
Breast augmentation and rhytidectomy command extended consultation-to-recovery cycles spanning months, while liposuction and rhinoplasty turn over faster with compressed pre-operative pathways.
- Breast Augmentation:Silicone gel-filled implants meeting ISO 14607 biocompatibility standards dominate reconstructive and elective volumes. Demand concentrates in Berlin and Munich university hospitals where BfArM traceability mandates favor centralized procurement systems.
- Liposuction:Tumescent fluid infiltration followed by cannula-assisted adipocyte extraction defines the technical standard. North Rhine-Westphalia clinics report expanding volumes as downtime-averse patients substitute this for more invasive body contouring alternatives.
- Rhytidectomy:Surgical facial rejuvenation retains premium pricing but faces volume pressure from non-surgical substitutes.
- Rhinoplasty:Structural nasal modification combines functional and aesthetic indications with specialized surgeon requirements.
Breast augmentation dominates installed base. Liposuction is where expansion concentrates.
Target Demographic:
Cost stratification separates age-cohort preferences, with premium service bundling attaching to established earners while younger segments drive minimally invasive entry-point procedures.
- Women:Facial rejuvenation and breast procedures constitute the core revenue base. Bavarian private clinics capture disproportionate margin pools through bundled consultation-procedure-aftercare packages targeting this demographic.
- Men:Body contouring and hair restoration segments show accelerating inflows from a smaller base. Hamburg and Cologne operators are expanding dedicated male aesthetic verticals with distinct marketing protocols.
- Age 18-34:Preventive and entry-point procedures concentrate here, with neurotoxin and filler protocols driving frequency.
- Age 35-50:Surgical intervention thresholds cross as disposable income peaks and aging signs intensify.
Women retain majority volume share. Men represent the steepest expansion trajectory.
Technique:
Volume throughput and margin structure diverge sharply across the invasiveness spectrum, with capital equipment requirements scaling inversely to procedure intensity.
- Minimally Invasive:Laser-assisted lipolysis and radiofrequency skin tightening expand addressable pools beyond traditional surgical candidates. Baden-Württemberg practitioners adopt stacked modality protocols compressing patient downtime to 48-72 hours.
- Non-Surgical:Botulinum toxin and hyaluronic acid filler protocols capture facial rejuvenation volumes previously directed toward rhytidectomy. Quarterly refresh cycles through subscription contracts concentrate lifetime value in metropolitan Berlin.
- Invasive:Traditional surgical approaches retain premium positioning for complex reconstructive and dramatic aesthetic transformations.
- Laser-Based:Fractional CO2 technology hybridizes with microneedling platforms for periorbital cases across Bavaria.
Non-surgical methods dominate procedure counts. Minimally invasive techniques are gaining share fastest.
Facility Type:
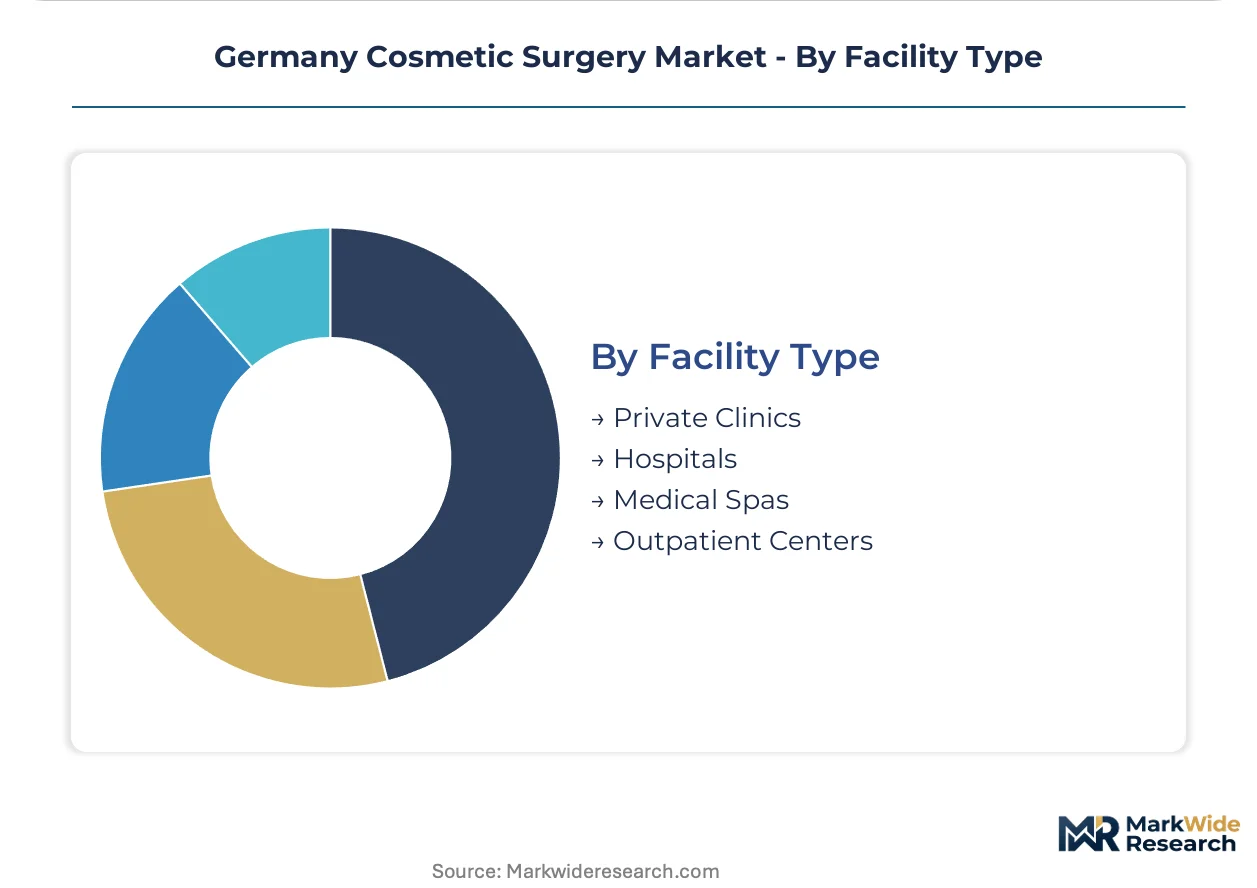
Patient flow and reimbursement pathways shape facility economics, with private operators capturing margin premiums unavailable to hospital-based providers.
- Private Clinics:Bundled premium service packages and direct-pay models sustain above-average margins. Berlin and Munich specialty clinics leverage medical tourism corridors from Switzerland and Austria to sustain utilization during domestic troughs.
- Hospitals:Reconstructive indications and complex cases requiring overnight stay capacity anchor this segment. University hospitals in Hamburg and Cologne centralize procurement through manufacturer-direct contracts bypassing fragmented wholesale channels.
- Medical Spas:Entry-point aesthetic services and maintenance protocols concentrate in this channel with lighter regulatory burden.
- Outpatient Centers:Same-day surgical procedures with reduced overhead structures compete on accessibility and price positioning.
Private clinics command margin leadership. Outpatient centers are where volume growth concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Bavarian private clinics while North Rhine-Westphalia operators compete on accessibility and volume throughput. This asymmetry shapes capital deployment patterns across German metropolitan clusters.
Bavaria
Facial rejuvenation demand from affluent patient cohorts drives premium service bundling in Munich and Nuremberg. BfArM registration requirements for implant traceability systems favor established multi-site operators with centralized procurement infrastructure. Augsburg clinics report expanding adoption of stacked laser-radiotherapy protocols for periorbital cases.
North Rhine-Westphalia
Downtime-averse patients in Cologne and Düsseldorf accelerate minimally invasive body contouring volumes. German Medical Association continuing education mandates create specialist certification bottlenecks for invasive procedures. Dortmund outpatient centers leverage pay-per-procedure financing to lower capital barriers for independent practitioners.
Baden-Württemberg
Stuttgart and Karlsruhe aesthetic practices pioneer hybrid fractional CO2 and radiofrequency microneedling platforms. EU MDR economic operator obligations force distributor consolidation, pushing university hospitals toward manufacturer-direct procurement contracts. Freiburg medical spas capture entry-point neurotoxin and filler maintenance protocols through subscription pricing models.
Berlin-Brandenburg
Swiss and Austrian medical tourism inflows sustain above-average utilization rates at specialty clinics during domestic demand troughs. Federal Ministry of Health coordination with EMA on pharmaceutical approvals shapes botulinum toxin and dermal filler market access. Potsdam teleconsultation protocols expand catchment radii beyond traditional 50-kilometer clinic access zones.
Hamburg
Male aesthetic vertical expansion concentrates in body contouring and hair restoration segments with distinct marketing protocols. BfArM enforcement of post-market surveillance liability restructuring prompts procurement centralization at university hospitals. Lübeck practitioners report nursing capacity strains from minimally invasive procedure volume growth without proportional reimbursement adjustment.
Germany Cosmetic Surgery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in device and implant supply. The German market structures around three tiers: multinational pharmaceutical-device conglomerates with full aesthetic portfolios, dedicated energy-based device manufacturers, and regional clinic operators with service bundling expertise. Competitive dynamics center on M&A consolidation of mid-tier distributors under EU MDR compliance pressure and strategic partnerships between device vendors and private clinic chains for exclusive territorial arrangements.
Within the pharmaceutical-device conglomerate tier, AbbVie Inc. and Johnson & Johnson Services, Inc. occupy positions anchored by injectable neuromodulator and breast implant heritage respectively. Merz Pharma exemplifies the integrated portfolio archetype spanning fillers, toxins, and skin tightening devices. Among energy-based device specialists, Cynosure Inc., Lumenis Inc., and Alma Lasers represent the capital equipment supply layer where BfArM traceability mandates are compressing distributor margins and accelerating direct-to-clinic contracting.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Bausch Health Companies Inc. |
| Johnson & Johnson Services, Inc. (MENTOR) |
| Cynosure Inc. |
| Lumenis Inc. |
| Alma Lasers |
| Merz Pharma |
| Evolus Inc. |
| Syneron Medical Ltd |
| Others |
Pricing and Supply Chain Analysis
Silicone gel implant manufacturing concentrates among three EU MDR-certified suppliers, anchoring margin pools downstream with university hospitals and multi-site clinic chains that command volume-tier pricing leverage. This upstream oligopoly shapes procurement economics across German aesthetic services, where traceability compliance costs filter through to patient-facing price structures.
Pricing Analysis
Configured-to-order implant specifications command substantial premiums over standard catalogue configurations, with ISO 14607 certification tier and surgeon reputation anchoring price differentiation. Subscription-based neurotoxin maintenance contracts in metropolitan Berlin concentrate lifetime value while reducing per-session price sensitivity. Cost compression in mid-tier outpatient centers intensifies as pay-per-procedure financing democratizes access. Price-sensitive younger cohorts seeking entry-point fillers drive volume; affluent 35-50 segments absorb premium surgical bundling with minimal elasticity.
Supply Chain Analysis
Extended payment terms from device manufacturers to clinic chains now stretch 90-120 days, easing working capital pressure for capital-intensive energy-based platform acquisitions. Medical-grade silicone feedstock draws from Germany, USA, and Japan; laser componentry rests on German and Israeli precision optics supply. Single-source vulnerability pervades EU MDR-compliant breast implant certification. Distribution runs through manufacturer-direct hospital contracts and fragmented wholesale channels serving independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German aesthetic services exhibit cyclical recovery characteristics as deferred elective procedures from economic uncertainty periods convert to scheduled volumes. Disposable income normalization among established earners drives this rebound pattern.
For Market Incumbents: Entrench market position through backward integration into implant traceability systems that satisfy BfArM economic operator obligations, while consolidating mid-tier distributor relationships threatened by MDR compliance cost escalation. Multi-site operators should centralize procurement infrastructure to capture volume-tier pricing leverage against silicone gel supply concentration.
For New Entrants and Emerging Players: Male aesthetic verticals in body contouring and hair restoration represent the most penetrable entry point, with Hamburg and Cologne demonstrating viable demand formation. Teleconsultation-enabled pre-operative assessment protocols offer geographic arbitrage opportunities beyond traditional 50-kilometer catchment radii. Go-to-market positioning should emphasize subscription-based maintenance contracts that concentrate patient lifetime value.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed clinic chains possessing multi-site footprints in Bavaria and North Rhine-Westphalia. Long-term viability over a 5-10 year horizon hinges on MDR compliance infrastructure and male aesthetic segment development. Monitor BfArM enforcement intensity on post-market surveillance liability as the inflection signal for distributor consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Infrastructure | BfArM traceability mandates separate capital-rich operators from fragmented competitors unable to absorb compliance costs. |
| Male Aesthetic Vertical Expansion | Underpenetrated body contouring demand in Hamburg and Cologne offers first-mover positioning before segment saturation. |
| Subscription Pricing Migration | Quarterly neurotoxin refresh contracts in Berlin concentrate lifetime value and reduce per-session price sensitivity. |
| Teleconsultation Integration | Remote pre-operative protocols expand clinic catchment radii beyond traditional geographic constraints. |
| Pay-per-Procedure Financing | Leasing structures for laser platforms lower capital barriers for independent practitioners in secondary cities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hospital procurement databases, and industry association disclosures. Clinicians, private clinic operators, biomedical engineers, and GPO contracts managers provided operational perspective. BfArM device registrations, EU MDR implementation timelines, German Medical Association continuing education mandates, and EMA pharmaceutical approvals supplied institutional context. Bottom-up procedure volume estimates triangulate against top-down market value reconstruction.
Forecast inputs span procedure type mix, technique adoption curves, facility configuration shifts, and demographic penetration rates across the projection horizon. Segmentation dimensions include invasiveness tier, target demographic cohort, facility type, and regional metropolitan cluster. CAGRs derive from fitted growth curves calibrated to historical procedure volume trajectories and regulatory implementation schedules. Medical tourism corridor utilization and MDR compliance cost pass-through inform scenario boundaries.
Practitioners should monitor BfArM enforcement intensity, Swiss and Austrian patient inflow volatility, and minimally invasive technique substitution rates for early signals of trajectory deviation. Forecasts reflect assumptions regarding regulatory implementation timelines and disposable income normalization. Macroeconomic contraction, accelerated non-surgical substitution, or MDR deadline extensions would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Dimpleplasty Market