
 Saudi Arabia Cosmetic Surgery Market | 2026-2036
Saudi Arabia Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Cosmetic Surgery Market Insights
The Saudi Arabia cosmetic surgery sector is restructuring around a sharp split between premium hospital-based procedures and commoditized clinic offerings. Enfield Royal Saudia leverages its integrated surgical and hospitality model to capture high-margin reconstructive work. Mouwasat Medical Services anchors its position through multi-city ambulatory capacity. Dr. Sulaiman Al Habib Medical Group differentiates via JCI-accredited infrastructure that commands premium pricing.
Cosmetic surgery encompasses invasive and minimally invasive procedures that reshape or enhance physical appearance through surgical incision, tissue manipulation, or energy-based intervention, typically performed under local or general anesthesia in controlled clinical environments. Rhinoplasty and breast augmentation dominate procedure volume, while laser-based technologies capture expanding share in skin resurfacing and body contouring due to shorter recovery protocols. Radiofrequency applications are gaining traction in non-surgical tightening segments where patients prioritize downtime reduction over dramatic transformation.
SFDA regulates medical devices and injectables used in aesthetic procedures, while MOHAP licenses facilities and practitioner credentials across the Kingdom. CCHI reimbursement policies indirectly shape demand by excluding elective cosmetic work, channeling patients toward private payment and financing structures. Stakeholders must monitor how evolving Saudi medical liability frameworks and incoming data-protection obligations affect consent protocols and marketing reach.
Market Dynamics
SFDA medical device registration timelines and MOHAP facility licensing standards are compressing market entry windows while elevating capital requirements for new surgical centers across the Kingdom.
Growth Catalysts
- Non-surgical aesthetic demand:Radiofrequency and laser-based skin tightening protocols attract young professionals in Riyadh and Jeddah who prioritize minimal downtime over surgical transformation.
- MOHAP licensing standardization:Unified facility accreditation requirements across Saudi regions reduce regulatory arbitrage and channel investment toward compliant multi-specialty hospitals.
- Medical tourism positioning:Jeddah's coastal clinic clusters leverage proximity to pilgrimage traffic and Red Sea leisure corridors to capture cross-border aesthetic patients from Gulf neighbors.
Market Restraints
- Import dependency for capital equipment:Laser platforms and surgical lasers originate primarily from US and German OEMs, exposing operators to currency volatility and extended lead times.
- SFDA registration bottlenecks:Novel injectable formulations face 18-24 month approval cycles that delay revenue recognition for distributors and clinics awaiting new product launches.
- CCHI reimbursement exclusion:The national health insurance framework categorically denies coverage for elective cosmetic procedures, limiting addressable demand to self-pay and private financing segments.
Strategic Opportunities
- Eastern Province penetration:Dammam and Khobar exhibit surgical capacity gaps relative to population density and per-capita income levels, offering first-mover positioning for JCI-accredited entrants.
- Hybrid surgical-hospitality models:Integrated recovery suites and concierge protocols command premium pricing from high-net-worth Saudi patients seeking discretion and extended post-operative monitoring.
- Teleconsultation triage:Virtual pre-operative assessment platforms reduce geographic friction for patients in secondary cities and filter qualified candidates toward centralized surgical hubs.
Industry Challenges
- Specialized surgeon scarcity:Board-certified plastic surgeons with dual aesthetic and reconstructive credentials remain concentrated in Riyadh and Jeddah, constraining expansion timelines for provincial facilities.
- Legacy EMR integration:Established hospital groups face technical debt when connecting aesthetic-specific practice management systems to enterprise-grade electronic health record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Cosmetic Surgery Market |
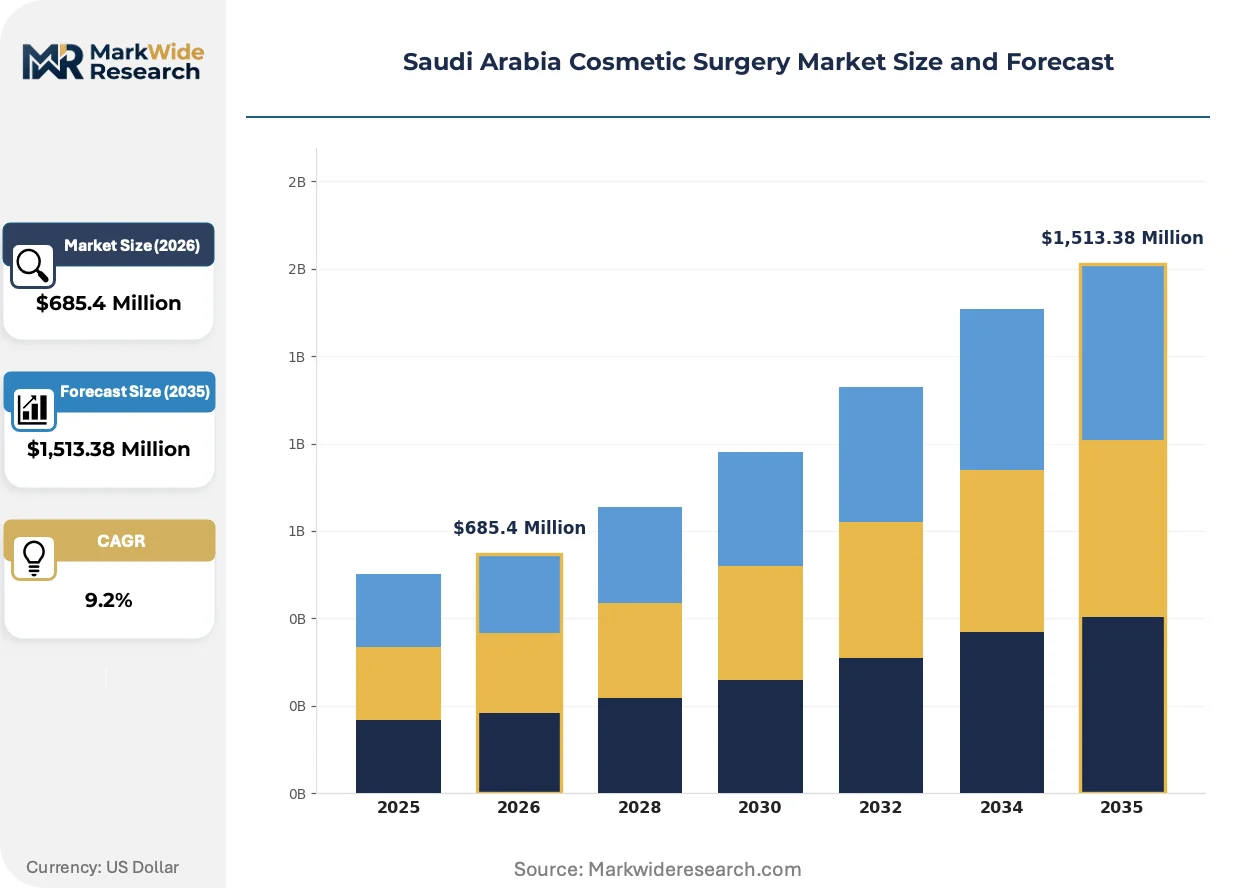
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Rhinoplasty, Liposuction, Breast Augmentation, Tummy Tuck Technology: Laser, Ultrasound, Radiofrequency, Botox End User: Men, Women, Clinics, Hospitals Delivery Mode: In-person, Online Consultation, Mobile Clinics, Home Services |
| Companies Covered | Enfield Royal Saudia, Mouwasat Medical Services, King Faisal Specialist Hospital & Research Centre, Royal Clinic, The Clinics, Dr. Sulaiman Al Habib Medical Group, Novomed Centers, Harley Clinic Saudia, NMC Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Cosmetic Surgery Market Trends and Innovations
Energy-based modalities and digital patient engagement tools are redrawing competitive boundaries between hospital-based surgical suites and ambulatory clinic networks across Saudi urban centers.
Fractional laser resurfacing technology is consolidating position in acne scar revision and photodamage correction protocols. Dermatology-focused clinics in Riyadh's private hospital corridor adopt these platforms at accelerated replacement cycles. The technology is consolidating revenue streams previously captured by surgical alternatives, compressing average revenue per patient while expanding total addressable procedure volume.
SFDA's tightened adverse event reporting requirements for dermal fillers and implantable devices now mandate real-time post-market surveillance. Manufacturers must maintain Saudi-based pharmacovigilance infrastructure or risk registration suspension. High-volume injectable distributors are responding by embedding clinical outcome tracking into patient management workflows.
Subscription-based aesthetic maintenance programs displace transactional procedure booking in Jeddah's coastal clinic clusters. Younger patient cohorts prefer predictable monthly commitments covering neuromodulator touch-ups and laser maintenance sessions. This behavioral pivot is most visible among female professionals aged 25-34 seeking ongoing rather than episodic aesthetic investment.
Saudi Arabia Cosmetic Surgery Market Segmentation
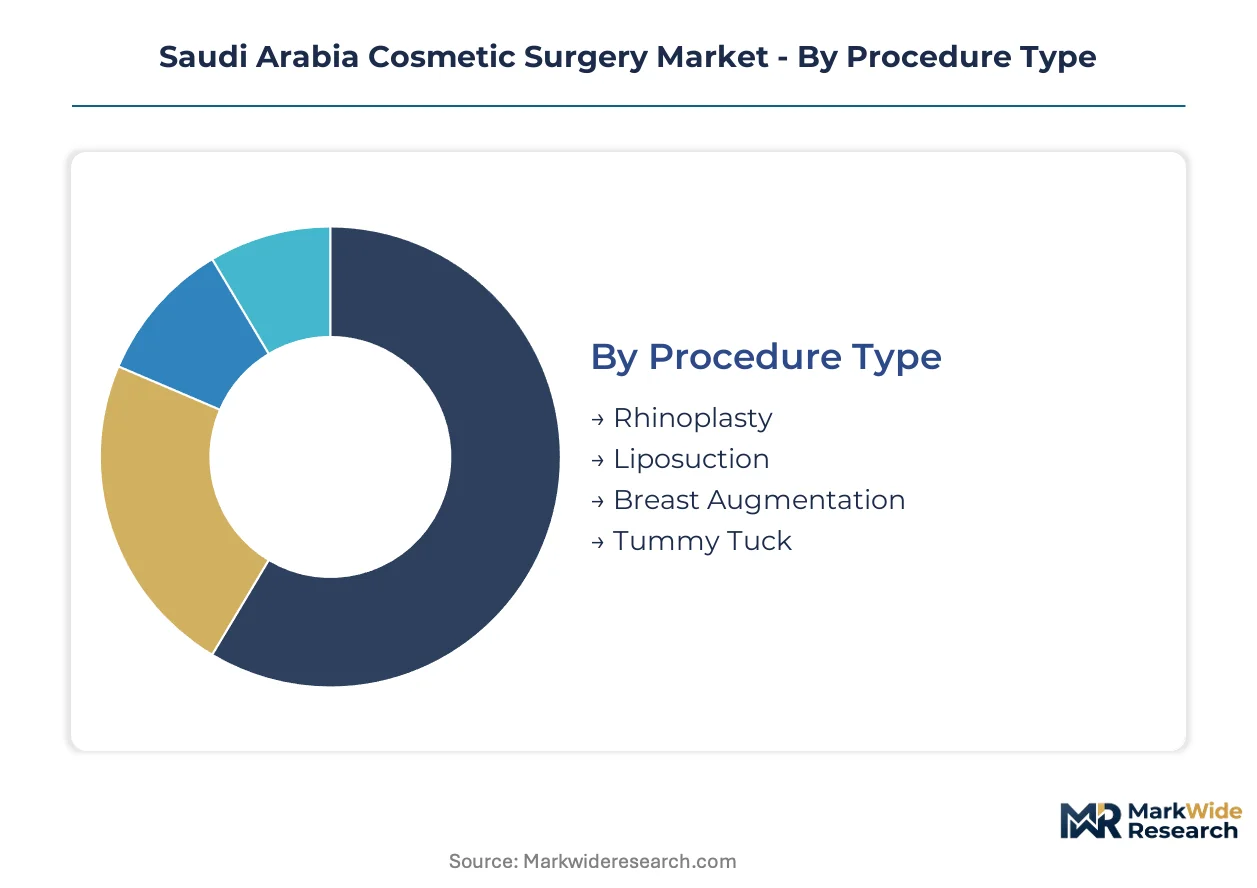
Saudi Arabia's cosmetic surgery market fragments across procedure complexity, technology platforms, and patient access channels. Each segmentation axis reveals distinct margin profiles and regulatory exposure that shape investment allocation across Riyadh's hospital corridor and Jeddah's coastal clusters.
Procedure Type:
The customization-vs-standardization spectrum spans reconstructive precision work to commodified body contouring, with surgical complexity dictating facility licensing tiers and pricing power.
- Rhinoplasty:Nasal reshaping procedures demand board-certified plastic surgeons with dual aesthetic-reconstructive credentials. Demand concentrates in Riyadh's private hospital corridor where JCI-accredited infrastructure commands premium positioning for complex septorhinoplasty cases.
- Liposuction:Fat removal techniques range from traditional suction-assisted lipectomy to power-assisted variants. Jeddah's coastal clinic clusters capture volume through tumescent protocols that reduce anesthesia requirements and enable same-day discharge.
- Breast Augmentation:Implant-based and autologous reconstruction options serve diverse patient profiles across the Kingdom.
- Tummy Tuck:Abdominoplasty procedures address post-bariatric and postpartum body contouring needs in major urban centers.
Leading the category by volume: Liposuction. Growing fastest: Rhinoplasty.
Technology:
Cost tier stratification separates capital-intensive laser platforms from consumable-driven injectable segments, with reimbursement exclusion pushing patients toward out-of-pocket technology choices.
- Laser:Fractional and ablative laser systems target skin resurfacing, acne scar revision, and photodamage correction. Riyadh dermatology-focused clinics adopt these platforms at accelerated replacement cycles, compressing revenue per patient while expanding total addressable volume.
- Radiofrequency:Non-surgical tightening protocols attract young professionals in Riyadh and Jeddah who prioritize minimal downtime. SFDA's tightened adverse event reporting for energy-based devices now mandates real-time post-market surveillance infrastructure.
- Ultrasound:High-intensity focused ultrasound applications serve non-invasive body contouring segments.
- Botox:Neuromodulator injections dominate maintenance-oriented aesthetic programs.
Dominating capital expenditure: Laser. Expanding most quickly: Radiofrequency.
End User:
Customer type segmentation reveals divergent service expectations, with institutional buyers negotiating bundled contracts while individual patients drive discretionary premium spend.
- Women:Female patients aged 25-34 in Jeddah's coastal clusters prefer subscription-based aesthetic maintenance programs covering neuromodulator touch-ups and laser sessions over transactional booking models.
- Hospitals:Multi-specialty hospital groups anchor high-margin reconstructive work through integrated surgical and hospitality models that command premium pricing from high-net-worth Saudi patients seeking discretion.
- Men:Male patient volumes are climbing across rhinoplasty and body contouring categories.
- Clinics:Ambulatory clinic networks compete on accessibility and price transparency.
Representing largest addressable base: Women. Capturing highest revenue per case: Hospitals.
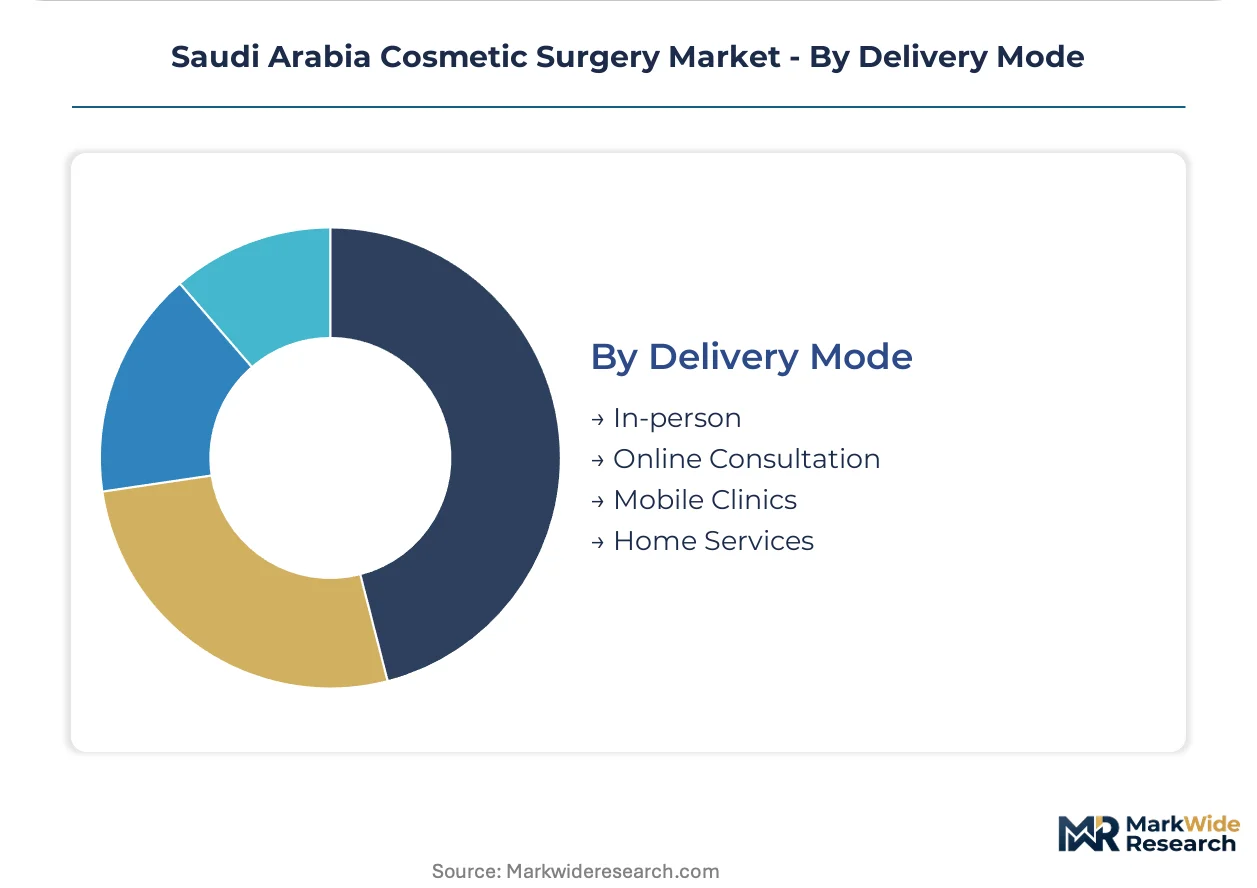
Delivery Mode:
Geography of service delivery determines regulatory compliance burden, with centralized surgical hubs facing MOHAP facility licensing standards while distributed models navigate mobile practice restrictions.
- In-person:Traditional clinic and hospital-based consultations remain mandatory for surgical procedures requiring general anesthesia. SFDA medical device registration requirements and MOHAP licensing standards elevate capital requirements for new surgical centers.
- Online Consultation:Virtual pre-operative assessment platforms reduce geographic friction for patients in secondary cities and filter qualified candidates toward centralized surgical hubs in Riyadh and Jeddah.
- Mobile Clinics:Deployable units serve peri-urban and secondary city populations with limited local surgical capacity.
- Home Services:Post-operative monitoring and non-invasive touch-up protocols extend into residential settings.
Generating highest procedure volume: In-person. Gaining share fastest: Online Consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's private hospital corridor anchors the Kingdom's cosmetic surgery capacity, drawing patients from across Saudi Arabia and neighboring Gulf states seeking JCI-accredited infrastructure and board-certified specialist concentration.
Riyadh
Riyadh commands the highest surgical volume through its integrated medical-hospitality complexes serving high-net-worth Saudi patients. SFDA medical device registration requirements and MOHAP facility licensing standards elevate capital barriers for new entrants in the capital's premium corridor. The King Faisal Specialist Hospital & Research Centre and Dr. Sulaiman Al Habib Medical Group anchor reconstructive and aesthetic capacity in Riyadh's central medical district.
Jeddah
Jeddah's coastal clinic clusters capture accelerating demand from young professionals aged 25-34 prioritizing minimal-downtime procedures. MOHAP's unified licensing framework reduces regulatory arbitrage between municipal jurisdictions in the Western Region. Subscription-based aesthetic maintenance programs displace transactional booking models across Jeddah's Red Sea leisure corridor.
Eastern Province
Dammam and Khobar exhibit surgical capacity gaps relative to population density and per-capita income levels in the Eastern Province. CCHI reimbursement policies channel elective cosmetic demand toward private payment structures regardless of geographic location. First-mover positioning awaits JCI-accredited entrants willing to deploy teleconsultation triage platforms connecting secondary cities to centralized surgical hubs.
NEOM Northwest
NEOM's emerging healthcare zone targets medical tourism positioning through proximity to Red Sea leisure and pilgrimage traffic corridors. The zone's regulatory sandbox framework may accelerate SFDA registration timelines for novel aesthetic technologies. Ambulatory clinic networks are evaluating deployable units to serve peri-urban populations with limited local surgical capacity.
Saudi Arabia Cosmetic Surgery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the certification-infrastructure dimension, with JCI-accredited hospital groups commanding pricing power while ambulatory clinics compete on accessibility. The market structure concentrates around three archetypes: integrated surgical-hospitality complexes, multi-city ambulatory networks, and dermatology-focused clinic chains. Consolidation is accelerating through MOHAP licensing standardization that favors capital-rich incumbents, while technology licensing agreements redistribute energy-based device portfolios across clinic networks.
Within the integrated hospital tier, Enfield Royal Saudia and Dr. Sulaiman Al Habib Medical Group exemplify premium-positioned operators leveraging JCI-accredited infrastructure. Mouwasat Medical Services anchors the multi-city ambulatory archetype through distributed capacity across Saudi urban centers. These three structures represent the dominant competitive configurations reshaping Kingdom-wide patient flow.
| Leading Market Players |
|---|
| Enfield Royal Saudia |
| Mouwasat Medical Services |
| King Faisal Specialist Hospital & Research Centre |
| Royal Clinic |
| The Clinics |
| Dr. Sulaiman Al Habib Medical Group |
| Novomed Centers |
| Harley Clinic Saudia |
| NMC Healthcare |
| Others |
Pricing and Supply Chain Analysis
JCI-accredited hospital certification creates a sharp bifurcation between premium surgical suites and commodity clinic offerings across Saudi Arabia, with this tier divergence manifesting in divergent equipment procurement strategies and patient payment structures that reshape capital allocation decisions.
Pricing Analysis
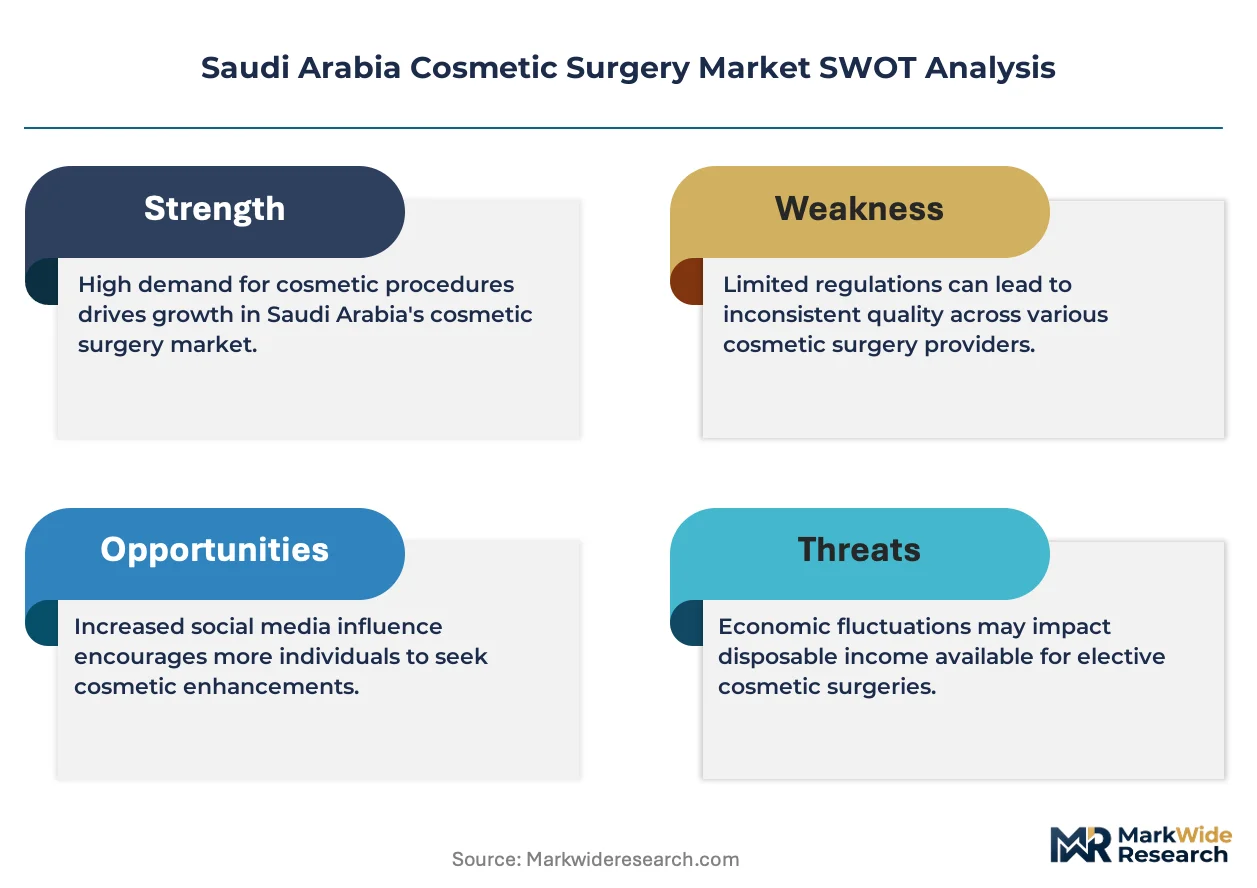
Outcome-linked pricing anchors the Saudi cosmetic surgery market, with rhinoplasty and reconstructive procedures commanding premium positioning tied to surgical success rates and complication profiles. Three-tier pricing structure across premium, standard, and economy levels separates JCI-accredited hospitals from MOHAP-licensed clinics and unaccredited ambulatory centers. Cost compression in the clinic tier intensifies because tumescent liposuction protocols reduce anesthesia overhead and enable same-day discharge economics. Young professionals aged 25-34 in Jeddah exhibit highest price sensitivity, while high-net-worth Saudi patients in Riyadh's private hospital corridor demonstrate least elasticity.
Supply Chain Analysis
Dual-sourcing requirements for laser platforms and surgical devices mandate multi-supplier qualification across US and German OEMs, with SFDA registration timelines forcing distributors to maintain parallel qualification tracks. Geographic supply concentration centers on the United States, Germany, and South Korea for fractional laser systems, radiofrequency generators, and high-intensity focused ultrasound devices. Raw material dependencies span optical components, precision surgical instruments, and biocompatible implant materials. Single-source vulnerability runs through extended lead times for novel injectable formulations facing 18-24 month SFDA approval cycles. Distribution runs through specialized medical device distributors with Saudi-based pharmacovigilance infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's cosmetic surgery sector sits in a technology-transition phase, with radiofrequency and laser-based modalities displacing traditional surgical alternatives across skin tightening and body contouring segments.
For Market Incumbents: Acquire board-certified plastic surgeon practices with dual aesthetic-reconstructive credentials to lock down scarce specialist capacity before provincial expansion accelerates. SFDA's tightened adverse event reporting requirements threaten registration suspension for manufacturers lacking Saudi-based pharmacovigilance infrastructure. Vertical integration into teleconsultation triage platforms reduces geographic friction and filters qualified candidates toward centralized surgical hubs. For New Entrants and Emerging Players: Enter via JCI-accredited facility deployment in Dammam and Khobar, where surgical capacity gaps relative to population density and per-capita income levels offer first-mover positioning. The Eastern Province represents the most penetrable geography given MOHAP's unified licensing framework reducing regulatory arbitrage. Subscription-based aesthetic maintenance programs targeting female professionals aged 25-34 provide a differentiated go-to-market angle displacing transactional booking models. For Investors and Strategic Acquirers: Re-rating potential sits with integrated surgical-hospitality complexes given MOHAP licensing standardization favoring capital-rich incumbents over fragmented clinic networks. Long-term viability across the projection horizon hinges on capturing premium-margin reconstructive work rather than commoditized body contouring volume. Watch SFDA registration timeline compression for novel energy-based devices as the inflection indicator signaling technology portfolio refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Novel injectable and energy-based device approvals unlock revenue recognition for distributors awaiting product launches. |
| JCI Accreditation Investment | Premium pricing power from internationally certified infrastructure commands patient preference in Riyadh's hospital corridor. |
| Teleconsultation Platform Deployment | Virtual pre-operative assessment reduces geographic friction for secondary city patients and filters surgical candidates. |
| Subscription Program Launch | Predictable monthly commitments from young professionals in Jeddah displace transactional booking and improve retention. |
| Eastern Province Facility Buildout | Dammam and Khobar capacity gaps relative to income levels offer first-mover positioning for compliant entrants. |
Research Methodology
Multi-period observation of procedure volume trajectories, technology adoption curves, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with plastic surgeons, medical device distributors, MOHAP licensing officials, and hospital procurement managers. Primary fieldwork combined with secondary validation from SFDA registration databases, MOHAP facility licensing records, CCHI reimbursement policy documents, and hospital procurement contracts. Bottom-up facility capacity modeling and top-down spending pattern analysis provided triangulation across data sources.
Segment-weighting approaches distributed total market value across procedure type, technology platform, end user category, and delivery mode dimensions. Growth projections across the modeling period derived from elasticity modeling against demographic shifts, income trajectory assumptions, and technology substitution rates. CAGRs were computed from year-over-year progression in segment-specific spending patterns. Industry-specific forecast inputs incorporated SFDA registration pipeline visibility and MOHAP licensing queue data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SFDA registration timeline extensions or MOHAP licensing standardization delays. Projections reflect assumptions around specialist supply expansion, technology adoption curves, and patient financing access. Deviation in CCHI reimbursement policy toward selective cosmetic coverage would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Services Market