
 US Sex Reassignment Surgery Market | 2026-2036
US Sex Reassignment Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
US Sex Reassignment Surgery Market Intelligence
Expanded insurance reimbursement and hospital-based financing programs is rewriting access dynamics for surgical providers. Cleveland Clinic leverages its integrated health system model to sustain high procedural volumes across multiple sites. Cedars-Sinai anchors its position through specialized fellowship training and dedicated gender-affirming surgical units. Mayo Clinic competes via destination medicine branding that attracts interstate patients seeking comprehensive perioperative coordination.
US sex reassignment surgery encompasses a spectrum of gender-affirming procedures including vaginoplasty, phalloplasty, chest reconstruction, and facial feminization, performed using microvascular free-flap techniques, implant-based reconstruction, and refined aesthetic contouring to align secondary sex characteristics with patient identity. These interventions serve both functional restoration and psychological well-being objectives within multidisciplinary care frameworks. Chest surgery dominates procedural frequency due to lower complexity and broader insurance authorization, while vaginoplasty commands premium reimbursement and extended operative timelines that concentrate margin pools at tertiary centers. Facial feminization is expanding fastest among younger demographics seeking non-genital procedures, with private practices capturing disproportionate share of this segment through boutique cash-pay models.
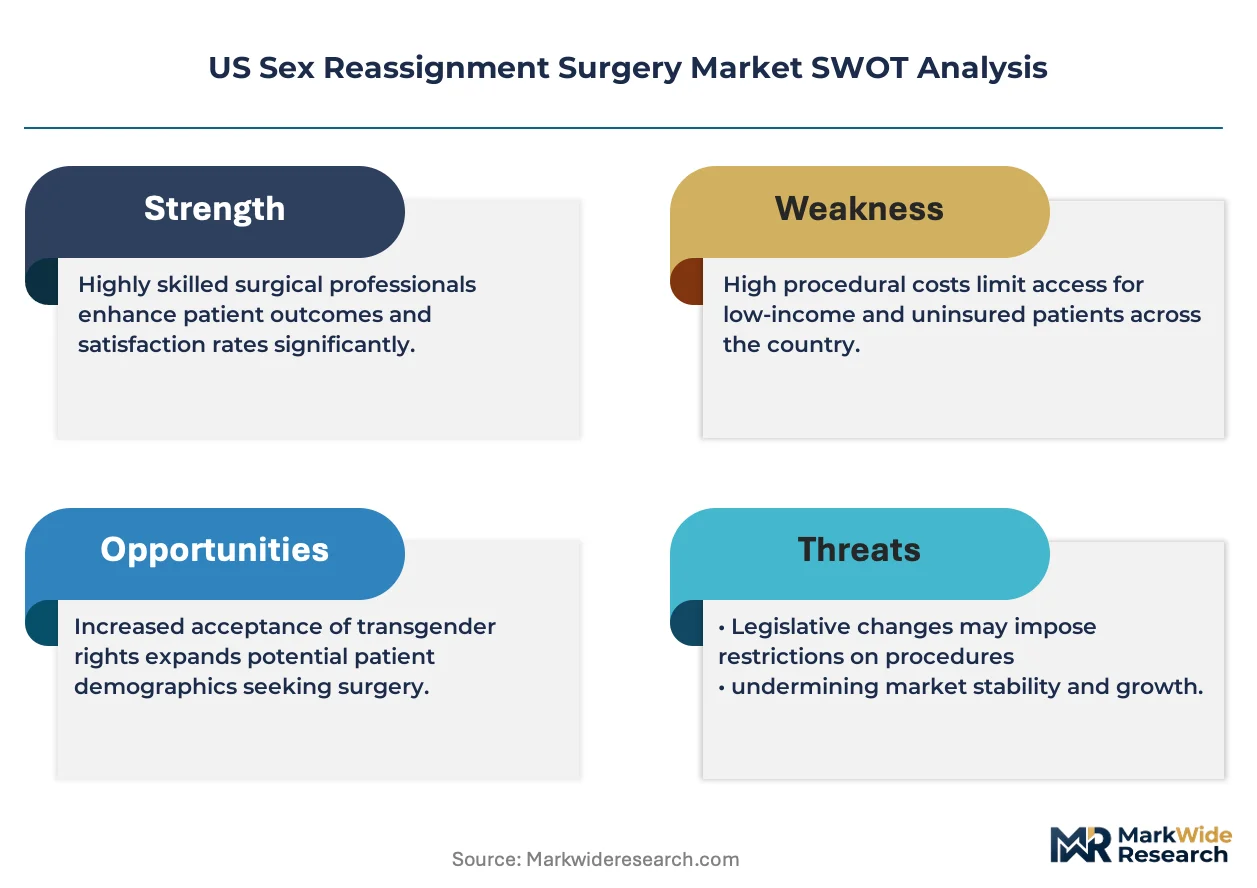
FDA oversight of surgical implants and devices intersects with state-level Medicaid policy variations and CMS National Coverage Determination frameworks to create uneven access geography across the US. OSHA standards for surgical suite staffing and HIPAA privacy protections further shape operational compliance costs and patient flow protocols. Stakeholders must monitor pending state legislation restricting gender-affirming care for minors, as these measures threaten to fragment referral networks and redirect patient migration patterns toward protective jurisdictions.
Market Dynamics
Medicaid expansion across progressive states is dismantling cost barriers that previously confined surgical access to affluent cash-pay patients, redirecting patient flows toward hospital systems with established gender-affirming programs and compressing margins at independent surgical practices.
Growth Catalysts
- Expanded Medicaid Coverage:Progressive state Medicaid programs now reimburse vaginoplasty and chest reconstruction procedures, removing financial barriers for younger patient cohorts. This policy shift concentrates demand at academic medical centers with established prior authorization workflows.
- Microvascular Free-Flap Advancement:Refined perforator flap techniques reduce donor-site morbidity in phalloplasty and vaginoplasty, expanding candidate pools for complex genital reconstruction. Tertiary centers with specialized reconstructive teams capture these high-complexity cases.
- Youth Demand Concentration:Patients under 30 now represent the fastest-growing surgical cohort, particularly for chest masculinization and facial feminization. This demographic shift favors providers with dedicated adolescent transition clinics and mental health integration.
Market Restraints
- Input Cost Volatility:Silicone implant prices fluctuate with medical-grade polymer supply chains, squeezing margins on breast augmentation and facial implant procedures. Independent practices lack volume leverage to negotiate stable vendor contracts.
- Regulatory Fragmentation:State-level restrictions on gender-affirming care for minors in conservative jurisdictions fragment referral networks. Patients must travel across state lines, creating administrative burdens for coordinating surgeons.
- Technical Limitation:Current phalloplasty techniques cannot reliably achieve tactile erogenous sensation comparable to cisgender anatomy. This functional ceiling limits patient satisfaction metrics and word-of-mouth referral generation.
Strategic Opportunities
- Telehealth Preoperative Coordination:Virtual consultation platforms enable interstate patient acquisition before travel for surgery. Mayo Clinic and Cleveland Clinic deploy this channel to capture patients from restrictive states.
- FDA 3D-Printed Implant Pathway:Custom facial implant fabrication via additive manufacturing promises patient-specific contouring. Early adopters in facial feminization can differentiate from standard implant portfolios.
- Destination Medicine Packaging:Comprehensive perioperative hospitality services attract patients from states with limited surgical capacity. Cedars-Sinai bundles housing, transportation, and postoperative nursing into premium offerings.
Industry Challenges
- Specialized Surgical Workforce Gap:Fellowship-trained gender-affirming surgeons remain concentrated at fewer than 20 academic centers nationwide. Community hospitals struggle to recruit qualified proceduralists.
- HIPAA Compliance Complexity:Interstate patient flows require coordination across state privacy frameworks with varying consent requirements. Electronic health record interoperability gaps create documentation friction.
- Prior Authorization Burden:Insurance denials for gender-affirming procedures necessitate dedicated administrative staff. Smaller practices cannot sustain the appeals workload required for Medicaid reimbursement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sex Reassignment Surgery Market |
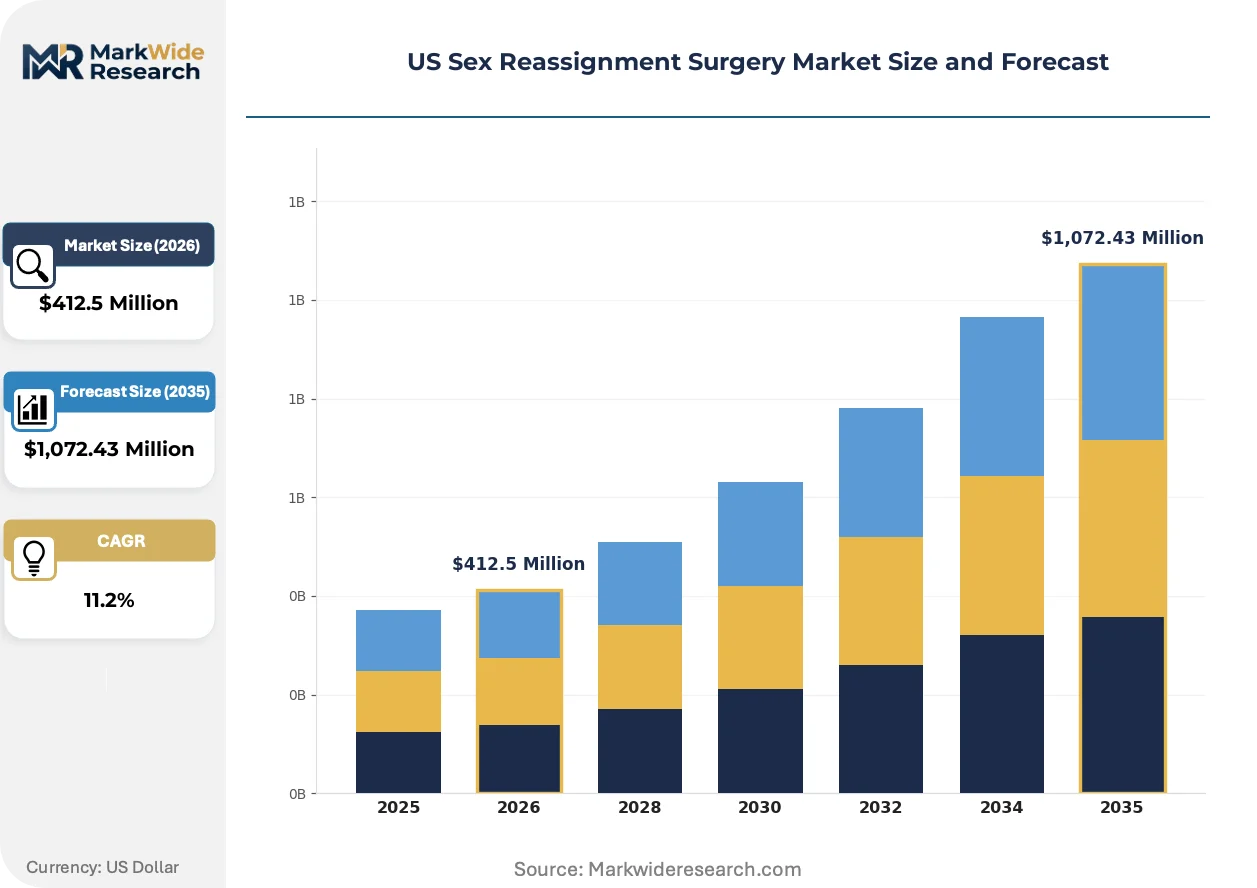
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,072.43 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Vaginoplasty, Phalloplasty, Chest Surgery, Facial Feminization End User: Hospitals, Clinics, Surgical Centers, Private Practices Patient Demographics: Transgender Women, Transgender Men, Non-Binary Individuals, Gender Non-Conforming Insurance Coverage: Private Insurance, Medicaid, Medicare, Out-of-Pocket |
| Companies Covered | Icahn School of Medicine at Mount Sinai, Cedars-Sinai, Cleveland Clinic, Boston Medical Center, Mayo Clinic, The Johns Hopkins University, Moein Surgical Arts, Kaiser Permanente, University of California, San Francisco Center of Excellence for Transgender Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sex Reassignment Surgery Market Strategic Shifts & Innovations
Preoperative planning workflows are digitizing rapidly, with three-dimensional imaging and virtual surgical simulation compressing revision rates and patient dissatisfaction. These technological and procedural shifts reshape competitive positioning among surgical providers.
Robotic-assisted microsurgery platforms are digitizing flap dissection and vessel anastomosis in phalloplasty and vaginoplasty procedures. Academic medical centers with capital equipment budgets deploy these systems to reduce operative time and surgeon fatigue. The technology is compressing the learning curve for complex genital reconstruction, enabling volume expansion at tertiary centers without proportional specialist hiring.
CMS National Coverage Determination frameworks intersect with state Medicaid policy variations to create uneven reimbursement geography. Progressive states with explicit gender-affirming care mandates secure federal matching funds for surgical coverage. Conservative states with exclusionary policies redirect patient migration toward protective jurisdictions, concentrating surgical volume at coastal academic centers.
Younger patients are compressing their surgical decision timelines, seeking chest reconstruction and facial feminization within months of social transition rather than years. This behavioral shift favors providers with streamlined intake protocols and minimal waitlists. Urban coastal markets with established LGBTQ+ health infrastructure capture this accelerated demand, while inland regions experience patient outmigration.
US Sex Reassignment Surgery Market Segmentation
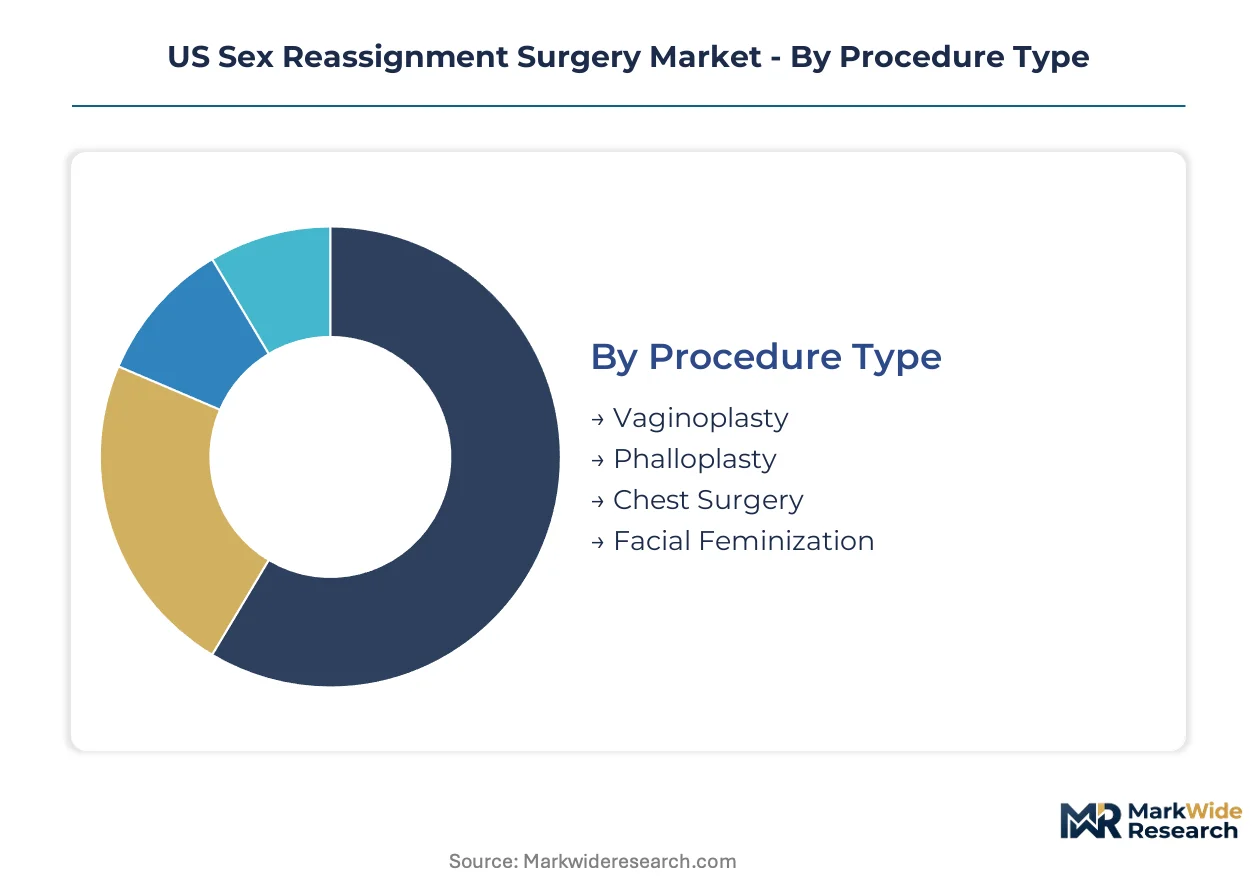
Segmentation in the US sex reassignment surgery market illuminates how reimbursement pathways, procedural complexity, and patient identity configurations concentrate margin pools and operational requirements across distinct provider ecosystems. Understanding these divides enables stakeholders to align capital deployment, workforce training, and regulatory compliance with specific demand clusters.
Procedure Type:
Cost tier stratification across genital and non-genital interventions determines reimbursement rates, operative duration, and the minimum viable scale for surgical programs.
- Vaginoplasty:Penile inversion or intestinal graft techniques construct neovaginal canal and vulvar anatomy. Tertiary centers in California and Massachusetts capture these high-reimbursement cases through dedicated microsurgical teams and extended postoperative nursing protocols.
- Phalloplasty:Radial forearm or anterolateral thigh free-flap construction creates neophallus with urethral extension and optional prosthetic implantation. Demand concentrates at Cleveland Clinic and Cedars-Sinai where specialized reconstructive fellowship pipelines sustain procedural volume.
- Chest Surgery:Subcutaneous mastectomy or implant-based reconstruction aligns thoracic contour with gender identity. Broader insurance authorization and lower technical barriers expand access to community hospitals and ambulatory surgical centers.
- Facial Feminization:Bony contouring, rhinoplasty, and soft-tissue refinement reduce masculine facial markers. Private practices in urban coastal markets capture disproportionate share through boutique cash-pay models targeting younger demographics.
Vaginoplasty commands the established base. The steepest expansion runs through facial feminization.
End User:
Facility type governs credentialing requirements, capital equipment access, and the scope of integrated perioperative services available to gender-affirming patients.
- Hospitals:Academic medical centers with Level I trauma designation host multidisciplinary gender-affirming programs combining surgery, endocrinology, and mental health. Medicaid reimbursement workflows and prior authorization infrastructure concentrate demand at these institutions.
- Clinics:Outpatient facilities affiliated with hospital systems deliver chest reconstruction and facial procedures under local or monitored anesthesia. Lower fixed costs enable competitive pricing for insured patients.
- Surgical Centers:Ambulatory settings handle implant-based breast augmentation and select chest masculinization cases with same-day discharge protocols.
- Private Practices:Independent surgeons offer facial feminization and minor revisions through direct-pay arrangements, bypassing insurance administrative burden.
Hospitals anchor the revenue base. Surgical centers are gaining share fastest through streamlined scheduling and reduced infection risk profiles.
Patient Demographics:
Identity-based demand segments exhibit distinct procedural preferences, insurance coverage rates, and geographic distribution patterns across the United States.
- Transgender Women:Patients assigned male at birth seeking feminization procedures including vaginoplasty, orchiectomy, and facial contouring. California and New York Medicaid programs explicitly cover these interventions, removing cost barriers.
- Transgender Men:Patients assigned female at birth pursuing chest masculinization, hysterectomy, and phalloplasty or metoidioplasty. Younger cohorts in Massachusetts and Washington compress decision timelines following social transition.
- Non-Binary Individuals:Patients seeking selective masculinization or feminization without full binary transition. Demand favors customizable surgical packages and mental health integration.
- Gender Non-Conforming:Patients with fluid or expansive gender expressions pursuing procedure combinations outside standard protocols. Smaller volume segment requiring individualized consent frameworks.
Transgender women represent the established surgical base. Transgender men are expanding most quickly through earlier social transition and improved chest surgery access.
Insurance Coverage:
Payment modality determines patient acquisition geography, administrative staffing requirements, and the competitive viability of independent versus hospital-affiliated practices.
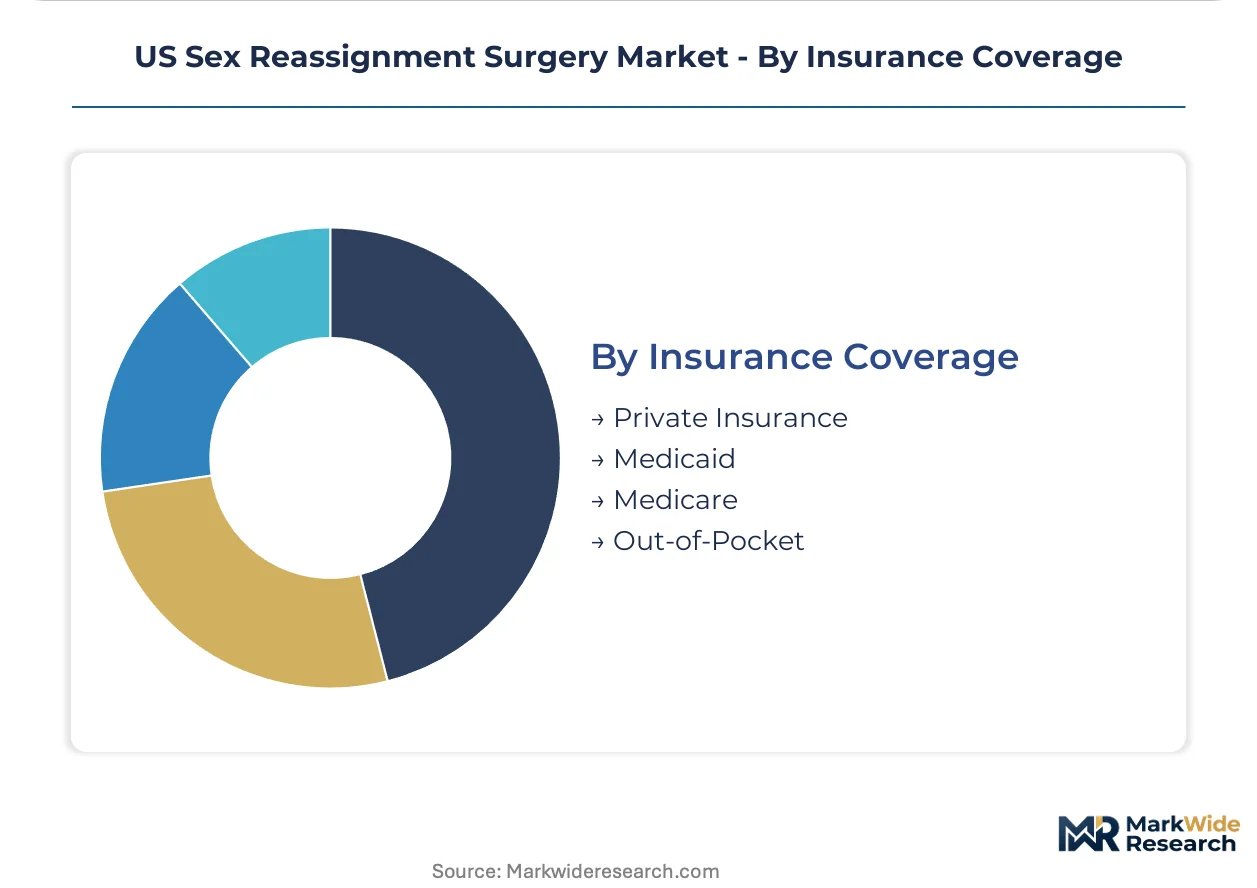
- Private Insurance:Employer-sponsored plans increasingly include gender-affirming surgery riders following federal nondiscrimination guidance. Prior authorization complexity favors established hospital programs with dedicated appeals staff.
- Medicaid:State-level expansion in progressive jurisdictions now reimburses vaginoplasty and chest reconstruction. Federal matching funds flow to California, New York, and Massachusetts programs.
- Medicare:Limited coverage for patients over 65 concentrates at academic centers with geriatric anesthesia expertise.
- Out-of-Pocket:Direct payment persists for facial feminization and revision procedures where insurance exclusions or aesthetic customization drive cash transactions.
Private insurance anchors current revenue. Medicaid expansion is climbing the fastest as state mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid expansion across progressive states is dismantling cost barriers that previously confined surgical access to affluent cash-pay patients, redirecting patient flows toward hospital systems with established gender-affirming programs and compressing margins at independent surgical practices.
California
California's Medicaid program explicitly covers vaginoplasty and chest reconstruction, removing financial barriers for transgender women and men. The state's Department of Health Care Services administers these benefits through managed care plans. Los Angeles and San Francisco anchor the highest surgical volumes, with Cedars-Sinai and UCSF Center of Excellence capturing concentrated demand.
New York
New York's Medicaid expansion includes comprehensive gender-affirming surgery coverage following state mandate implementation. The Department of Health oversees prior authorization workflows that favor academic medical centers. New York City and the Icahn School of Medicine at Mount Sinai sustain the densest cluster of fellowship-trained surgeons on the East Coast.
Massachusetts
Massachusetts combines Medicaid reimbursement with robust commercial insurance mandates for transgender healthcare. The state's Health Connector authority enforces nondiscrimination provisions in plan offerings. Boston Medical Center anchors New England's largest gender-affirming surgical program, drawing patients from neighboring restrictive states.
Washington
Washington's Apple Health Medicaid program covers chest masculinization and facial feminization for younger patient cohorts. The state's Health Care Authority manages utilization review processes that streamline access. Seattle's Pacific Northwest concentration supports Kaiser Permanente's integrated delivery model for coordinated perioperative care.
Illinois
Illinois Medicaid expansion under the ACA includes gender-affirming surgery benefits administered by the Department of Healthcare and Family Services. Chicago's metropolitan concentration supports Midwest surgical capacity, though patient outmigration toward coastal centers persists due to specialized workforce gaps.
US Sex Reassignment Surgery Market Key Industry Players
Channel-controlling players compete with product-specialist players across a bifurcated structure where academic medical centers capture Medicaid-reimbursed complex cases while private practices dominate cash-pay facial procedures. The market consolidates around tertiary centers with fellowship pipelines and microsurgical capabilities, compressing community hospital participation to lower-complexity chest interventions. Strategic archetypes include integrated health systems, destination medicine brands, and boutique cosmetic practices. Dominant competitive moves center on interstate patient acquisition through telehealth platforms and premium perioperative hospitality bundling.
Among integrated health system operators, Cleveland Clinic and Mayo Clinic exemplify the destination medicine archetype through multi-site coordination and interstate referral networks. Cedars-Sinai occupies a position within the specialized academic center tier, leveraging dedicated fellowship training and gender-affirming surgical units to sustain procedural volume. These three organizations represent the concentration of high-complexity genital reconstruction capacity nationwide.
| Leading Market Players |
|---|
| Icahn School of Medicine at Mount Sinai |
| Cedars-Sinai |
| Cleveland Clinic |
| Boston Medical Center |
| Mayo Clinic |
| The Johns Hopkins University |
| Moein Surgical Arts |
| Kaiser Permanente |
| University of California, San Francisco Center of Excellence for Transgender Health |
| Others |
Cost & Logistics Intelligence
Undercapacity at specialized microsurgical centers in California and Massachusetts drives both surgeon premium pricing and hospital system consolidation, compressing margins at independent practices unable to secure fellowship-trained proceduralists or negotiate silicone implant volume contracts with vendors.
Pricing Analysis
Certification level (ACGME fellowship completion and ASPS membership) creates the primary spread between academic medical center rates and community hospital pricing. Three-tier pricing structure across premium microsurgical genital reconstruction, standard chest surgery, and economy facial feminization segments reflects technical complexity and insurance reimbursement differentials. Pricing pressure stems from Medicaid expansion in progressive states requiring dedicated prior authorization staff that smaller practices cannot sustain. Cash-pay patients in facial feminization exhibit lowest price sensitivity, while Medicaid-dependent transgender men seeking chest masculinization face highest cost barriers where state coverage remains incomplete.
Supply Chain Analysis
Tariff exposure between China and the United States dominates medical-grade silicone supply risk for facial and chest implants. Manufacturing concentrates in Germany, Switzerland, and the United States for microsurgical instruments and FDA-cleared implant portfolios. Raw material dependencies span medical-grade polymers, titanium plating systems, and custom-fabricated dilators. Single-source vulnerability persists for specialized vaginoplasty graft materials sourced from limited European suppliers. Distribution runs through hospital system GPO contracts and direct manufacturer agreements with academic medical centers, bypassing independent surgical centers on complex genital reconstruction inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where regulatory entrenchment through Medicaid prior authorization workflows and ACGME fellowship pipelines creates sustainable competitive isolation for established academic centers.
For Market Incumbents: Entrench position by deepening microsurgical team capacity at existing sites rather than geographic expansion, and secure exclusive silicone implant vendor contracts to lock in supply cost advantages against emerging hospital competitors. State-level restrictions on gender-affirming care for minors threaten referral network fragmentation, making interstate telehealth preoperative coordination the critical defensive lever for patient retention. For New Entrants and Emerging Players: Establish a beachhead in facial feminization through cash-pay boutique models in urban coastal markets with established LGBTQ+ health infrastructure, bypassing Medicaid administrative burden entirely. Target non-binary individuals seeking selective procedure packages outside standard binary protocols, where customizable surgical offerings and mental health integration create differentiation from template-driven academic programs. Go-to-market positioning centers on accelerated intake timelines and minimal waitlists. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated health systems with destination medicine branding that captures interstate patient flows through bundled perioperative hospitality services. Long-term viability favors acquisition targets with established fellowship pipelines and microsurgical robotics capital equipment already deployed. Watch state Medicaid expansion announcements as the primary inflection signal for volume redistribution toward newly covered jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Fellowship Pipeline Expansion | ACGME-accredited training programs at Cleveland Clinic and Cedars-Sinai lock in specialized surgeon supply for complex genital reconstruction. |
| Telehealth Preoperative Platform | Virtual consultation infrastructure enables Mayo Clinic to capture interstate patients from restrictive states before travel for surgery. |
| Medicaid Prior Authorization Infrastructure | Dedicated administrative workflows at Boston Medical Center secure reimbursement for vaginoplasty and chest reconstruction in Massachusetts. |
| Robotic Microsurgery Capital Deployment | Academic medical centers with da Vinci systems compress operative time and learning curves for phalloplasty flap dissection. |
| Destination Medicine Hospitality Bundling | Cedars-Sinai packages housing, transportation, and postoperative nursing to attract patients from surgical deserts in conservative jurisdictions. |
Research Approach
Cross-validation between surgeon interviews at academic medical centers and secondary analysis of CMS National Coverage Determination frameworks anchors the qualitative findings. Primary fieldwork engaged gender-affirming surgical program directors, Medicaid prior authorization specialists, hospital GPO contracts managers, and biomedical engineers specializing in implant design. Secondary sources include FDA 510(k) filings for surgical devices, state Medicaid policy databases, hospital procurement records, and ACGME fellowship accreditation rosters. Bottom-up procedure volume estimates triangulate against top-down reimbursement flow analysis.
Calibration against historical Medicaid expansion patterns and surgical workforce graduation rates shapes the projection framework across the analysis window. Segmentation dimensions span procedure type complexity tiers, facility credentialing levels, patient demographic identity configurations, and state-level insurance coverage archetypes. CAGRs derive from elasticity modeling of reimbursement policy shifts and youth cohort surgical decision acceleration. Forecast inputs incorporate fellowship pipeline output trajectories and interstate patient migration elasticity to protective jurisdictions.
Stress conditions across state legislative restriction intensity, silicone implant supply disruption, and fellowship program expansion limits were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Medicaid matching fund continuity and ACGME accreditation stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market