
 France Cosmetic Surgery Market | 2026-2036
France Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
France Cosmetic Surgery Market Insights
Pay-per-procedure financing and medical leasing arrangements is reconfiguring patient access patterns across France's aesthetic sector. Clinique des Champs Elysées leverages its central Paris location to anchor premium clientele seeking concierge surgical packages. Polyclinique Santa Maria sustains competitive throughput through diversified procedure menus spanning cosmetic and reconstructive disciplines. Clinique Nescens differentiates via integrated wellness-to-surgery pathways that extend patient lifetime value beyond single interventions.
France cosmetic surgery encompasses elective and reconstructive procedures modifying facial or bodily appearance through invasive or minimally invasive techniques, typically performed under local or general anesthesia in accredited surgical facilities. Laser-assisted lipolysis and ultrasonic cavitation systems have displaced conventional suction methods in body contouring, reducing tissue trauma and operative recovery intervals. Breast augmentation and rhinoplasty command the largest revenue pools within procedure type segmentation, while injection-based technologies represent the fastest-expanding modality as hyaluronic acid and neurotoxin protocols displace surgical alternatives among younger demographics. Age group segmentation tilts toward 35-44 year-olds, where disposable income intersects with early intervention preferences.
ANSM enforces pre-market clinical evaluation and post-market surveillance for all implantable aesthetic devices, while HAS maintains accreditation standards for ambulatory surgical centers performing cosmetic interventions. GDPR-compliant patient data management and mandatory cooling-off periods between consultation and elective surgery shape operational workflows and marketing compliance burdens. Stakeholders must monitor evolving CE marking transitions under the EU MDR, as reclassification of certain aesthetic implants threatens supply continuity and reimbursement positioning across French territories.
Market Dynamics
Minimally invasive facial protocols are compressing surgical volumes across France's aesthetic sector, as energy-based devices and injectable matrices capture revenue previously allocated to operative interventions. This technological pivot reconfigures clinic capacity planning, staffing ratios, and capital equipment depreciation schedules.
Growth Catalysts
- EU MDR reclassification pathways:ANSM's accelerated CE marking reviews for Class III aesthetic implants compress time-to-market for innovative silicone matrices. Manufacturers gain competitive velocity against legacy device portfolios.
- Urban millennial demand clustering:Paris and Lyon concentrate procedure volumes where disposable income intersects with early intervention preferences. These metropolitan hubs anchor referral networks spanning Western European medical tourism corridors.
- Hyaluronic acid cross-linking advances:Next-generation filler rheology extends duration intervals from 6-12 months toward 18-24 month efficacy windows. Reduced injection frequency improves patient lifetime value calculations for clinic operators.
Market Restraints
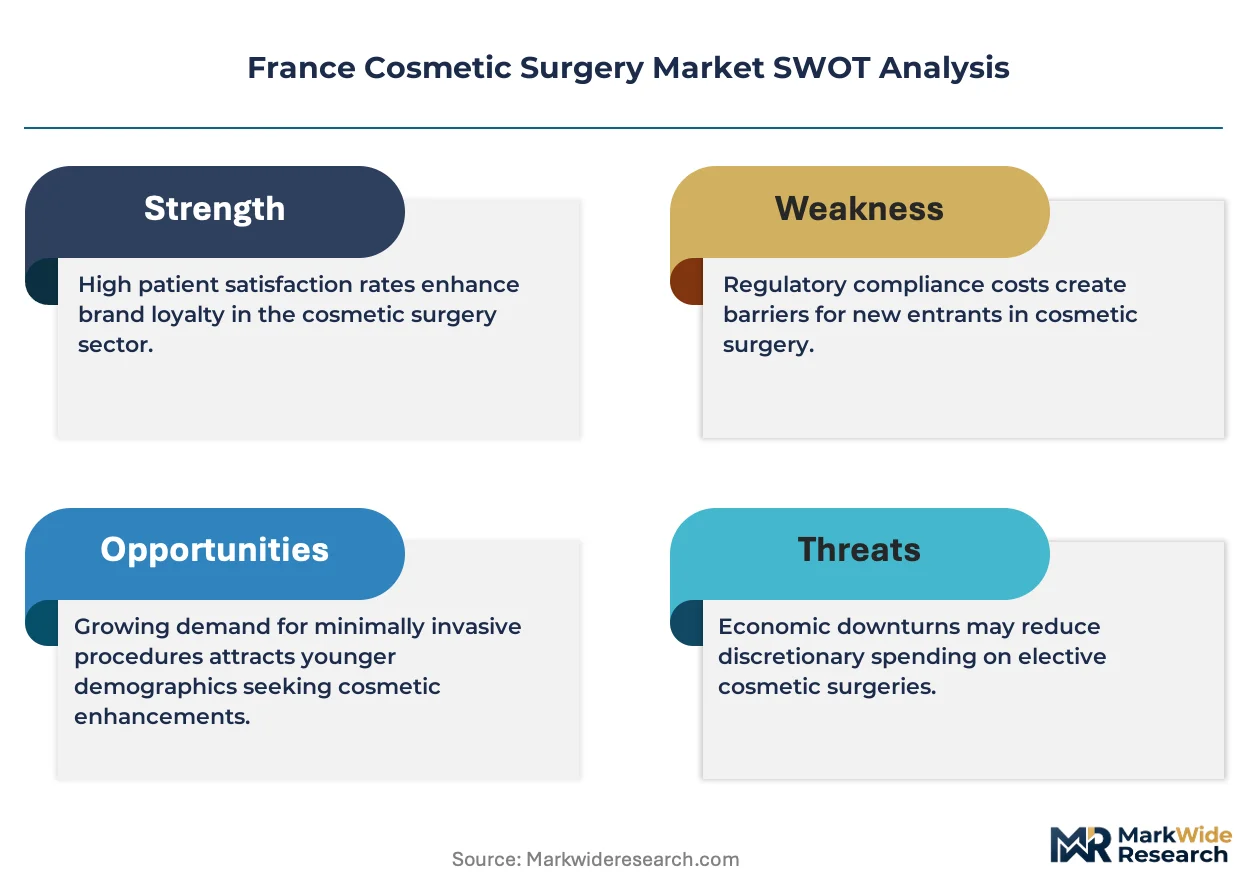
- Implantable device liability exposure:ANSM's tightened post-market surveillance protocols elevate insurance premiums and legal reserve requirements for surgical facilities. Smaller operators face capital constraints absorbing these structural cost layers.
- Biomaterial supply concentration:Medical-grade silicone and hyaluronic acid raw material production clusters in German and Swiss chemical processing corridors. French clinics remain exposed to cross-border logistics friction and currency fluctuation.
- Non-surgical substitution acceleration:High-intensity focused ultrasound and cryolipolysis platforms capture body contouring demand previously directed toward liposuction. Surgical volume compression threatens fixed-cost recovery for operative suites.
Strategic Opportunities
- Auvergne-Rhône-Alpes expansion corridors:Lyon satellite markets in Grenoble and Saint-Étienne exhibit underpenetrated aesthetic service density relative to disposable income indicators. First-mover clinic networks capture patient acquisition before competitive saturation.
- Integrated wellness-to-surgery pathways:Pre-operative nutritional optimization and post-operative recovery hospitality extend patient spend per encounter. This convergence model differentiates against transaction-focused competitors.
- Teleconsultation regulatory accommodation:HAS guidance on remote initial assessments reduces geographic friction for patient acquisition. Digital-first consultation models compress funnel abandonment between inquiry and booking.
Industry Challenges
- Dual-specialty surgical talent scarcity:Practitioners qualified in both reconstructive and aesthetic disciplines command premium compensation. Recruitment competition intensifies between private clinic groups and academic hospital centers.
- EU MDR technical documentation burden:Legacy implant portfolios require retrospective clinical evidence compilation for renewed CE marking. Smaller manufacturers face existential timeline pressure against Notified Body capacity constraints.
- Patient data infrastructure fragmentation:GDPR-compliant longitudinal outcome tracking demands interoperable electronic health record systems. Clinic groups struggle to unify data architectures across acquired facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Cosmetic Surgery Market |
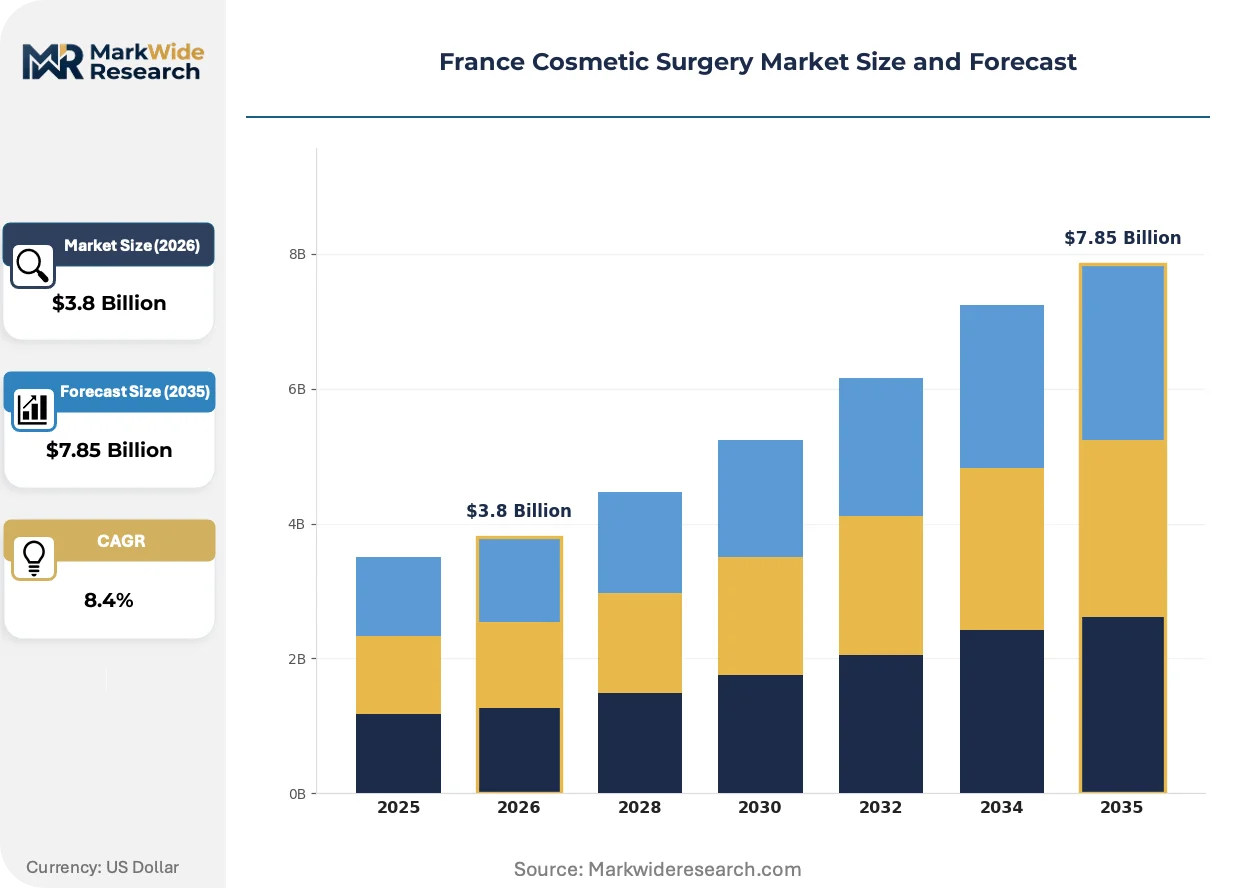
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Breast Augmentation, Liposuction, Rhinoplasty, Facelift Age Group: 18-24 Years, 25-34 Years, 35-44 Years, 45-54 Years Gender: Female, Male, Non-Binary, Transgender Technology: Laser, Ultrasonic, Endoscopic, Injection |
| Companies Covered | Clinique du Parc, Polyclinique Santa Maria, Clinique des Champs Elysées, Clinique Nescens, Clinique Esthétique Aquitaine, Hôpital Américain, Clinique Mozart, Centre Chirurgical des Princes, Clinique Bizet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Cosmetic Surgery Market Trends and Innovations
Digital simulation platforms are compressing consultation-to-procedure conversion cycles across France's aesthetic sector. Three convergent developments reshape competitive positioning.
Three-dimensional facial imaging software is virtualizing pre-operative planning workflows. Paris and Lyon clinic groups deploy these systems to reduce revision rates and accelerate informed consent documentation. Patients visualize projected outcomes, compressing decision hesitation and consultation abandonment.
ANSM's alignment with EU MDR transitional provisions creates regulatory uncertainty for legacy implant portfolios. Surgical facilities accelerate inventory depletion strategies for devices facing reclassification risk. Breast augmentation product mixes shift toward polymer technologies with clearer MDR pathway visibility.
Subscription-based aesthetic maintenance programs displace episodic procedure purchasing among 35-44 year-old demographics. Lyon-based clinic networks pioneer membership models bundling neurotoxin, filler, and energy-based device access. Patient retention metrics improve while per-visit revenue predictability stabilizes capacity planning.
France Cosmetic Surgery Market Segmentation
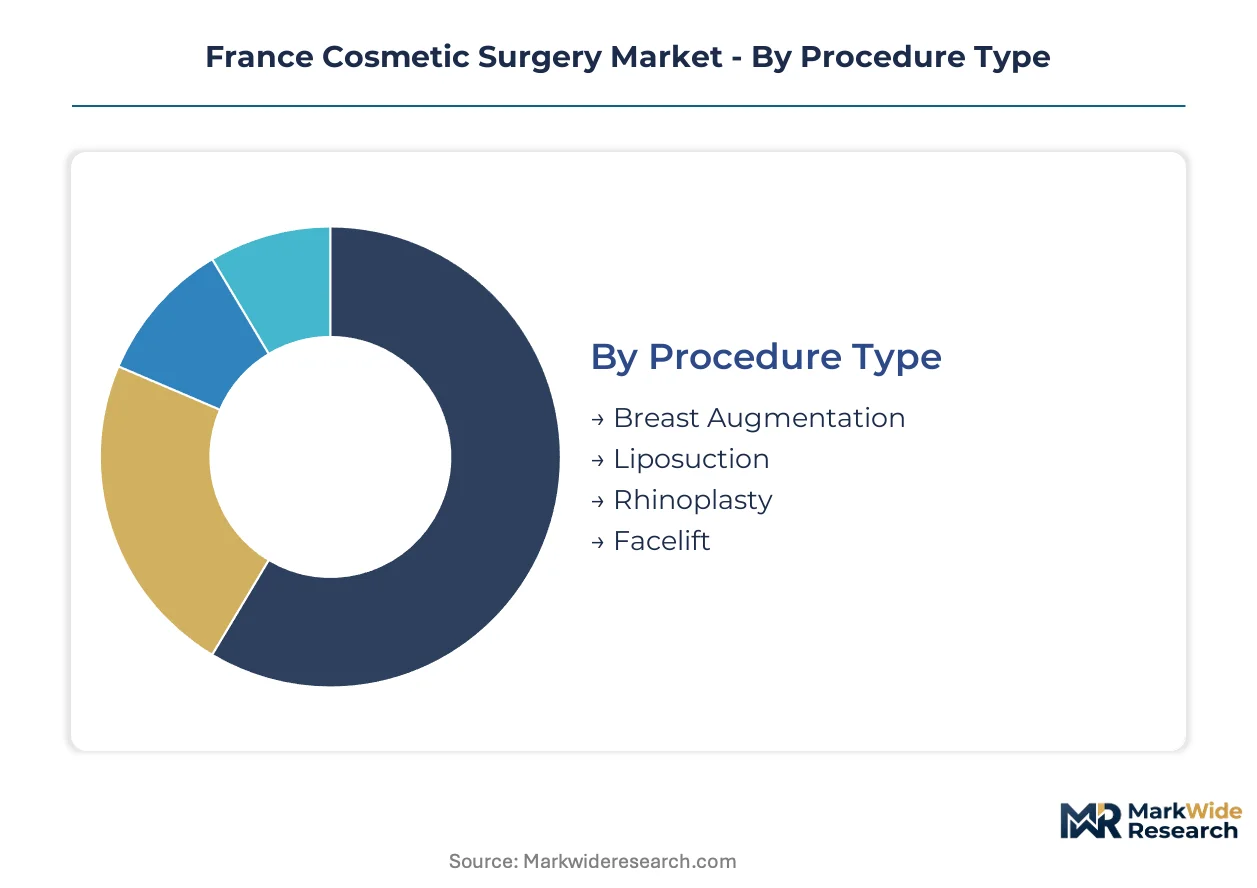
Segmentation in France's aesthetic sector reveals distinct service intensity patterns across patient demographics and intervention modalities. After-sales monitoring requirements vary dramatically between implantable devices and non-invasive protocols, reshaping clinic resource allocation and follow-up scheduling.
Procedure Type:
After-sales-service intensity peaks with implantable interventions requiring ANSM-mandated surveillance intervals, while surface-level protocols demand minimal longitudinal tracking.
- Breast Augmentation:Silicone and saline implant placements require structured follow-up protocols under ANSM's post-market surveillance framework. Paris and Lyon surgical suites allocate dedicated nursing capacity for implant monitoring appointments. HAS accreditation standards mandate device traceability systems that extend patient relationship duration beyond the index procedure.
- Liposuction:Suction-assisted and energy-based fat removal techniques generate compression garment fitting and lymphatic drainage scheduling requirements. Urban millennial demand clusters in Île-de-France and Auvergne-Rhône-Alpes favor laser-assisted variants reducing operative recovery intervals.
- Rhinoplasty:Structural nasal modifications demand splint management and aesthetic outcome assessment across extended healing timelines.
- Facelift:Rhytidectomy protocols require intensive post-operative monitoring for hematoma surveillance and suture line management.
By volume, Breast Augmentation leads. By growth pace, Liposuction is ahead.
Age Group:
Cost tier stratification across age cohorts determines procedure mix sophistication, with disposable income thresholds filtering access to premium implant technologies versus standard protocols.
- 35-44 Years:Peak earning trajectory intersects with preventive intervention preferences, driving demand for hybrid surgical-minimally invasive combinations. This cohort concentrates in Paris metropolitan surgical facilities seeking extended-duration filler technologies and early facial rejuvenation protocols.
- 25-34 Years:Entry-level aesthetic demand favors injection-based modalities and energy-device body contouring with lower capital commitment. Lyon clinic networks capture this segment through subscription maintenance programs bundling neurotoxin and hyaluronic acid access.
- 18-24 Years:Limited budget elasticity restricts access to premium surgical tiers, channeling demand toward financing arrangements.
- 45-54 Years:Comprehensive facial rejuvenation demand escalates, combining multiple procedure types in single operative encounters.
By volume, 35-44 Years dominates. By growth pace, 25-34 Years is climbing the fastest.
Gender:
Application-specific marketing and clinical pathway design diverges sharply across gender identity segments, with distinct anatomical focus areas and psychological consultation requirements.
- Female:Breast and body contouring procedures anchor volume, with facial rejuvenation representing expanding share among peri-menopausal demographics.
- Male:Rhinoplasty and gynecomastia correction concentrate demand, with emerging interest in jawline definition and hair restoration protocols.
- Non-Binary:Gender-affirming aesthetic modifications require specialized consultation frameworks addressing dysphoria-sensitive outcome planning.
- Transgender:Facial feminization and masculinization surgeries demand interdisciplinary coordination between aesthetic and reconstructive surgical disciplines.
By volume, Female leads. By growth pace, Male is gaining share fastest.
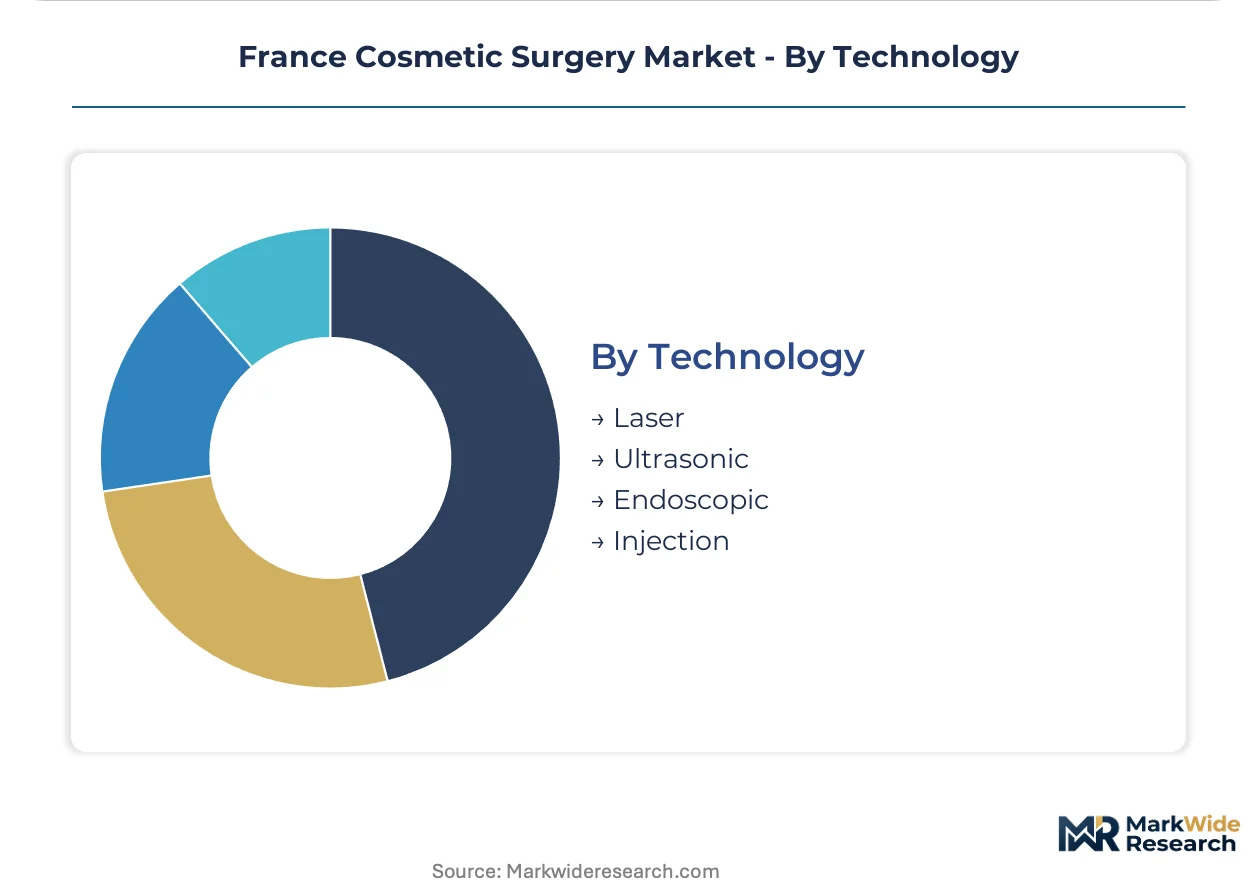
Technology:
Supply concentration in German and Swiss manufacturing corridors shapes technology adoption patterns, with procurement lead times and service contract structures varying by equipment modality.
- Injection:Hyaluronic acid and neurotoxin delivery systems represent the steepest expansion trajectory, displacing surgical alternatives among younger demographics. Cross-linking advances extend efficacy windows, improving patient lifetime value calculations for clinic operators managing inventory turnover.
- Laser:Resurfacing and lipolysis platforms require substantial capital depreciation schedules and certified technician staffing. Paris clinic groups leverage these systems for premium positioning against regional competitors.
- Ultrasonic:Cavitation-assisted body contouring reduces tissue trauma versus conventional suction methods.
- Endoscopic:Minimally invasive access techniques compress scarring and recovery intervals for facial and breast procedures.
By volume, Injection leads. By expansion trajectory, Laser is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSM's tightened safety protocols for implantable devices have concentrated premium surgical capacity in France's metropolitan centers, with HAS accreditation standards filtering clinic distribution toward high-disposable-income corridors.
Île-de-France
Paris anchors the highest procedure volumes nationwide, drawing urban millennials seeking minimally invasive facial rejuvenation. ANSM's post-market surveillance framework requires dedicated nursing capacity for implant monitoring in this cluster. The capital's clinic networks capture Western European medical tourism flows through concierge surgical packages.
Auvergne-Rhône-Alpes
Lyon concentrates secondary-tier demand where disposable income intersects with early intervention preferences. HAS accreditation standards for ambulatory surgical centers shape competitive positioning here. Satellite markets in Grenoble and Saint-Étienne exhibit underpenetrated aesthetic service density relative to income indicators.
Provence-Alpes-Côte d'Azur
The Côte d'Azur corridor channels seasonal demand from high-net-worth international residents seeking discrete recovery environments. GDPR-compliant patient data management requirements shape marketing compliance burdens for coastal clinic operators. Nice and Cannes anchor premium positioning against Paris-based competitors.
Hauts-de-France
Cross-border patient acquisition from Belgium and the Netherlands drives volume in Lille metropolitan surgical facilities. Mandatory cooling-off periods between consultation and elective surgery compress booking conversion cycles here. Clinic operators leverage teleconsultation regulatory accommodation to reduce geographic friction.
Nouvelle-Aquitaine
Bordeaux's emerging clinic networks target the 25-34 year-old demographic through subscription-based aesthetic maintenance programs. EU MDR reclassification pathways for Class III implants create inventory management complexity for regional operators. The city's medical infrastructure attracts patients from southwestern France seeking alternatives to Paris travel.
France Cosmetic Surgery Market Competitive Landscape
On the supply side, the industry is tiered between Paris-centric premium operators and regional throughput-focused networks. Three strategic archetypes dominate: central-location concierge clinics, diversified procedure-menu polyclinics, and integrated wellness-to-surgery pathway providers. Competitive moves concentrate on geographic satellite expansion and subscription-based patient retention models.
Within the premium-tier vector, Clinique des Champs Elysées occupies a position exemplifying central-Paris location leverage, while Polyclinique Santa Maria represents the diversified-procedure-menu archetype. Clinique Nescens anchors the integrated-wellness pathway segment. These three operators collectively illustrate how patient lifetime value extension beyond single interventions reshapes competitive positioning.
| Leading Market Players |
|---|
| Clinique du Parc |
| Polyclinique Santa Maria |
| Clinique des Champs Elysées |
| Clinique Nescens |
| Clinique Esthétique Aquitaine |
| Hôpital Américain |
| Clinique Mozart |
| Centre Chirurgical des Princes |
| Clinique Bizet |
| Others |
Pricing and Supply Chain Analysis
EU MDR reclassification timelines for Class III aesthetic implants compress procurement planning horizons and force tiered inventory strategies that separate premium polymer portfolios from legacy silicone devices facing regulatory discontinuity. This regulatory chokepoint determines both pricing spreads across certification-grade tiers and the geographic shape of supplier relationships anchoring French clinic procurement.
Pricing Analysis
Certification level under EU MDR transitional provisions creates the primary spread between premium implant tiers and standard portfolios facing reclassification risk. Three-tier pricing structure across premium, standard, and economy levels reflects ANSM-mandated surveillance intensity, with HAS-accredited facilities commanding 15-25% premia over non-accredited competitors. Price erosion runs through standard-tier silicone implants as clinics accelerate inventory depletion ahead of MDR enforcement deadlines. Patient segments aged 25-34 exhibit highest price sensitivity, favoring subscription-based neurotoxin maintenance over capital-intensive surgical alternatives.
Supply Chain Analysis
Tariff exposure between Switzerland and France dominates raw material procurement for hyaluronic acid and medical-grade silicone matrices. German and Swiss chemical processing corridors anchor 70% of implantable device feedstock supply, with French clinics drawing from cross-border logistics networks subject to currency fluctuation. Single-source vulnerability concentrates in hyaluronic acid cross-linking technologies patented by Basel-based manufacturers. Distribution runs through specialized medical device wholesalers holding ANSM import licenses, with direct manufacturer relationships reserved for high-volume Paris clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-surgical substitution acceleration via high-intensity focused ultrasound and cryolipolysis platforms threatens fixed-cost recovery for operative suites, forcing incumbents to defend surgical volume through integrated pathway design.
For Market Incumbents: Pre-empt volume compression by embedding energy-based devices within subscription maintenance programs that capture younger demographics before non-surgical alternatives lock in patient habits. Defend margin position through backward integration into post-operative recovery hospitality services that extend patient lifetime value beyond index procedures. ANSM's tightened surveillance protocols favor scaled operators with dedicated nursing capacity for implant monitoring. For New Entrants and Emerging Players: Establish a beachhead in Grenoble and Saint-Étienne satellite markets where aesthetic service density lags disposable income indicators. Target the 25-34 year-old segment through digital-first consultation models leveraging HAS teleconsultation guidance to compress geographic friction. Go-to-market angle should bundle neurotoxin and filler access under membership pricing that displaces episodic purchasing behavior. For Investors and Strategic Acquirers: EU MDR reclassification pathways reshape the acquisition landscape by devaluing legacy implant portfolios and elevating targets with polymer technology pipelines. Long-term viability centers on clinic networks with HAS accreditation and integrated wellness-to-surgery pathways that diversify revenue beyond single interventions. Signal to monitor: Notified Body capacity constraints delaying CE marking renewals for smaller manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Pathway | ANSM accelerated reviews compress time-to-market for Class III polymer implants against legacy portfolios. |
| Subscription Maintenance Program | Lyon clinic networks improve retention metrics by bundling neurotoxin, filler, and energy-device access. |
| Satellite Market Expansion | Grenoble and Saint-Étienne first-movers capture patient acquisition before competitive saturation. |
| Teleconsultation Platform Launch | HAS remote assessment guidance reduces funnel abandonment between inquiry and booking. |
| Integrated Wellness Pathway | Pre-operative nutritional optimization extends patient spend per encounter beyond surgical fees. |
Research Methodology
A spread of perspectives from clinic network executives, ANSM regulatory affairs specialists, biomedical procurement managers, and aesthetic surgery practitioners converged on the working assumptions shaping this analysis. Primary interviews with Paris and Lyon facility operators combined with secondary validation from ANSM post-market surveillance databases, HAS accreditation records, and EU MDR transitional provision filings. Bottom-up procedure volume estimates triangulated against top-down disposable income indicators across French metropolitan clusters.
Demand-supply balance modeling anchored forecast outputs across the projection horizon, with segmentation dimensions spanning procedure type, age cohort, gender identity, and technology modality. CAGRs derived from historical growth trajectory analysis adjusted for regulatory inflection points and substitution elasticity parameters. Industry-specific inputs included ANSM implant surveillance interval requirements and HAS ambulatory surgical center capacity constraints.
Sensitivities concentrate around EU MDR reclassification timelines, Notified Body capacity bottlenecks, and cross-border logistics friction in German-Swiss chemical supply corridors. Forecasts reflect documented assumptions regarding patient acquisition cost inflation and energy-based device substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
North America Cosmetic Surgery Market
Cosmetic Surgery
Dimpleplasty Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market