
 Brachioplasty Market | 2026-2036
Brachioplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Brachioplasty Market Analytics
Board-certified plastic surgeon credentialing is redrawing competitive boundaries in aesthetic arm surgery. Allergan (AbbVie) leverages its injectables portfolio to cross-sell complementary body contouring solutions. Integra LifeSciences anchors its position through advanced wound care and regenerative technologies that support post-operative recovery protocols. Johnson & Johnson competes across the surgical continuum with sutures and hemostasis products tailored to soft tissue reconstruction.
Brachioplasty denotes surgical reshaping of the upper arm through excision of redundant skin and subcutaneous fat, typically requiring incision lengths of 8–20 cm along the medial brachial groove with closure under tension-reducing techniques. The procedure addresses functional impairment and aesthetic deformity following massive weight loss or age-related dermatochalasia. Minimal incision brachioplasty captures expanding demand among patients seeking reduced scar burden, while liposuction-assisted variants dominate cases with moderate adiposity and good skin elasticity. Cosmetic clinics represent the fastest-growing end user channel as ambulatory surgical centers invest in dedicated body contouring suites.
FDA premarket notification requirements for surgical mesh materials shape product development timelines and clinical evidence burdens for manufacturers. The American Society of Plastic Surgeons practice guidelines influence payer coverage determinations and facility accreditation standards. Stakeholders must monitor evolving state-level scope-of-practice regulations that govern whether dermatology practices and day surgery centers may independently perform excisional arm contouring procedures.
Market Dynamics
Board-certified plastic surgeon credentialing requirements are tightening across ambulatory surgical centers, compressing the pool of qualified providers capable of performing excisional arm contouring procedures under tension-reducing closure protocols.
Growth Catalysts
- Post-bariatric patient volumes:Massive weight loss procedures in the United States are generating sustained demand for redundant skin excision, with cosmetic clinics in California and Florida expanding dedicated body contouring suites to capture this patient flow.
- MDR compliance pathways:The EU Medical Device Regulation's enhanced clinical evidence requirements for surgical mesh materials are accelerating manufacturer investment in bioresorbable suture technologies that reduce long-term foreign body burden.
- Minimal incision techniques:Liposuction-assisted brachioplasty variants are capturing patients with moderate adiposity and retained skin elasticity, broadening the addressable candidate pool beyond traditional excisional candidates.
Market Restraints
- Silicone mesh supply concentration:Surgical mesh raw material production clusters among three specialized chemical processors in Germany and Switzerland, creating vulnerability to export licensing disruptions.
- FDA premarket notification burdens:The agency's tightened 510(k) evidentiary standards for absorbable suture materials are extending product development timelines by eighteen to thirty-six months for novel polymer formulations.
- Non-surgical substitution:Cryolipolysis and radiofrequency skin tightening devices are capturing patients with mild-to-moderate arm laxity, compressing the lower-complexity segment of the surgical pipeline.
Strategic Opportunities
- Day surgery center expansion:Dermatology practices in Texas and Arizona are pursuing scope-of-practice regulatory amendments to permit independent performance of limited-incision arm contouring procedures.
- Regenerative adjunct protocols:Platelet-rich plasma and autologous fat grafting are converging with traditional excisional techniques to improve scar quality and contour refinement in high-visibility patient populations.
- Medicaid carve-outs:Several state Medicaid programs are piloting coverage for functional brachioplasty following documented intertrigo or mobility impairment, creating new reimbursement pathways previously restricted to cosmetic self-pay.
Industry Challenges
- Microsurgical fellowship pipeline:The declining completion rate of advanced aesthetic surgery fellowships is constraining the supply of surgeons trained in tension-reducing closure and scar optimization techniques.
- Facility accreditation timelines:AAAASF and Medicare certification processes for standalone body contouring suites require twelve-to-eighteen-month capital deployment cycles before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brachioplasty Market |
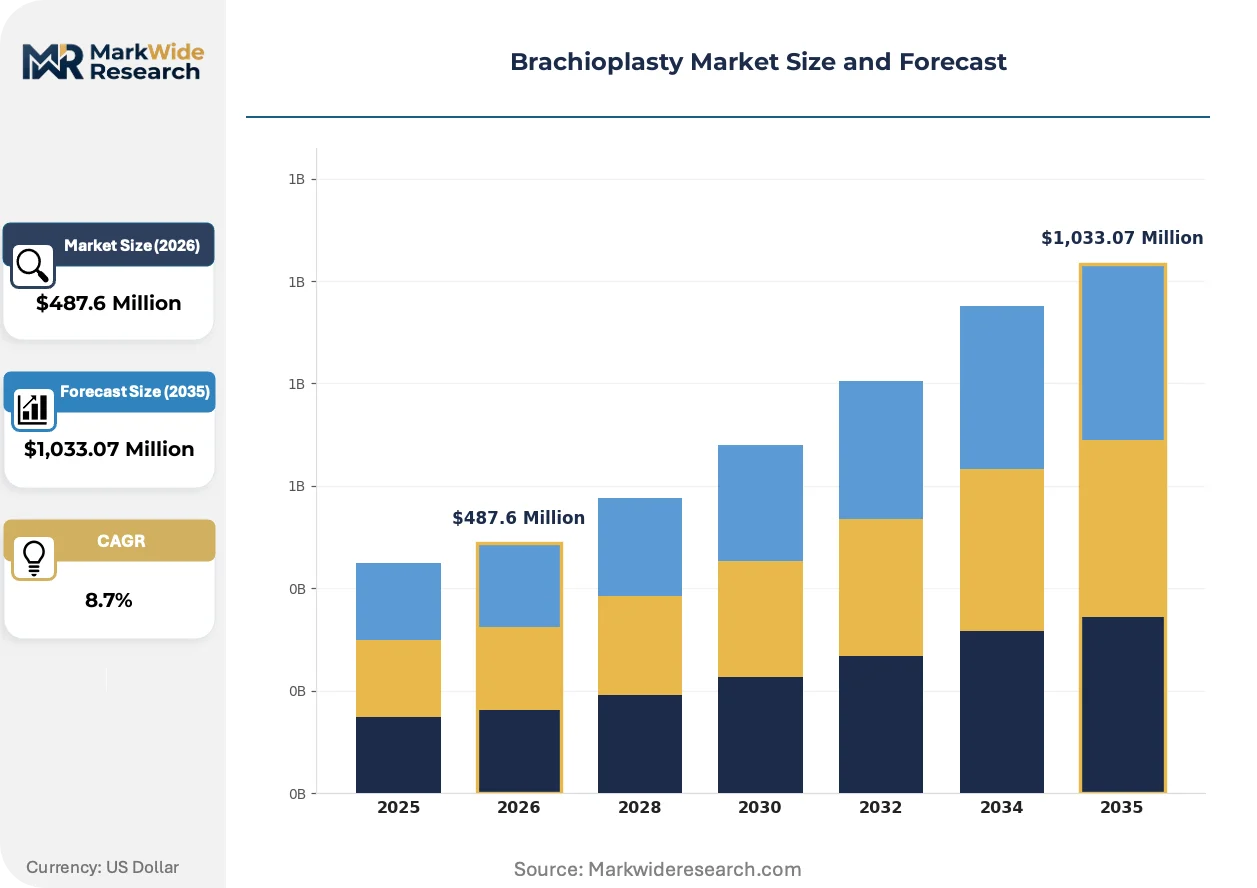
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Traditional Brachioplasty, Minimal Incision Brachioplasty, Double Incision Brachioplasty, Liposuction-assisted Brachioplasty Indication: Skin Sagging, Weight Loss, Aging, Body Contouring Material Used: Silicone Implants, Sutures, Surgical Mesh, Local Anesthesia End User: Cosmetic Clinics, Hospitals, Day Surgery Centers, Dermatology Practices |
| Companies Covered | Allergan (AbbVie), Integra LifeSciences, Johnson & Johnson, B. Braun Melsungen, Mindray Medical, Cynosure LLC, Alma Lasers, New York Plastic Surgical Group, Westlake Dermatology & Cosmetic Surgery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brachioplasty Market Evolving Landscape
Arm contouring is experiencing simultaneous pressure toward less invasive techniques and more rigorous outcome documentation, with technology vendors and surgical facilities racing to align product portfolios with evolving patient risk tolerance.
Barbed suture technology is fragmenting traditional closure material markets. These self-anchoring polydioxanone constructs distribute tension across the wound length without knot stacking. High-volume cosmetic surgery centers in Miami and Los Angeles are adopting barbed systems for fifty to sixty percent of brachioplasty closures. The technology is fragmenting market share among established monofilament suppliers while enabling faster operative times and reduced suture extrusion rates.
FDA's updated guidance on absorbable surgical sutures is reshaping clinical trial design requirements. The document mandates extended biocompatibility testing for novel polymer degradation profiles. Manufacturers targeting the soft tissue reconstruction segment are responding with parallel-track regulatory strategies that pursue CE marking under MDR while accumulating US clinical data, prioritizing European market entry to sustain revenue during FDA review cycles.
Patients are compressing their decision timelines through direct-to-clinic digital consultation platforms. Virtual assessment tools using standardized photography protocols are displacing traditional in-person screening visits in the patient acquisition funnel. This behavioral shift is most pronounced in coastal metropolitan markets where cosmetic surgery practices have integrated three-dimensional simulation software into their scheduling workflows, reducing consultation-to-procedure intervals by forty percent.
Brachioplasty Market Segmentation
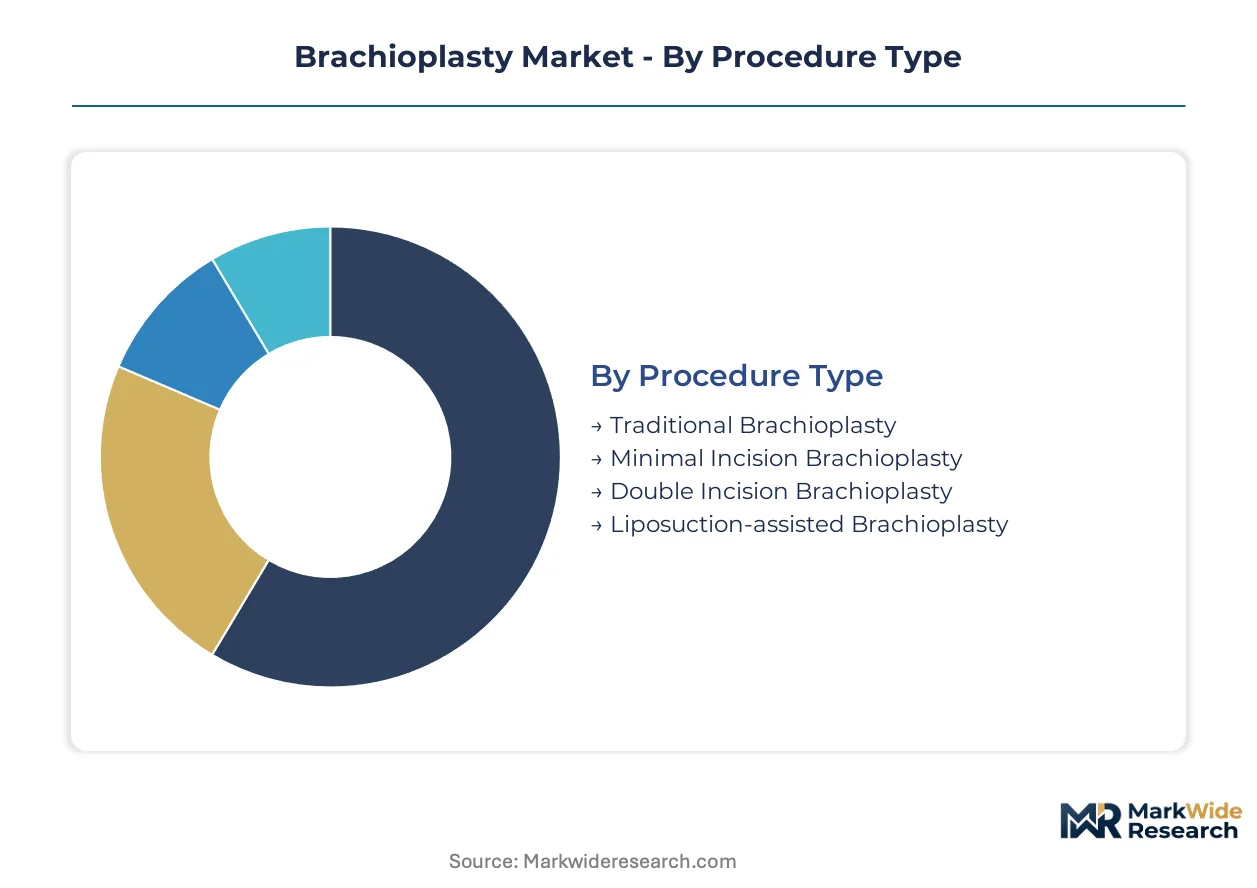
Brachioplasty procedure selection hinges on patient tissue quality and scar tolerance, with channel preferences diverging sharply between hospital-based reconstruction and ambulatory cosmetic surgery. Material suppliers and device manufacturers calibrate portfolio investments against these segment boundaries.
Procedure Type:
Channel economics favor traditional excisional techniques in hospital outpatient departments where bundled reimbursement covers longer operative times, while minimal incision variants flow through cosmetic clinics seeking higher patient turnover.
- Traditional Brachioplasty:Full-length medial arm incision with wide undermining and layered closure addresses severe dermatochalasia. California and Florida cosmetic clinics report highest volumes for post-bariatric reconstruction where skin excess exceeds ten centimeters.
- Minimal Incision Brachioplasty:Limited axillary incision with liposuction adjunct reduces scar burden. Texas day surgery centers are capturing demand from patients prioritizing concealment over maximal tissue excision.
- Double Incision Brachioplasty:Medial and lateral incisions address circumferential laxity.
- Liposuction-assisted Brachioplasty:Suction lipectomy with limited skin resection suits moderate adiposity cases.
Traditional brachioplasty dominates installed base. Minimal incision brachioplasty is where expansion concentrates.
Indication:
Reimbursement pathways split sharply between functional indications qualifying for insurance coverage and purely aesthetic motivations requiring self-pay arrangements.
- Skin Sagging:Age-related dermatochalasia drives demand among patients over fifty-five. Medicare Advantage plans in select states are piloting prior authorization pathways for documented functional impairment.
- Weight Loss:Massive weight loss following bariatric surgery generates the most complex cases. Florida cosmetic clinics have built dedicated post-bariatric protocols capturing this patient flow.
- Aging:Gradual collagen depletion creates incremental demand.
- Body Contouring:Elective aesthetic enhancement without functional indication.
Weight loss indication anchors revenue per procedure. Skin sagging is climbing the fastest as demographic shifts expand the candidate pool.
Material Used:
Procurement patterns bifurcate between premium bioresorbable systems in high-margin cosmetic channels and cost-optimized standard materials in institutional settings.
- Sutures:Absorbable monofilament and barbed polydioxanone constructs constitute the largest material spend category. Barbed systems are gaining share fastest in Miami and Los Angeles cosmetic surgery centers.
- Surgical Mesh:Synthetic and biologic meshes provide reinforcement for high-tension closures. FDA's tightened 510(k) evidentiary standards are extending development timelines for novel polymer formulations.
- Silicone Implants:Limited application in arm contouring.
- Local Anesthesia:Tumescent solutions enable awake procedures in office-based settings.
Sutures dominate material procurement volume. Surgical mesh is where manufacturer R&D investment concentrates.
End User:
Facility type determines regulatory burden, reimbursement eligibility, and capital intensity requirements for market participants.
- Cosmetic Clinics:Dedicated aesthetic surgery centers with AAAASF accreditation capture the highest-margin cases. California and Florida lead expansion of body contouring suites.
- Day Surgery Centers:Medicare-certified ambulatory facilities perform functional brachioplasty under hospital outpatient prospective payment. Texas and Arizona centers are pursuing scope-of-practice amendments for limited-incision procedures.
- Hospitals:Academic medical centers manage complex post-bariatric reconstruction.
- Dermatology Practices:Office-based settings with limited surgical privileges.
Cosmetic clinics dominate premium pricing capture. Day surgery centers are gaining share fastest as scope-of-practice regulations evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical processors in Germany and Switzerland dominate surgical mesh raw material production, concentrating supply risk for manufacturers dependent on silicone-based reinforcement materials. This geographic clustering shapes procurement strategies and regulatory filing patterns across the brachioplasty supply chain.
United States
FDA tightened 510(k) evidentiary standards for absorbable suture materials, extending development timelines for novel polymer formulations. California and Florida cosmetic clinics are expanding dedicated body contouring suites to capture post-bariatric patient flows. Miami and Los Angeles high-volume centers now adopt barbed suture systems for fifty to sixty percent of brachioplasty closures.
Germany
EU MDR compliance pathways for surgical mesh materials are accelerating manufacturer investment in bioresorbable suture technologies. The country's national pharmaceutical regulator enforces enhanced clinical evidence requirements that exceed pre-2017 directive standards. Specialized chemical processors in industrial clusters supply raw silicone materials to global mesh manufacturers.
Switzerland
Swissmedic oversees stringent device certification processes that influence European market entry strategies for suture and mesh suppliers. The country's chemical processing sector anchors continental supply for surgical mesh polymers. Basel-area manufacturers are prioritizing bioresorbable formulations to reduce long-term foreign body burden in soft tissue reconstruction.
Brazil
ANVISA regulatory frameworks govern import licensing for surgical materials used in post-bariatric reconstruction procedures. São Paulo cosmetic surgery centers are developing protocols for massive weight loss patients with severe dermatochalasia. Rio de Janeiro clinics report rising demand for minimal incision techniques among patients prioritizing scar concealment.
South Korea
MFDS certification requirements for absorbable medical devices shape product development timelines for regional manufacturers. Seoul Capital Area aesthetic surgery practices are integrating three-dimensional simulation software into patient acquisition workflows. Busan-Ulsan medical device distributors are expanding portfolios to include tension-reducing closure systems.
Brachioplasty Market Competitive Landscape
Concentration sits with diversified medical device conglomerates that cross-leverage surgical material portfolios across multiple soft tissue reconstruction applications. The competitive structure tiers between premium suture and mesh specialists, integrated wound care platforms, and aesthetic device manufacturers seeking procedural adjacencies. Dominant competitive moves include portfolio diversification into complementary body contouring solutions and regulatory parallel-tracking that prioritizes European market entry during extended FDA review cycles.
Among diversified healthcare conglomerates, Johnson & Johnson and B. Braun Melsungen exemplify integrated surgical material suppliers that span sutures, hemostasis, and soft tissue reconstruction categories. Allergan (AbbVie) occupies a position at the aesthetic-procedural intersection, leveraging injectables portfolios to cross-sell complementary body contouring offerings. Integra LifeSciences represents the wound care and regenerative technology archetype, anchoring post-operative recovery protocols that support tension-reducing closure techniques.
| Leading Market Players |
|---|
| Allergan (AbbVie) |
| Integra LifeSciences |
| Johnson & Johnson |
| B. Braun Melsungen |
| Mindray Medical |
| Cynosure LLC |
| Alma Lasers |
| New York Plastic Surgical Group |
| Westlake Dermatology & Cosmetic Surgery |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German silicone processors and mesh manufacturers lock in both raw material access and eighteen-to-thirty-six month price visibility for absorbable suture development cycles. These contracts insulate high-volume cosmetic surgery centers from spot market volatility while exposing smaller day surgery centers to procurement cost compression.
Pricing Analysis
FDA's tightened 510(k) evidentiary standards dictate the pricing tier structure across brachioplasty material procurement. Three-tier pricing structure across premium, standard, and economy levels separates barbed polydioxanone systems in Miami and Los Angeles cosmetic clinics from cost-optimized monofilament sutures in institutional settings. Cost compression in the standard tier is intensifying because MDR compliance investments are forcing manufacturers to recoup clinical trial expenses through premium channel markups. Day surgery centers exhibit highest price sensitivity due to Medicare reimbursement caps, while cosmetic clinics absorb premium pricing for scar optimization technologies.
Supply Chain Analysis
Inventory lead times for surgical mesh raw materials now stretch across quarterly planning horizons due to concentrated silicone production in Germany and Switzerland. The supply chain draws from specialized chemical processors in Basel-area industrial clusters and southwestern German manufacturing zones, with polydioxanone polymer feedstocks sourced from South Korean petrochemical specialists. Single-source vulnerability concentrates in Swissmedic-certified silicone purification facilities. Distribution runs through authorized medical device distributors to AAAASF-accredited cosmetic clinics and Medicare-certified ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brachioplasty market sits in a cyclical recovery phase as post-bariatric patient volumes rebound from pandemic-deferred procedures and cosmetic surgery utilization normalizes across coastal metropolitan markets.
For Market Incumbents: Compound market position through backward integration into bioresorbable polymer production and captive supply of barbed suture raw materials. The threat of non-surgical substitution via cryolipolysis devices demands defensive investment in regenerative adjunct protocols combining platelet-rich plasma with excisional techniques. Certification investment in EU MDR compliance pathways anchors European revenue during extended FDA review cycles.
For New Entrants and Emerging Players: Differentiate on bioresorbable mesh formulations that reduce long-term foreign body burden in high-tension closures. The most penetrable white space sits in Texas and Arizona day surgery centers pursuing scope-of-practice amendments for limited-incision arm contouring. Target Medicaid carve-out pilots in select states as a go-to-market angle for functional indication coverage.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap suture specialists with established CE marking and underutilized FDA submission capacity. Long-term viability over a five-to-ten year horizon rests on convergence between aesthetic surgery and regenerative medicine protocols. The signal to watch as inflection indicator is state-level Medicaid expansion for functional brachioplasty coverage following documented intertrigo or mobility impairment.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Pathway | CE marking under EU MDR accelerates European market entry before FDA clearance completion. |
| Bioresorbable Polymer Investment | Novel degradation profiles address FDA's extended biocompatibility testing mandates for absorbable sutures. |
| Cosmetic Clinic Partnership | AAAASF-accredited body contouring suites in California and Florida capture highest-margin post-bariatric cases. |
| Scope-of-Practice Lobbying | Regulatory amendments in Texas and Arizona expand addressable provider base for limited-incision procedures. |
| Regenerative Protocol Development | Platelet-rich plasma adjuncts differentiate premium offerings in scar-conscious patient populations. |
Research Methodology
A standing panel of board-certified plastic surgeons, ambulatory surgical center administrators, biomedical procurement managers, and GPO contracts specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare outpatient prospective payment data, and American Society of Plastic Surgeons procedural volume surveys. Bottom-up procedure volume estimates triangulated against top-down surgical material consumption data from distributor channels.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled procedure type, material category, facility accreditation tier, and geographic regulatory cluster as core segmentation dimensions. CAGRs were derived from procedure volume trajectories and material pricing elasticity assumptions, incorporating post-bariatric patient flow projections and non-surgical substitution elasticities as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable FDA evidentiary standards and continued scope-of-practice expansion in target states; material deviation in regulatory timelines or reimbursement policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Global Plastic Surgery and Integumentary System Procedures Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery and Procedure Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Spain Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market