
 Rhinoplasty Market | 2026-2036
Rhinoplasty Market Size, Share, and Industry Trends Forecast 2026-2036
Rhinoplasty Market Intelligence
The capital-intensity gap between integrated implant manufacturers and standalone surgical clinics is collapsing as device costs fall and outpatient procedural volumes surge. Stryker leverages its orthopedic manufacturing scale to produce precision nasal instruments at unit economics smaller rivals cannot match. GC Aesthetics anchors its position through specialized silicone and polymer implant portfolios tailored to ethnic anatomical variations.
Rhinoplasty denotes surgical modification of nasal bone, cartilage, and soft tissue to alter shape, improve respiratory function, or repair trauma, typically performed under general anesthesia with osteotomy, graft harvesting, or implant insertion. The procedure serves both aesthetic reconstruction and obstructive airway correction in otolaryngology and plastic surgery practice. Open rhinoplasty commands the premium procedural segment due to its visibility and precision for complex revision cases, while filler rhinoplasty represents the fastest-expanding category as hyaluronic acid injections offer reversible, lunch-hour alternatives. End-user demand tilts toward plastic surgeons and cosmetic surgery clinics where margin pools concentrate on bundled aesthetic packages rather than functional reimbursement pathways.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation govern implant biocompatibility, sterilization validation, and clinical safety documentation for nasal devices. The EPA and OSHA intersect through operating-room waste protocols and surgical staff exposure limits that shape facility compliance costs. Stakeholders must monitor evolving AI-assisted surgical planning tools and shifting payer policies on cosmetic versus functional indication coverage to anticipate where procedural economics will compress or expand.
Market Dynamics
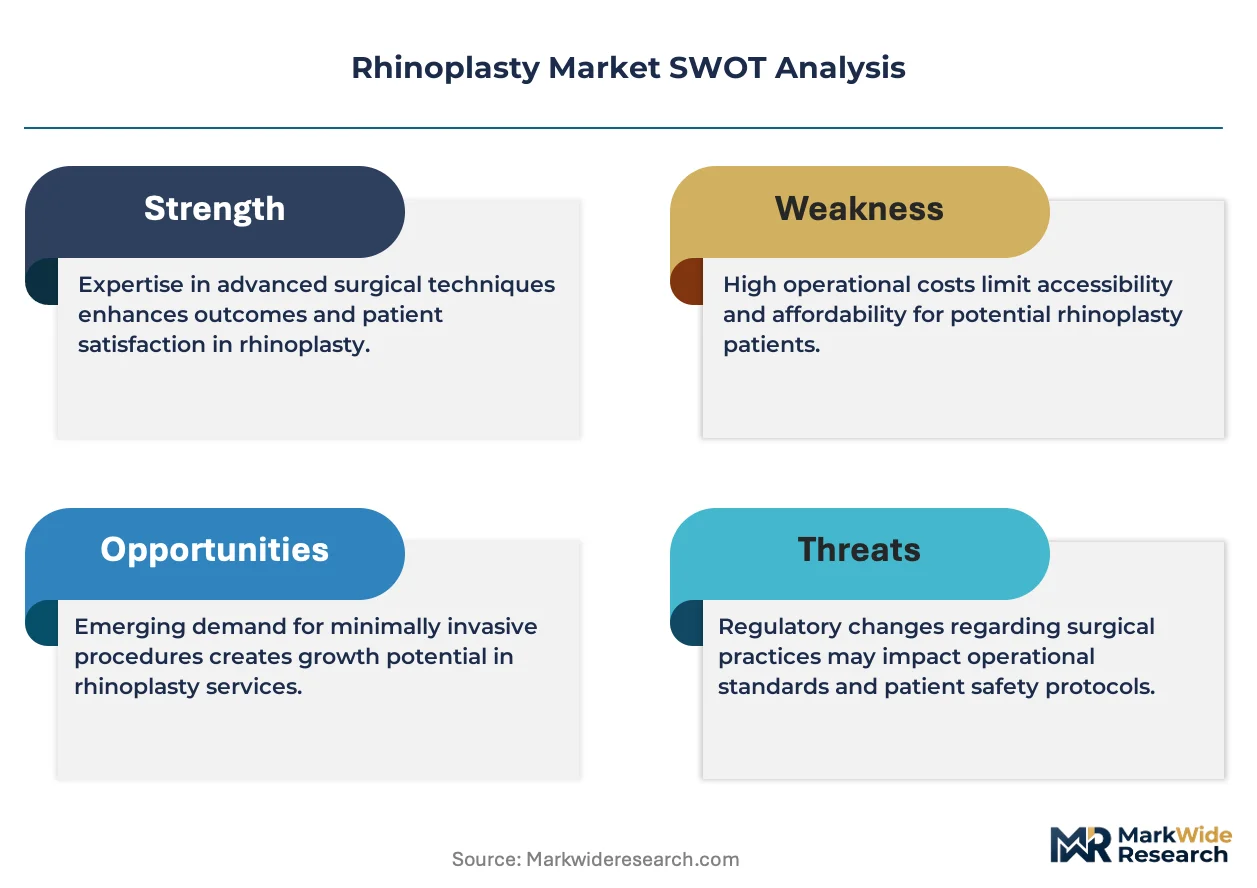
The convergence of minimally invasive techniques and AI-assisted surgical planning is compressing procedure recovery windows while elevating precision standards, forcing implant manufacturers and surgical clinics to recalibrate capital allocation toward digital infrastructure and outpatient capacity expansion.
Growth Catalysts
- EU MDR compliance mandates:Stricter CE marking requirements for nasal implants under the EU Medical Device Regulation are filtering out substandard suppliers and consolidating demand toward certified manufacturers with validated biocompatibility documentation.
- Hyaluronic acid filler adoption:Reversible, non-surgical rhinoplasty using HA injections is expanding the addressable patient base to risk-averse consumers who previously avoided operative intervention.
- South Korea medical tourism infrastructure:Seoul's cluster of specialist surgeons and bundled aesthetic packages attracts cross-border patients from Southeast Asia and the Middle East, amplifying procedural volume beyond domestic demand.
Market Restraints
- Silicone implant cost volatility:Medical-grade silicone feedstock prices fluctuate with petrochemical input cycles, squeezing gross margins for implant manufacturers without backward integration into polymer production.
- Supply concentration in German precision instrument makers:Nasal osteotomes and specialized forceps production clusters in Solingen and Tuttlingen, creating single-source vulnerability for surgical clinics dependent on just-in-time instrument sterilization.
- Revision rhinoplasty technical ceiling:Scar tissue accumulation and cartilage depletion from prior surgeries limit corrective options, capping the addressable market for complex secondary procedures.
Strategic Opportunities
- Brazil's underserved interior cities:São Paulo and Rio de Janeiro concentrate specialist density while secondary metros like Belo Horizonte and Curitiba present whitespace for clinic network expansion with lower competitive intensity.
- AI-powered 3D morphing software:Preoperative simulation tools that project postoperative outcomes are converging with patient management platforms, enabling premium pricing for data-driven consultation workflows.
- Telemedicine pre-screening channels:Virtual consultation pipelines reduce geographic friction for international patients, allowing Seoul and Dubai clinics to capture upstream patient flow before competitors with physical-only intake.
Industry Challenges
- Surgeon training pipeline constraints:Fellowship positions in rhinoplasty subspecialization remain scarce relative to demand, lengthening time-to-autonomy for new practitioners and constraining clinic expansion velocity.
- FDA 510(k) clearance timelines:Novel implant materials face extended review cycles for biocompatibility validation, delaying product commercialization and compressing effective patent life.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhinoplasty Market |
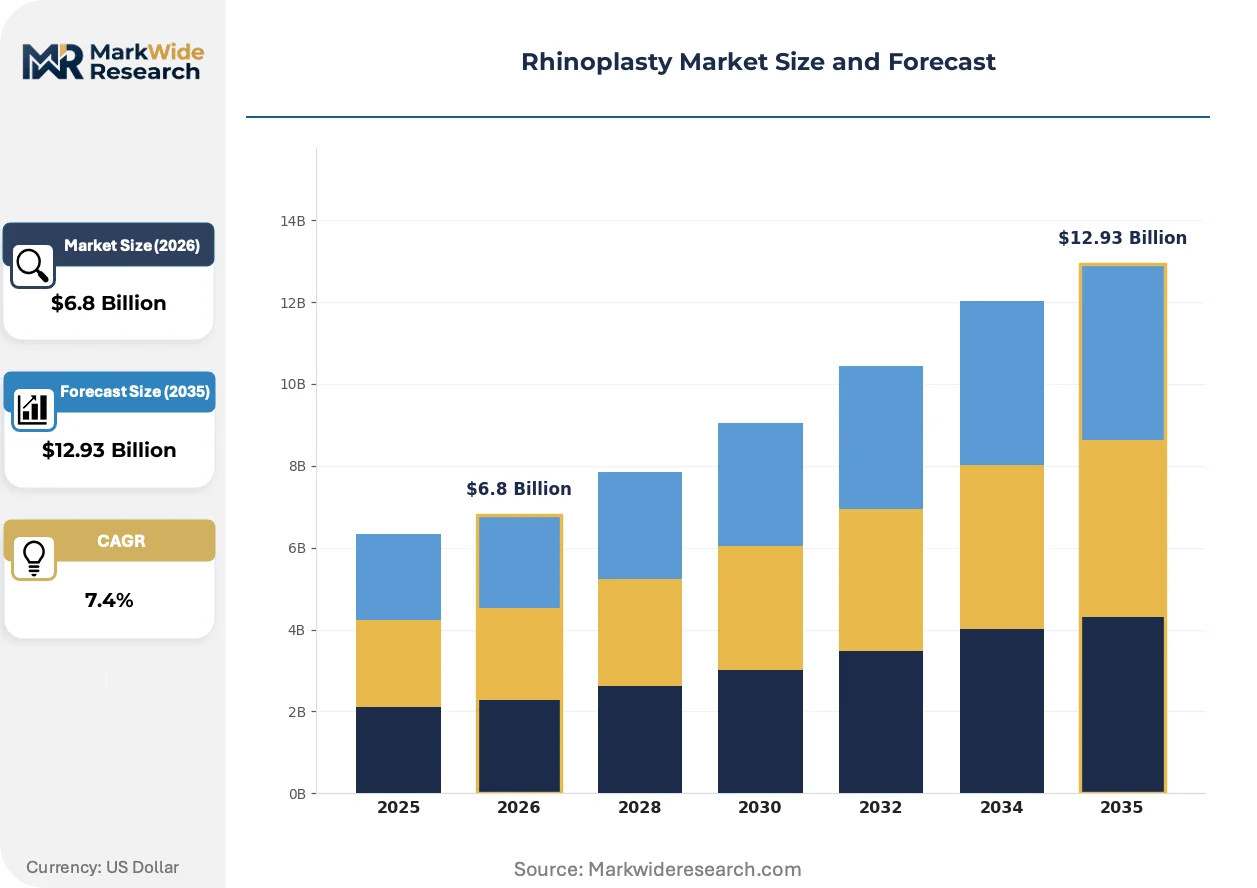
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Open Rhinoplasty, Closed Rhinoplasty, Revision Rhinoplasty, Filler Rhinoplasty End User: Cosmetic Surgeons, ENT Specialists, Plastic Surgeons, Hospitals Service Type: Aesthetic Surgery, Functional Surgery, Minimally Invasive Procedures, Emergency Services Age Group: Adults, Teenagers, Under 18, Seniors |
| Companies Covered | Stryker, Implantech, GC Aesthetics, Surgiform Technologies LLC, Grover Aesthetics, Sunset Cosmetic Surgery, Abbvie, COMEG Medical Technologies, NOUVAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhinoplasty Market Strategic Shifts & Innovations
Digital surgical planning and regenerative biomaterials are converging to redefine procedural economics, shifting value capture from hardware implants toward software-enabled precision and biologic integration.
Ultrasonic rhinoplasty systems employing piezoelectric inserts for controlled bone sculpting are displacing traditional hammer-and-chisel osteotomy in premium clinic settings. High-volume cosmetic surgery centers in Beverly Hills and Gangnam District are adopting these systems to reduce perioperative trauma and accelerate patient throughput. The technology is displacing conventional instrument sets in revision cases where precision margins determine functional outcomes.
The EU Medical Device Regulation's post-market surveillance requirements are mandating implant traceability systems that track device performance across patient lifecycles. Manufacturers must now maintain clinical follow-up registries that feed into European databases, elevating compliance costs but creating competitive moats for firms with robust quality management systems. Silicone and porous polyethylene implant categories face the steepest documentation burdens, advantaging incumbents with established regulatory affairs infrastructure over new market entrants.
Patients are increasingly unbundling consultation, procedure, and aftercare across competing providers rather than accepting single-clinic packages. This fragmentation is compressing loyalty economics for established practices while empowering specialized recovery facilities and independent nursing services to capture downstream value. The pattern is most pronounced in Dubai and Bangkok, where medical tourism intermediaries facilitate multi-provider itineraries that optimize cost and perceived quality across jurisdictions.
Rhinoplasty Market Segmentation
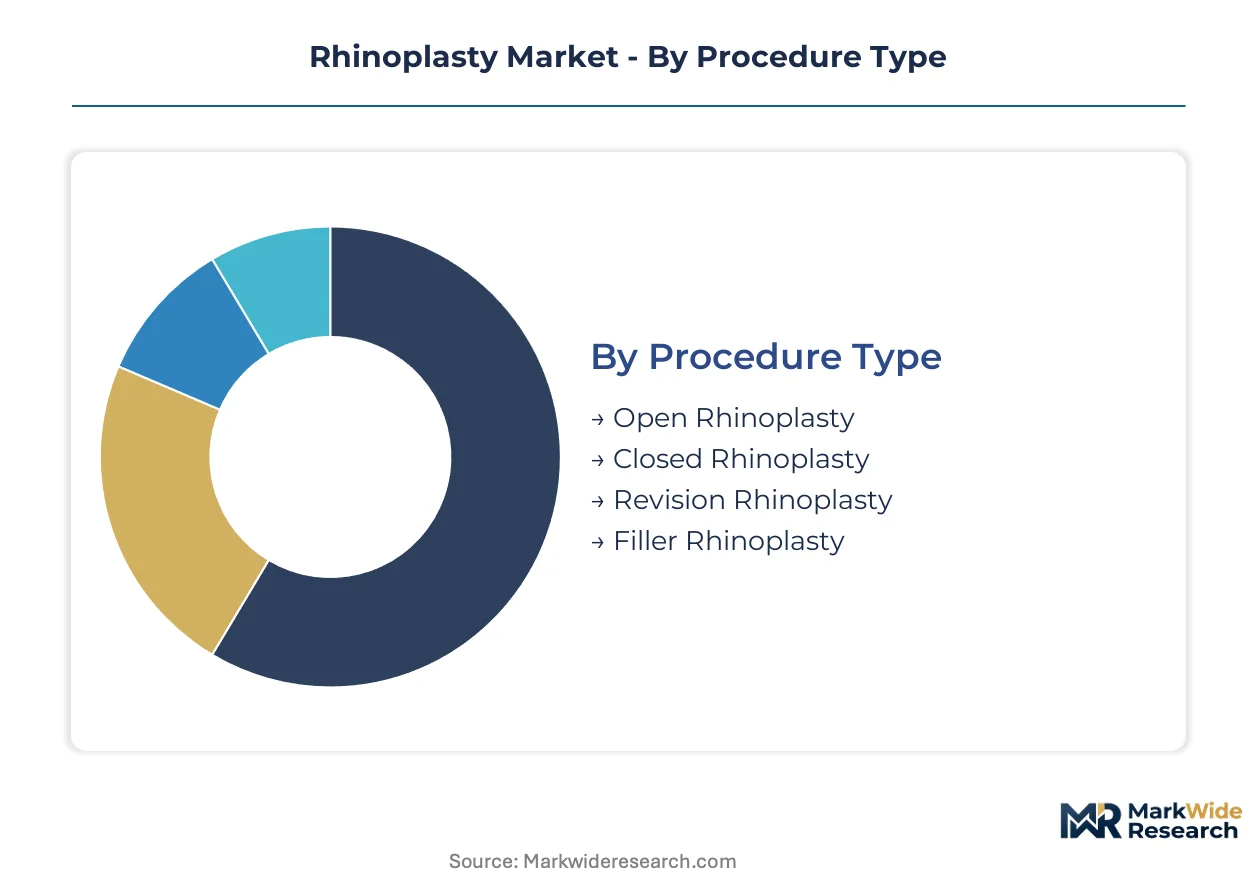
Rhinoplasty market segmentation reveals how procedural economics concentrate across distinct channel pathways. Surgeons, hospitals, and specialized clinics each capture different margin pools based on complexity tier and reimbursement eligibility.
Procedure Type:
Channel flow varies sharply by invasiveness: open procedures anchor hospital operating rooms and academic centers, while filler injections migrate to medspa settings with lower capital barriers.
- Open Rhinoplasty:Full surgical exposure via columellar incision enables complex structural grafting and precise tip refinement. Demand clusters at Beverly Hills and Gangnam District premium practices where revision cases command bundled aesthetic packages exceeding functional reimbursement rates.
- Filler Rhinoplasty:Hyaluronic acid injections reshape nasal contours without operative intervention. Seoul and Dubai cosmetic clinics report surging volumes from Middle Eastern and Southeast Asian medical tourists seeking reversible, lunch-hour alternatives to permanent alteration.
- Closed Rhinoplasty:Endonasal approach preserves columellar integrity with limited visibility, suiting primary dorsal hump reduction.
- Revision Rhinoplasty:Scar tissue and cartilage depletion from prior surgeries constrain technical options and elongate operative time.
Open rhinoplasty dominates installed base. Filler rhinoplasty is where expansion concentrates.
End User:
Cost tier stratification separates high-complexity academic centers from volume-driven ambulatory surgery centers.
- Plastic Surgeons:Board-certified specialists command premium pricing for aesthetic rhinoplasty through bundled consultation-surgery-aftercare packages. Los Angeles and Miami practices report highest procedural density for ethnic rhinoplasty requiring specialized implant portfolios.
- Cosmetic Surgeons:Fellowship-trained practitioners focus exclusively on elective nasal reshaping without functional airway mandate. Brazilian clinics in São Paulo concentrate volume through medical tourism intermediaries packaging accommodation and procedure.
- ENT Specialists:Otolaryngologists integrate septoplasty with aesthetic modification, capturing functional insurance reimbursement.
- Hospitals:Academic medical centers handle trauma reconstruction and complex revision cases requiring overnight admission.
Plastic surgeons dominate installed base. Cosmetic surgeons are where expansion concentrates.
Service Type:
Application focus determines margin structure: aesthetic pathways rely on out-of-pocket payment while functional procedures navigate payer preauthorization.
- Aesthetic Surgery:Elective nasal reshaping for facial harmony and proportion improvement. South Korean clinics bundle rhinoplasty with blepharoplasty and jaw contouring into multi-procedure tourist packages.
- Functional Surgery:Septorhinoplasty corrects obstructive airway pathology with potential insurance coverage. United States hospital systems document medical necessity through computed tomography and polysomnography.
- Minimally Invasive Procedures:Thread lifts and energy-based skin tightening offer intermediate intervention between filler and surgery.
- Emergency Services:Acute trauma reconstruction addresses nasal fracture and septal hematoma within hours of injury.
Aesthetic surgery dominates installed base. Minimally invasive procedures are where expansion concentrates.
Age Group:
Customer type alignment shapes marketing channels: social media drives teenage awareness while discreet referral networks access senior patients.
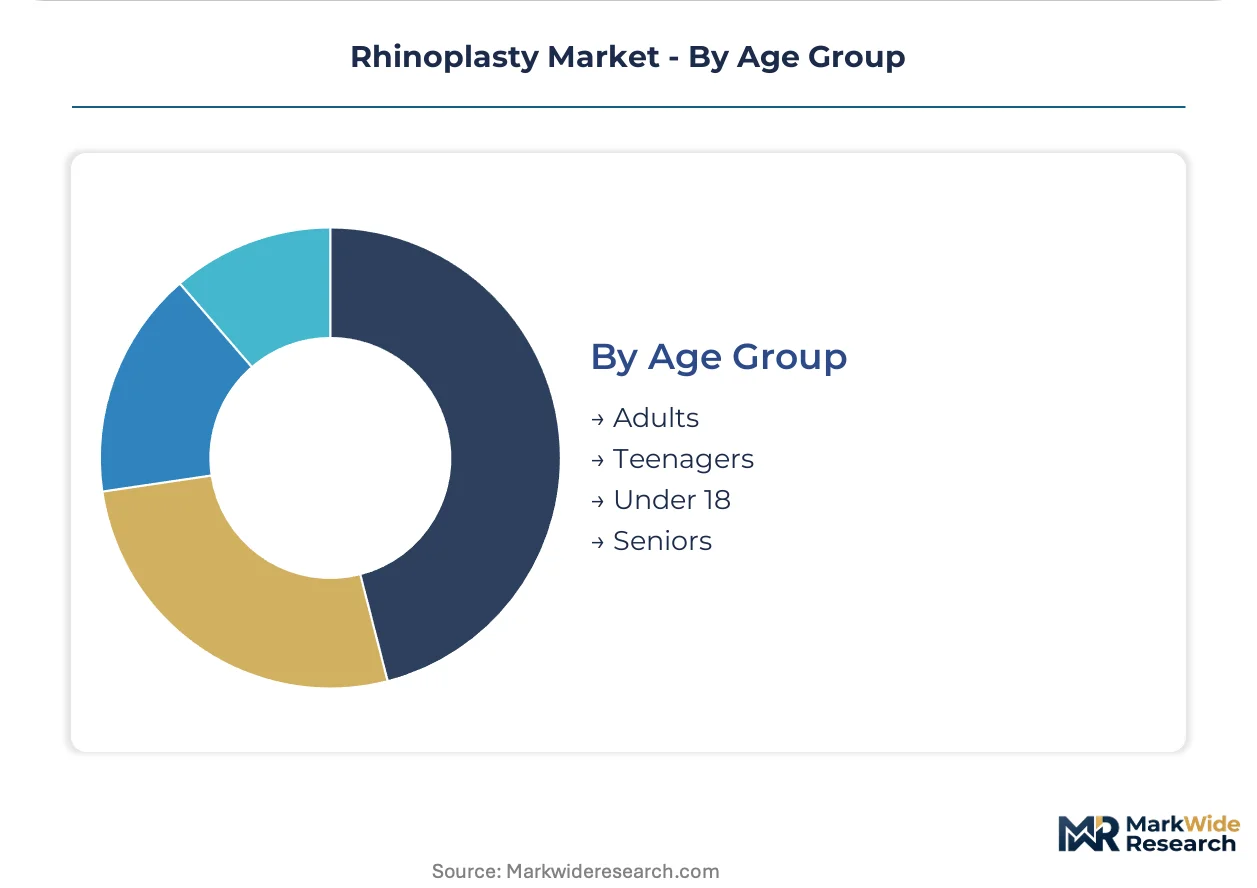
- Adults:Patients aged 18-55 represent core procedural volume with stable facial skeletal structure. Brazilian and Iranian markets report peak demand among professionals seeking career-adjacent appearance investment.
- Teenagers:Post-pubertal nasal development completion enables safe surgical intervention. South Korean high school graduates schedule procedures during academic breaks before university matriculation.
- Under 18:Pediatric cases limited to congenital deformity or traumatic reconstruction with guardian consent.
- Seniors:Aging-related nasal tip ptosis and structural weakening drive functional-aesthetic combination procedures.
Adults dominate installed base. Teenagers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Seoul's Gangnam District exceeds that of Beverly Hills by 30-40% for bundled aesthetic packages, while Brazilian clinics in São Paulo undercut both markets by half on procedural fees alone. This asymmetry reflects divergent cost structures, regulatory burdens, and medical tourism infrastructure maturity across three distinct national markets.
United States
Academic medical centers in Los Angeles and Miami drive demand for ethnic rhinoplasty requiring specialized implant portfolios. FDA 510(k) clearance pathways govern nasal implant biocompatibility documentation, extending review cycles for novel materials. Beverly Hills premium practices command bundled consultation-surgery-aftercare packages exceeding functional reimbursement rates by 3-4x.
South Korea
Seoul's specialist surgeon density attracts cross-border patients from Southeast Asia and the Middle East seeking multi-procedure tourist packages. MFDS regulates medical device safety and post-market surveillance for nasal implants. The Gangnam District cluster bundles rhinoplasty with blepharoplasty and jaw contouring, capturing premium pricing through reputation arbitrage.
Brazil
São Paulo and Rio de Janeiro concentrate procedural volume through medical tourism intermediaries packaging accommodation and surgery. ANVISA oversees implant registration and clinical safety standards for nasal devices. Secondary metros like Belo Horizonte and Curitiba present whitespace for clinic network expansion with lower competitive intensity and reduced real estate costs.
Germany
Solingen and Tuttlingen host precision instrument manufacturing clusters for nasal osteotomes and specialized forceps. EU MDR compliance mandates under the Medical Device Regulation filter substandard suppliers through stricter CE marking requirements. German academic centers handle complex revision cases requiring overnight admission and multidisciplinary airway reconstruction.
United Arab Emirates
Dubai clinics capture upstream patient flow from GCC nationals and African medical tourists through telemedicine pre-screening channels. MOHAP regulates cosmetic surgery facility licensing and practitioner credentialing. The emirate's free zone infrastructure enables rapid clinic establishment with streamlined import pathways for FDA-cleared and CE-marked implants.
Rhinoplasty Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated orthopedic manufacturers leveraging manufacturing scale against specialized aesthetic implant designers focused on ethnic anatomical variation. The market structures around three tiers: diversified medical device conglomerates with regulatory affairs infrastructure, dedicated aesthetic implant specialists with polymer chemistry expertise, and regional surgical clinic chains with captive patient flow. Dominant competitive moves include portfolio diversification into complementary facial procedures and strategic partnerships with medical tourism intermediaries.
Among diversified manufacturers, Stryker occupies a position exemplifying manufacturing scale advantages in precision nasal instruments. GC Aesthetics represents the specialized implant archetype with tailored silicone and polymer portfolios. Surgiform Technologies LLC anchors the dedicated aesthetic technology tier. These three entities collectively illustrate how regulatory compliance capacity, material science specialization, and regional market access define competitive positioning in this market.
| Leading Market Players |
|---|
| Stryker |
| Implantech |
| GC Aesthetics |
| Surgiform Technologies LLC |
| Grover Aesthetics |
| Sunset Cosmetic Surgery |
| Abbvie |
| COMEG Medical Technologies |
| NOUVAG |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation agreements with German precision instrument manufacturers lock in surgical tool access and stabilize cost visibility for high-volume cosmetic surgery chains. These contracts insulate Beverly Hills and Gangnam District clinics from spot-market volatility in medical-grade silicone feedstock while cementing supplier relationships that competitors cannot replicate.
Pricing Analysis
The customization-premium spread between patient-specific implant configurations and standard off-the-shelf nasal devices exceeds two-to-one in Seoul's premium clinic tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by surgeon reputation and bundled aftercare inclusion. Cost compression in the standard tier is intensifying because Stryker's manufacturing scale advantages force smaller implant specialists into price concessions. Medical tourists from Southeast Asia demonstrate highest price sensitivity, while Middle Eastern patients seeking revision rhinoplasty show least elasticity.
Supply Chain Analysis
Inbound logistics costs from German instrument clusters through Rotterdam port congestion add 12-15% landed cost premiums for Dubai and Bangkok clinics. Manufacturing concentration centers on Germany for precision osteotomes, the United States for silicone and porous polyethylene implants, and South Korea for ultrasonic piezoelectric systems. Raw material dependencies rest on medical-grade silicone polymers, titanium alloys for structural grafts, and hyaluronic acid feedstock. Single-source vulnerability in Solingen instrument production creates systemic risk. Distribution runs through medical device distributors with regional sterilization partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rhinoplasty sits in early-cycle expansion as filler rhinoplasty penetration among risk-averse first-time patients creates a downstream pipeline for eventual surgical conversion.
For Market Incumbents: Consolidate regulatory affairs capacity and backward integration into polymer production to defend against Stryker's unit economics pressure. Acquire MFDS-registered Korean implant specialists to preempt Seoul clinic chains from developing captive supply. CE marking documentation depth serves as the primary moat against emerging Asian manufacturers. For New Entrants and Emerging Players: Post-operative recovery facility networks represent an underserved service layer where established clinics cede margin to fragmented local providers. Target Brazil's secondary metros Belo Horizonte and Curitiba for whitespace clinic establishment with lower competitive density. Deploy telemedicine pre-screening to capture international patient flow before physical clinic contact. For Investors and Strategic Acquirers: Regional surgical clinic chains with captive patient flow and established medical tourism intermediary relationships offer the strongest acquisition target archetype. Long-term viability hinges on AI-assisted surgical planning software integration and ethnic-specific implant portfolio depth. Monitor FDA 510(k) clearance timeline compression as the inflection signal for novel material commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | CE marking documentation creates competitive moats filtering substandard implant suppliers from European market access. |
| AI-Assisted Surgical Planning Integration | Preoperative 3D morphing software enables premium consultation pricing and reduces revision liability exposure. |
| Medical Tourism Intermediary Partnership | Seoul and Dubai clinics capture upstream patient flow through bundled accommodation-procedure packages. |
| Ultrasonic Rhinoplasty System Adoption | Piezoelectric bone sculpting reduces perioperative trauma and accelerates patient throughput in premium settings. |
| Ethnic-Specific Implant Portfolio Expansion | Specialized silicone geometries for Middle Eastern and Asian nasal anatomy command pricing premiums in Los Angeles and Miami. |
Research Approach
Initial hypotheses were tested against primary input from plastic surgery clinic directors, biomedical engineers at implant manufacturers, hospital purchasing committee members, and medical tourism intermediaries and refined through secondary validation against FDA 510(k) clearance databases, EU MDR post-market surveillance registries, MFDS device approval filings, and ANVISA registration records. Bottom-up procedural volume estimates from cosmetic surgery clinics triangulated against top-down implant shipment data from German and United States manufacturers.
Variance decomposition across procedure type, end-user channel, service aesthetic versus functional focus, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segmented growth rate modeling incorporating hyaluronic acid filler adoption curves, medical tourism flow projections, and minimally invasive technique penetration patterns. Industry-specific inputs included surgeon training pipeline constraints and silicone feedstock price volatility assumptions.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR post-market surveillance requirements, and MFDS biocompatibility standards; material policy shifts would require re-modeling. Specific risks include FDA review timeline extension for novel implant materials and EU MDR documentation burden escalation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Cosmetic Surgery and Services Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Italy Cosmetic Surgery Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Cosmetic Surgery Products Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Saudi Arabia Cosmetic Surgery Market
Cosmetic Surgery
Global Blepharoplasty Market
Cosmetic Surgery
France Cosmetic Surgery Market