
 Japan Cosmetic Surgery Market | 2026-2036
Japan Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Cosmetic Surgery Market Insights
Men seeking jawline contouring and hair restoration is expanding within Japan's cosmetic surgery patient base. SBC Medical Group leverages its multi-clinic network to sustain volume across Greater Tokyo. Shonan Beauty Clinic anchors its reputation in non-invasive facial rejuvenation. Aoyama Cosmetic Surgery differentiates through boutique positioning in Tokyo's premium district.
Cosmetic surgery encompasses elective and reconstructive procedures modifying facial or body structures through surgical incision, laser ablation, or injectable implantation, typically performed under local or general anesthesia in accredited clinical settings. Blepharoplasty and rhinoplasty command mature demand among East Asian facial aesthetic preferences, while non-invasive service types capture expanding margin pools as energy-based devices and biostimulatory fillers reduce downtime. The invasive segment still occupies the largest revenue share due to higher per-procedure pricing and facility requirements.
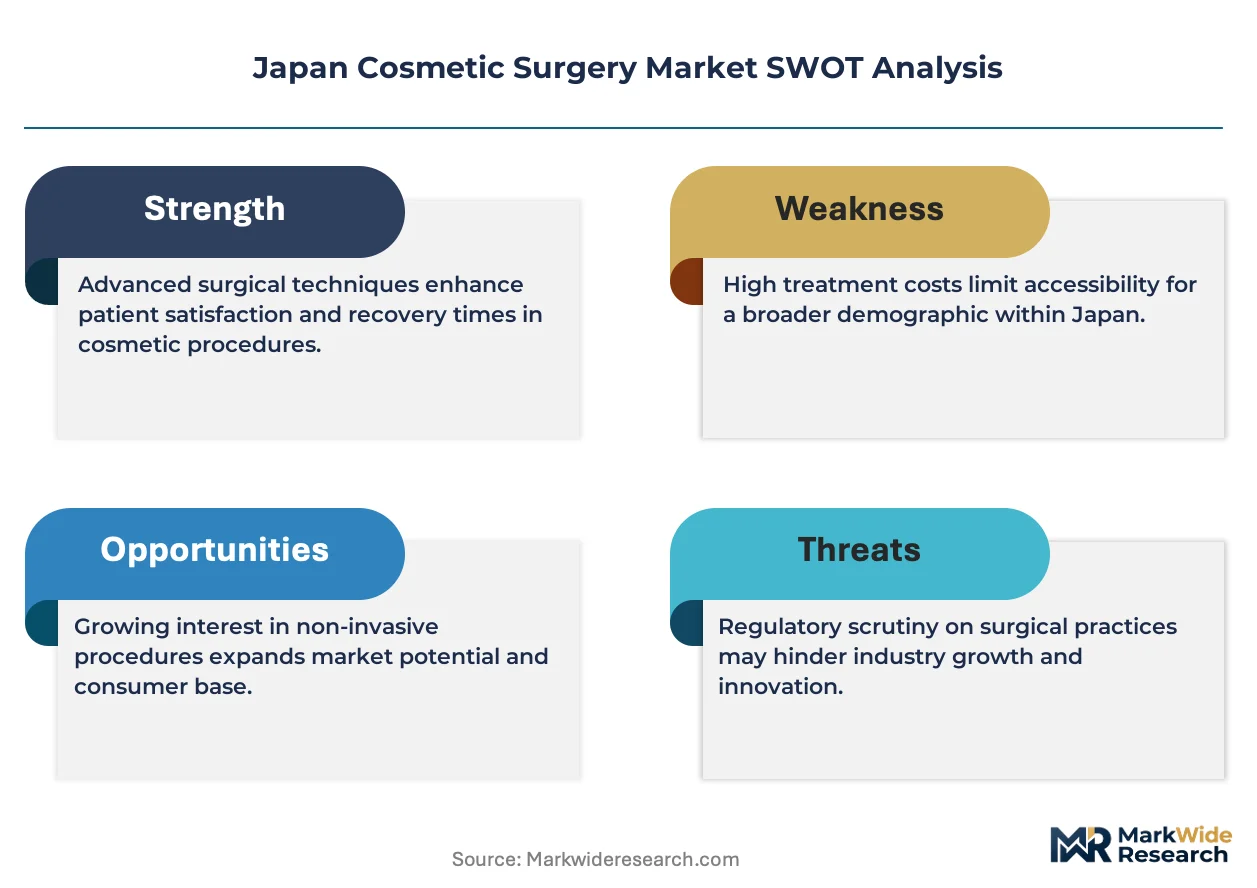
PMDA governs medical device approvals for implants and energy-based equipment, while Japan's Ministry of Health, Labour and Welfare sets facility standards and physician certification requirements that shape market access. METI's healthcare industry promotion frameworks influence technology import pathways for advanced laser and ultrasound platforms. Stakeholders must monitor how PMDA's evolving regenerative medicine policies will reshape permissible cell-based aesthetic therapies.
Market Dynamics
PMDA's expanded medical device approval pathways for novel dermal filler materials are compressing time-to-market for regenerative aesthetic products, while male patient enrollment accelerates faster than historical clinic capacity planning assumed.
Growth Catalysts
- Regulatory Modernization:PMDA's streamlined regenerative medicine policies now accommodate cell-based aesthetic therapies previously restricted to clinical trials, expanding the addressable procedure base for Tokyo's clinic clusters.
- Demographic Expansion:Male patients seeking jawline contouring and hair restoration procedures are enrolling at rates that outpace historical gender ratios in Japan's cosmetic surgery market.
- Material Innovation:Biostimulatory fillers incorporating polycaprolactone and calcium hydroxylapatite are reducing procedure downtime while extending treatment intervals, improving clinic throughput metrics.
Market Restraints
- Physician Certification Bottlenecks:Japan's Ministry of Health, Labour and Welfare maintains strict facility standards and specialist certification requirements that limit qualified practitioner supply relative to demand concentration in Greater Tokyo.
- Import Dependency for Energy Devices:Advanced laser and ultrasound platforms remain concentrated among foreign original equipment manufacturers, exposing clinics to currency volatility and extended service timelines.
- Substitution from Non-Invasive Alternatives:High-intensity focused ultrasound and radiofrequency devices are capturing margin pools from traditional surgical procedures among younger demographics prioritizing minimal downtime.
Strategic Opportunities
- Osaka-Kyoto Corridor Expansion:Clinic network saturation in Tokyo's Shibuya and Shinjuku districts creates white space for premium positioning in Kansai's underserved urban centers.
- Regenerative Medicine Integration:PMDA's evolving framework for cell-based therapies enables autologous stem cell applications in facial rejuvenation, commanding premium pricing relative to synthetic alternatives.
- Hybrid Service Models:Subscription-based maintenance programs combining energy-based treatments with periodic filler refreshers are locking in patient lifetime value beyond discrete procedure economics.
Industry Challenges
- Specialist Training Pipeline Constraints:Japan's dermatological and plastic surgery residency programs produce insufficient board-certified practitioners to match expansion timelines of multi-clinic networks.
- Equipment Depreciation Cycles:Energy-based device platforms require capital refresh every three to four years to maintain competitive positioning, straining balance sheets of mid-scale independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Cosmetic Surgery Market |
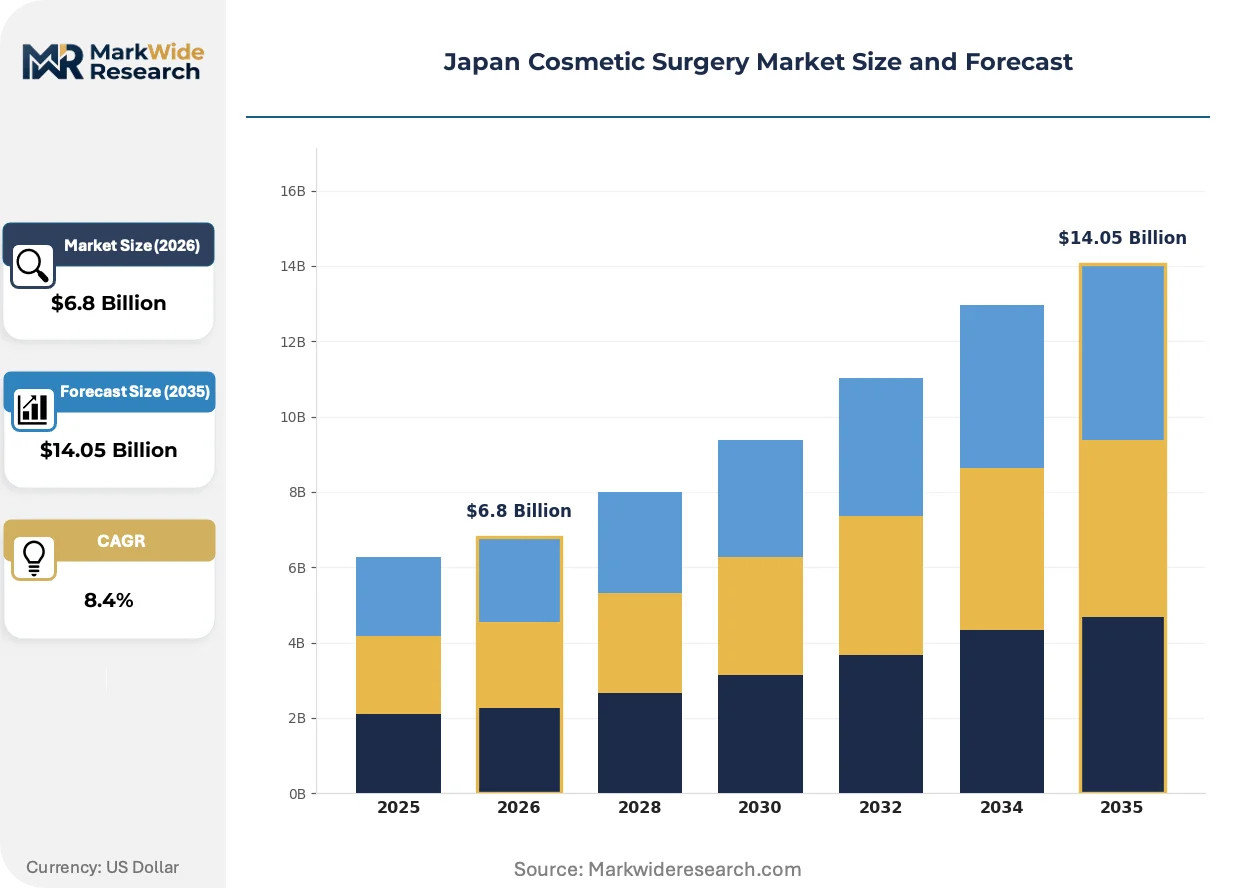
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Rhinoplasty, Blepharoplasty, Breast Augmentation, Liposuction Demographic: Women, Men, Age Group 18-30, Age Group 31-50 Service Type: Invasive, Non-Invasive, Reconstructive, Aesthetic Delivery Mode: Outpatient, Inpatient, Online Consultation, Homecare |
| Companies Covered | Aoyama Cosmetic Surgery, Shinjuku Cosmetic Surgery Clinic, SBC Medical Group, Verite Clinic, TCB Tokyo Central Cosmetic Surgery, Shonan Beauty Clinic, Keisei Cosmetic Surgery, Otsuka Cosmetic & Plastic Surgery, Tokyo Cosmetic Surgery Clinic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Cosmetic Surgery Market Trends and Innovations
Technology convergence between imaging diagnostics and treatment delivery is compressing consultation-to-procedure timelines, while regulatory clarity on novel materials reshapes competitive positioning among Tokyo's clinic clusters.
Hybrid ultrasound-guided injection systems are unifying real-time tissue visualization with precise filler placement, reducing complication rates and revision procedures. Aesthetic clinics in Shibuya and Shinjuku districts are adopting these platforms at accelerated replacement cycles. This technology convergence is unifying diagnostic and therapeutic workflows into single-visit protocols that maximize per-hour revenue.
PMDA's expanded regenerative medicine policies now explicitly permit adipose-derived stem cell therapies for facial volumization, creating a new compliance category distinct from traditional device-based approvals. Japanese clinic operators must navigate dual-track certification requirements for cell processing facilities. The invasive segment faces the most significant competitive pressure as autologous alternatives capture patients seeking natural-appearing outcomes.
Subscription-based aesthetic maintenance is displacing discrete procedure purchasing among younger demographics in Tokyo's premium districts. Clinics are unbundling comprehensive treatment packages into monthly membership tiers covering periodic energy-based sessions and filler touch-ups. This behavioral shift is most visible among male patients aged 28-40 seeking jawline definition without surgical commitment.
Japan Cosmetic Surgery Market Segmentation
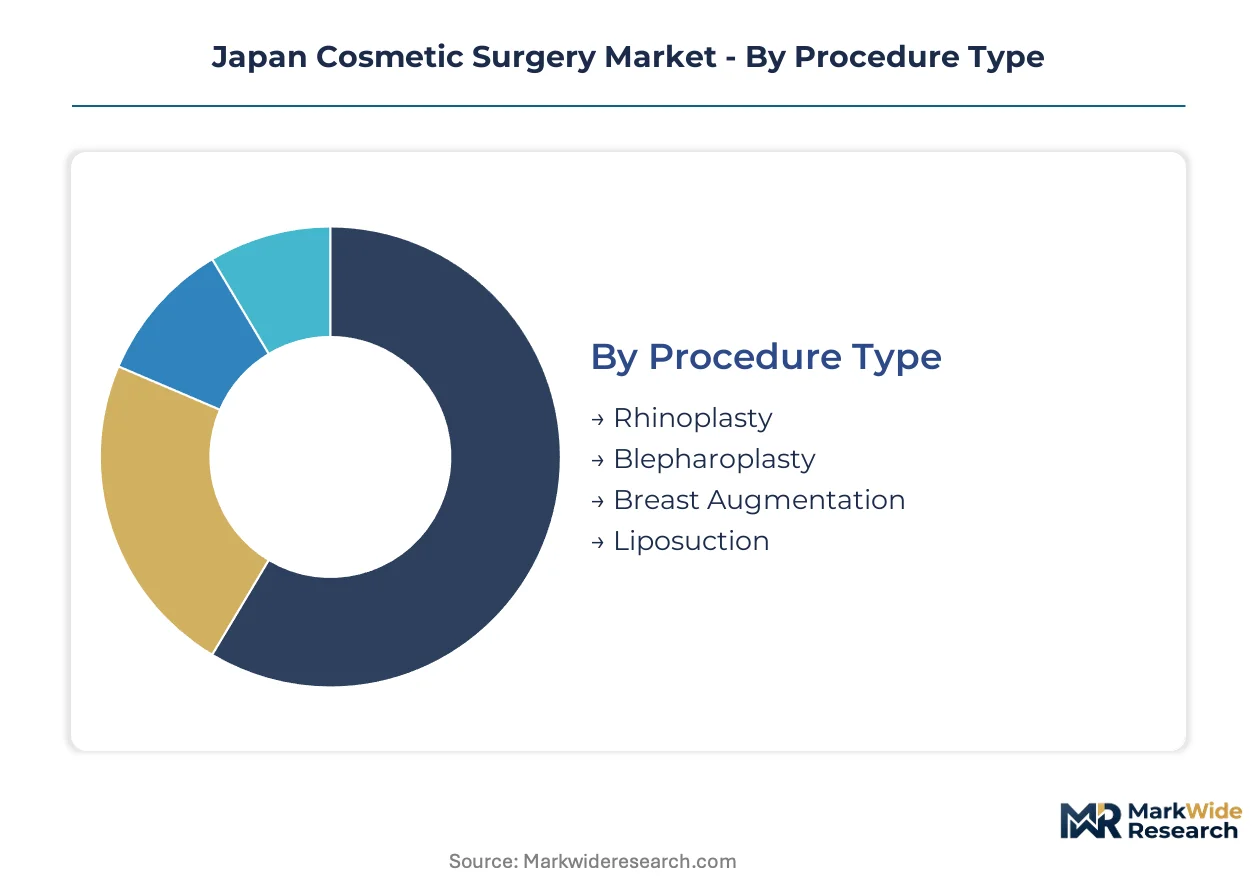
Procedure complexity and recovery duration create distinct operational footprints across Japan's cosmetic surgery market. Segmentation reveals how Tokyo's clinic clusters allocate resources between high-margin invasive interventions and volume-driven non-invasive services.
Procedure Type:
Customization ranges from standardized anatomical modifications to highly individualized contouring protocols across this category.
- Rhinoplasty:Nasal structure modification through osteotomy, cartilage grafting, or implant placement addresses dorsal hump reduction and tip refinement. Demand concentrates among Tokyo's Shibuya district clinics serving East Asian facial aesthetic preferences, where PMDA-approved silicone and porous polyethylene implants compete with autologous cartilage techniques.
- Blepharoplasty:Upper and lower eyelid surgery removes excess skin, orbital fat, and muscle tissue to create defined supratarsal folds. Patient enrollment in Shinjuku clusters favors double-eyelid creation among younger demographics, while aging populations drive lower lid bag reduction procedures.
- Liposuction:Suction-assisted fat removal targets localized adipose deposits through tumescent or ultrasound-assisted techniques.
- Breast Augmentation:Implant-based or fat-transfer mammoplasty procedures utilize PMDA-regulated silicone gel or saline devices.
Leading the category by volume: Blepharoplasty. Expanding most quickly: Rhinoplasty.
Demographic:
Patient acquisition costs and lifetime value calculations diverge sharply across age and gender cohorts in Greater Tokyo.
- Women:Female patients historically dominate facial rejuvenation and body contouring procedures, with concentration in 31-50 age brackets seeking maintenance interventions.
- Men:Male patient enrollment accelerates fastest across jawline contouring and hair restoration categories, with SBC Medical Group and Shonan Beauty Clinic reporting capacity constraints in Greater Tokyo.
- Age Group 18-30:Younger patients prioritize non-invasive entry procedures and subscription-based maintenance models.
- Age Group 31-50:Mid-career professionals drive invasive procedure volume with higher disposable income and surgical acceptance.
Highest absolute volume: Women. Steepest expansion trajectory: Men.
Service Type:
Capital intensity and regulatory burden separate surgical from non-surgical service delivery models.
- Invasive:Surgical procedures requiring general anesthesia and accredited facility standards command premium pricing and extended recovery protocols. This segment occupies the largest revenue share due to higher per-procedure economics and specialized infrastructure requirements.
- Non-Invasive:Energy-based devices and injectable treatments reduce downtime while capturing expanding margin pools among younger demographics prioritizing minimal disruption.
- Aesthetic:Elective procedures modifying appearance without medical necessity drive discretionary spending patterns.
- Reconstructive:Medically indicated procedures address congenital conditions, trauma sequelae, or oncological reconstruction.
Revenue concentration: Invasive. Fastest share gain: Non-Invasive.
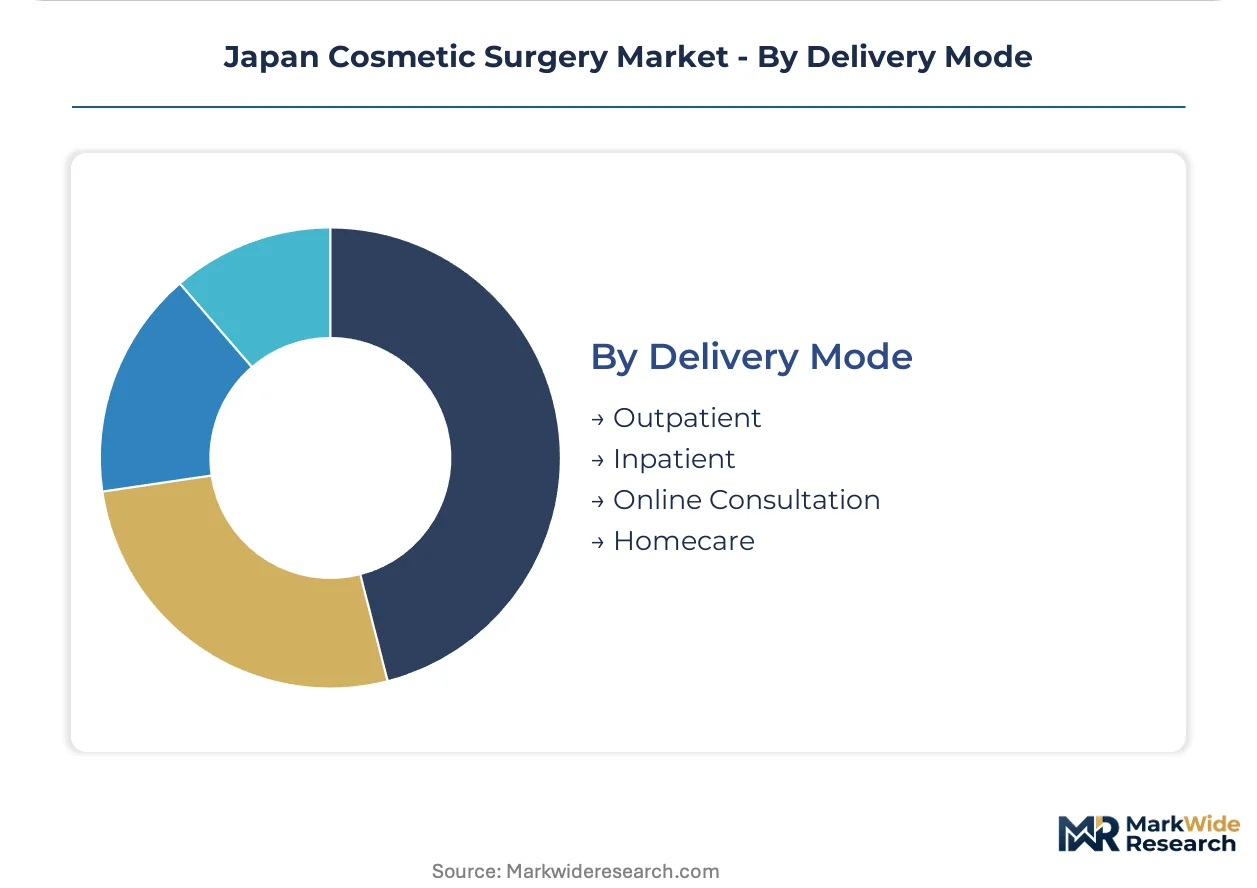
Delivery Mode:
Facility overhead and regulatory compliance scale differently across care settings.
- Outpatient:Ambulatory surgical centers and clinic-based procedures minimize overnight stay costs while maintaining PMDA facility standards. Tokyo's Shibuya and Shinjuku clusters operate predominantly on this model.
- Online Consultation:Digital pre-screening and treatment planning compress consultation-to-procedure timelines, with hybrid platforms integrating imaging diagnostics.
- Inpatient:Hospital-based delivery accommodates complex reconstructive cases requiring extended monitoring.
- Homecare:Post-procedure recovery support and remote monitoring extend care continuity beyond facility discharge.
Dominant volume mode: Outpatient. Fastest infrastructure investment: Online Consultation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's cosmetic surgery market concentrates consumption in metropolitan corridors while production of energy-based devices and implant materials relies heavily on foreign manufacturers. Domestic clinic networks absorb imported equipment across fragmented regional demand centers.
Kanto/Tokyo
Shibuya and Shinjuku districts generate the highest procedure volume through dense clinic clustering and premium positioning. PMDA's medical device approval pathways accommodate novel dermal fillers entering through Tokyo's import channels. Male patient enrollment for jawline contouring accelerates fastest in this corridor, straining existing practitioner capacity.
Kansai/Osaka
Osaka-Kyoto corridor presents expansion white space as Tokyo clinic saturation drives network diversification. The region's aging demographic sustains facial rejuvenation demand while younger cohorts adopt subscription-based maintenance models. Independent operators in Osaka's Umeda district compete with emerging multi-clinic brands from the capital.
Chubu/Nagoya
Nagoya's industrial base supports medical device distribution infrastructure serving central Japan aesthetic practices. METI's healthcare industry promotion frameworks influence technology import pathways through this logistics hub. Regional clinics lag Tokyo in regenerative medicine adoption due to slower PMDA consultation access.
Kyushu
Fukuoka's growing medical tourism positioning attracts domestic patients seeking lower-cost alternatives to Tokyo pricing. Local practitioners emphasize non-invasive service types to minimize facility overhead requirements. Equipment depreciation cycles pressure mid-scale operators dependent on aging laser platforms.
Hokkaido
Sapporo's isolated geography limits specialist practitioner supply relative to dispersed rural demand across northern Japan. Patients travel to Tokyo for complex invasive procedures while local clinics focus on injectable maintenance and energy-based treatments. Seasonal tourism creates periodic demand spikes for discreet recovery protocols.
Japan Cosmetic Surgery Market Competitive Landscape
Top-tier vendors anchor multi-clinic network expansion, while independent boutique operators defend margin through specialization. The market structure exhibits tiered consolidation with scale-driven groups capturing volume and premium-positioned clinics extracting pricing power. Three archetypes dominate: metropolitan network operators, district-focused premium brands, and technology-forward device-integrated practices. Competitive moves center on geographic network densification and hybrid service model unbundling.
Among Tokyo-based network operators, SBC Medical Group exemplifies scale-driven consolidation across Greater Tokyo, while Shonan Beauty Clinic occupies a position emphasizing non-invasive facial rejuvenation. Aoyama Cosmetic Surgery represents the premium-tier boutique archetype in Tokyo's premium district. These three entities collectively illustrate the strategic segmentation between volume capture, technology specialization, and luxury positioning that defines competitive dynamics.
| Leading Market Players |
|---|
| Aoyama Cosmetic Surgery |
| Shinjuku Cosmetic Surgery Clinic |
| SBC Medical Group |
| Verite Clinic |
| TCB Tokyo Central Cosmetic Surgery |
| Shonan Beauty Clinic |
| Keisei Cosmetic Surgery |
| Otsuka Cosmetic & Plastic Surgery |
| Tokyo Cosmetic Surgery Clinic |
| Others |
Pricing and Supply Chain Analysis
Imported laser platform costs from Germany and South Korea cascade through Tokyo's clinic tiers, with Shibuya premium operators absorbing currency volatility while Fukuoka independents defer equipment refresh cycles. This upstream concentration fragments pricing power across Japan's metropolitan corridors.
Pricing Analysis
Margin tightening in mid-tier outpatient clinics reflects biostimulatory filler commoditization as PMDA approvals expand supplier pools. Three-tier pricing structure across premium, standard, and economy levels separates Aoyama district boutiques from Shinjuku volume operators and Kyushu value positioning. Pricing pressure intensifies in non-invasive segments as HIFU device saturation erodes per-session economics. Younger male demographics aged 28-40 exhibit highest price sensitivity through subscription model preference, while reconstructive patients show lowest elasticity due to medical necessity.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and German OEMs controlling advanced ultrasound and laser platform manufacturing. Silicone implant raw materials draw from Germany, France, and domestic Nagoya polymer processors. Supply chain risk centers on yen-dollar-euro currency volatility compressing clinic procurement budgets. Distribution runs through Tokyo import channels with METI healthcare promotion frameworks shaping customs clearance timelines for regenerative medicine devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's cosmetic surgery sector is transitioning from surgical incision dominance toward energy-based device and biostimulatory filler platforms, with autologous stem cell therapies emerging as the next capability frontier.
For Market Incumbents: Deploy hybrid service model unbundling to lock patient lifetime value against HIFU substitution threat. SBC Medical Group and Shonan Beauty Clinic should consolidate Osaka-Kyoto corridor presence before Tokyo saturation triggers price warfare. PMDA regenerative medicine certification investment creates defensible positioning as cell-based therapies command premium pricing.
For New Entrants and Emerging Players: The premium-economy price-point gap in Nagoya and Fukuoka creates white-space entry corridors underserved by Tokyo network operators. Target subscription-native male demographics aged 28-40 through jawline contouring specialization with device-integrated consultation workflows. Partner with South Korean OEMs for leased equipment models reducing capital barriers.
For Investors and Strategic Acquirers: PMDA's explicit adipose-derived stem cell therapy authorization is the leading indicator that regenerative medicine integration will reshape competitive economics. Multi-clinic networks with cell processing facility certifications represent priority acquisition archetypes. Watch for male patient enrollment crossing threshold ratios in quarterly clinic disclosures as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Medicine Certification | PMDA cell-therapy approval unlocks premium pricing tiers for autologous facial volumization procedures. |
| Osaka-Kyoto Network Expansion | Geographic diversification captures underserved Kansai demand before Tokyo clinic density triggers margin compression. |
| Hybrid Subscription Model Launch | Membership tiers convert discrete procedure economics into predictable recurring revenue from male demographics. |
| South Korean OEM Partnership | Equipment leasing agreements reduce capital intensity for mid-scale operators facing three-year depreciation cycles. |
| Cell Processing Facility Investment | Dual-track PMDA compliance for device and cell-based therapies creates regulatory moat against synthetic filler competitors. |
Research Methodology
Independent corroboration across clinic network executives, PMDA regulatory consultants, and biomedical device distributors underwrites the qualitative findings in this study. Primary interviews with plastic surgery residency program directors, Greater Tokyo clinic operations managers, and South Korean OEM country representatives combined with secondary validation from METI healthcare industry reports, PMDA medical device approval databases, and Japan Cosmetic Surgery Association membership records. Bottom-up procedure volume estimates triangulated against top-down market sizing across invasive, non-invasive, and regenerative service categories.
Comparable-period anchoring linked historical enrollment patterns to forward projection assumptions across the analysis window. Segmentation modeling incorporated procedure type complexity, demographic cohort behavior, service delivery capital intensity, and metropolitan corridor saturation indices. CAGRs were derived from trend extrapolation calibrated to PMDA approval velocity and male patient enrollment trajectory. Forecast inputs included equipment depreciation cycle timing, stem cell therapy regulatory pathway clarity, and subscription model adoption elasticity among younger demographics.
Inputs from clinic network disclosures and OEM import records were available through the study window; gaps in real-time patient enrollment telemetry introduce uncertainty bands around near-term volume assumptions. Forecasts reflect documented assumptions regarding PMDA regenerative medicine policy evolution and currency stability for German and South Korean equipment procurement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Cosmetic Surgery Market
Cosmetic Surgery
Brachioplasty Market
Cosmetic Surgery
Rhinoplasty Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
Brazil Cosmetic Surgery Market
Cosmetic Surgery
Rhytidectomy Market
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
China Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
Asia-Pacific Cosmetic Surgery Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
North America Cosmetic Surgery Market