
 China Cosmetic Surgery Market | 2026-2036
China Cosmetic Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
China Cosmetic Surgery Market Intelligence
South Korea's cross-border clinic networks is fragmenting as Chinese patients redirect spending toward domestic providers. AbbVie Inc (Allergan Inc) anchors its position through captive supply of hyaluronic acid fillers. Sisram Medical Ltd (Alma Lasers) differentiates via energy-based device portfolios tailored to Asian skin phenotypes. Medytox Inc competes on neurotoxin manufacturing scale within regional supply chains.
China cosmetic surgery encompasses invasive and minimally invasive procedures performed to alter aesthetic appearance, utilizing laser wavelengths between 532 nm and 10,600 nm, absorbable sutures, and silicone or cohesive gel implants to modify soft tissue and bone structure for reconstructive or elective enhancement purposes. Rhinoplasty and breast augmentation command premium pricing due to implant import dependency and surgeon certification scarcity. Minimally invasive technologies capture expanding share as laser surgery platforms and injectable biologics reduce recovery intervals. Private clinics concentrate margin pools through direct-to-consumer channel control and bundled service packaging.
NMPA device registration requirements and SAMR advertising enforcement shape product commercialization timelines and clinic marketing compliance burdens. GB standards for medical laser safety and clinical trial localization mandates filter multinational device entrants. Stakeholders must monitor regulatory divergence between national standards and provincial enforcement intensity to calibrate market entry sequencing.
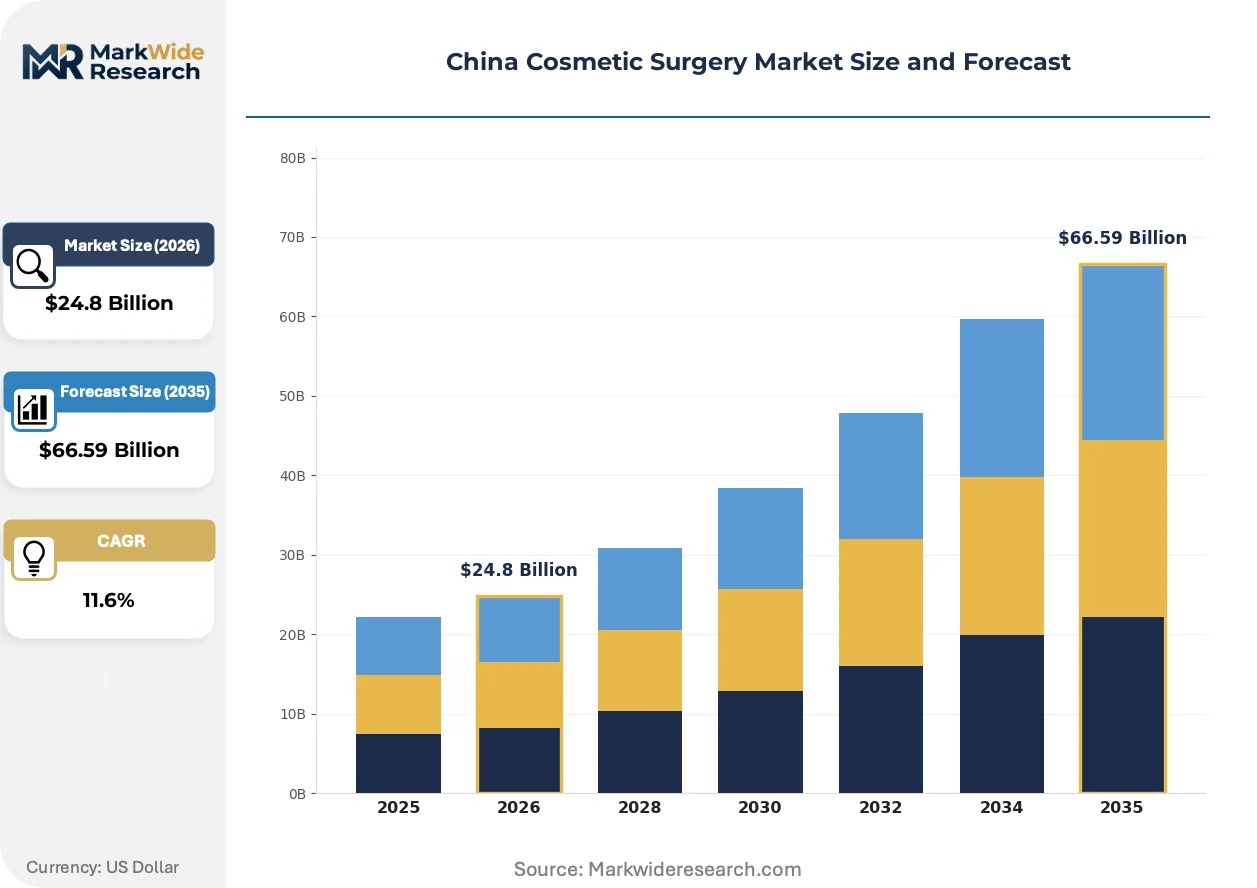
Market Dynamics
Domestic clinic chains are capturing patient flows that previously exited to Seoul, compressing cross-border arbitrage margins and forcing pricing recalibration across Shanghai and Beijing surgical corridors.
Growth Catalysts
- NMPA streamlined registration pathways:Accelerated approval timelines for Class III medical devices reduce commercialization lag for energy-based platforms entering Chinese aesthetic clinics.
- Injectable biologics:Hyaluronic acid and neurotoxin formulations command expanding share as recovery intervals shrink and outpatient procedural volume concentrates in tier-one cities.
- Young adult demographic concentration:Urban professionals aged 22-35 in Shanghai, Beijing, and Shenzhen drive procedural frequency through social media channel influence and disposable income allocation.
Market Restraints
- Implant import dependency:Cohesive gel and silicone implant supply concentrates among Korean and German manufacturers, exposing margin compression from currency volatility and logistics disruption.
- Surgeon certification scarcity:Limited residency slots for aesthetic specialization create capacity bottlenecks at premium-tier facilities in tier-one cities.
- SAMR advertising enforcement:Stricter scrutiny of before-after imagery and efficacy claims constrains patient acquisition spend and creative testing velocity for clinic operators.
Strategic Opportunities
- Energy-based device localization:Domestic manufacturing of laser platforms tailored to Asian skin phenotypes opens substitution potential against imported systems.
- Tier-two city penetration:Chengdu, Hangzhou, and Wuhan surgical corridors exhibit underdeveloped clinic density relative to disposable income growth.
- Dual carbon goals alignment:MEE incentives for energy-efficient medical device production create procurement preference tailwinds for certified domestic manufacturers.
Industry Challenges
- Clinical talent pipeline gaps:Aesthetic surgery fellowship completion rates lag procedural demand growth, forcing wage inflation for board-certified practitioners.
- GB standards compliance complexity:Medical laser safety certification timelines extend product launch windows, requiring parallel regulatory track management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cosmetic Surgery Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $66.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
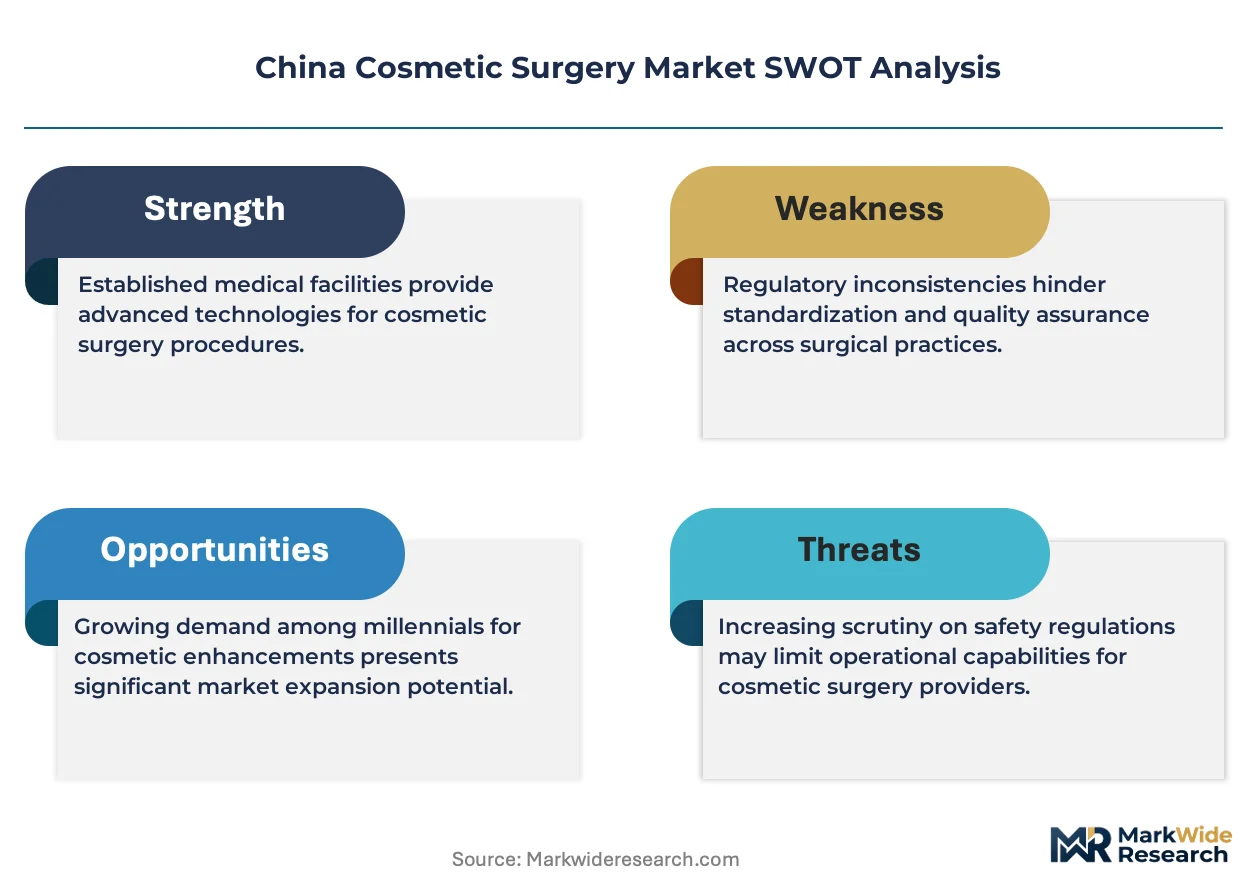
| Segmentation | Procedure Type: Rhinoplasty, Liposuction, Breast Augmentation, Facelift End User: Male, Female, Teenagers, Adults Technology: Laser Surgery, Minimally Invasive, Traditional Surgery, Non-Surgical Operating Facility: Private Clinics, Hospitals, Ambulatory Surgical Centers, Day Surgery Centers |
| Companies Covered | Candela Corporation, Cutera Inc, AbbVie Inc (Allergan Inc), Sisram Medical Ltd (Alma Lasers), Medytox Inc, Nestlé Skin Health (Galderma Laboratories), Lumenis Inc, Bausch Health Companies Inc, Merz Pharma GmbH & Co KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cosmetic Surgery Market Strategic Shifts & Innovations
Technological substitution and regulatory recalibration are compressing traditional procedural boundaries, while patient acquisition channels fragment across digital platforms and direct clinic engagement.
Fractional laser wavelengths between 532 nm and 10,600 nm are migrating from hospital-based dermatology departments to private clinic ownership models. Aesthetic chains in Beijing and Shanghai are acquiring energy-based platforms at accelerated replacement cycles. This technology migration from institutional to commercial settings compresses equipment utilization rates and forces manufacturers toward service-contract bundling.
NMPA tightened medical device registration rules for aesthetic implants, extending clinical trial localization mandates for foreign manufacturers. Multinational entrants must establish domestic trial infrastructure or partner with local principal investigators. Breast augmentation and rhinoplasty device categories face the steepest compliance burden, with some applicants pivoting toward minimally invasive alternatives.
Patient acquisition is fragmenting from aggregator platforms toward clinic-controlled social media channels. Tier-one city operators are building in-house content teams and KOL networks to reduce commission burdens. This channel disintermediation is most visible in Shanghai, where top surgical groups now derive majority bookings through proprietary WeChat ecosystems rather than third-party referral services.
China Cosmetic Surgery Market Segmentation
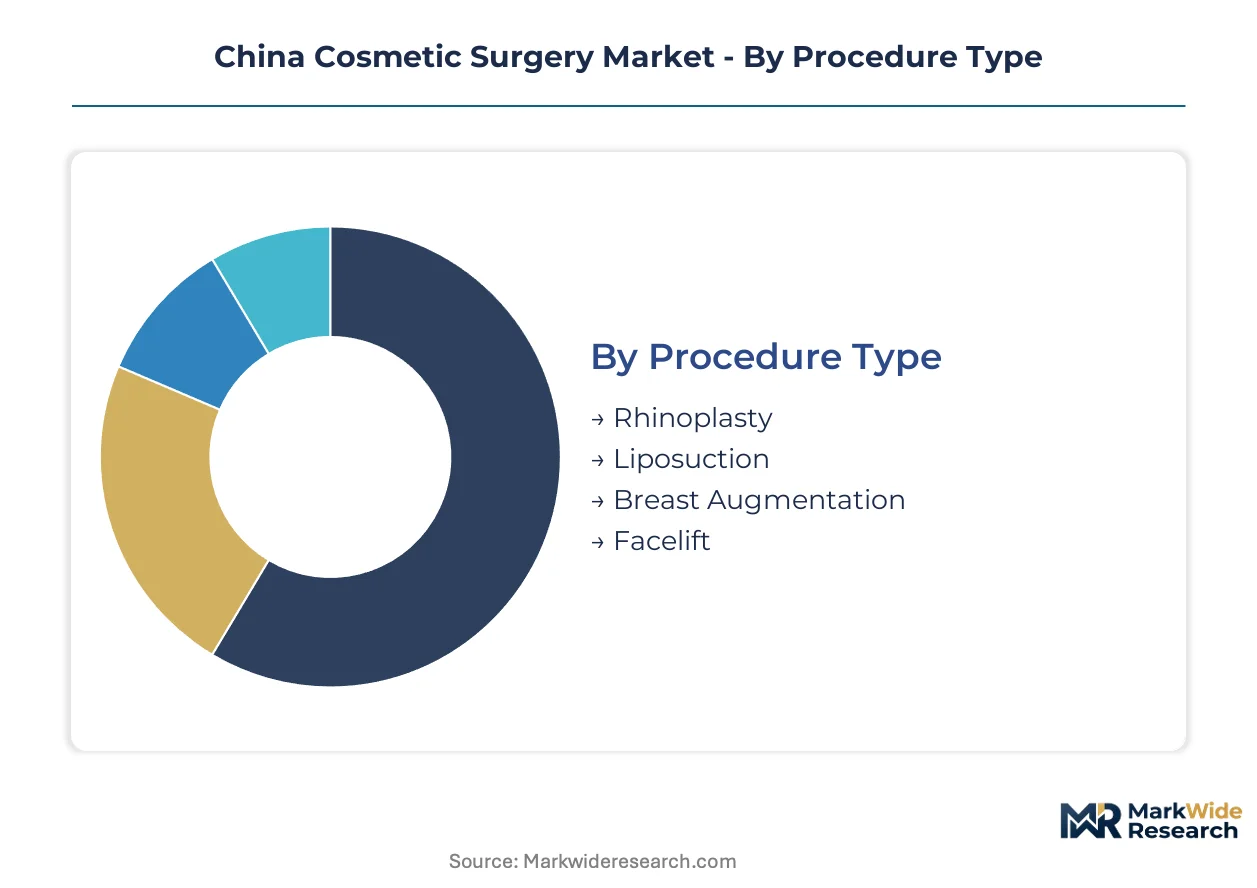
Procedural mix in China cosmetic surgery reflects divergent margin structures across implant-dependent and energy-based modalities. Segmentation by facility type and technology platform reveals where NMPA compliance burdens concentrate and where domestic substitution accelerates.
Procedure Type:
Cost tier stratification separates import-dependent implant procedures from energy-based alternatives with shorter commercialization pathways.
- Rhinoplasty:Silicone and porous polyethylene implants dominate structural modification, with Korean and German manufacturers controlling supply. Shanghai and Beijing surgical corridors absorb premium pricing due to surgeon certification scarcity and import logistics.
- Liposuction:Energy-assisted platforms utilizing laser wavelengths between 532 nm and 1064 nm displace traditional suction cannulas. Demand concentrates in private clinic chains seeking faster patient turnover and reduced recovery intervals.
- Breast Augmentation:Cohesive gel implants face extended NMPA registration timelines.
- Facelift:SMAS-layer techniques compete with thread lift alternatives.
Rhinoplasty commands the established base. The steepest expansion runs through liposuction.
End User:
Customer type distribution tracks disposable income concentration and social media channel influence across generational cohorts.
- Male:Rhinoplasty and hair transplantation drive procedural volume, with Beijing and Shenzhen clinics reporting rising consultation rates for jawline contouring. Male patient share expands fastest in tier-one cities where professional appearance norms intensify.
- Female:Breast augmentation and facial rejuvenation retain volume leadership across all facility types. Female patients aged 22-35 in Shanghai exhibit highest procedural frequency and bundled service uptake.
- Teenagers:Double eyelid surgery dominates parental-supervised demand.
- Adults:Anti-aging modalities concentrate in private clinic networks.
Female patients anchor revenue concentration. Male patient acquisition represents the fastest-climbing trajectory.
Technology:
Application maturity separates established surgical modalities from platforms benefiting from NMPA registration streamlining.
- Laser Surgery:Fractional and ablative platforms operating at 10600 nm and 1550 nm wavelengths treat resurfacing and pigmentation. Beijing hospital dermatology departments transfer equipment to private ownership models, compressing manufacturer service contract pricing.
- Minimally Invasive:Injectable biologics and thread lifts reduce recovery intervals to 24-72 hours. Shanghai clinic chains capture margin expansion as outpatient volume shifts from inpatient surgical suites.
- Traditional Surgery:Implant-based procedures face certification bottlenecks.
- Non-Surgical:Energy-based tightening and injectable neurotoxins expand fastest.
Laser surgery retains installed base dominance. Minimally invasive modalities gain share fastest.
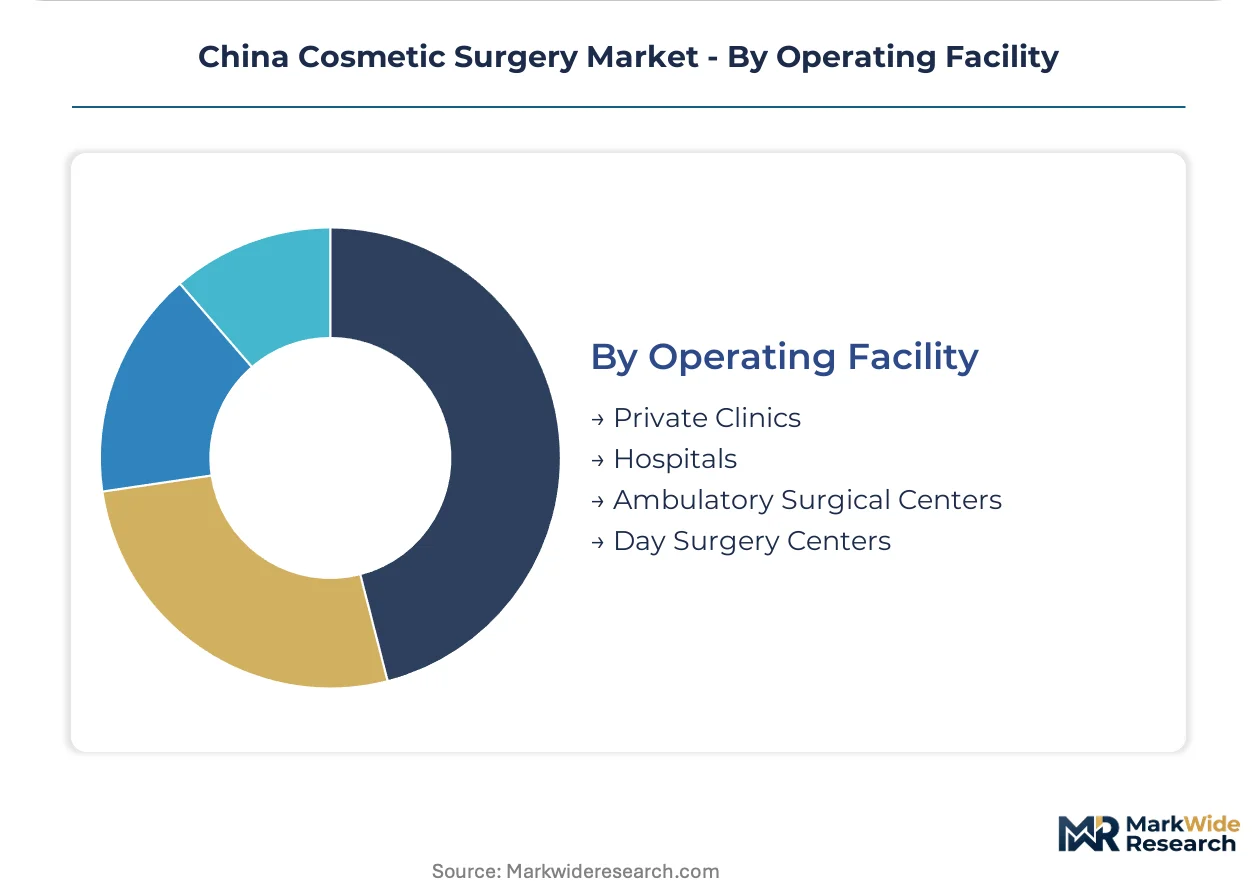
Operating Facility:
Supply concentration across facility types determines pricing autonomy and patient acquisition channel control.
- Private Clinics:Direct-to-consumer marketing through proprietary WeChat ecosystems reduces aggregator commission burdens. Tier-one city surgical groups consolidate margin pools through bundled service packaging and KOL network deployment.
- Hospitals:Public tertiary institutions retain complex reconstructive caseloads and residency training pipelines. NMPA device registration compliance burdens concentrate here due to procurement audit requirements.
- Ambulatory Surgical Centers:Minimally invasive volume migrates to specialized outpatient facilities.
- Day Surgery Centers:Recovery-optimized environments capture injectable and laser procedure share.
Private clinics concentrate premium pricing power. Day surgery centers expand capacity most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Chinese provinces diverge sharply between coastal megacities pursuing premium aesthetic services and interior regions where minimally invasive volume concentrates at lower price points. Tier-one surgical corridors absorb disproportionate implant-dependent procedure share, while tier-two markets favor energy-based platforms with faster commercialization pathways.
Yangtze River Delta
Shanghai anchors procedural volume leadership through young professional demand for facial rejuvenation and body contouring. NMPA streamlined registration pathways accelerate device approvals for energy-based platforms entering aesthetic clinics. Suzhou and Hangzhou surgical corridors capture spillover demand as clinic chains expand proprietary WeChat booking ecosystems.
Pearl River Delta
Shenzhen and Guangzhou drive male patient acquisition for rhinoplasty and hair transplantation services. SAMR advertising enforcement constrains before-after imagery deployment across social media channels. Dongguan manufacturing clusters supply laser platform components to domestic device assemblers targeting Asian skin phenotype customization.
Beijing-Tianjin-Hebei
Capital-region hospitals retain complex reconstructive caseloads and residency training pipelines for aesthetic specialization. GB standards for medical laser safety extend certification timelines for multinational device entrants. Tianjin port logistics handle cohesive gel implant imports from Korean manufacturers serving northern tier-one clinics.
Sichuan-Chongqing
Chengdu exhibits underdeveloped clinic density relative to disposable income growth among urban professionals aged 22-35. MEE incentives for energy-efficient medical device production create procurement preferences for certified domestic manufacturers. Chongqing surgical groups test bundled service packaging for thread lift and injectable biologics combinations.
Shandong Peninsula
Qingdao and Jinan absorb secondary demand for breast augmentation and liposuction as tier-two city penetration accelerates. Dual carbon goals alignment shapes hospital procurement criteria for laser surgery platforms with reduced power consumption. Weihai medical device subcontractors supply fractional laser handpiece components to domestic OEMs.
China Cosmetic Surgery Market Key Industry Players
Capability concentration sits with multinational device manufacturers holding NMPA Class III registrations; scale advantage sits with domestic clinic chains controlling patient acquisition channels. The vendor base separates into three tiers: global implant suppliers, energy-based platform manufacturers, and regional service aggregators. Strategic moves concentrate on backward integration into biologics manufacturing and proprietary channel development through direct-to-consumer digital ecosystems.
Within the multinational device tier, AbbVie Inc (Allergan Inc) and Sisram Medical Ltd (Alma Lasers) exemplify divergent positioning strategies. AbbVie anchors premium positioning through captive supply of hyaluronic acid fillers. Sisram occupies a specialization position via energy-based device portfolios. Medytox Inc represents regional manufacturing scale within neurotoxin supply chains.
| Leading Market Players |
|---|
| Candela Corporation |
| Cutera Inc |
| AbbVie Inc (Allergan Inc) |
| Sisram Medical Ltd (Alma Lasers) |
| Medytox Inc |
| Nestlé Skin Health (Galderma Laboratories) |
| Lumenis Inc |
| Bausch Health Companies Inc |
| Merz Pharma GmbH & Co KGaA |
| Others |
Cost & Logistics Intelligence
Tianjin port freight corridors absorb elevated logistics costs for Korean-manufactured cohesive gel implants, compressing margins for northern tier-one clinics while southern operators exploit Dongguan component sourcing to sustain price differentiation across premium and standard service tiers.
Pricing Analysis
Long-term offtake contracts dominate implant procurement between Korean manufacturers and Beijing-Shanghai surgical chains, while spot purchasing governs energy-based device transactions. Price differentiation rests on NMPA Class III certification status and surgeon board certification tier. Cost compression in minimally invasive segments is intensifying because domestic device manufacturers are undercutting imported laser platform pricing. Tier-two city patients exhibit highest price sensitivity; tier-one young professionals demonstrate lowest sensitivity due to social media-influenced quality prioritization.
Supply Chain Analysis
Extended payment terms from Korean implant manufacturers to domestic clinic chains have tightened to 45 days from 90 days, straining working capital. Geographic supply concentration centers on South Korea and Germany for cohesive gel and silicone implants, with China dominating fractional laser component assembly. Raw material dependencies include medical-grade silicone, hyaluronic acid fermentation feedstock, and 1064 nm laser diode arrays. Single-source vulnerability runs through Korean neurotoxin API supply. Distribution feeds from manufacturer-certified service engineers directly into clinic equipment procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in tier-two surgical corridors where patient acquisition channel control remains undeveloped and disposable income growth outpaces clinic density expansion.
For Market Incumbents: Entrench NMPA registration expertise as a defensive moat against emerging domestic device manufacturers by accelerating Class III pathway navigation for next-generation energy platforms. Secure exclusive surgeon certification pipelines through residency fellowship sponsorships to lock in talent scarcity leverage. For New Entrants and Emerging Players: Chengdu and Wuhan surgical corridors present white-space penetration targets where WeChat-native patient acquisition infrastructure remains underbuilt. Target male jawline contouring segments in Shenzhen where consultation rates climb fastest. Deploy KOL-network-first go-to-market strategies to bypass aggregator commission structures. For Investors and Strategic Acquirers: NMPA-authorized domestic device assemblers with Asian skin phenotype customization capabilities represent the priority acquisition archetype. Long-term viability hinges on regulatory localization speed rather than technology differentiation alone. Monitor SAMR advertising enforcement intensity as the inflection signal for patient acquisition cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Compresses commercialization lag for energy-based platforms entering Shanghai aesthetic clinics. |
| Domestic Laser Device Manufacturing Scale-Up | Enables substitution against imported systems through MEE energy-efficiency certification alignment. |
| Exclusive Surgeon Fellowship Sponsorship | Locks in board-certified talent pipelines amid aesthetic specialization residency slot scarcity. |
| Proprietary WeChat Patient Acquisition Buildout | Reduces aggregator commission burdens for tier-one clinic chains in Beijing and Shanghai. |
| Hyaluronic Acid Biologics Backward Integration | Captures margin pools currently extracted by AbbVie's captive filler supply dominance. |
Research Approach
Desk research of NMPA medical device registration databases, SAMR advertising enforcement bulletins, and hospital procurement records preceded structured interviews with aesthetic clinic chain operators, biomedical device regulatory consultants, and GPO contracts managers. Primary fieldwork with Shanghai and Beijing surgical group procurement heads validated secondary estimates of equipment replacement cycles and bundled service pricing. Bottom-up procedural volume modeling triangulated against top-down disposable income allocation surveys across tier-one and tier-two urban centers.
The analytical framework held NMPA regulatory trajectory and dual carbon goals procurement incentives fixed across the projection horizon while varying urban professional demographic growth assumptions. Segmentation dimensions modeled encompassed procedure invasiveness tier, technology platform wavelength category, facility ownership structure, and patient generational cohort. CAGRs derived from equipment installed base expansion rates and per-procedure revenue yield compression trends. Forecast inputs included social media channel influence coefficients and surgeon certification completion pipeline data.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by domestic energy-device manufacturers would shift outcomes beyond modeled ranges. Macroeconomic volatility affecting medical tourism flows, regulatory deviation in provincial SAMR enforcement intensity, or technological substitution in neurotoxin formulation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Surgery
Breast Reconstruction Surgery and Treatment Market
Cosmetic Surgery
UK Cosmetic Surgery Market
Cosmetic Surgery
Global Mastopexy Market
Cosmetic Surgery
France Cosmetic Surgery Market
Cosmetic Surgery
US Sex Reassignment Surgery Market
Cosmetic Surgery
US Gender Reassignment Surgery Market
Cosmetic Surgery
Japan Cosmetic Surgery Market
Cosmetic Surgery
Minimally Invasive Cosmetic Procedures Market
Cosmetic Surgery
Germany Cosmetic Surgery Market
Cosmetic Surgery
Reconstructive Surgery Market
Cosmetic Surgery
Gynecomastia Procedures Market
Cosmetic Surgery
India Cosmetic Surgery Market
Cosmetic Surgery
Australia Cosmetic Surgery Market
Cosmetic Surgery
Mexico Cosmetic Surgery Market
Cosmetic Surgery
Liposuction Market
Cosmetic Surgery
North America Cosmetic Surgery Market