
 Cosmetic Ingredients Market | 2026-2036
Cosmetic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Ingredients Market Intelligence
Expanded production capacity in China is tilting the supply balance for commodity ingredients like certain surfactants and emollients. BASF SE leverages its extensive R&D infrastructure to develop high-performance active ingredients. Croda International Plc differentiates through its focus on sustainable and ethically sourced materials. Meanwhile, Dow Inc. competes on the scale of its polymer and silicone production for personal care applications.
Cosmetic ingredients are the individual chemical compounds and raw materials, both synthetic and natural, that constitute personal care products. These substances provide specific functions, such as moisturization, preservation, or delivering active benefits to the skin and hair. The skin care application segment continues to command the largest share, driven by a high valuation on active ingredients. Within product types, emollients and surfactants form the high-volume base, while specialized antioxidants and preservatives command higher margins.
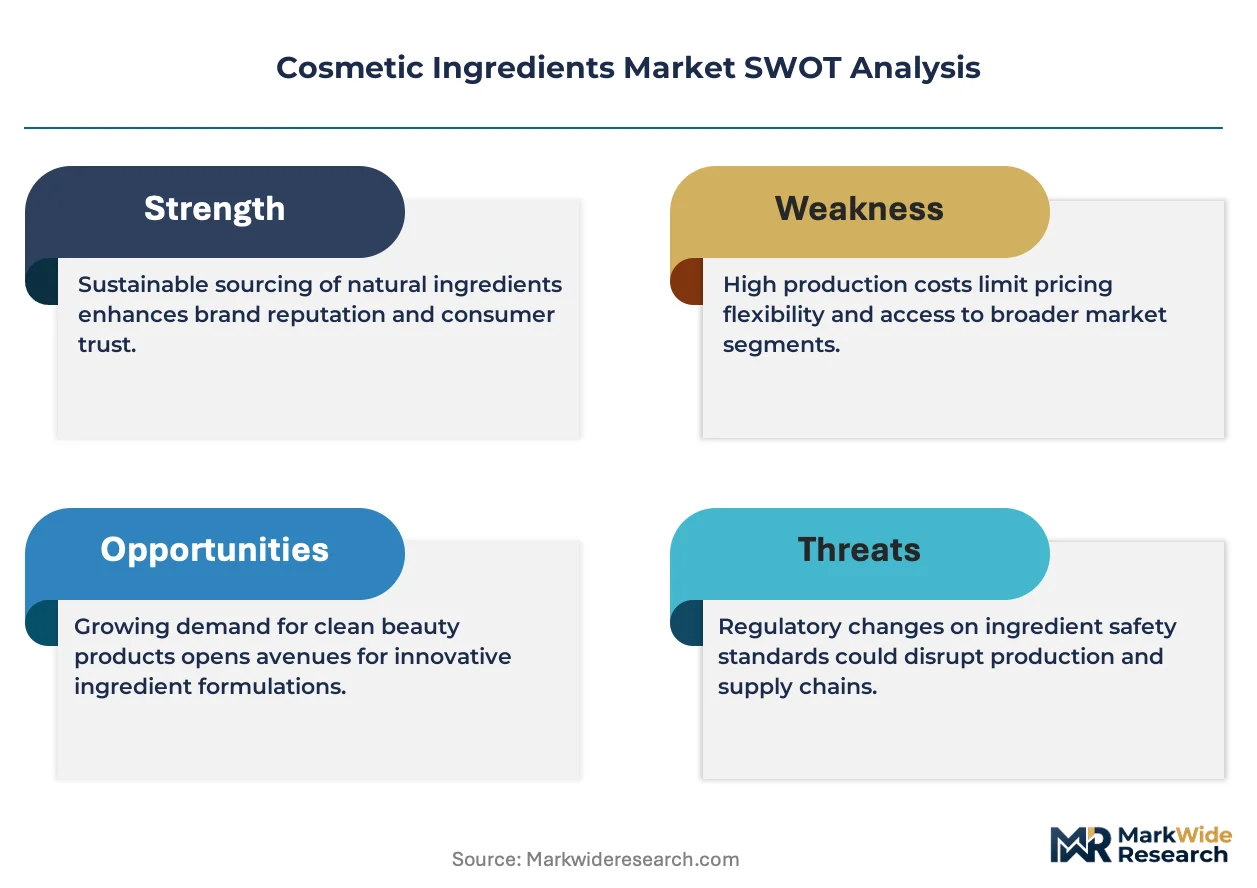
Regulatory frameworks are a primary force shaping product development and market access. The European Union's REACH and ECHA regulations impose strict chemical safety and registration requirements. In the United States, the FDA's oversight governs ingredient safety and labeling for all cosmetics. Navigating the divergence in international 'clean' and 'natural' ingredient definitions will be a central strategic challenge for formulators and brands.
Market Dynamics
The central market dynamic is the structural tension between consumer demand for natural, sustainable ingredients and the industry's scaled manufacturing reliance on petrochemical-derived commodity chemicals. This conflict drives innovation in green chemistry and biotechnology to bridge the performance and cost gap.
Growth Catalysts
- Sustainable Sourcing Mandates:Regulatory frameworks like the EU Green Deal are compelling manufacturers to prioritize biodegradable and ethically sourced materials, stimulating R&D in green chemistry and bio-fermentation for active ingredients.
- Demand for Multifunctionality:The 'skinimalism' trend, particularly in North American and European markets, boosts demand for single ingredients that offer multiple benefits, such as moisturizing antioxidants or sun-protecting emollients, simplifying formulations.
- Beauty Tech Innovation Hubs:Advanced beauty markets, led by South Korea, accelerate the adoption of novel ingredients. The rapid product development cycles in K-beauty create a consistent pull for new textures, actives, and delivery systems.
Market Restraints
- Input Cost Volatility:Reliance on agricultural feedstocks for natural ingredients introduces price and supply volatility linked to climate events and crop yields, impacting margins for botanical extracts and essential oils.
- Regulatory Divergence:Conflicting definitions and standards for 'clean' and 'natural' ingredients between major markets, such as the EU's ECHA framework and the FDA's oversight in the US, create compliance friction for brands.
- Commodity Supply Concentration:The concentration of high-volume surfactant and silicone production in China creates potential supply chain vulnerabilities and pricing pressures for formulators dependent on these foundational materials.
Strategic Opportunities
- Bio-fermentation Scale-Up:Advances in biotechnology present an opportunity to produce nature-identical actives like peptides and hyaluronic acid with greater consistency, purity, and sustainability than traditional extraction methods.
- Expansion in Southeast Asia:Markets such as Indonesia and Vietnam represent significant growth potential, with rising disposable incomes and a growing consumer base seeking sophisticated skin care and hair care solutions.
- Ingredients for Microbiome Health:A deeper scientific understanding of the skin microbiome opens a new frontier for pre, pro, and post-biotic ingredients designed to support a healthy skin barrier function.
Industry Challenges
- Chemical Registration Timelines:Navigating the complex and lengthy registration process for new chemical entities under regulations like the EU's REACH can delay market entry for innovative ingredients by several years.
- Supply Chain Traceability:Establishing and documenting full traceability for natural ingredients to meet consumer and regulatory demands for transparency is a significant operational and logistical challenge for suppliers.
- Standardization Gaps:The absence of a harmonized global standard for 'natural' or 'organic' cosmetic ingredients forces suppliers to navigate a patchwork of disparate private and national certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Ingredients Market |
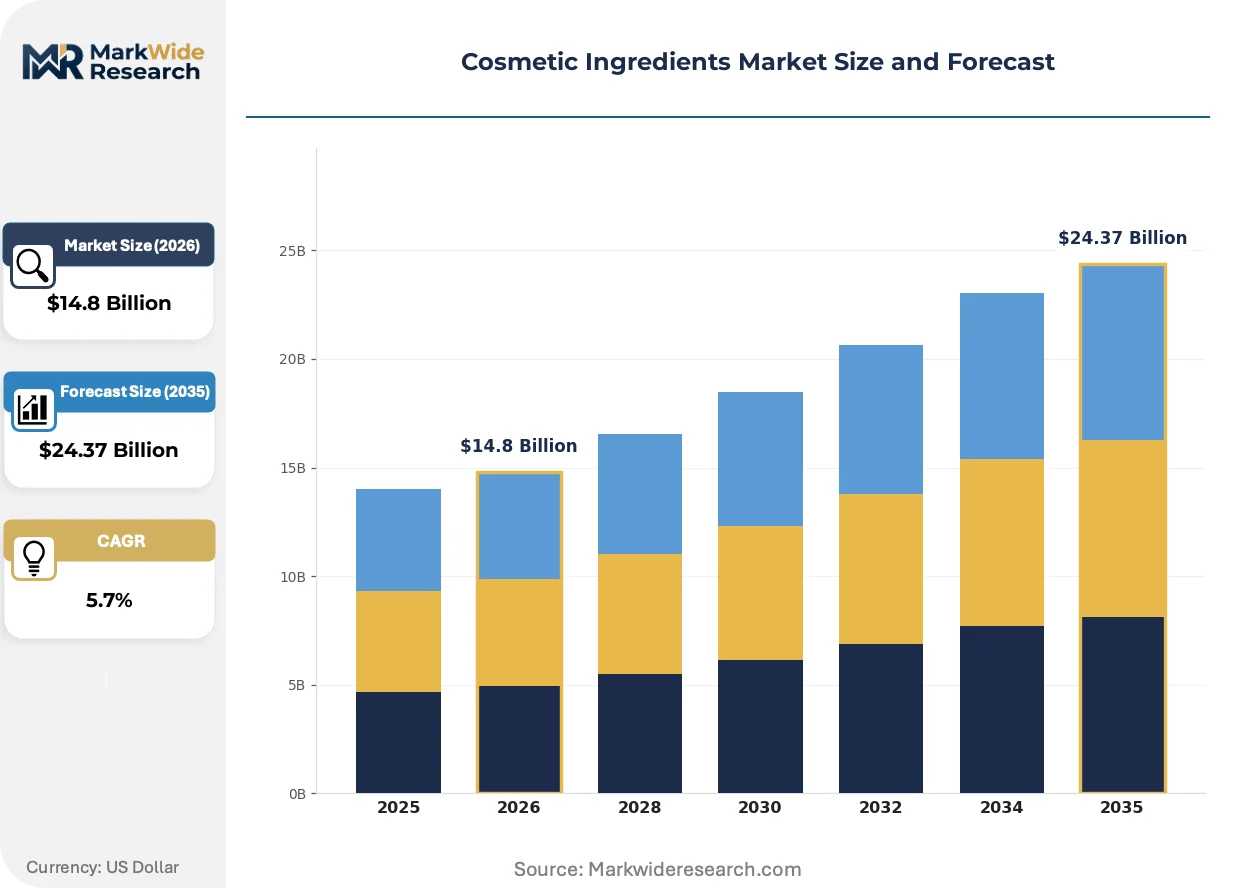
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Humectants, Surfactants, Antioxidants, Preservatives, Thickeners Application: Skin Care, Hair Care, Makeup, Oral Care, Sun Care, Fragrances End User: Cosmetics Manufacturers, Personal Care Brands, Dermatology Clinics, Spas, Salons, Online Retailers Form: Liquid, Powder, Gel, Paste, Oil, Cream |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, Croda International Plc, Clariant AG, Solvay SA, Ashland Global Holdings Inc., Innospec Inc., The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Ingredients Market Strategic Shifts & Innovations
Biotechnology is fundamentally altering ingredient discovery and production, enabling the creation of high-performance, sustainable actives that were previously unfeasible to source or synthesize at scale. This shift is accompanied by a demand for clinical-level data to substantiate product efficacy claims.
Precision fermentation is a key enabling technology for producing pure, nature-identical molecules like squalane or collagen. Premium skin care and 'clean' beauty brands are the primary adopters, seeking alternatives to animal-derived or environmentally taxing ingredients. This technology is hybridizing the performance of synthetics with the marketing appeal of natural sourcing, compressing the innovation cycle for potent actives.
Regulatory bodies are increasing scrutiny on ingredient safety and marketing claims, exemplified by China's NMPA updates. These rules mandate more extensive safety data and efficacy substantiation for new ingredients entering the Chinese market. This raises the compliance burden but also levels the playing field, forcing suppliers to invest in robust clinical testing and documentation, particularly for active ingredients targeting the skin care segment.
A significant behavioral shift is the rise of the 'skintellectual' consumer who actively researches ingredient lists before purchase. This trend, amplified by digital platforms and mobile apps, disrupts traditional brand loyalty and elevates the importance of ingredient-led marketing. The direct-to-consumer channel in markets like the United States and Australia is where this ingredient-centric purchasing behavior is most pronounced.
Cosmetic Ingredients Market Segmentation
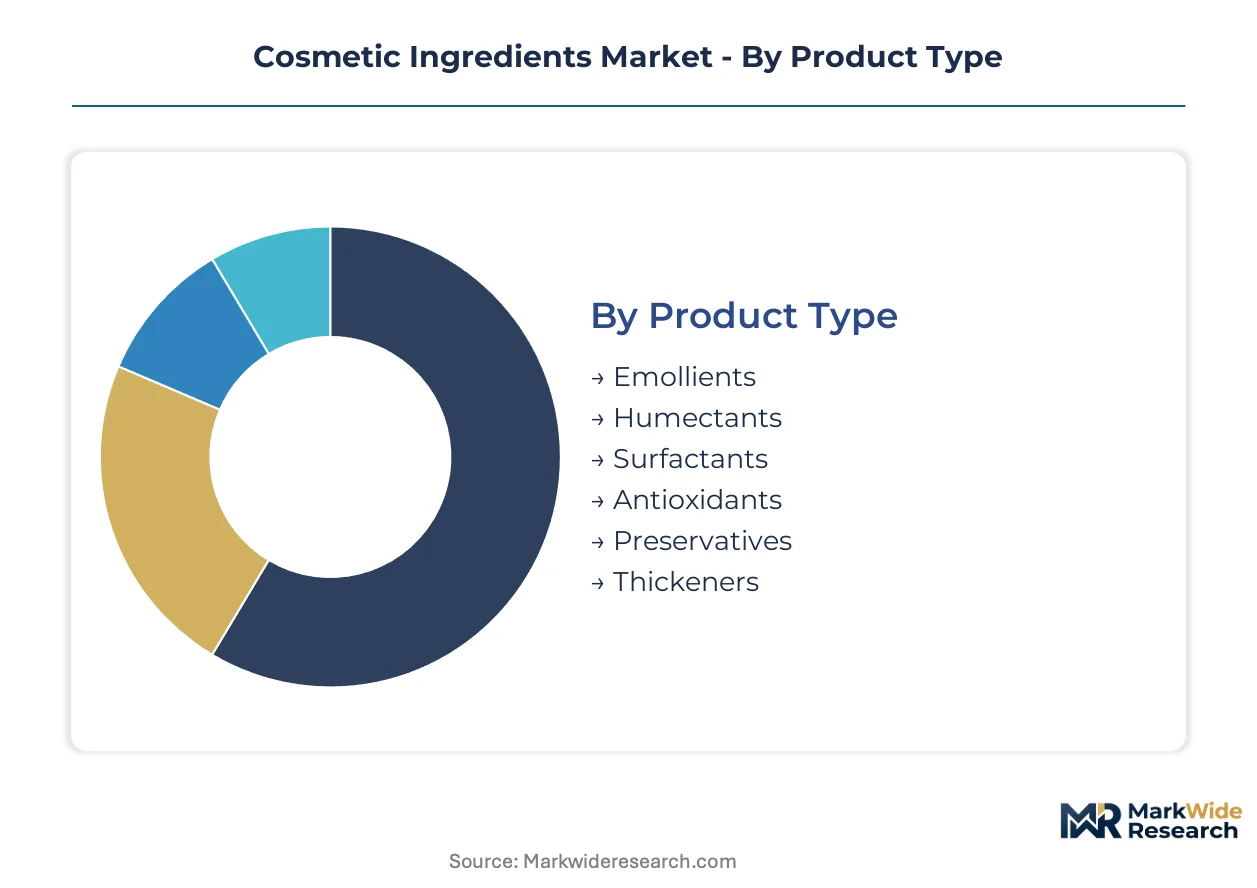
Understanding the Cosmetic Ingredients Market through segmentation reveals the diverse functional roles these materials play in personal care formulations. This granular analysis provides insights into ingredient demand patterns across various product types and end-use applications. Formulators strategically select ingredients based on desired performance, regulatory compliance, and consumer trends.
Product Type:
Cosmetic ingredients span a wide use-case spectrum, from foundational textural components to highly specialized active compounds delivering targeted benefits.
- Emollients:These ingredients provide skin softening and smoothing properties, often preventing water loss. Demand concentrates in the skin care sector across Europe, driven by consumer preference for barrier-supporting formulations.
- Surfactants:These compounds serve as cleansing agents, emulsifiers, and foaming agents, crucial for product stability. High-volume use in hair care and cleansing products across global markets sustains daily hygiene routines.
- Humectants:These ingredients attract and retain moisture in skin or hair, essential for hydration claims.
- Antioxidants:These protect formulations and skin from oxidative damage, with rising demand for natural extracts in premium skin care.
- Preservatives:These inhibit microbial growth, ensuring product safety and shelf life, under strict regulatory scrutiny.
- Thickeners:These modify viscosity and texture of cosmetic formulations, enhancing sensory appeal.
The dominant share belongs to Emollients, while Antioxidants are closing the gap fastest.
Application:
The diverse application landscape for cosmetic ingredients reflects varying consumer needs and product functionalities across personal care categories.
- Skin Care:This segment uses broad ingredients, including active compounds and moisturizers. High consumer valuation on active ingredients in South Korea drives innovation.
- Hair Care:Formulations rely on surfactants, conditioners, and styling polymers to cleanse, nourish, and manage hair. The Asia-Pacific region exhibits significant volume consumption for shampoos and conditioners.
- Makeup:This requires pigments, binders, and film-formers, with innovation focused on long-wear and skin-benefiting properties.
- Oral Care:This incorporates abrasives, fluoride, and antimicrobials for dental hygiene, adhering to specific health regulations.
- Sun Care:This demands UV filters and antioxidants for protection against solar radiation, with stringent efficacy testing required.
- Fragrances:This utilizes essential oils, aroma chemicals, and fixatives to impart scent, requiring complex formulation for stability.
Skin Care applications consistently account for the largest volume consumption, reflecting its broad consumer base and daily usage.
End User:
The procurement and distribution channels for cosmetic ingredients vary significantly based on the end-user's scale and specialization.
- Cosmetics Manufacturers:These large-scale entities purchase raw ingredients in bulk to produce various personal care products. Their demand is driven by efficiency and cost-effectiveness for global distribution.
- Personal Care Brands:Brands source ingredients to develop unique formulations aligning with their identity and consumer preferences. This segment prioritizes innovative, sustainable materials for differentiation.
- Dermatology Clinics:These acquire specialized active ingredients for professional-grade treatments and prescriptions, emphasizing efficacy.
- Spas:These utilize ingredients for professional facial and body treatments, focusing on natural extracts and sensory experiences.
- Salons:These procure hair care and skin care ingredients for professional services, seeking bulk formats and performance-driven formulations.
- Online Retailers:Some specialized online platforms offer raw ingredients to DIY formulators or small-batch producers.
Cosmetics Manufacturers and Personal Care Brands represent the primary direct purchasers of ingredients, shaping bulk procurement patterns.
Form:
The physical form of cosmetic ingredients dictates their handling, formulation compatibility, and ultimate application within finished products.
- Liquid:Many active ingredients, extracts, and humectants are supplied in liquid form, facilitating dispersion and integration. This format is widely adopted in manufacturing processes across Europe and North America.
- Powder:Pigments, mineral sunscreens, and botanical extracts are commonly supplied as powders, offering stability and concentrated delivery. Demand is significant in makeup and dry-mix formulations, especially in Asian markets.
- Gel:Ingredients like carbomers or hyaluronic acid are supplied as gels or gel-forming agents, valued for thickening and sensory properties.
- Paste:Certain emollients, waxes, or clay-based ingredients are delivered as pastes, providing specific textural and binding characteristics.
- Oil:Natural oils and essential oils provide emollients, carriers, or active components in skin and hair care.
- Cream:Some pre-blended bases or specialized actives might be delivered in a cream-like consistency for ease of use.
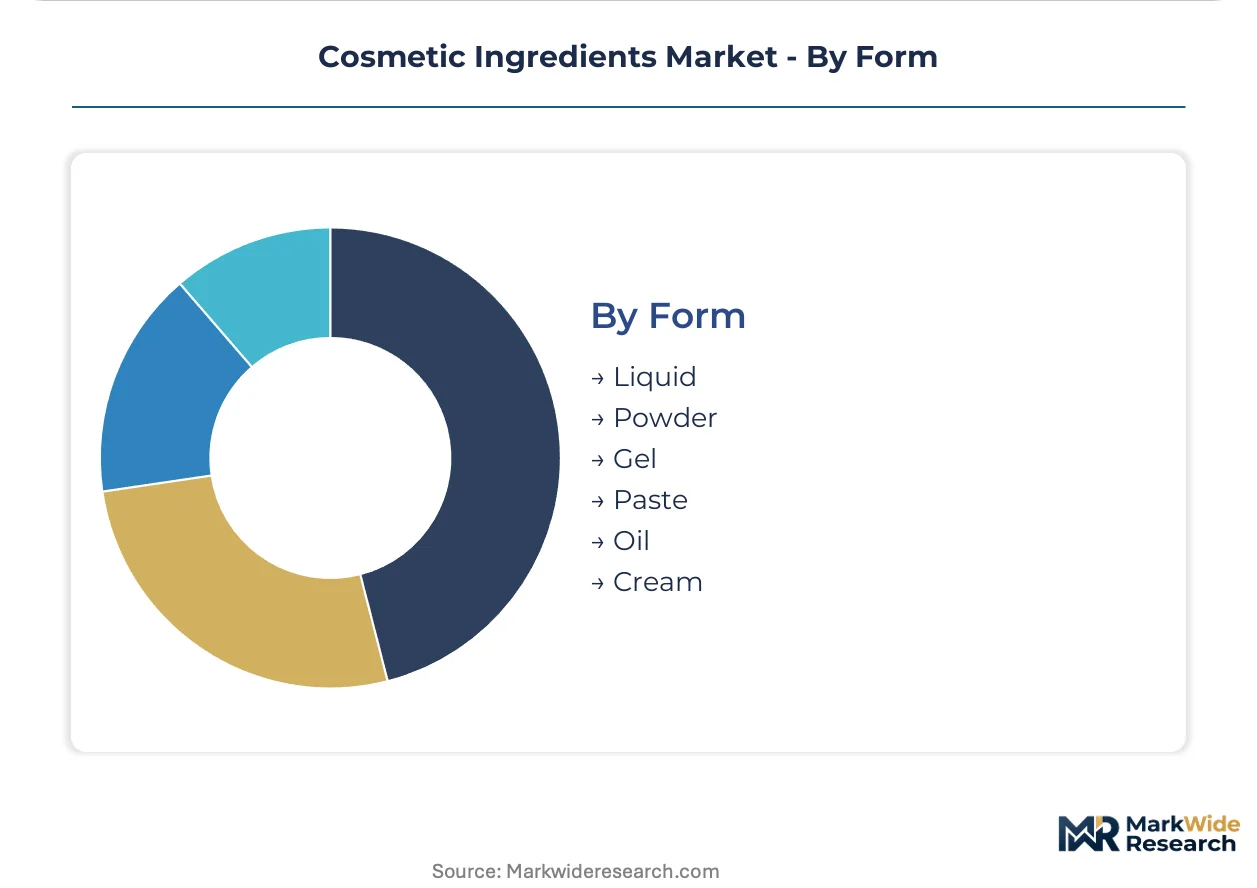
Liquid and Powder forms offer the greatest versatility for formulators, enabling integration into a wide array of cosmetic products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's ECHA regulations significantly influence cosmetic ingredient development across member states. These stringent frameworks prioritize chemical safety and environmental impact for formulators. Global demand for natural and sustainable materials shapes regional market dynamics, driving innovation and compliance efforts.
Germany
Germany's robust chemical industry drives demand for high-performance active ingredients. REACH regulations and the EU Green Deal compel manufacturers to prioritize sustainable sourcing. The Rhine-Ruhr area hosts numerous specialized chemical producers developing bio-based solutions.
United States
American consumer preference for 'clean' beauty products shapes ingredient demand. The FDA's oversight governs ingredient safety and labeling for all cosmetics marketed domestically. California's beauty industry fosters innovation in natural extracts and direct-to-consumer ingredient marketing.
South Korea
South Korea's rapid product development cycles create consistent demand for novel ingredients and advanced delivery systems. The MFDS enforces strict safety and efficacy standards for cosmetic formulations. Seoul's beauty tech innovation hubs accelerate the adoption of new textures and potent actives.
China
China's expanded production capacity for commodity ingredients balances global supply for many basic chemicals. The NMPA updates mandate extensive safety data and efficacy substantiation for new ingredients. The Yangtze River Delta region is a major manufacturing base for surfactants and emollients.
India
India's rising disposable incomes drive increased demand for sophisticated skin care and hair care solutions. BIS standards ensure product quality and safety for local and imported cosmetic products. Mumbai serves as a commercial hub for both domestic and international ingredient suppliers.
Cosmetic Ingredients Market Key Industry Players
Specialty ingredient formulators and commodity chemical giants split the cosmetic ingredients market, reflecting a tiered competitive structure. This landscape combines highly fragmented niche players with a few large, diversified corporations. Key archetypes include R&D-intensive innovators focused on high-margin actives and scale-driven bulk producers of foundational materials. Companies pursue strategic partnerships and portfolio diversification to enhance their competitive positioning and market reach.
At the scale-driven end, Dow Inc. and BASF SE exemplify companies leveraging extensive chemical production capabilities for personal care applications. These global corporations provide a broad portfolio of foundational ingredients, including polymers and surfactants. Croda International Plc, meanwhile, represents the archetype of a specialty ingredient provider, focusing on sustainable and ethically sourced materials for premium formulations. These entities occupy distinct positions within the market, from high-volume foundational chemicals to premium, performance-enhancing actives, reflecting diverse strategic approaches.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| Croda International Plc |
| Clariant AG |
| Solvay SA |
| Ashland Global Holdings Inc. |
| Innospec Inc. |
| The Lubrizol Corporation |
Cost & Logistics Intelligence
Overcapacity in commodity chemical production in China drives both supplier behavior and pricing posture, particularly for foundational cosmetic ingredients. This dynamic incentivizes aggressive pricing strategies while specialty ingredient suppliers maintain premium positions.
Pricing Analysis
Geographic price spreads for cosmetic ingredients reflect regional supply concentrations and regulatory compliance costs. The dominant pricing structure for high-volume commodity ingredients like surfactants and emollients is contract-based long-term offtake, while specialized actives often employ value-based or tiered models. Price differentiation stems from quality grade, specific certifications like Ecocert or COSMOS, and the volume scale of procurement. Pricing softness affects commodity ingredients due to expanded production capacity, while R&D-intensive bio-fermented actives command higher margins. Cosmetics manufacturers exhibit higher price sensitivity for foundational materials, whereas premium personal care brands prioritize ingredient efficacy and sustainability claims.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common for large-volume purchasers of cosmetic ingredients. Geographic supply concentration for commodity ingredients centers on China, particularly for surfactants and silicones, creating potential vulnerabilities. Raw material dependencies include petrochemical derivatives for synthetic compounds and agricultural feedstocks for natural extracts. Regulatory divergence between major markets, such as ECHA and FDA frameworks, represents a structural supply chain risk for global formulators. Distribution runs through a mix of direct sales from large chemical producers and specialized ingredient distributors, with online platforms serving smaller-batch producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cosmetic Ingredients Market is experiencing a cyclical recovery, driven by renewed consumer spending on personal care products and a focus on wellness.
For Market Incumbents: Insulate core product lines by investing in sustainable sourcing and green chemistry R&D, mitigating the threat of regulatory shifts and new bio-fermentation entrants. Diversify supply chains to reduce reliance on single-country production hubs for commodity chemicals. Prioritize certification investment for new ingredients, ensuring compliance with stringent frameworks like REACH and NMPA updates.
For New Entrants and Emerging Players: Establish a beachhead in niche, high-growth segments like microbiome health ingredients or advanced delivery systems. The premium skin care and 'clean' beauty brand segments represent the most penetrable market opportunities. A compelling go-to-market angle involves substantiating efficacy claims with robust clinical data and ensuring transparent, ethically sourced material narratives.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the bio-fermentation and green chemistry sub-segments, signaling significant R&D and scale-up investments. The long-term viability of this market remains strong, anchored by persistent consumer demand for efficacious and sustainable personal care. Target acquisition archetypes include specialty ingredient providers with proprietary bio-fermentation platforms or robust traceability technologies. Increased patent filings for novel, nature-identical actives serve as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-fermentation | Scales production of sustainable, high-purity actives meeting rising consumer demand. |
| Green Manufacturing Transition | Reduces environmental footprint and aligns with global regulatory mandates like the EU Green Deal. |
| Long-term Supply Agreement for Natural Feedstocks | Secures stable access to critical botanical resources, mitigating input cost volatility. |
| Joint Venture in Advanced Delivery Systems | Accelerates innovation in ingredient encapsulation, enhancing product efficacy and stability. |
| Investment in Traceability Platforms | Ensures transparent sourcing and compliance with evolving consumer and regulatory demands. |
Research Approach
Desk research of regulatory filings, industry association reports, and academic literature preceded structured interviews with R&D directors, procurement leads, and regulatory affairs specialists across the cosmetic ingredients value chain. This dual-pronged approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Both bottom-up and top-down triangulation methods were applied to reconcile data discrepancies and refine market sizing estimates.
Assumptions regarding consumer preference shifts and regulatory stability were held fixed across the analysis window, while technological innovation rates were varied. The analytical framework modeled segmentation dimensions including product type, application, form, and regional regulatory clusters. Compound Annual Growth Rates were derived from historical market performance and projected shifts in demand drivers. Key industry-specific forecast inputs included the adoption rate of bio-fermentation technologies and the impact of 'skinimalism' trends on formulation complexity.
Stress conditions across raw material pricing, geopolitical stability, and regulatory stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions regarding market evolution and competitive responses. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Yeast Autolysates Market
Ingredients
Liquid Feed Market
Ingredients
Interesterified CBE Market
Ingredients
Clean Label Starch Market
Ingredients
Lupine Peptides Market
Ingredients
North America Cocoa Products Market
Ingredients
Salt Market
Ingredients
Coconut Oil Based Products Market
Ingredients
Apple Extract Market
Ingredients
South America Protein Market
Ingredients
Cocoa Processing Market
Ingredients
Corn Steep Liquor Market
Ingredients
US Ingredients Market
Ingredients
Sunflower Protein Market
Ingredients
Global Distillers Grains Market
Ingredients
Oyster Shell Powder Market