
 Liquid Feed Market | 2026-2036
Liquid Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Feed Market Analysis
Molasses is pivoting toward urea-molasses blends as corn syrup price volatility reshapes liquid feed economics. Cargill, Incorporated leverages its North American grain origination network to secure molasses supply contracts. BASF SE anchors its position through precision premix technology that integrates vitamin stability into liquid matrices. Archer Daniels Midland Company dominates bulk distribution infrastructure across the Mississippi River corridor.
Liquid feed denotes free-flowing, pumpable rations containing 30-70% moisture, typically formulated with molasses, urea, fats, and trace minerals to deliver metabolizable energy and bypass protein to ruminants. Protein Supplements command the largest value pool due to soybean meal price linkage and dairy farmer willingness to pay for milk yield response. Energy Supplements represent the fastest-growing category as ethanol co-product streams expand distillers solubles availability for beef backgrounding operations.
The FDA enforces Current Good Manufacturing Practice requirements for animal food under FSMA, compelling liquid feed mills to implement hazard analysis and preventive controls. EPA nutrient management rules in Chesapeake Bay watershed states restrict nitrogen application rates, indirectly stimulating demand for precision-dosed liquid supplements that reduce excretion. Stakeholders must monitor how state-level carbon accounting frameworks treat enteric methane reduction claims tied to liquid feed additives.
Market Dynamics
The FDA's FSMA animal food safety mandates are restructuring liquid feed formulation requirements, forcing mills to retool for hazard analysis and preventive controls while molasses-urea blend economics displace corn syrup dependence.
Growth Catalysts
- Precision Nutrition Demand:Dairy operations in the United States seek metabolizable energy optimization through pumpable rations, driving adoption of protein-fortified liquid supplements.
- FSMA Compliance Requirements:Current Good Manufacturing Practice rules compel liquid feed mills to implement documented hazard controls, creating pull for integrated premix technology.
- Ethanol Co-Product Streams:Distillers solubles availability from biofuel processing is expanding energy supplement formulations for beef backgrounding systems.
Market Restraints
- Input Cost Volatility:Corn syrup price swings destabilize liquid feed economics, forcing formulators toward molasses-urea alternatives with narrower margin profiles.
- Supply Concentration Risk:Mississippi River corridor infrastructure dominates bulk distribution, creating geographic vulnerability to barge and rail disruptions.
- Regulatory Friction:EPA nutrient management rules in Chesapeake Bay watershed states restrict nitrogen application rates, complicating supplement dosing protocols.
Strategic Opportunities
- Underpenetrated Beef Systems:Brazil's Mato Grosso integrated operations present expansion potential for precision-dosed liquid protein supplements in rapidly scaling feedlots.
- Carbon Accounting Tailwinds:State-level frameworks treating enteric methane reduction claims create incentive structures for additive-enhanced liquid feed formulations.
- Distribution Innovation:On-farm blending systems and direct-to-producer delivery models are compressing traditional distributor margins while capturing value.
Industry Challenges
- Formulation Expertise Gap:Liquid matrix vitamin stability engineering requires specialized knowledge that outpaces current technical training pipelines.
- Legacy System Integration:Dry feed infrastructure retrofitting for pumpable rations demands capital outlays that mid-size operations struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Feed Market |
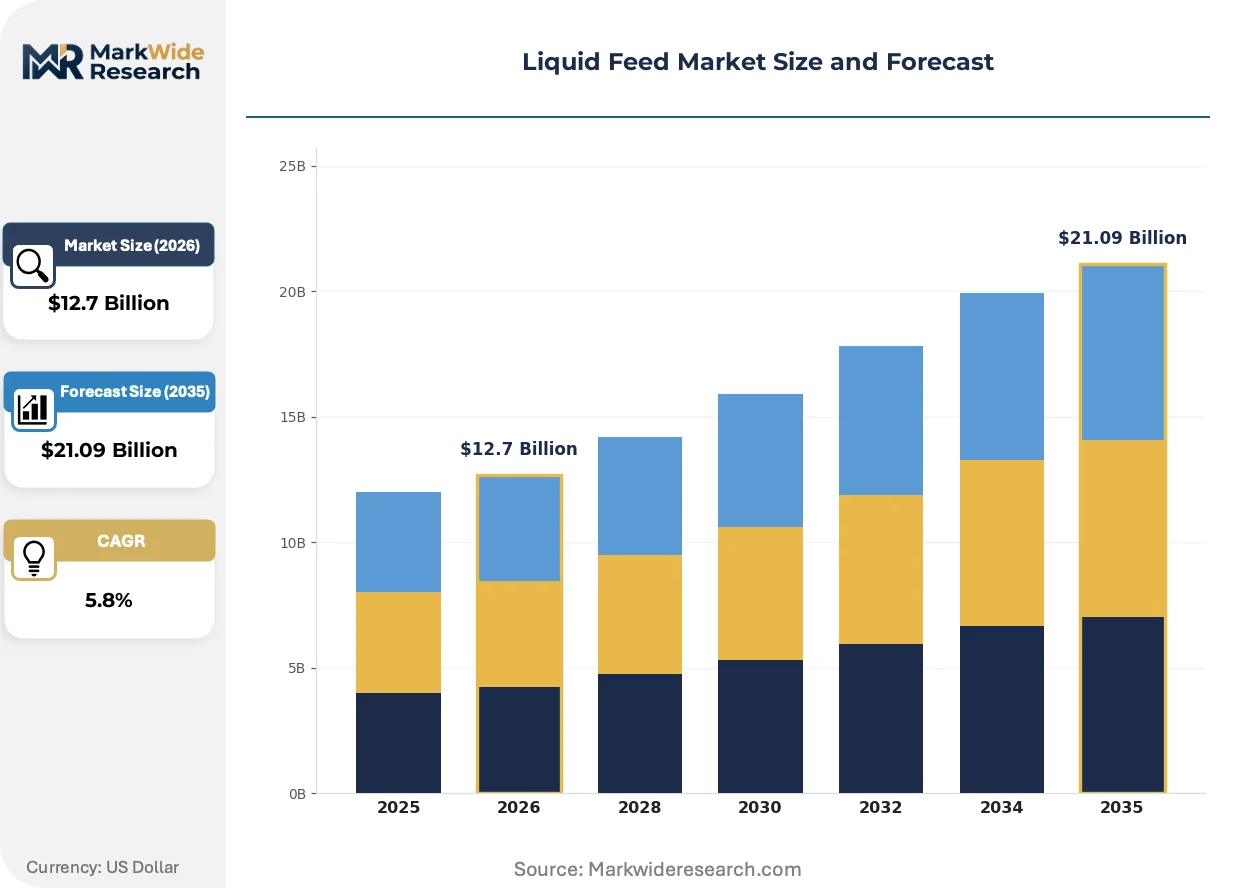
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $21.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Energy Supplements, Nutrient Solutions, Mineral Mixes Application: Dairy Cattle, Beef Cattle, Poultry, Swine End User: Farmers, Agricultural Cooperatives, Feed Manufacturers, Livestock Producers Distribution Channel: Direct Sales, Online Retail, Distributors, Agronomy Stores |
| Companies Covered | GrainCorp Ltd., Liquid Feeds International, Cargill, Incorporated, Voermol Feeds, Alliance Liquid Feeds LLC, Archer Daniels Midland Company, Land O’Lakes Inc., Double S Liquid Feed Services, Inc, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Feed Market Emerging Trajectories
Formulation science and regulatory precision are converging to reshape liquid feed economics, with moisture-content optimization and bypass protein delivery becoming technical battlegrounds.
Encapsulated lipid technology is overtaking conventional fat supplementation in high-performance dairy rations. The technology protects unsaturated fatty acids through rumen passage for direct intestinal absorption. Large herd operations in the upper Midwest are adopting at accelerated rates. This shift is compressing demand for unprotected vegetable oil blends while enabling higher energy density without fermentation disruption.
REACH chemical registration requirements in Europe are tightening trace mineral additive specifications for imported feed materials. The regulation mandates full supply chain disclosure for cobalt, copper, and selenium compounds. Liquid premix exporters to EU member states must revalidate formulation dossiers. German and Dutch compound feed manufacturers are consolidating supplier bases to reduce compliance fragmentation.
Buyer consortiums at the processor level are consolidating procurement of liquid feed additives. Large dairy cooperatives in Wisconsin and California now negotiate direct supply agreements, bypassing traditional distribution layers. This disintermediation is compressing regional distributor margins while transferring formulation specification power to end-users. The pattern is most visible in high-volume protein supplement categories where scale economies dominate.
Liquid Feed Market Segmentation
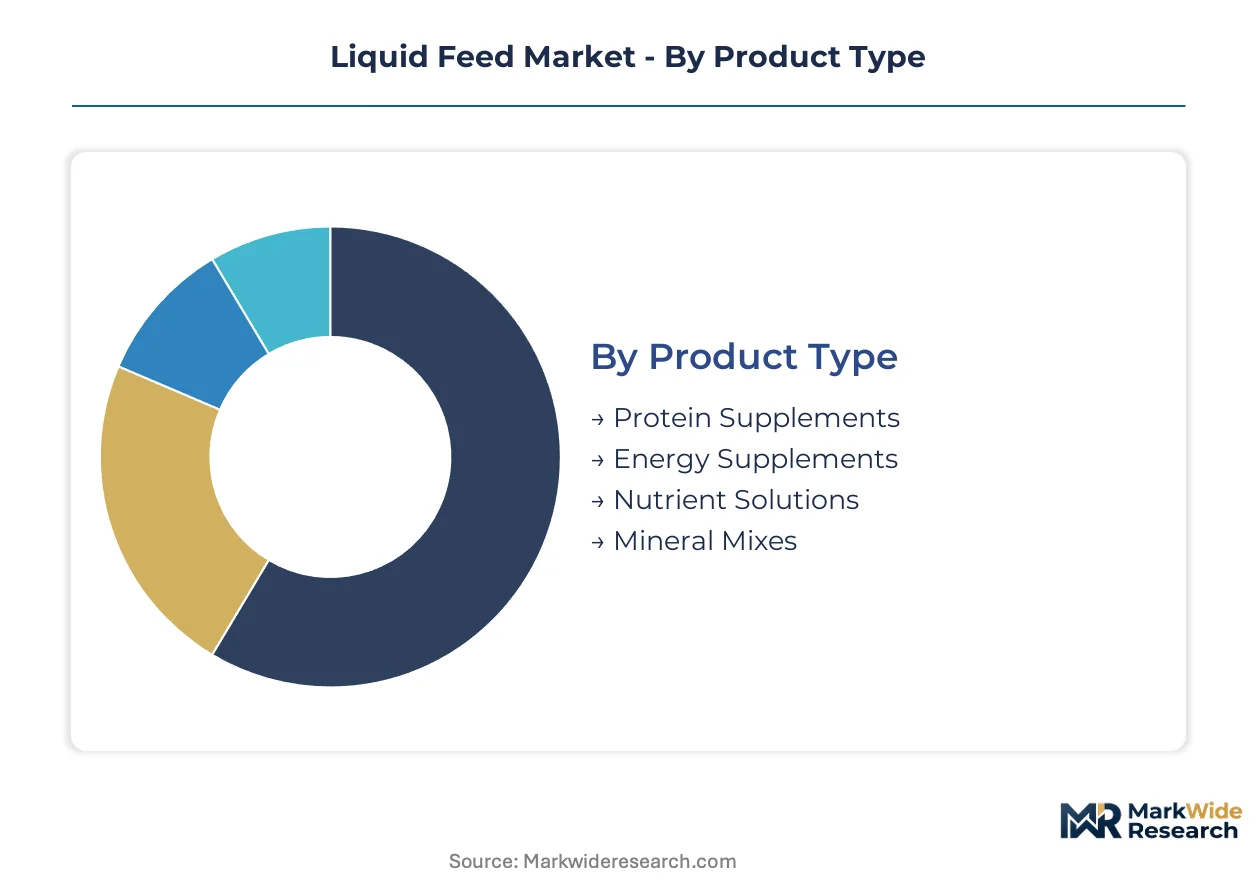
Liquid feed segmentation reflects the tension between commodity bulk formulations and precision-dosed specialty products. Producers select product types based on herd size, labor constraints, and integration with existing feed infrastructure.
Product Type:
Moisture content and nutrient density specifications differentiate liquid feed categories, with formulation science determining functional performance in ruminant digestive systems.
- Protein Supplements:Urea-molasses blends and bypass protein suspensions deliver rumen-degradable and escape protein to dairy operations. Demand concentrates in large Wisconsin and California cooperatives seeking milk yield response optimization amid volatile soybean meal pricing.
- Energy Supplements:Distillers solubles and glycerin-based formulations provide metabolizable energy for beef backgrounding. Rapid adoption is occurring in Texas Panhandle feedlots where ethanol co-product proximity reduces landed costs.
- Nutrient Solutions:Water-soluble vitamin and trace mineral suspensions for precision dosing in automated systems.
- Mineral Mixes:Suspended macro and trace mineral blends targeting specific regional soil deficiencies.
Mature deployment sits with Protein Supplements. Newer deployment is concentrated in Energy Supplements.
Application:
Species-specific digestive physiology drives formulation requirements, with ruminant applications commanding volume leadership due to rumen fermentation compatibility.
- Dairy Cattle:High-producing Holstein operations in the upper Midwest deploy pumpable protein-energy blends through parlor-mounted dispensers. Herds exceeding 1,000 head drive specifications for automated mixing and delivery systems.
- Beef Cattle:Backgrounding and finishing operations in the Southern Plains utilize liquid energy supplements to stretch forage supplies. Mato Grosso integrated systems in Brazil are scaling adoption for zebu crossbreed weight gain protocols.
- Poultry:Limited adoption restricted to breeder operations requiring precise methionine and lysine delivery.
- Swine:Nursery phase applications for palatability enhancement and medication delivery in automated systems.
Volume leadership belongs to Dairy Cattle. Steepest expansion trajectory is occurring in Beef Cattle applications.
End User:
Procurement scale and technical capability determine end-user segmentation, with vertical integration levels shaping supplier relationship structures.
- Farmers:Small-to-mid-scale operations purchasing through agronomy retailers with limited on-farm storage infrastructure.
- Agricultural Cooperatives:Large dairy consortiums in Wisconsin and California negotiating direct supply agreements, bypassing traditional distribution layers.
- Feed Manufacturers:Compound feed mills integrating liquid premixes into total mixed rations for third-party customers.
- Livestock Producers:Vertically integrated beef and dairy operations with captive liquid feed blending capacity.
Procurement consolidation is most advanced among Agricultural Cooperatives. Technical service requirements are highest for Feed Manufacturers.
Distribution Channel:
Channel selection reflects delivery logistics economics and formulation shelf stability requirements.
- Direct Sales:Bulk tanker delivery from manufacturing plants to large operations with on-farm storage. Cargill and ADM leverage Mississippi River corridor infrastructure for cost-efficient bulk movement.
- Distributors:Regional intermediaries maintaining inventory for mid-scale producers requiring smaller batch flexibility.
- Agronomy Stores:Local retail points for tote and drum quantities serving hobby farmers and small commercial operations.
- Online Retail:Emerging channel for specialty additives and small-volume supplements with extended shelf stability.
Margin compression is most severe in Distributor channels. Digital infrastructure investment is concentrating in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Brazil's interior and India's coastal manufacturing corridors are accelerating liquid feed capacity expansion through tariff exemptions and streamlined customs protocols.
United States
Dairy cooperatives in Wisconsin and California drive bulk procurement of protein-fortified liquid supplements through parlor automation investments. FDA's FSMA animal food safety mandates compel mills to implement documented hazard analysis and preventive controls. The Mississippi River corridor anchors bulk distribution infrastructure where barge terminals enable cost-efficient molasses and distillers solubles movement to Texas Panhandle feedlots.
Brazil
Integrated zebu beef systems in Mato Grosso scale liquid energy supplement adoption for weight-gain protocols in rapidly expanding feedlots. ANVISA's feed additive registration requirements shape import compliance for trace mineral premixes. São Paulo state's industrial corridor concentrates formulation manufacturing capacity serving southeastern dairy clusters.
Germany
REACH chemical registration mandates tighten trace mineral additive specifications for cobalt and selenium compounds in imported feed materials. EFSA guidance on animal nutrition influences formulation standards across EU member states. The Lower Rhine region hosts compound feed manufacturers consolidating supplier bases to reduce compliance fragmentation.
India
FSSAI's feed safety regulations and state-level dairy development boards stimulate organized sector adoption of pumpable nutrient solutions. The National Dairy Development Board's cooperative procurement networks create volume aggregation for liquid supplement trials. Gujarat's Anand district and Karnataka's Bangalore rural belt concentrate precision-dosing infrastructure deployment.
Australia
Extended drought cycles drive demand for molasses-based energy supplements in Queensland and New South Wales cattle operations. The country's national agricultural regulator enforces residue monitoring protocols for imported premix components. Victoria's Gippsland dairy region tests automated blending systems for metabolizable energy optimization in pasture-based systems.
Liquid Feed Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated agribusiness conglomerates commanding bulk formulation volumes while regional blenders capture customized specification work. The vendor base arranges across three tiers: multinational grain processors with captive supply chains, premix technology specialists with stability-engineering capabilities, and independent distributors with last-mile logistics density. Strategic moves concentrate on backward integration into molasses origination and direct-to-producer delivery model deployment.
Among North American grain-origination conglomerates, Cargill, Incorporated and Archer Daniels Midland Company occupy positions defined by Mississippi River corridor infrastructure control and bulk tanker fleet scale. BASF SE exemplifies the premix technology archetype through precision formulation capabilities integrating vitamin stability into liquid matrices. These three anchors represent distinct competitive vectors: supply security, distribution density, and technical specification power.
| Leading Market Players |
|---|
| GrainCorp Ltd. |
| Liquid Feeds International |
| Cargill, Incorporated |
| Voermol Feeds |
| Alliance Liquid Feeds LLC |
| Archer Daniels Midland Company |
| Land O'Lakes Inc. |
| Double S Liquid Feed Services, Inc |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Large dairy cooperatives in Wisconsin and California command contract-based procurement leverage that anchors long-term offtake pricing for protein-fortified liquid supplements. This buyer concentration compresses spot-market premiums while rewarding volume commitments with stabilized molasses and distillers solubles supply.
Pricing Analysis
Short lead-time premiums apply to urgent replenishment orders from Texas Panhandle feedlots facing forage shortfalls. Contract-based long-term offtake dominates bulk procurement, with price differentiation resting on volume scale and FSMA compliance certification tier. Cost compression in standard-grade urea-molasses blends is intensifying because ethanol co-product proximity reduces landed energy supplement costs. Small-to-mid-scale farmers purchasing through agronomy retailers exhibit highest price sensitivity, while vertically integrated livestock producers with captive blending capacity show least.
Supply Chain Analysis
Direct-to-producer channels handle hyperscale cooperative demand through bulk tanker delivery from Mississippi River corridor manufacturing plants. Raw material sourcing draws from Brazilian sugarcane molasses, United States corn ethanol distillers solubles, and Canadian canola oilseed processing streams. Single-source vulnerability concentrates in Mississippi River barge infrastructure for bulk molasses movement. Distribution runs through integrated grain-origination conglomerates with captive tanker fleets serving large dairy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around FSMA compliance capabilities that force smaller regional blenders toward acquisition or exit. Technical specification power is migrating to end-users with direct procurement scale.
For Market Incumbents: Anticipate disintermediation pressure from Wisconsin and California dairy cooperatives negotiating direct supply agreements by securing backward integration into molasses origination. Lock in Mississippi River corridor infrastructure control through barge terminal investments. Defend against premix technology specialists by accelerating vitamin stability engineering R&D. For New Entrants and Emerging Players: Regional distributors with last-mile logistics density represent the most accessible partnership channel for penetrating mid-scale dairy operations in India's Gujarat and Karnataka clusters. Target Brazil's Mato Grosso integrated beef systems for white-space expansion in precision-dosed liquid energy supplements. Deploy on-farm blending system sales as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors premix technology specialists with stability-engineering capabilities over commodity bulk formulators. Long-term viability hinges on regulatory compliance moats widening through REACH and FSMA enforcement convergence. Watch state-level carbon accounting framework adoption as the inflection signal for additive-enhanced formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Origination | Cargill's Brazilian sugarcane supply contracts secure input cost stability against corn syrup volatility. |
| FSMA Compliance Certification Investment | BASF's precision premix technology integrates documented hazard controls for FDA-mandated liquid feed mills. |
| Direct-to-Producer Delivery Model Deployment | ADM's bulk tanker fleet compression eliminates distributor margins for large dairy cooperative procurement. |
| Vitamin Stability Engineering R&D | Encapsulated lipid technology protects unsaturated fatty acids for direct intestinal absorption in Holstein operations. |
| Geographic Manufacturing Footprint Expansion | São Paulo state's industrial corridor concentrates formulation capacity for southeastern Brazilian dairy clusters. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this liquid feed market assessment. Primary interviews with liquid feed mill operators, dairy cooperative procurement directors, beef feedlot nutritionists, and agronomy retail buyers combined with FDA FSMA guidance documents, EPA nutrient management rules, ANVISA registration databases, and REACH chemical dossiers. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Data-stream reconciliation across shipment records, production capacity disclosures, and end-user consumption surveys informed the analytical framework. Segmentation dimensions spanned product type, application species, end-user procurement scale, and distribution channel structure across the projection horizon. CAGRs derived from trend extrapolation of molasses-urea blend economics, ethanol co-product availability curves, and precision dosing infrastructure deployment rates.
Caveats apply where EPA nitrogen application restrictions, Brazilian tariff protocol shifts, or vitamin stability technology breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about FSMA compliance cost trajectories and cooperative procurement consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Yeast Autolysates Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Valerian Root Oil Market
Ingredients
Baking Ingredients Market
Ingredients
Carica Papaya Seed Oil Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Tuna and Algae Omega-3 Ingredient Market
Ingredients
Millet Protein Market
Ingredients
Eucalyptus Oil Market
Ingredients
Cold Pressed Oil Market
Ingredients
Upcycled Citrus Peel Fiber Concentrates Market
Ingredients
Shortening Fats Market
Ingredients
Hops Derivative Market
Ingredients
Vegetable Concentrates Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Sesame Oil Market