
 Oyster Shell Powder Market | 2026-2036
Oyster Shell Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Oyster Shell Powder Market Outlook
Aftermarket technical service revenue is rewriting profitability expectations for calcination equipment suppliers serving oyster shell processors. Omya AG leverages its global carbonates infrastructure to sustain long-term supply agreements with pharmaceutical formulators. Huber Engineered Materials anchors North American production through controlled calcination capacity. Imerys S.A. competes on mineral processing expertise across multiple calcium-derived product lines.
Oyster shell powder consists of calcium carbonate derived from crushed and processed Crassostrea shells, typically containing 90-95% CaCO3 with trace magnesium and strontium; manufacturers apply thermal calcination or mechanical grinding to achieve particle sizes from 50 microns to sub-10 micron grades for targeted absorption rates. Raw powder dominates agricultural liming applications where cost sensitivity outweighs purity requirements, while calcined powder commands premium positioning in pharmaceutical tablet excipients and high-bioavailability animal feed supplements where thermal activation enhances digestibility.
EPA Office of Water standards for agricultural runoff mitigation shape calcium carbonate demand in US soil amendment programs, while EMA quality guidelines for mineral excipients constrain pharmaceutical-grade supply chains to certified Good Manufacturing Practice facilities. China's NMPA and SAMR jointly oversee feed additive registration, creating compliance barriers for uncertified imports. Stakeholders must monitor evolving heavy-metal testing thresholds and carbon footprint disclosure rules as procurement criteria shift beyond unit pricing toward verified supply chain documentation.
Market Dynamics
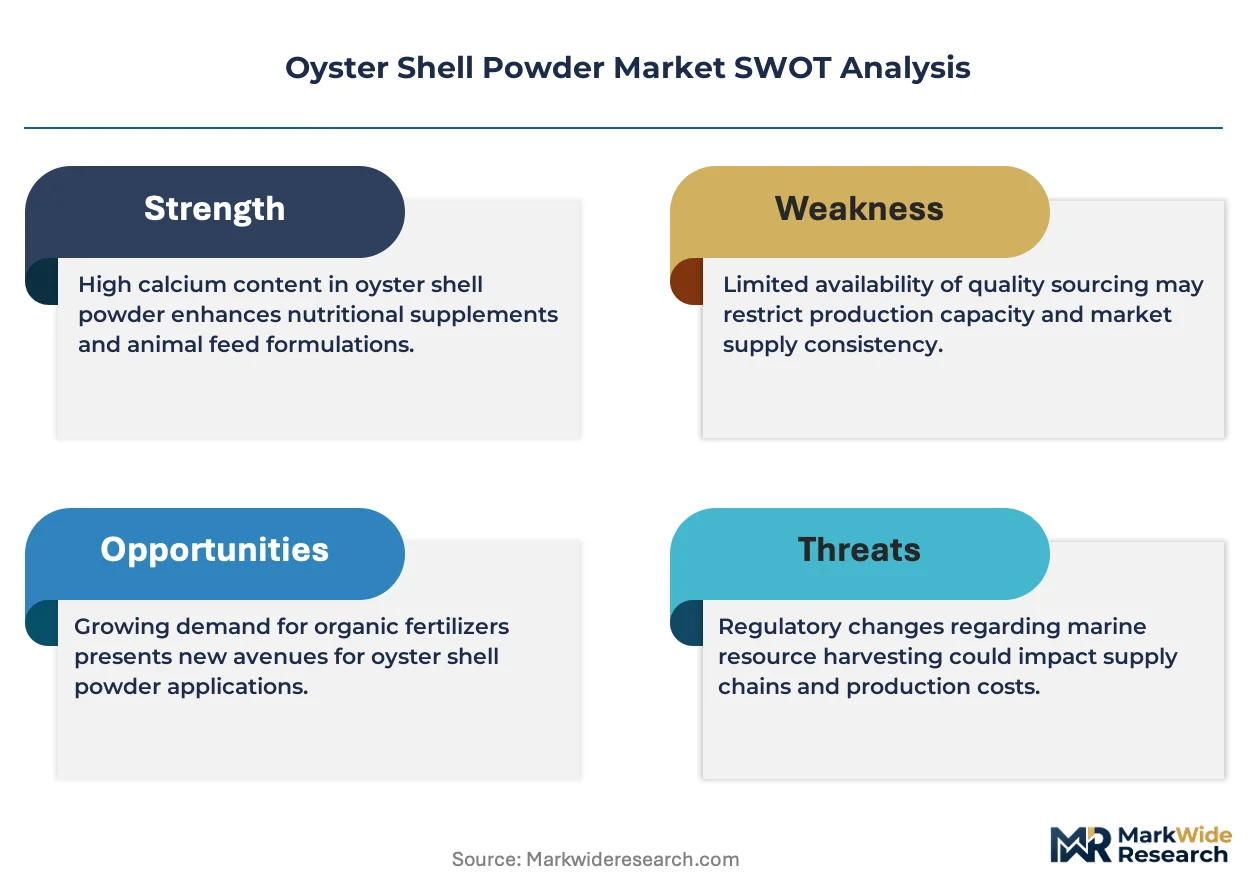
Calcination technology upgrades and tightening pharmaceutical-grade purity mandates are compressing margins for mechanical-grinding-only processors while rewarding integrated producers with thermal activation capabilities.
Growth Catalysts
- EMA Quality Guidelines:Pharmaceutical-grade mineral excipient certification is forcing tablet formulators toward certified Good Manufacturing Practice facilities, consolidating procurement to qualified suppliers.
- Aquaculture cluster proximity:Coastal shell stockpiling near calcination plants in China's Fujian and Guangdong provinces reduces raw material logistics costs for animal nutrition buyers.
- Soil amendment programs:EPA Office of Water agricultural runoff mitigation standards are expanding calcium carbonate demand among commercial farming operations seeking pH correction compliance.
Market Restraints
- Shell supply concentration:Raw material availability clusters in coastal aquaculture zones, exposing processors to weather-related harvest disruptions and seasonal volume swings.
- Calcination energy costs:Thermal activation requires sustained high-temperature processing, making natural gas price volatility a direct margin pressure for pharmaceutical-grade powder producers.
- Limestone substitution:Ground calcium carbonate from quarried limestone competes aggressively in agricultural liming where trace mineral content carries no premium.
Strategic Opportunities
- Carbon capture integration:Calcination facilities pairing oyster shell processing with carbon dioxide mineralization are accessing EU Green Deal innovation subsidies and green procurement preferences.
- Functional food expansion:High-bioavailability calcium fortification in plant-based dairy alternatives represents an underpenetrated channel for sub-10 micron grades.
- Veterinary prescription diets:SAMR feed additive registration pathways are opening for therapeutic calcium supplements targeting companion animal renal health formulations.
Industry Challenges
- Heavy-metal testing protocols:Evolving EPA and ECHA thresholds for lead, cadmium, and arsenic require continuous laboratory infrastructure investment and batch-level documentation systems.
- Particle size standardization:Absorption-rate specifications vary across pharmaceutical, feed, and food applications, complicating multi-segment production scheduling and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oyster Shell Powder Market |
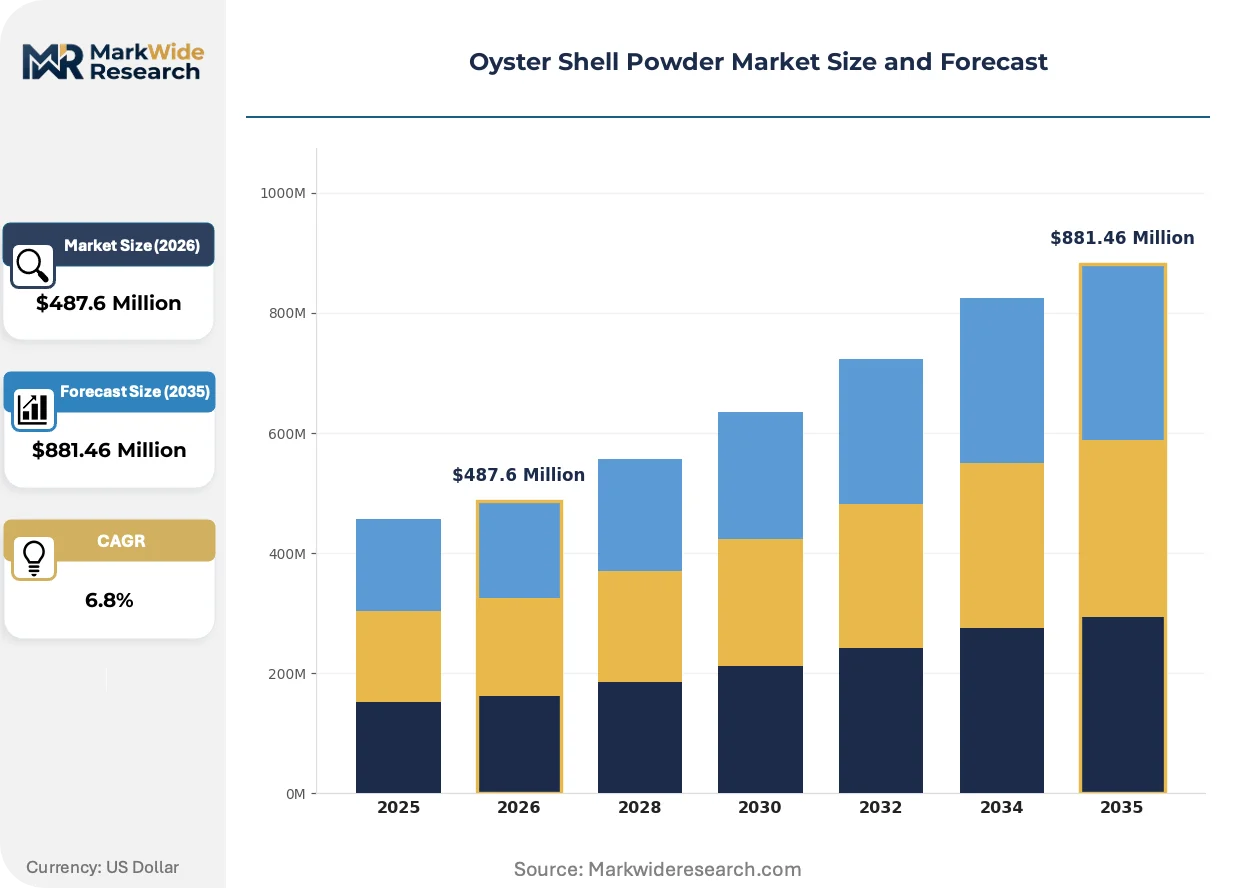
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcined Powder, Raw Powder, Granulated Powder, Calcium Supplement Application: Agriculture, Pharmaceuticals, Animal Nutrition, Cosmetics End User: Farmers, Healthcare Providers, Cosmetic Manufacturers, Feed Producers Distribution Channel: Online Retail, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Beihai Hahs Land Biotech, Omya AG, Huber Engineered Materials, The Wright Group, Weifang Noga Biochem, Penglai Marine Bio-Tech, Imerys S.A., Sudeep Pharma, Caltron Clays & Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oyster Shell Powder Market Strategic Shifts
Process automation and regulatory disclosure requirements are digitizing quality assurance workflows while reshaping how buyers verify supply chain provenance beyond traditional certificate-of-analysis documentation.
Near-infrared spectroscopy coupled with machine learning classification is digitizing real-time calcium carbonate purity verification during grinding operations. Pharmaceutical formulators in Germany and Switzerland are adopting these inline monitoring systems to reduce laboratory testing bottlenecks. The technology is digitizing batch-release decision timelines from days to hours, compressing working capital requirements for just-in-time tablet manufacturing.
REACH Annex XVII amendments on nanomaterial registration are creating compliance thresholds for sub-100 nanometer calcium carbonate powders used in advanced drug delivery systems. European formulators must now submit full toxicological dossiers for these grades, elevating documentation costs. The regulation is diverting R&D investment toward controlled particle engineering that stays above the nanomaterial threshold while maintaining bioavailability performance.
Buyers are consolidating supplier relationships around vertically integrated processors offering carbon footprint disclosure and shell-provenance traceability. Large animal nutrition compounders in Denmark and the Netherlands are replacing spot-market purchasing with multi-year offtake agreements tied to verified emission reductions. This preference shift is marginalizing traders and mechanical-grinding-only job shops lacking calcination capacity or sustainability certification.
Oyster Shell Powder Market Segmentation
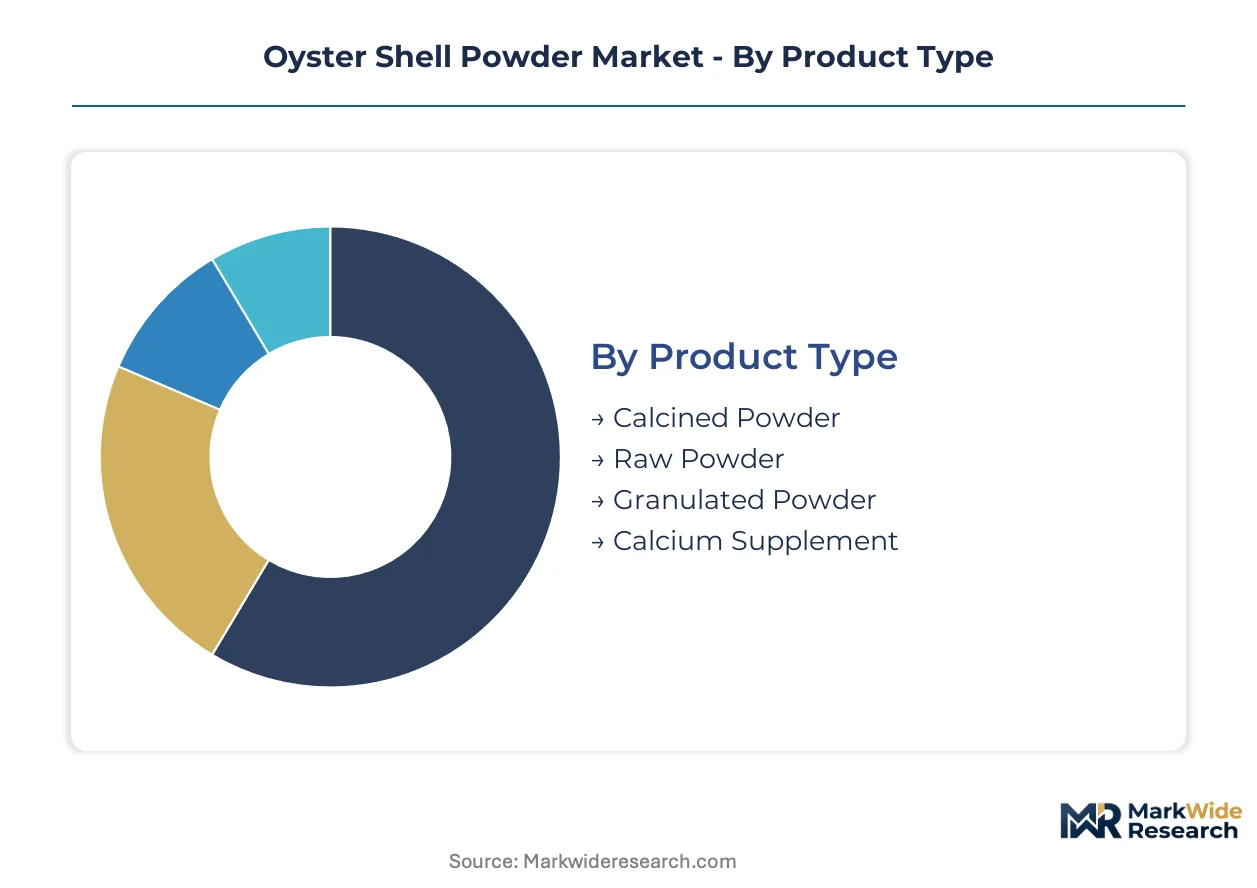
Segmentation in the oyster shell powder market reveals how calcination capabilities and purity grades partition commercial opportunity. Equipment service intensity, regulatory compliance tiers, and absorption-rate specifications create distinct profit pools that favor integrated processors over mechanical-grinding-only operators.
Product Type:
Aftermarket technical service revenue concentrates around calcination equipment, where thermal activation capabilities determine which processors can serve pharmaceutical and premium feed buyers.
- Calcined Powder:Thermally activated at 800-900°C to convert calcium carbonate to calcium oxide with enhanced bioavailability. Demand clusters among pharmaceutical tablet formulators in Germany and Switzerland where EMA mineral excipient guidelines mandate certified Good Manufacturing Practice production.
- Raw Powder:Mechanically ground without thermal treatment, typically 90-95% CaCO3 with particle sizes of 50-200 microns. Agricultural liming operations in the US Midwest prioritize this grade where EPA Office of Water runoff mitigation standards drive volume procurement without purity premiums.
- Granulated Powder:Agglomerated into 2-4mm pellets for controlled-release soil amendment applications. Coastal aquaculture regions in China's Fujian province supply feedstock to domestic granulation facilities.
- Calcium Supplement:Ultra-fine sub-10 micron grades for direct human consumption and functional food fortification. Plant-based dairy alternatives represent an underpenetrated channel requiring verified heavy-metal documentation.
Raw powder holds the largest share; momentum sits with calcined powder as pharmaceutical-grade purity mandates tighten.
Application:
Cost tier differentiation separates commodity agricultural liming from certified pharmaceutical excipients where batch-level documentation commands substantial price premiums.
- Agriculture:Soil pH correction and nutrient supplementation across commercial farming operations. US corn-belt states drive volume through EPA-mandated runoff mitigation programs.
- Pharmaceuticals:Tablet excipients and antacid formulations requiring sub-10 micron particle sizes with certified purity. Swissmedic and EMA quality guidelines constrain supply chains to qualified European facilities.
- Animal Nutrition:High-bioavailability calcium fortification in poultry, swine, and aquaculture feeds. China's SAMR registration requirements create compliance barriers for uncertified imports.
- Cosmetics:Exfoliant and mineral filler applications in premium skincare formulations. REACH Annex XVII nanomaterial thresholds divert R&D toward controlled particle engineering above 100 nanometers.
Agriculture absorbs the greatest tonnage; cosmetics is climbing the fastest as green beauty positioning elevates shell-derived mineral alternatives.
End User:
Customer type determines procurement sophistication, with healthcare and feed compounders demanding carbon footprint disclosure that mechanical-grinding job shops cannot provide.
- Farmers:Price-sensitive bulk purchasers prioritizing cost-per-ton over trace mineral content. Cooperative purchasing in Denmark and the Netherlands is consolidating around multi-year offtake agreements with verified emission data.
- Healthcare Providers:Hospital and clinic networks sourcing pharmaceutical-grade supplements for therapeutic calcium deficiency protocols. German hospital procurement groups specify inline near-infrared spectroscopy verification to compress batch-release timelines.
- Cosmetic Manufacturers:Premium formulators requiring sub-10 micron grades with heavy-metal testing documentation. EU Green Deal innovation subsidies attract processors pairing carbon capture with shell calcination.
- Feed Producers:Compounders integrating calcium supplements into prescription veterinary diets. SAMR pathways for companion animal renal health formulations are opening new therapeutic segments.
Feed producers represent the largest procurement volume; healthcare providers are gaining share fastest as clinical nutrition protocols expand.
Distribution Channel:
Supply concentration in coastal aquaculture zones shapes logistics economics, favoring direct sales relationships that bypass spot-market intermediaries.
- Online Retail:E-commerce platforms serving small-scale agricultural operators and specialty cosmetic formulators. Real-time inventory visibility matters for just-in-time soil amendment scheduling.
- Direct Sales:Long-term contracts between integrated processors and large animal nutrition compounders. Danish and Dutch buyers are replacing spot purchasing with multi-year agreements tied to verified emission reductions.
- Wholesale:Regional distributors aggregating mechanical-grinding-only output for agricultural liming markets. Margin pressure from natural gas price volatility is squeezing traders lacking calcination capacity.
- Specialty Stores:Garden center and farm supply retailers serving hobbyist and small commercial growers. Seasonal volume swings from weather-related harvest disruptions complicate inventory planning.
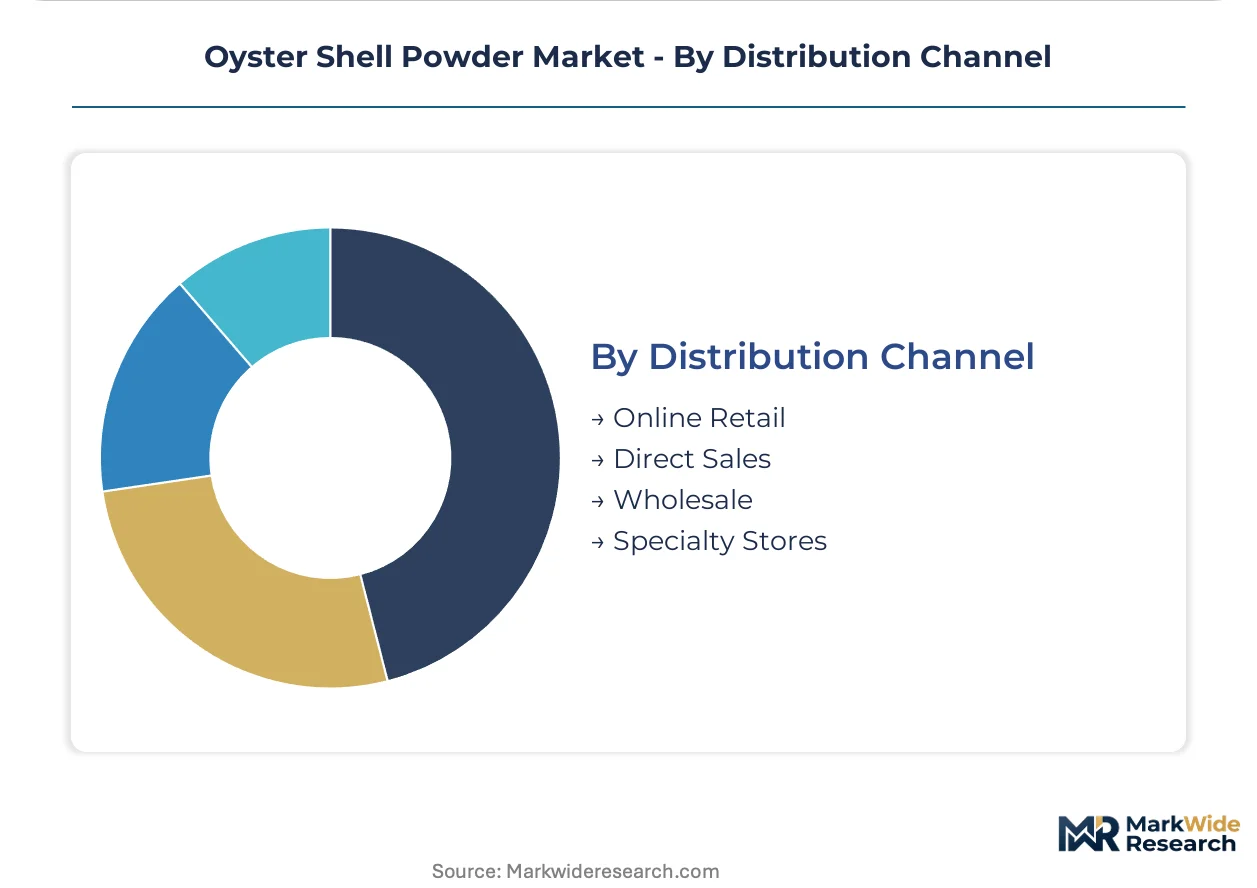
Direct sales command the greatest value; online retail is expanding most quickly as procurement digitization reaches smaller agricultural operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese agricultural buyers exhibit the highest price elasticity, accepting lower-purity raw powder for soil amendment, while Swiss and German pharmaceutical formulators absorb substantial premiums for certified excipient grades with full batch documentation.
China
Fujian and Guangdong coastal aquaculture clusters supply shell stockpiles to domestic calcination facilities serving animal nutrition compounders. SAMR and NMPA jointly administer feed additive registration, creating compliance barriers for uncertified imports. Qingdao processors are expanding granulated powder capacity for controlled-release agricultural applications.
United States
Corn-belt commercial farming operations drive agricultural liming volume through EPA Office of Water runoff mitigation programs. The agency's agricultural discharge standards mandate pH correction compliance across Iowa, Illinois, and Indiana watersheds. Huber Engineered Materials anchors North American production through controlled calcination capacity in Georgia.
Germany
Pharmaceutical tablet formulators in Baden-Württemberg and Bavaria source calcined powder under EMA mineral excipient guidelines mandating certified Good Manufacturing Practice facilities. Inline near-infrared spectroscopy verification compresses batch-release timelines from days to hours. Stuttgart-area procurement groups specify carbon footprint disclosure in multi-year supply agreements.
Switzerland
Swissmedic quality protocols constrain pharmaceutical-grade supply chains to qualified European facilities with full heavy-metal testing documentation. Basel and Zurich formulators prioritize sub-10 micron grades for antacid and therapeutic calcium deficiency protocols. The country's hospital procurement networks specify verified supply chain provenance beyond traditional certificate-of-analysis documentation.
India
Gujarat and Maharashtra feed producers integrate calcium supplements into poultry and aquaculture formulations under FSSAI and BIS quality benchmarks. Domestic mechanical-grinding operations serve price-sensitive agricultural markets where limestone substitution pressure is most acute. Mumbai-based compounders are exploring SAMR-aligned registration pathways for export-oriented production.
Oyster Shell Powder Market Competitive Environment
Capability concentration sits with integrated calcination specialists; scale advantage sits with diversified carbonates conglomerates. The market structures around three tiers: global mineral processors with multi-product calcium portfolios, regional aquaculture-integrated calciners, and mechanical-grinding job shops exposed to limestone substitution. Strategic moves center on carbon capture integration for EU Green Deal subsidy access and backward integration into coastal shell stockpiling.
Among diversified carbonates conglomerates, Omya AG and Imerys S.A. exemplify the integrated archetype leveraging global infrastructure for long-term pharmaceutical supply agreements. Huber Engineered Materials occupies a position anchoring North American production through controlled thermal activation capacity. Chinese specialists including Beihai Hahs Land Biotech and Penglai Marine Bio-Tech represent the aquaculture-proximate tier with coastal shell access.
| Leading Market Players |
|---|
| Beihai Hahs Land Biotech |
| Omya AG |
| Huber Engineered Materials |
| The Wright Group |
| Weifang Noga Biochem |
| Penglai Marine Bio-Tech |
| Imerys S.A. |
| Sudeep Pharma |
| Caltron Clays & Chemicals |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European calcination facilities serving EMA-certified pharmaceutical buyers is tightening supply discipline and amplifying pricing power for integrated producers with thermal activation capabilities. This utilization squeeze is forcing tablet formulators toward multi-year offtake commitments while compressing margins for mechanical-grinding-only operators locked in spot-market agricultural sales.
Pricing Analysis
Aftermarket technical service revenue from calcination equipment maintenance and upgrade contracts drives lifetime value for equipment suppliers serving oyster shell processors. Three-tier pricing structure across pharmaceutical-grade, feed-grade, and agricultural-grade levels separates certified Good Manufacturing Practice excipients from commodity liming products. Price differentiation hinges on thermal activation certification and batch-level heavy-metal documentation. Cost compression in raw powder tiers is intensifying because limestone substitution pressure erodes trace mineral premiums. Farmers in the US Midwest exhibit highest price sensitivity, while Swiss hospital procurement networks absorb substantial premiums for verified supply chain provenance.
Supply Chain Analysis
Export-control restrictions on advanced calcination kiln technology are limiting equipment flows to uncertified processors in emerging markets. Raw material supply concentrates in China's Fujian and Guangdong coastal aquaculture clusters, with secondary sourcing from US Gulf Coast and Indian Gujarat shell stockpiles. Production draws from oyster shell harvests, natural gas feedstock for thermal activation, and precision grinding media. Single-source vulnerability in coastal aquaculture zones exposes processors to weather-related harvest disruptions. Distribution runs through direct sales relationships between integrated calciners and large animal nutrition compounders, marginalizing spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as carbon footprint disclosure systems and batch-level traceability protocols create interoperability standards that favor integrated data-capture over fragmented mechanical-grinding operations.
For Market Incumbents: Entrench calcination capacity advantages by securing multi-year shell supply agreements with China's coastal aquaculture cooperatives before regional competitors replicate thermal activation infrastructure. Invest in inline near-infrared spectroscopy systems to compress batch-release timelines for German and Swiss pharmaceutical buyers. Limestone substitution pressure in agricultural tiers demands defensive certification investments that preserve trace mineral premiums. For New Entrants and Emerging Players: Pursue carbon capture integration partnerships with EU Green Deal subsidy programs to offset calcination energy costs and access green procurement preferences. Plant-based dairy alternatives represent the most penetrable white-space channel for sub-10 micron calcium supplement grades. Lead with verified heavy-metal documentation and carbon footprint disclosure to differentiate from established mechanical-grinding job shops. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among calcination equipment suppliers with aftermarket technical service contracts and long-term pharmaceutical supply agreements. Five-to-ten year viability favors integrated processors with captive shell stockpiling and thermal activation capabilities over pure-play grinding operations. Watch for SAMR feed additive registration pathway expansions into companion animal therapeutic segments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coastal Shell Stockpiling | Secures raw material access for Fujian and Guangdong calcination facilities serving SAMR-registered feed compounders. |
| Carbon Capture Technology Integration | Unlocks EU Green Deal innovation subsidies for calcination facilities mineralizing CO2 during thermal activation. |
| Long-term Supply Agreement with Pharmaceutical Formulators | Locks in EMA-certified demand from German and Swiss tablet manufacturers requiring GMP facility sourcing. |
| Near-Infrared Spectroscopy System Deployment | Compresses batch-release timelines from days to hours for just-in-time manufacturing at Stuttgart-area procurement groups. |
| SAMR Feed Additive Registration Pathway Expansion | Opens therapeutic calcium supplement segments for companion animal renal health formulations in China's veterinary market. |
Study Parameters
Cross-validation between primary interviews with calcination plant managers, pharmaceutical procurement leads, and animal nutrition compounders and secondary validation through customs trade data, EPA agricultural runoff program filings, and EMA quality guideline documents anchors the qualitative findings. Bottom-up triangulation aggregates facility-level capacity and utilization estimates while top-down verification cross-checks against carbonates industry association reports and SEC filings from diversified mineral processors.
Calibration against historical price spreads between raw and calcined powder grades, energy cost fluctuations, and regulatory certification timelines shapes the analytical framework across the analysis window. Segmentation dimensions include product type tier, application purity requirements, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from regression analysis of volume trajectories against agricultural pH correction mandates, pharmaceutical excipient demand curves, and feed additive registration expansion patterns.
Sensitivities concentrate around natural gas price volatility affecting calcination economics, evolving EPA and ECHA heavy-metal testing thresholds, and SAMR registration pathway timing for therapeutic feed segments. Forecasts reflect assumptions on coastal aquaculture harvest stability and carbon capture subsidy continuity. Material shifts in EU Green Deal funding allocation or Chinese environmental enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
RTD/High Strength Premixes Market
Ingredients
Proteose Peptone Market
Ingredients
Global Dry Yeast Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Bouillon Market
Ingredients
Buckwheat Groat Flour Market
Ingredients
Europe Corn Glucose Market
Ingredients
North America Collagen Ingredients Market
Ingredients
North America Dairy Ingredients Market
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Ahiflower Oil Market
Ingredients
Soy Lecithin Market
Ingredients
Canola Meal Market
Ingredients
Encapsulated Salt Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
India Olive Oil Market