
 Middle East and Africa Fermented Drinks Market | 2026-2036
Middle East and Africa Fermented Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fermented Drinks Market Foresight
Multi-pack bundling of kefir and kombucha is hardening as the dominant retail configuration across Middle Eastern supermarket chains. Danone S.A. leverages its dairy fermentation expertise to anchor premium kefir lines in Saudi Arabia and Egypt. PepsiCo Inc. competes through extended distribution networks that push kombucha into convenience channels previously reserved for carbonated soft drinks. Heineken N.V. navigates the non-alcoholic fermented segment with specialized brewing capabilities adapted for halal market requirements.
Fermented drinks in the Middle East and Africa encompass beverages produced through controlled microbial fermentation of substrates including dairy, fruit, grains, and herbs, yielding products with live or inactive cultures, organic acids, and altered nutritional profiles. These drinks serve commercial purposes spanning digestive health positioning, alcohol-free social consumption, and functional hydration in climates with high ambient temperatures. Kefir commands the largest ingredient-driven margin pool due to established dairy infrastructure and consumer familiarity with cultured milk products. Kombucha represents the fastest-growing product type as health stores and cafes in urban South Africa and Nigeria build dedicated refrigerated sections for the category.
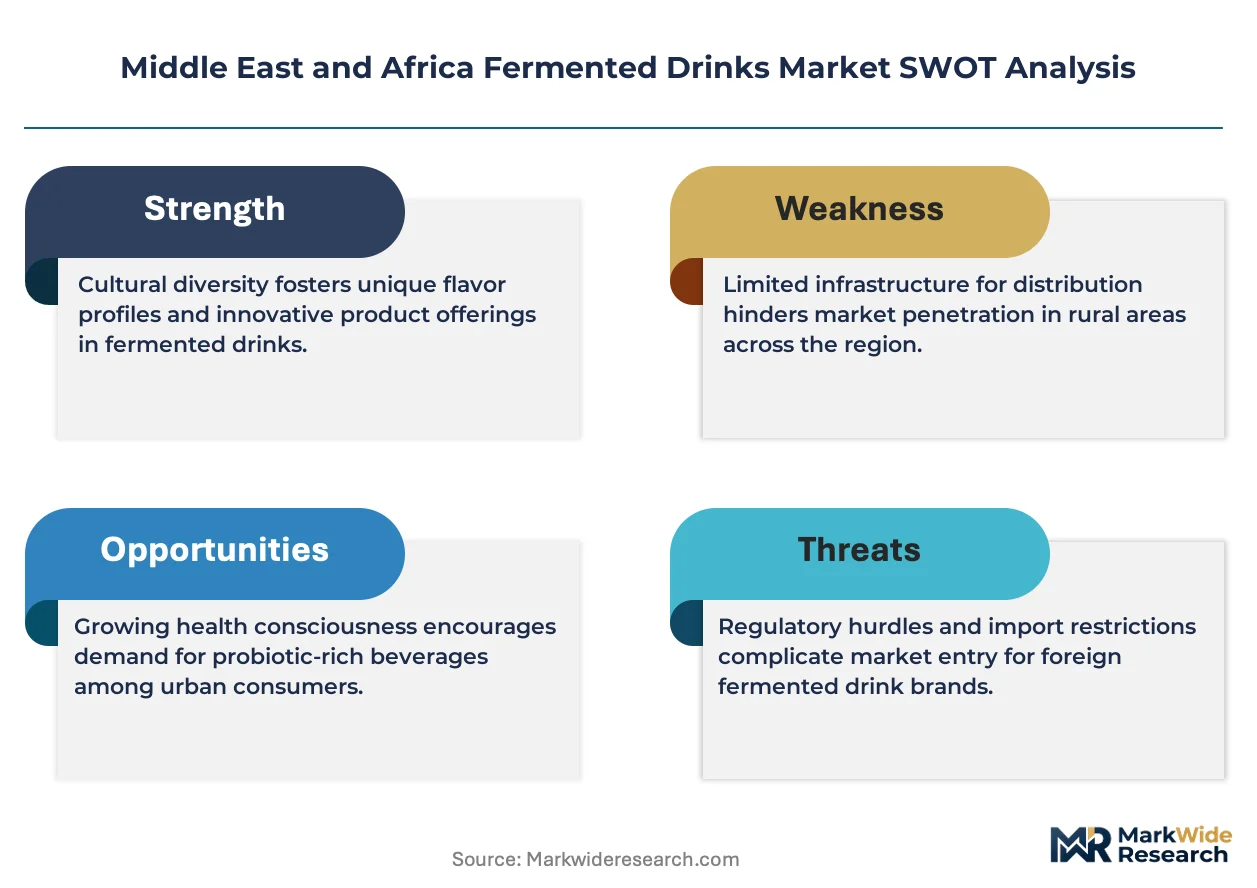
Saudi Arabia's Food and Drug Authority and South Africa's Department of Health enforce divergent standards for live culture counts and health claims, creating compliance complexity for cross-border suppliers. The UAE's Ministry of Industry and Advanced Technology aligns with Gulf standardization protocols that mandate halal certification for all dairy-based fermented beverages sold domestically. Egypt's National Food Safety Authority inspects imported cultures and starter materials at ports of entry, extending clearance timelines for new market entrants. Stakeholders must monitor regulatory divergence between Gulf Cooperation Council harmonization efforts and national-level enforcement variations that determine viable market entry pathways.
Market Dynamics
Live culture stability requirements are forcing capital reallocation toward cold-chain infrastructure across Middle Eastern and African distribution networks. Temperature excursions during last-mile delivery destroy probiotic viability, compelling retailers to invest in refrigerated shelving and logistics partners to deploy IoT monitoring systems.
Growth Catalysts
- SFDA Halal Certification Streamlining:Saudi Arabia's Food and Drug Authority has unified dairy-based fermented beverage approval pathways, reducing halal certification timelines for cross-border suppliers entering the Kingdom.
- Urban Café Culture Expansion:Lagos and Johannesburg kombucha taprooms are cultivating direct-to-consumer channels that bypass traditional retail markups while building brand communities.
- Kefir Starter Culture Localization:Egyptian dairy cooperatives are developing regionally adapted kefir grains that tolerate higher ambient fermentation temperatures, reducing energy costs for small-scale producers.
Market Restraints
- Glass Bottle Import Dependency:Premium kombucha packaging relies heavily on imported amber glass, exposing Nigerian and Kenyan bottlers to currency fluctuation risks and extended lead times.
- Live Culture Shelf-Life Compression:Unrefrigerated storage conditions in informal retail channels degrade probiotic counts below label claims, triggering compliance violations under South Africa's Department of Health regulations.
- Concentrated Dairy Input Markets:Fluid milk procurement concentrates among three major cooperatives in the UAE and Saudi Arabia, limiting negotiating leverage for independent kefir processors.
Strategic Opportunities
- Ethiopian Orthodox Fasting Calendar Alignment:Non-dairy fermented beverages positioned for lenten consumption periods capture a chronically underserved segment within Africa's second-most populous nation.
- MOHAP Functional Claims Pathway:The UAE's Ministry of Health and Prevention is piloting accelerated review processes for digestive health positioning, rewarding early movers with temporary exclusivity windows.
- Mobile Cold-Chain Leasing Models:Pay-per-use refrigerated container networks are emerging along the Nairobi-Mombasa corridor, enabling kombucha producers to test market depth without fixed asset commitments.
Industry Challenges
- Microbiology Talent Scarcity:Commercial-scale fermentation operations across the Gulf states compete for a limited pool of food microbiologists trained in anaerobic culture management.
- Multi-Jurisdiction Label Harmonization:Divergent live culture count disclosure requirements between Egypt's National Food Safety Authority and Gulf standardization protocols force SKU fragmentation or compliance trade-offs.
- Starter Material Quarantine Delays:Egyptian port inspections of imported SCOBY and kefir grains extend clearance timelines, disrupting production schedules for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fermented Drinks Market |
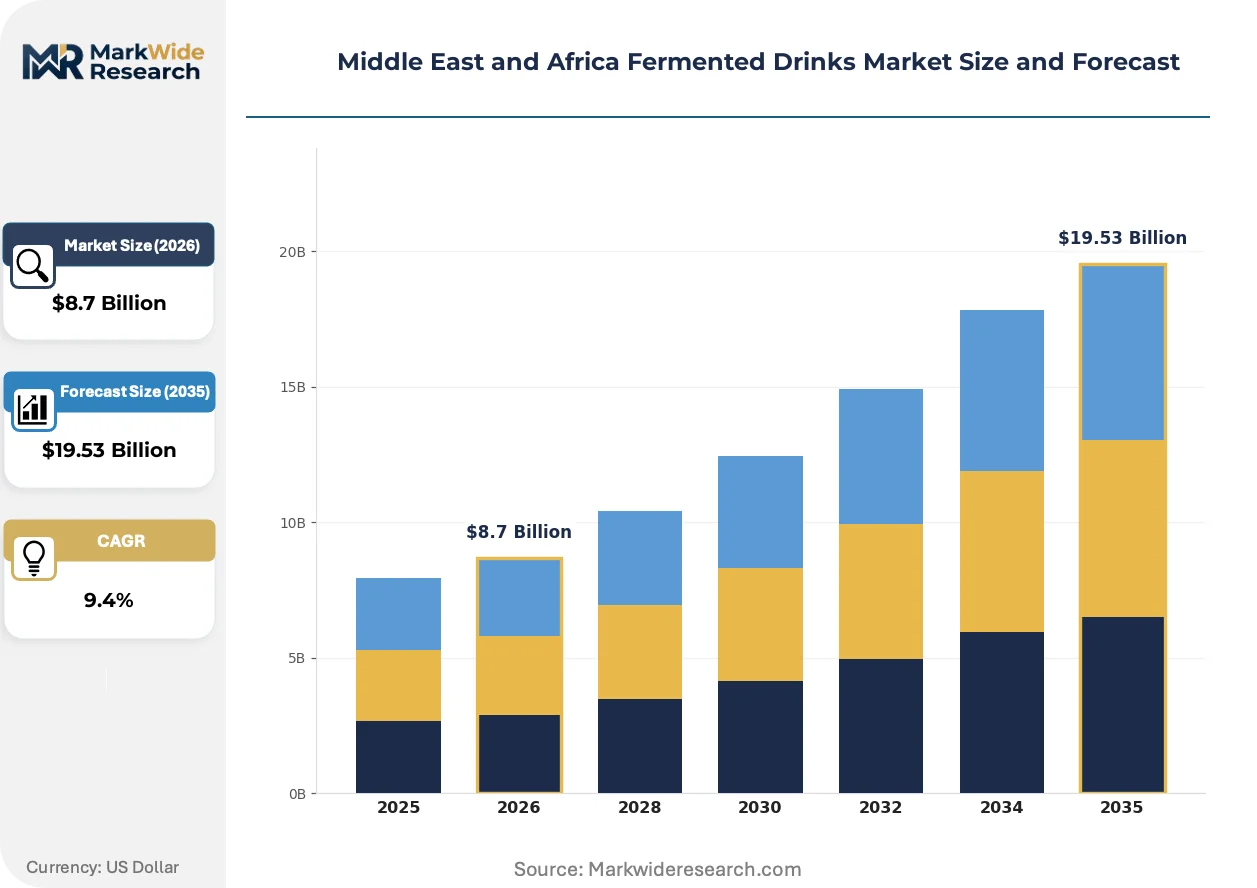
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Kombucha, Tepache, Kvass Ingredients: Fruit, Grains, Herbs, Dairy End User: Retail Consumers, Cafes, Restaurants, Health Stores Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Yakult Honsha Co., Ltd., PepsiCo Inc., Danone S.A., Anheuser-Busch InBev, Al Rabie Saudi Foods Co., Nestlé S.A., The Coca-Cola Company, Heineken N.V., GT's Kombucha, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fermented Drinks Market Shifts & Advancements
Precision fermentation monitoring systems are migrating from pharmaceutical applications into beverage production, enabling real-time metabolite tracking that was previously cost-prohibitive for mid-scale operations.
Consolidated shelf-life extension technology is consolidating competitive advantage for regional kefir processors. Vacuum-assisted fermentation chambers manufactured by Israeli equipment suppliers now enable Egyptian and Jordanian dairies to achieve 21-day refrigerated stability without chemical preservatives. Mid-market retailers in Dubai and Riyadh are adopting these systems to reduce shrinkage from expired live-culture inventory. The technology is consolidating margin pools toward operators with capital deployment capacity, compressing opportunities for artisanal producers lacking equipment financing access.
SFDA's 2024 implementation of digital traceability mandates for probiotic beverages is reshaping supply chain documentation requirements. All dairy-based fermented products sold in Saudi Arabia must now carry blockchain-verified cold-chain records from production through retail. Kefir importers are restructuring supplier agreements to allocate compliance cost responsibilities, while domestic Saudi producers are capturing relative advantage through shorter chain complexity. The regulation most acutely affects Egyptian exporters who lack integrated logistics partnerships capable of generating compliant data streams.
Subscription-based replenishment models are displacing conventional supermarket purchasing among affluent consumers in Cape Town and Johannesburg. Kombucha brands offering weekly home delivery with customizable flavor rotations are achieving retention rates that informal retail channels cannot match. Health-conscious professionals aged 25-40 constitute the core subscriber base, prioritizing convenience over unit price comparison. This behavioral shift concentrates demand capture among brands with direct-to-consumer infrastructure, marginalizing traditional wholesalers in South Africa's urban core.
Middle East and Africa Fermented Drinks Market Segmentation
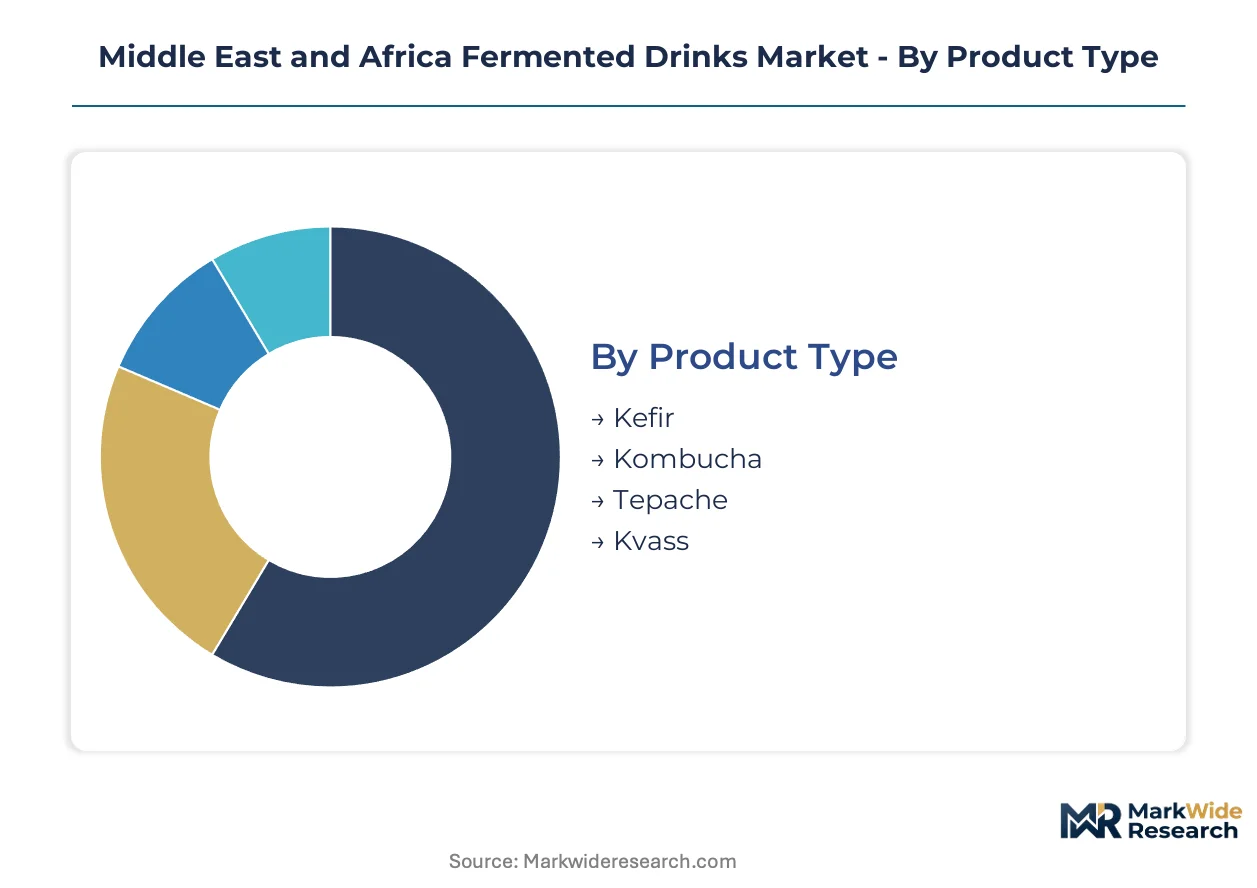
Segmentation in the Middle East and Africa fermented drinks market reveals how consumer priorities diverge across climate conditions, religious dietary requirements, and urban infrastructure gaps. Buyers navigate trade-offs between probiotic potency verification, halal certification assurance, and cold-chain reliability that reshape competitive positioning.
Product Type:
Consumer familiarity with fermentation traditions determines trial willingness and price elasticity across markets.
- Kefir:Cultured milk beverage with tart flavor profile and high probiotic density. Saudi Arabia and Egypt dominate demand as established dairy consumption cultures reduce education costs for processors. The category benefits from existing cold-chain infrastructure in Gulf supermarket networks.
- Kombucha:Tea-based fermented drink with effervescent texture and SCOBY-derived organic acids. Lagos and Johannesburg health stores are expanding refrigerated shelf space fastest as young professionals seek alcohol-free social alternatives. Temperature sensitivity during distribution limits penetration in informal retail channels.
- Tepache:Pineapple-rind fermented beverage with lower alcohol content than traditional preparations. Mexican-origin positioning appeals to expatriate communities in Dubai and emerging craft segments in Cape Town.
- Kvass:Rye bread fermented drink with Eastern European heritage. Russian and Ukrainian diaspora populations in Israel and Kazakhstan sustain niche demand.
Kefir leads on scale; kombucha leads on momentum.
Ingredients:
Input sourcing geography dictates margin stability and regulatory compliance burden for processors.
- Dairy:Fluid milk and milk powder substrates leverage established procurement relationships with UAE and Saudi cooperatives. SFDA halal certification requirements add documentation overhead but unlock premium pricing in Gulf markets.
- Fruit:Pineapple, apple, and citrus bases enable non-dairy positioning for lactose-intolerant and vegan segments. Nigerian and Kenyan bottlers face amber glass import dependency that compresses margins.
- Grains:Rye, barley, and sorghum substrates support traditional fermentation methods with longer ambient-temperature stability. Ethiopian fasting calendar alignment creates seasonal demand concentration.
- Herbs:Rooibos, hibiscus, and mint infusions differentiate premium lines in South African health stores. Botanical sourcing from local cooperatives reduces foreign exchange exposure.
Dairy commands the deepest volume base; fruit inputs are climbing the fastest.
End User:
Purchase context shapes format preferences, packaging requirements, and brand communication strategies.
- Retail Consumers:Supermarket and online purchasers seeking home consumption formats. Subscription models in Cape Town and Johannesburg are displacing conventional purchasing with customizable flavor rotations.
- Health Stores:Dedicated wellness retailers with trained staff and refrigerated display capacity. South African expansion of probiotic beverage shelf space concentrates demand capture among brands with live-culture stability documentation.
- Cafes:On-premise consumption venues including kombucha taprooms in Lagos and Johannesburg. Direct-to-consumer channels bypass traditional retail markups while building brand communities.
- Restaurants:Foodservice accounts requiring bulk formats and consistent supply reliability. Halal certification mandates from Gulf standardization protocols determine supplier eligibility.
Retail consumers provide the broadest revenue base; health stores deliver the steepest expansion trajectory.
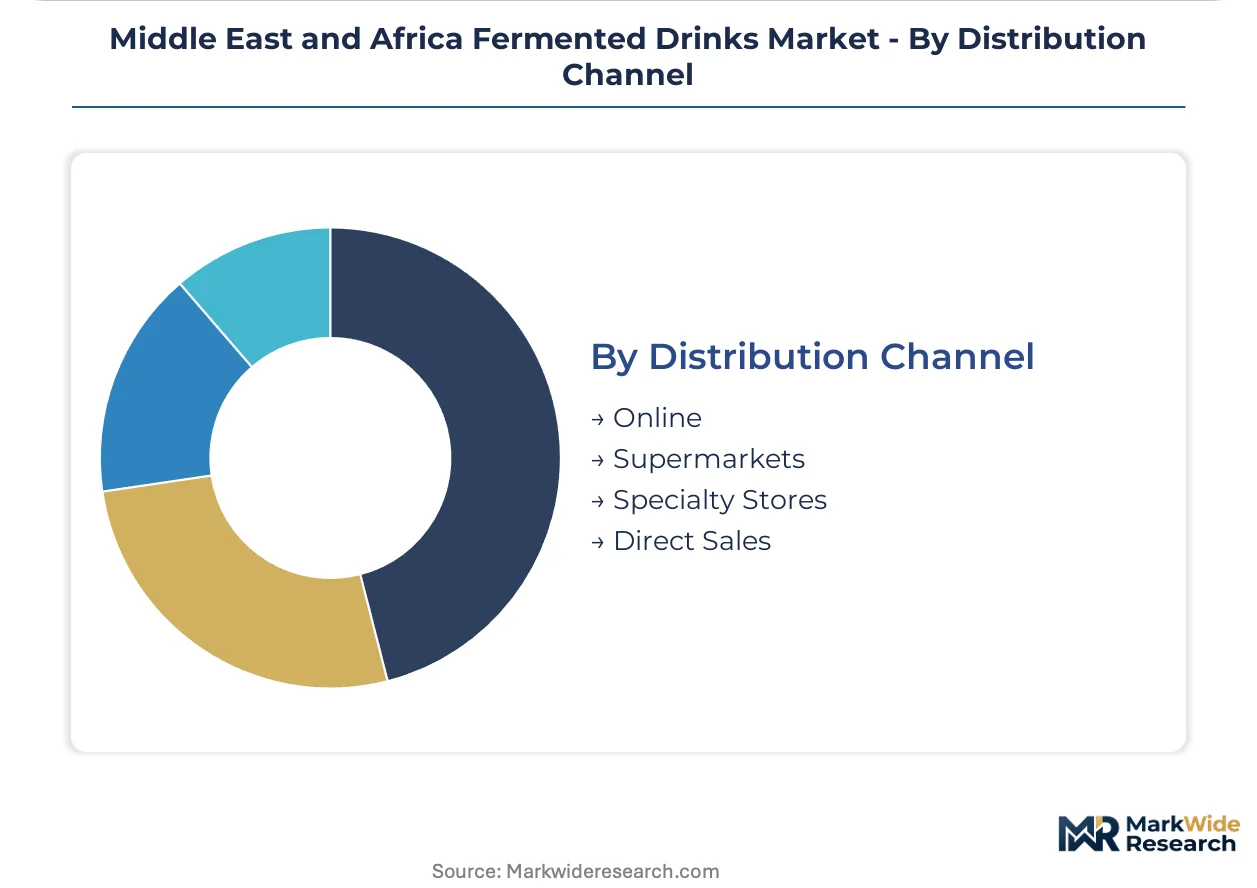
Distribution Channel:
Channel selection determines cold-chain investment requirements and customer data access.
- Supermarkets:Multi-pack bundling dominates as the standard retail configuration across Middle Eastern chains. Refrigerated shelving investments reduce shrinkage from expired live-culture inventory.
- Online:E-commerce platforms enable subscription replenishment and direct temperature-controlled delivery. Last-mile logistics partnerships with IoT monitoring systems protect probiotic viability.
- Specialty Stores:Curated wellness retailers with educated staff and premium positioning. Egyptian port inspection delays for imported starter materials disrupt supply consistency.
- Direct Sales:Producer-owned taprooms and farmers market presence. Mobile cold-chain leasing models along the Nairobi-Mombasa corridor enable market testing without fixed asset commitments.
Supermarkets anchor volume throughput; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermented dairy traditions in the Levant and North Africa established the foundation for commercial kefir production, while South African health stores pioneered kombucha retail infrastructure that now extends into Nigeria's urban centers.
Saudi Arabia
Domestic dairy cooperatives supply fluid milk to kefir processors at contracted volumes that limit independent entrants. SFDA unified halal certification pathways in 2024, compressing approval timelines for cross-border suppliers. Riyadh's supermarket chains deploy multi-pack bundling as the standard retail configuration for probiotic beverages.
United Arab Emirates
MOHAP pilots accelerated review processes for digestive health claims, rewarding early movers with temporary exclusivity windows. Dubai's health stores and kombucha taprooms cultivate direct-to-consumer channels that bypass traditional retail markups. MOIAT mandates halal certification for all dairy-based fermented beverages sold domestically.
South Africa
Subscription-based replenishment models displace conventional supermarket purchasing among affluent consumers in Cape Town and Johannesburg. The Department of Health enforces live culture count disclosure requirements that trigger compliance violations when informal retail channels degrade probiotic viability. Health stores expand refrigerated shelf space for kombucha as young professionals seek alcohol-free social alternatives.
Egypt
Dairy cooperatives develop regionally adapted kefir grains that tolerate higher ambient fermentation temperatures, reducing energy costs for small-scale producers. NFSA inspects imported cultures and starter materials at ports of entry, extending clearance timelines for new market entrants. Cairo's retail consumers provide the broadest revenue base for kefir distribution through established cold-chain networks.
Nigeria
Kombucha adoption accelerates among young professionals in Lagos, where urban café culture expansion supports dedicated taproom channels. Amber glass import dependency exposes bottlers to currency fluctuation risks and extended lead times. Lagos supermarkets test multi-pack bundling configurations as refrigerated shelving investments gradually reduce shrinkage from expired inventory.
Middle East and Africa Fermented Drinks Market Competitive Landscape
Premium-margin players sit above commodity-margin players across halal certification and cold-chain reliability dimensions, with domestic Saudi and Egyptian dairy specialists capturing relative advantage through shorter supply chain complexity. The competitive structure fragments across multinational beverage conglomerates, regional dairy cooperatives, and specialized kombucha craft producers. Three archetypes dominate: dairy fermentation heritage players leveraging existing cold infrastructure, beverage distribution network deployers seeking alcohol-free portfolio expansion, and direct-to-consumer subscription operators building brand communities. Dominant competitive moves include strategic partnerships with logistics providers for IoT-enabled cold-chain monitoring and portfolio diversification into non-dairy fermented alternatives.
Within the dairy fermentation heritage tier, Danone S.A. and Yakult Honsha Co., Ltd. exemplify multinational operators anchoring premium kefir lines through established Gulf distribution relationships. PepsiCo Inc. occupies a position among beverage network deployers extending kombucha into convenience channels previously reserved for carbonated soft drinks. Heineken N.V. represents the specialized brewing adaptation archetype, navigating non-alcoholic fermented segments with capabilities adjusted for halal market requirements. These three anchors illustrate how competitive positioning stratifies across certification access, temperature-controlled logistics partnerships, and direct-to-consumer infrastructure investment.
| Leading Market Players |
|---|
| Yakult Honsha Co., Ltd. |
| PepsiCo Inc. |
| Danone S.A. |
| Anheuser-Busch InBev |
| Al Rabie Saudi Foods Co. |
| Nestlé S.A. |
| The Coca-Cola Company |
| Heineken N.V. |
| GT's Kombucha |
| Others |
Supply & Pricing Matrix
Commercial food microbiologists concentrated in Cairo and Dubai command wage premiums that compress margin spreads between premium kefir and economy kombucha tiers. Labor-cost differentials between Gulf cold-chain specialists and Egyptian ambient-fermentation cooperatives create pricing-tier spreads that reward regional sourcing arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SFDA-certified halal kefir from conventional dairy ferments and informal kombucha. Price differentiation hinges on halal certification grade and cold-chain reliability documentation. Pricing pressure stems from amber glass import dependency compressing Nigerian bottler margins. Informal retail channels exhibit highest price sensitivity; subscription direct-to-consumer models show lowest.
Supply Chain Analysis
Regional distribution centers in Jeddah, Dubai, and Johannesburg anchor hub-and-spoke patterns for temperature-controlled kefir distribution. Manufacturing concentrates in Saudi Arabia, Egypt, and South Africa. Raw material dependencies include fluid milk from Gulf cooperatives, imported SCOBY cultures, and amber glass packaging. Single-source vulnerability around Egyptian port inspections for starter materials disrupts production schedules. Distribution runs through supermarket multi-pack bundling and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where SFDA's 2024 digital traceability mandate for probiotic beverages reshapes compliance investment returns and competitive moats.
For Market Incumbents: Deepen cold-chain infrastructure partnerships with IoT monitoring providers to defend against mobile cold-chain leasing entrants eroding fixed-asset advantages. Anchor premium positioning through accelerated MOHAP digestive health claims submissions before exclusivity windows close. Vertical integration into Egyptian kefir grain localization reduces energy cost exposure. For New Entrants and Emerging Players: Precision fermentation monitoring systems offer technology-first wedge into mid-scale Egyptian and Jordanian dairies lacking pharmaceutical-grade metabolite tracking. Target Ethiopian Orthodox fasting calendar alignment for non-dairy tepache positioning. Deploy mobile cold-chain leasing along Nairobi-Mombasa corridor before fixed-asset commitments. For Investors and Strategic Acquirers: Beverage distribution network deployers are the most active acquirer in this space, seeking alcohol-free portfolio expansion through kombucha capabilities. Five-to-ten year viability favors operators with halal certification access and direct-to-consumer infrastructure. Monitor SFDA blockchain traceability compliance rates as inflection indicator for Egyptian exporter distress.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Fast-Track | SFDA unified pathways compress approval timelines for cross-border kefir suppliers entering Saudi Arabia. |
| Cold-Chain IoT Deployment | Refrigerated container networks with real-time monitoring protect probiotic viability through last-mile delivery. |
| Starter Culture Localization | Egyptian dairy cooperatives developing heat-tolerant kefir grains reduce energy costs for small-scale producers. |
| Direct-to-Consumer Subscription | Weekly home delivery with customizable flavor rotations achieves retention rates informal retail cannot match. |
| Non-Dairy Fasting Calendar Alignment | Tepache and kombucha positioning for Ethiopian Orthodox lenten periods captures chronically underserved demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy cooperative managers, health store category buyers, cold-chain logistics operators, and fermentation microbiologists with secondary validation from SFDA regulatory filings, MOHAP pilot program disclosures, Egyptian National Food Safety Authority port inspection records, and South African Department of Health compliance bulletins. Bottom-up volume builds and top-down macro anchors were cross-checked for triangulation.
Comparable historical periods anchored the projection horizon to established growth trajectories in probiotic beverage adoption. Segmentation dimensions modeled include product type, ingredient substrate, end-user context, and distribution channel complexity. CAGRs were derived from slope analysis across the modeling period. Industry-specific forecast inputs incorporated halal certification penetration rates and cold-chain infrastructure investment flows.
The model holds under stable regulatory enforcement and intact cold-chain financing; deviation in currency volatility or port inspection delays would shift supply-side assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Europe Craft Spirits Market
Alcoholic Beverages
Turkey Tequila Market
Alcoholic Beverages
Edible Alcohol Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
India Alcohol Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Wine Enzymes Market
Alcoholic Beverages
Japan Beer Market
Alcoholic Beverages
Craft Rum Market
Alcoholic Beverages
Automated Brewing System Market
Alcoholic Beverages
Tequila Market
Alcoholic Beverages
Dark Spirits Market
Alcoholic Beverages
South America Beer Market
Alcoholic Beverages
Global Soju Market
Alcoholic Beverages
Wine Bottle Sterilizer Market
Alcoholic Beverages
Fruit Brandy Market