
 Indonesia Whey Protein Market | 2026-2036
Indonesia Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Whey Protein Market Foresight
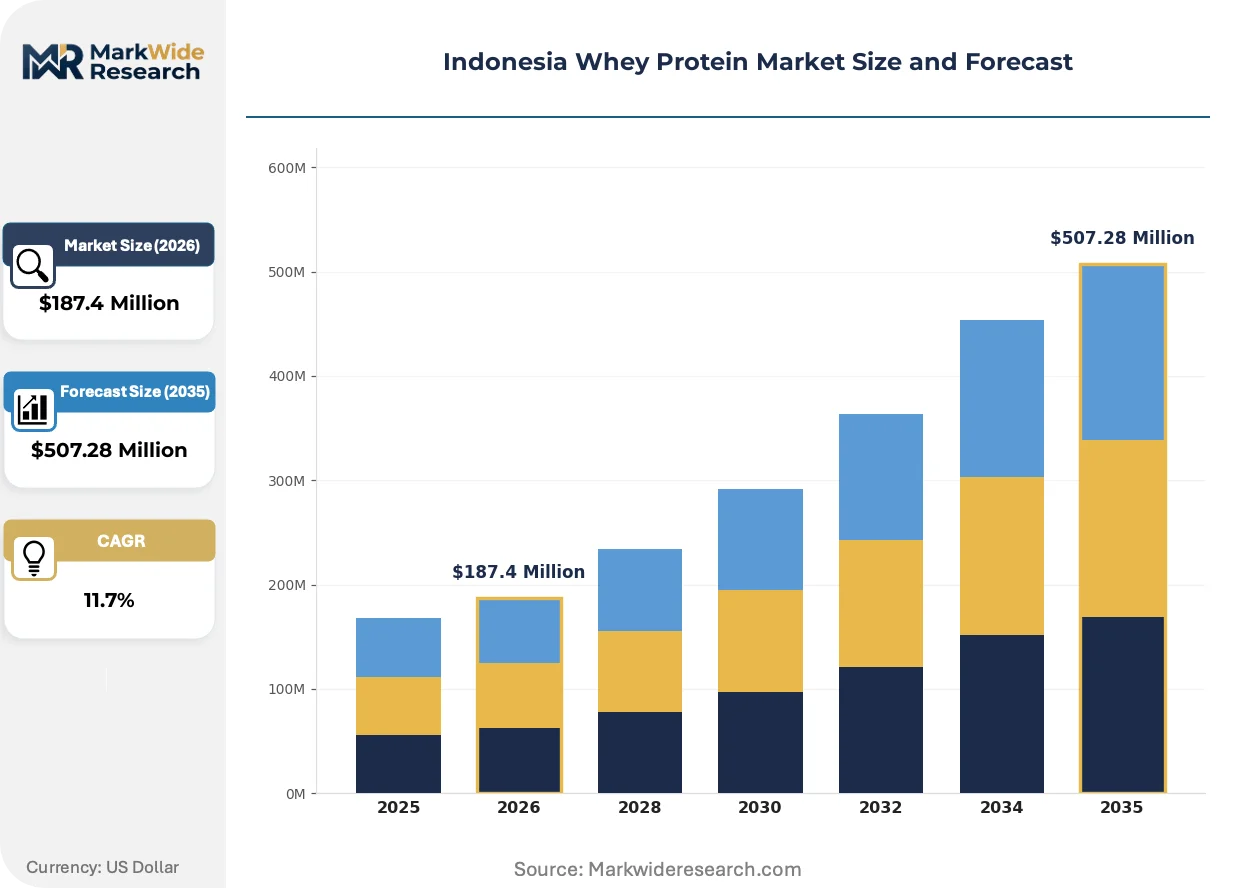
BPOM's tightened halal certification requirements is recalibrating the cost-of-entry calculus for whey protein suppliers entering Indonesia. Fonterra Co-operative Group leverages its established halal-compliant supply chains to sustain premium positioning in Jakarta's health store channel. Kalbe Nutritionals anchors its domestic manufacturing footprint to compete on landed cost against imported isolates. Glanbia plc differentiates through specialized sports nutrition formulations targeting Indonesia's expanding gym membership base.
Whey protein comprises the liquid fraction separated during cheese production, subsequently dried into powders containing protein concentrations ranging from 35% to 90% depending on processing intensity. Manufacturers employ membrane filtration or ion exchange to isolate protein fractions for nutritional applications spanning muscle recovery, weight management, and clinical nutrition support. Concentrate variants dominate volume flows through Indonesia's supermarket and online retail channels due to cost accessibility for general consumers. Isolate grades command margin concentration among athletes and bodybuilders prioritizing protein purity and reduced lactose content. Hydrolysate segments occupy niche positioning within premium sports nutrition, where enzymatic pre-digestion justifies higher price points for rapid absorption scenarios.
BPOM enforces halal labeling and safety standards for all imported dairy-derived supplements, while Indonesia's Ministry of Industry promotes domestic food processing through local content incentives that shape manufacturing location decisions. The country's national standardization agency, BSN, adopts Codex Alimentarius parameters for protein content claims, creating compliance benchmarks that filter lower-grade imports from formal channels. Stakeholders must monitor evolving halal audit protocols and regional trade agreement terms that could reshape tariff structures for Australian and New Zealand whey suppliers serving Indonesian demand.
Market Dynamics
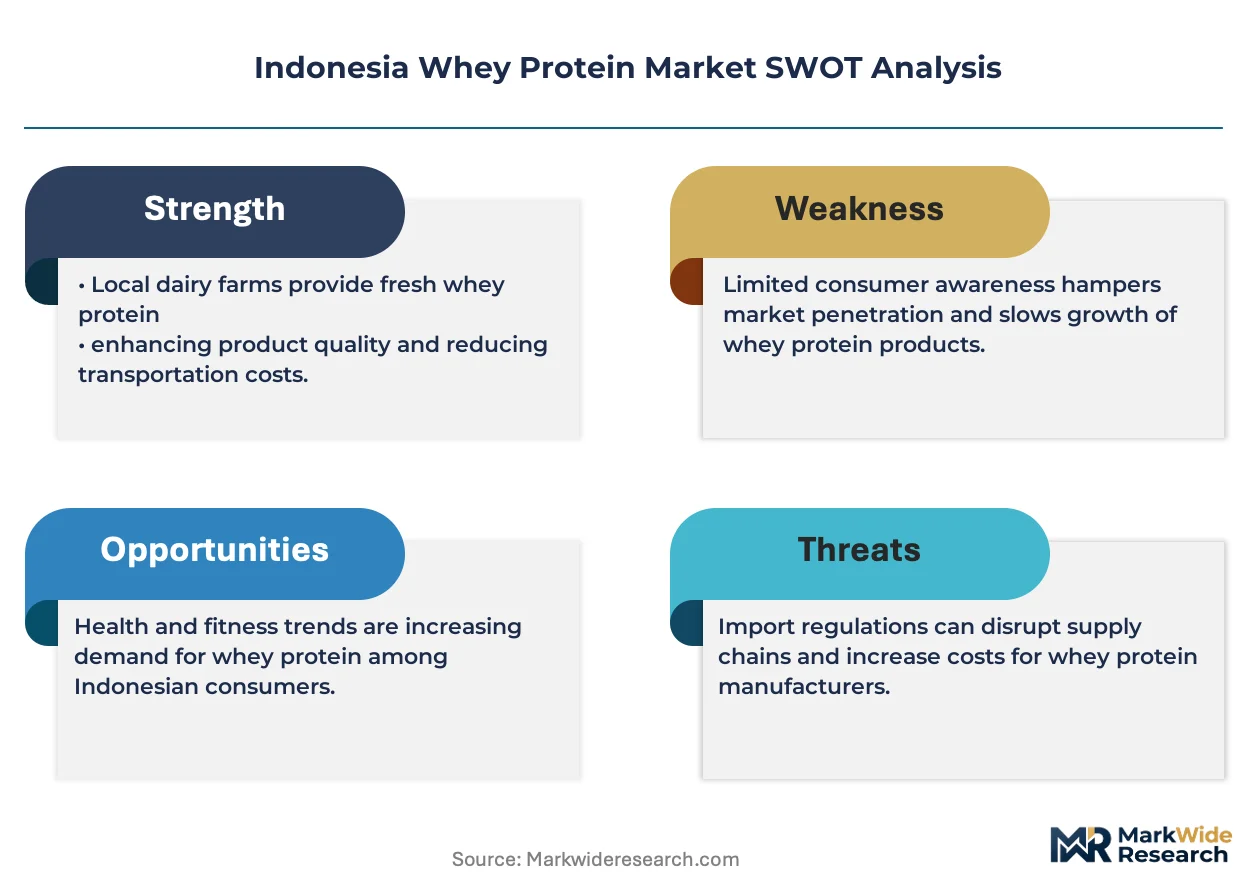
BPOM's tightened halal certification requirements are restructuring supplier economics across Indonesia's whey protein import channels, forcing compliance investments that favor established halal-compliant supply chains over new entrants.
Growth Catalysts
- Fitness infrastructure expansion:Gym density in Greater Jakarta and Surabaya creates concentrated demand pools for sports nutrition products. Urban millennials drive repeat purchase velocity through subscription models.
- BPOM halal mandates:Regulatory clarity around dairy-derived supplement labeling reduces market uncertainty for compliant suppliers. Formal channel expansion accelerates as certification barriers filter gray-market competition.
- Membrane filtration advances:Protein isolation technology improvements lower production costs for isolate grades. Domestic manufacturers capture margin previously lost to imported concentrates.
Market Restraints
- Import dependency concentration:Australian and New Zealand suppliers dominate raw whey feedstock flows. Currency volatility and shipping disruptions transmit directly to landed cost structures.
- Lactose intolerance prevalence:Southeast Asian digestive sensitivity limits concentrate-grade penetration. Isolate and hydrolysate premiums constrain mass-market accessibility.
- Halal audit timeline friction:BPOM certification cycles extend supplier onboarding by 6-12 months. Working capital requirements rise for inventory held in pre-approval status.
Strategic Opportunities
- Eastern Indonesia underpenetration:Makassar and Denpasar health retail channels carry limited whey protein SKUs. First-mover advantage exists for halal-certified brands building distributor relationships.
- Clinical nutrition convergence:Hospital and eldercare facilities adopt protein supplementation for sarcopenia management. Medical channel margins exceed sports nutrition retail by substantial spreads.
- Ministry of Industry local content incentives:Domestic manufacturing investments qualify for tax relief and preferential procurement access. Kalbe Nutritionals and similar players expand in-house drying and blending capacity.
Industry Challenges
- Halal supply chain verification complexity:Enzyme and processing aid sourcing requires documentary traceability from cheese production through final powder. Audit preparation consumes dedicated compliance personnel.
- Specialized formulation talent scarcity:Protein chemistry expertise for sports-specific applications concentrates in Jakarta. Regional manufacturing facilities face recruitment competition from pharmaceutical employers.
- Cold chain integrity maintenance:Humid tropical storage conditions degrade unprotected powder quality. Distribution partners require training on moisture-controlled warehousing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Whey Protein Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends End User: Athletes, Bodybuilders, Health Enthusiasts, General Consumers Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms Form: Powder, Ready-to-Drink, Bars, Capsules |
| Companies Covered | Lactalis Ingredients, Abbott Nutrition Indonesia, Kalbe Nutritionals, Nutrifood Indonesia, Fonterra Co-operative Group, FrieslandCampina Ingredients, PT Muscle First Indonesia, PT Dunia Protein, Glanbia plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Whey Protein Market Shifts & Advancements
Microbiome-targeted protein formulations and direct-to-consumer subscription platforms are fragmenting Indonesia's traditional supplement retail structure. Technology investments concentrate on supply chain transparency and personalized nutrition algorithms.
Cross-flow microfiltration technology is decentralizing protein production economics by enabling smaller-scale, modular processing units. Regional dairy cooperatives in East Java and Central Java adopt these systems to produce whey concentrate for local brand supply. Distributed manufacturing is compressing logistics costs and import dependency for mid-tier product lines.
Indonesia's Ministry of Industry local content requirements are reshaping manufacturing location decisions for international suppliers. Domestic blending and packaging operations now qualify imported isolate powders for reduced tariff treatment. Australian suppliers respond by establishing toll-manufacturing partnerships with Kalbe Nutritionals and similar domestic processors.
Subscription-based replenishment models are displacing traditional pharmacy and supermarket purchasing for core users. Jakarta-based fitness enthusiasts prioritize automated delivery over retail stock-up behavior. This channel shift is most visible among CrossFit and boutique gym members with established consumption routines.
Indonesia Whey Protein Market Segmentation
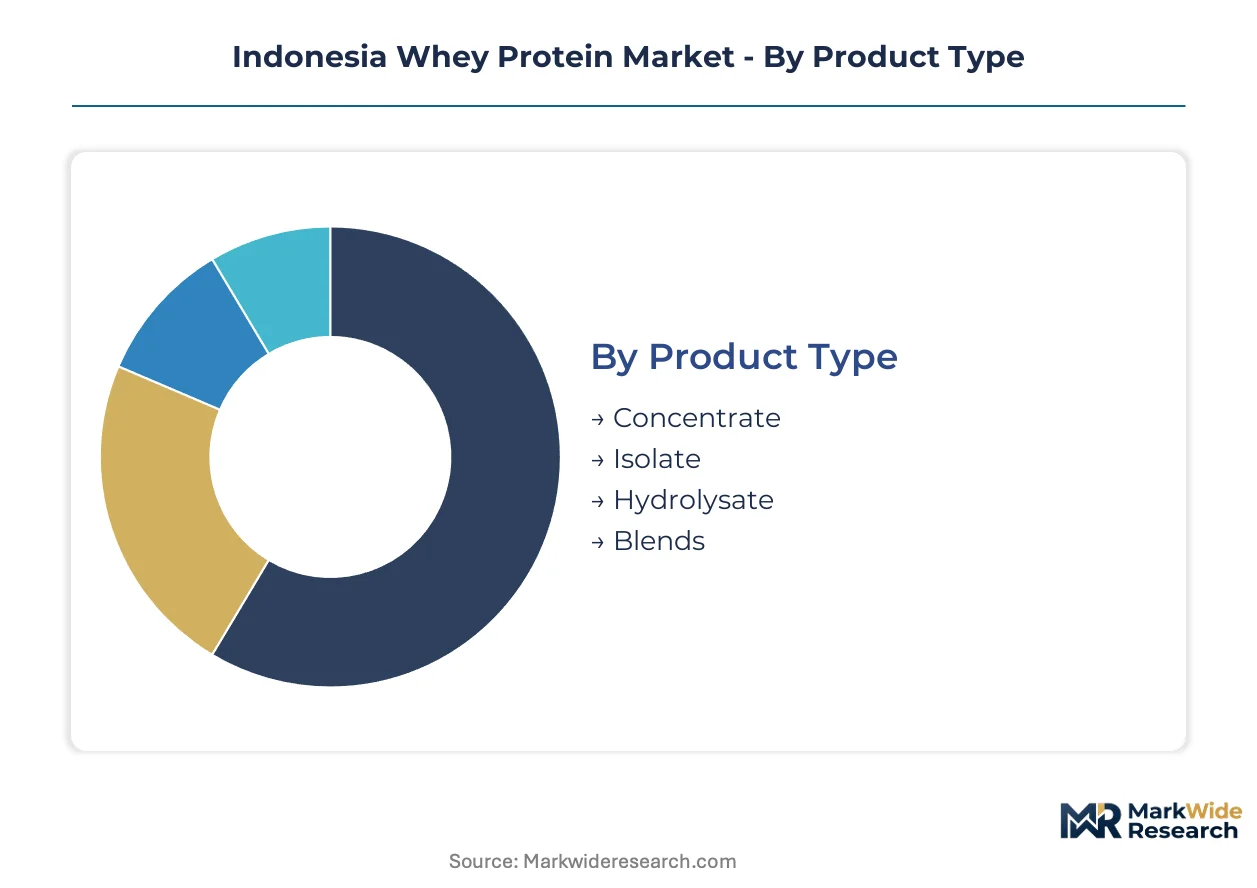
Indonesia's whey protein market fragments across four distinct dimensions that shape pricing power, channel strategy, and brand positioning. Product type and distribution channel decisions determine margin capture, while end-user targeting separates premium formulations from mass-market SKUs.
Product Type:
Buyers in this category differentiate primarily by lactose tolerance thresholds and protein purity requirements, creating tiered willingness-to-pay across processing intensities.
- Concentrate:Contains 35-80% protein with retained lactose and milk fats. Demand concentrates in Java's supermarket channels where price-sensitive general consumers prioritize cost accessibility over purity specifications.
- Isolate:Achieves 90%+ protein content through additional membrane filtration or ion exchange processing. Bodybuilders in Greater Jakarta's premium gym chains drive uptake for its reduced lactose profile and faster absorption kinetics.
- Hydrolysate:Enzymatically pre-digested for rapid amino acid availability. Clinical nutrition applications and elite athlete segments in Surabaya justify its substantial price premium.
- Blends:Combines concentrate and isolate ratios to balance cost and performance. Domestic manufacturers leverage these for mid-tier positioning in online retail.
Concentrate leads volumes today; isolate is gaining share fastest.
End User:
Consumption frequency and dosage precision separate professional users from casual adopters, reshaping formulation requirements and subscription economics.
- Athletes:Competitive and recreational competitors with structured training protocols. Sports-specific timing requirements drive demand for isolate and hydrolysate grades with batch-tested certification.
- Bodybuilders:High-volume consumers prioritizing lean mass accretion. Surabaya and Jakarta gym clusters generate concentrated repeat purchase velocity through direct-to-gym distribution.
- Health Enthusiasts:Wellness-focused millennials integrating protein into broader lifestyle regimens. Subscription platforms capture this segment through automated replenishment models.
- General Consumers:Occasional users seeking meal replacement or weight management support. Supermarket concentrate SKUs serve price-driven trial behavior.
General consumers dominate absolute headcount; athletes deliver highest per-capita spending expansion.
Distribution Channel:
Channel selection determines halal certification visibility, cold chain requirements, and customer education investment levels.
- Online Retail:E-commerce platforms and brand-direct websites. Jakarta-based fitness enthusiasts favor subscription automation and product review transparency over physical inspection.
- Supermarkets:Mass-market retail with limited SKU depth. Concentrate variants and blends occupy shelf space in Java's urban centers where impulse purchase behavior persists.
- Health Stores:Specialized retailers with trained staff and premium positioning. Isolate and hydrolysate grades command dedicated display in Greater Jakarta's supplement-focused chains.
- Gyms:Point-of-consumption sales through pro shops and vending. Post-workout immediate need states support higher price acceptance for ready-to-drink formats.
Online retail is expanding most quickly; health stores sustain premium margin capture.
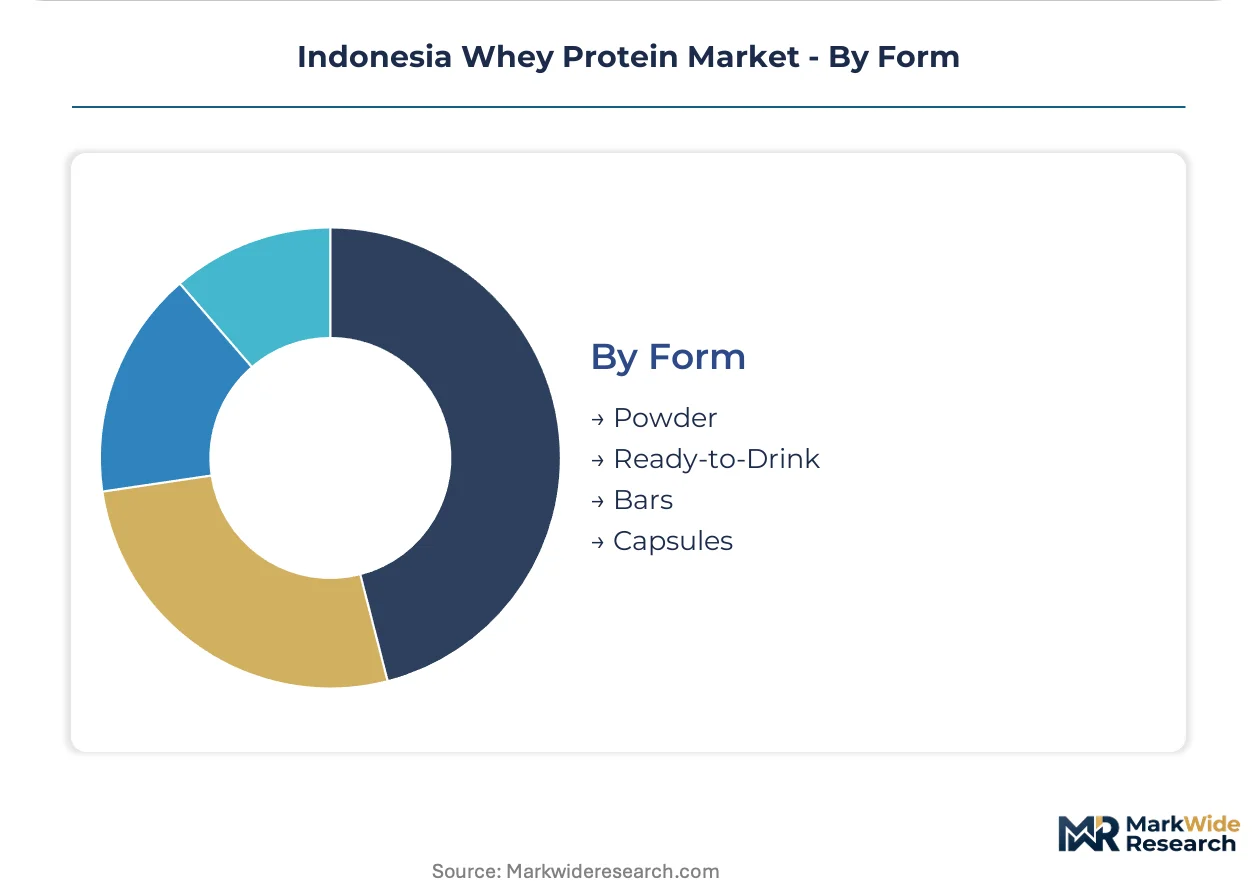
Form:
Convenience requirements and consumption occasion specificity drive format selection across storage, transport, and preparation constraints.
- Powder:Dried concentrate or isolate requiring reconstitution. Dominates volume through cost-per-serving efficiency and extended shelf stability in humid tropical conditions.
- Ready-to-Drink:Pre-mixed liquid formulations in single-serve packaging. Gym channel placement and on-the-go consumption in Jakarta's commuter corridors support premium pricing.
- Bars:Solid food-matrix protein delivery. Meal replacement positioning targets health enthusiasts seeking portability without preparation requirements.
- Capsules:Encapsulated protein or amino acid derivatives. Niche clinical and precision dosing applications with limited current penetration in Indonesian channels.
Powder leads volumes today; ready-to-drink shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness-conscious millennials cluster in Java's metropolitan corridors, concentrating purchasing power and gym infrastructure in ways that reshape supplier distribution priorities across the archipelago.
Greater Jakarta
CrossFit boxes and boutique fitness studios proliferate in South Jakarta and BSD City, generating concentrated demand for isolate-grade whey. BPOM's halal certification requirements filter imported products through formal channels, elevating compliance costs for gray-market competitors. Health store chains in Kelapa Gading and Senayan stock premium hydrolysate SKUs targeting affluent bodybuilders.
Surabaya
East Java's manufacturing base supports domestic toll-processing partnerships that reduce landed costs for Australian whey feedstock. The city's Ministry of Industry-registered facilities qualify for local content incentives that reshape import substitution economics. Gym density in Rungkut and Darmo clusters drives subscription-model adoption among young professionals.
Bandung
West Java's dairy cooperative network experiments with cross-flow microfiltration units for regional concentrate production. BPOM audit timelines extend supplier onboarding, favoring established halal-compliant processors with documentary traceability systems. Factory outlet channels in Lembang and Dago serve price-sensitive university students.
Makassar
South Sulawesi's health retail landscape carries limited whey protein SKU depth, creating first-mover openings for certified brands building distributor relationships. The national standardization agency's Codex-aligned protein content claims filter substandard imports from eastern Indonesia's formal channels. Local pharmacy chains in Panakkukang and Tamalanrea represent untapped clinical nutrition entry points.
Denpasar
Bali's wellness tourism infrastructure generates seasonal demand spikes for ready-to-drink protein formats in Seminyak and Ubud fitness centers. Humid tropical storage conditions degrade unprotected powder quality, forcing distributor training investments in moisture-controlled warehousing. Domestic blending operations in Badung regency qualify for tariff relief under Ministry of Industry local content schemes.
Indonesia Whey Protein Market Competitive Landscape
The competitive structure tilts toward halal-certified multinational suppliers with established Indonesian distribution partnerships. Three distinct archetypes occupy the market: Australasian dairy cooperatives leveraging origin halal credentials, domestic pharmaceutical conglomerates with in-house manufacturing footprints, and specialized sports nutrition formulators targeting gym-channel velocity. Capacity expansion and toll-manufacturing partnerships constitute the dominant competitive moves as players navigate BPOM certification friction.
Among the multinational dairy cooperatives, Fonterra Co-operative Group and FrieslandCampina Ingredients exemplify the halal-compliant supply chain archetype, occupying positions sustained by documentary traceability from cheese production through final powder. Kalbe Nutritionals anchors the domestic manufacturing tier, representing the local content incentive capture strategy through in-house drying and blending capacity. Glanbia plc sits within the specialized sports nutrition formulation segment, exemplifying premium positioning through isolate and hydrolysate grade concentration.
| Leading Market Players |
|---|
| Lactalis Ingredients |
| Abbott Nutrition Indonesia |
| Kalbe Nutritionals |
| Nutrifood Indonesia |
| Fonterra Co-operative Group |
| FrieslandCampina Ingredients |
| PT Muscle First Indonesia |
| PT Dunia Protein |
| Glanbia plc |
| Others |
Supply & Pricing Matrix
BPOM's halal certification mandate gates qualified supply access and premium-tier pricing power for whey protein suppliers entering Indonesia. The regulation forces documentary traceability investments that separate certified processors from gray-market competitors, compressing margins for non-compliant entrants while sustaining isolate-grade premiums for established players.
Pricing Analysis
Unbundled halal certification services command separate fees from product pricing, while bundled offerings from Australasian cooperatives absorb compliance costs into landed rates. Three-tier pricing structure across premium, standard, and economy levels separates hydrolysate clinical grades from isolate gym-channel SKUs and concentrate supermarket lines. Price differentiation centers on certification tier and volume scale, with isolate grades facing cost compression from domestic toll-processing expansion. General consumers in Java's supermarket channels exhibit highest price sensitivity; competitive bodybuilders in Greater Jakarta's premium gym chains show least.
Supply Chain Analysis
Halal qualification gating through BPOM's documentary traceability requirements filters feedstock sourcing to certified Australian and New Zealand dairy cooperatives with established audit protocols. Raw whey production draws from cheese-making byproduct streams, with enzymatic processing aids and membrane filtration equipment as critical component dependencies. Single-source vulnerability concentrates in trans-Tasman shipping lanes exposed to climate disruption. Distribution runs through Jakarta-based importers with cold chain warehousing before pharmacy, health store, and gym channel dispersal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's whey protein market functions as a geographic-arbitrage play between Australasian halal-certified supply origins and Java's concentrated demand pools, with BPOM's certification timeline differential creating working capital barriers that favor capitalized incumbents over underfunded entrants.
For Market Incumbents: To counter domestic toll-processing expansion by Kalbe Nutritionals and similar pharmaceutical conglomerates, deepen backward integration into Australian whey feedstock sourcing through long-term offtake agreements with Fonterra and FrieslandCampina. Fortify channel control by securing exclusive gym-chain distribution partnerships in Surabaya and BSD City before regional competitors replicate subscription automation capabilities. For New Entrants and Emerging Players: Enter via Makassar and Denpasar health retail channels where certified SKU depth remains minimal and first-mover distributor relationships yield disproportionate shelf access. Target clinical nutrition applications in South Sulawesi hospital systems and Bali eldercare facilities, where medical-channel margins exceed sports nutrition retail spreads. Pursue toll-manufacturing partnerships with Ministry of Industry-registered facilities to qualify for local content tariff relief. For Investors and Strategic Acquirers: Valuations sit cheapest among regional dairy cooperatives in East Java and Central Java experimenting with cross-flow microfiltration units for concentrate production. Long-term viability hinges on sustained BPOM regulatory enforcement that preserves certification barriers against gray-market erosion. Watch for Ministry of Industry local content incentive expansion as the inflection signal that would accelerate domestic manufacturing capacity buildout and compress import-dependent supplier margins.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Fast-Track Investment | BPOM audit preparation compresses supplier onboarding timelines from 12 months toward 6. |
| Toll-Manufacturing Partnership | Australian suppliers establish domestic blending capacity with Kalbe Nutritionals to capture local content tariff relief. |
| Clinical Nutrition Channel Entry | Hospital and eldercare procurement in Surabaya unlocks medical-grade margins above sports nutrition retail. |
| Subscription Platform Development | Jakarta-based fitness enthusiasts automate replenishment, displacing traditional pharmacy stock-up behavior. |
| Eastern Indonesia Distributor Buildout | Makassar and Denpasar health retail channels offer first-mover advantage before competitor SKU saturation. |
Research Methodology
Coverage spans Java, Sulawesi, and Bali, with primary inputs from each island's distinct supply and demand configuration. The analysis combines interviews with gym operators, health store buyers, pharmaceutical procurement managers, and BPOM regulatory affairs specialists with secondary validation from BPOM halal certification databases, Ministry of Industry local content registry filings, and BSN Codex Alimentarius adoption documentation. Bottom-up channel volume estimates triangulate against top-down dairy import trade flows.
Granularity-level framing models product type, end user, distribution channel, and form dimensions at the SKU level across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by price-per-kilogram realizations. Industry-specific forecast inputs include gym membership expansion rates in Greater Jakarta and Surabaya, and BPOM certification approval velocity trends.
Inputs from BPOM regulatory filings and Ministry of Industry incentive registries were available through the study window; gaps in real-time toll-manufacturing contract disclosures introduce uncertainty bands around domestic capacity expansion timing. Forecasts reflect documented assumptions on halal audit timeline stability and Australasian feedstock supply continuity. A model refresh is warranted upon material change in BPOM certification protocol stringency or Ministry of Industry local content threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Whipping Cream Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Global Quark and Fromage Frais Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Dry Buttermilk Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Textured Butter Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
North America Dairy Market
Dairy Products
Dairy Foods Market