
 Health Ingredients Market | 2026-2036
Health Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Health Ingredients Market Analysis
Modular premix bundling is consolidating buyer choice across the health ingredients supply chain. Cargill, Incorporated leverages backward integration into botanical extraction to sustain margin control over specialty extracts. BASF SE anchors its position through pharmaceutical-grade vitamin synthesis capacity at Ludwigshafen. Kerry Group differentiates via taste-masked delivery systems that compete on palatability in pediatric and geriatric formats.
Health ingredients comprise biologically active compounds—vitamins, minerals, amino acids, probiotics, and botanical extracts—formulated to deliver measurable physiological benefits beyond basic nutrition, typically standardized to defined purity thresholds and stability profiles under specified storage conditions. These inputs serve nutraceutical companies, food manufacturers, and healthcare professionals seeking evidence-based solutions for preventive health and targeted wellness interventions. Probiotics and amino acids represent the fastest-expanding product categories, driven by clinical pipeline expansion in gut-brain axis research and sports recovery applications. Powder and liquid forms capture disproportionate share in functional foods and beverages, while capsules dominate sports nutrition where portability and dose precision command premium positioning.
EFSA novel food regulations and FDA GRAS notification requirements shape substantiation burdens for bioactive ingredient suppliers, with non-compliant submissions facing extended evaluation timelines that delay market access. REACH compliance for botanical extracts and EU MDR spillover into ingestible medical foods further tighten purity and traceability mandates across European supply chains. Stakeholders must monitor evolving pharmacovigilance linkages between supplement adverse event reporting and ingredient-specific risk profiles to anticipate regulatory scope expansion.
Market Dynamics
Modular premix bundling is compressing supplier margins while concentrating procurement power among nutraceutical formulators seeking single-source accountability for bioactive stability and traceability documentation.
Growth Catalysts
- EFSA Novel Food Pathway Expansion:Accelerated approval timelines for fermented postbiotics are unlocking commercialization of next-generation gut health actives across European markets.
- Sports Nutrition Formulation Demand:Branched-chain amino acid premixes with instantized dissolution profiles are capturing volume from recovery beverage manufacturers in Germany and the United States.
- Precision Fermentation Scale-Up:Microbial production of rare botanical actives is collapsing cost curves for saffron-derived crocins and resveratrol analogues previously constrained by agricultural supply.
Market Restraints
- Botanical Raw Material Volatility:Climate-driven harvest failures in Indian turmeric and Chinese ginseng regions are forcing 12-18 month forward contracting to secure standardized curcumin and ginsenoside supply.
- REACH Compliance Burden:ECHA substance registration requirements for novel extracts are extending EU market entry timelines by 14-24 months and consuming 15-20% of R&D budgets for mid-tier suppliers.
- Synthetic Vitamin Price Compression:Pharmaceutical-grade ascorbic acid and tocopherol from Chinese chemical synthesis capacity is eroding margins for European fermentation-based producers.
Strategic Opportunities
- Pediatric Palatability Gap:Taste-masked probiotic sachets with stability-proven strains are penetrating underdeveloped markets for infant gut health in Southeast Asia.
- CSRD-Driven Disclosure:Corporate sustainability reporting mandates are creating premium positioning for suppliers with verified regenerative agriculture sourcing and blockchain-enabled traceability.
- AI-Formulation Convergence:Machine learning platforms predicting synergistic bioactive combinations are compressing development cycles for condition-specific premixes targeting sleep and cognitive health.
Industry Challenges
- Pharmacovigilance Integration:EFSA and FDA adverse event database linkages are demanding real-time batch-to-consumer traceability systems that legacy ERP infrastructure cannot support.
- Clinical Substantiation Talent Scarcity:Shortages of biostatisticians with nutraceutical trial design expertise are delaying IND-equivalent study completion for novel bioactive claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health Ingredients Market |
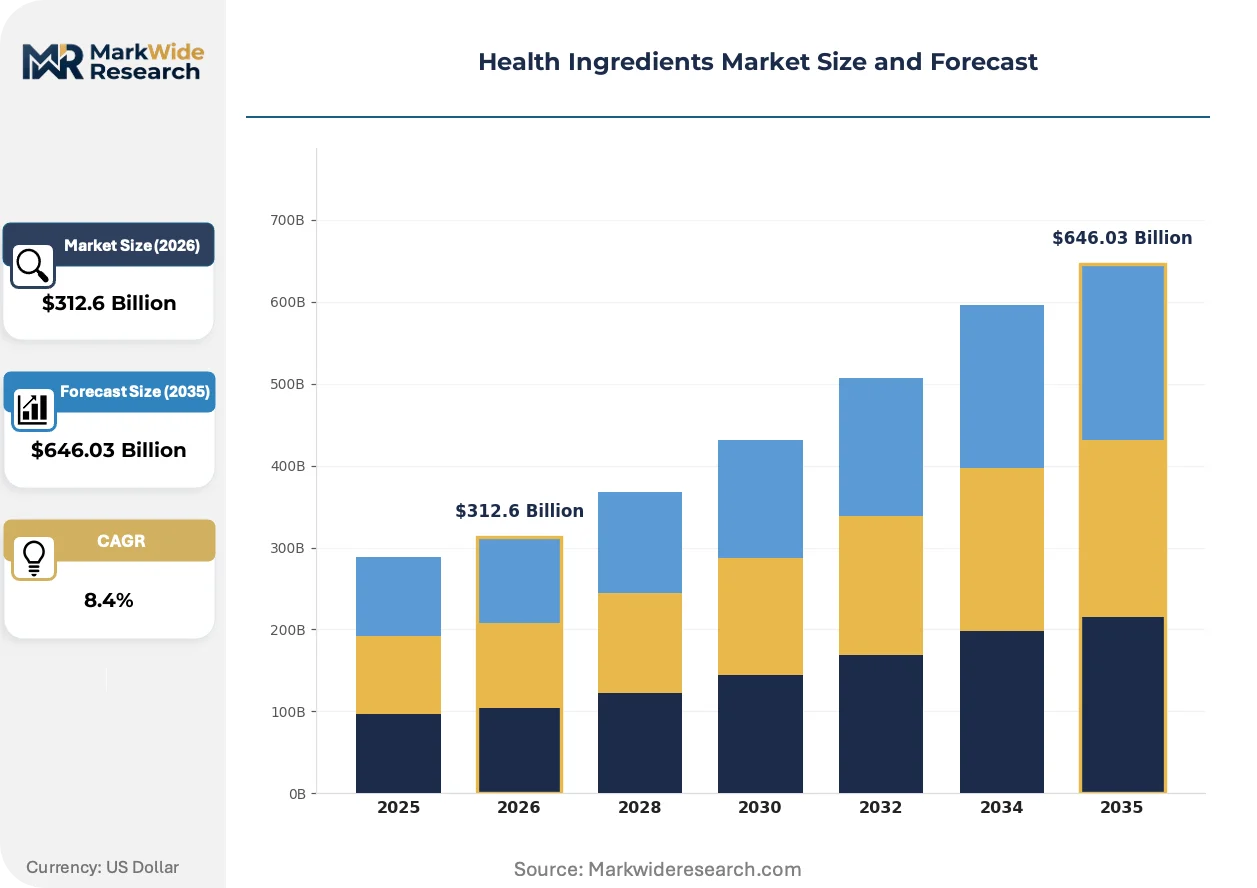
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics End User: Healthcare Professionals, Nutraceutical Companies, Food Manufacturers, Fitness Enthusiasts Form: Powder, Capsule, Liquid, Tablet Application: Dietary Supplements, Functional Foods, Personal Care, Sports Nutrition |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, BASF SE, DSM-Firmenich AG, Kerry Group, Ingredion Incorporated, Tate & Lyle PLC, DuPont de Nemours, Inc., Associated British Foods plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health Ingredients Market Emerging Trajectories
Bioprocess engineering and digital traceability infrastructure are converging to redefine how bioactive purity is verified, certified, and communicated through the ingredient supply chain.
Continuous fermentation technology is unifying upstream biomass production with downstream purification in single-site configurations. Nutraceutical contract manufacturers in the Netherlands and Denmark are adopting these systems to reduce cross-contamination risk between probiotic strains. The technology is unifying quality assurance and production economics by eliminating hold times that previously degraded viable cell counts.
EU MDR spillover into ingestible medical foods is tightening purity thresholds for ingredients destined for metabolic disorder management products. Manufacturers must now demonstrate pharmaceutical-grade batch consistency previously reserved for parenteral nutrition. German and French formulators are responding by segregating supply chains and demanding dedicated production lines from extract suppliers.
Direct-to-manufacturer digital procurement platforms are disintermediating traditional ingredient distributors for standardized vitamins and minerals. Large functional food producers in the United States are consolidating annual contracts through these channels, extracting 8-12% cost advantages while accepting longer lead times. This pattern is most visible in the Pacific Northwest beverage cluster, where formulators source ascorbic acid and zinc premixes through B2B marketplaces.
Health Ingredients Market Segmentation
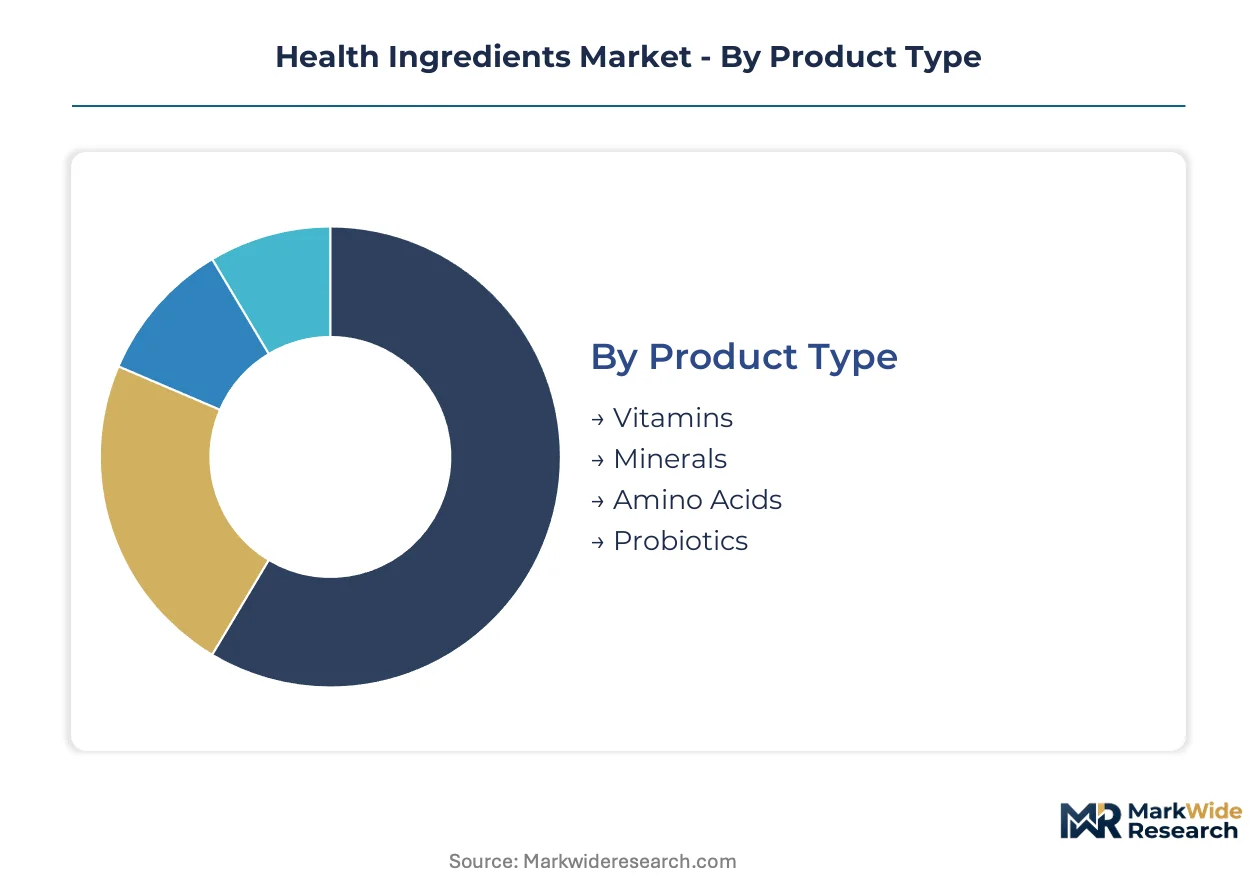
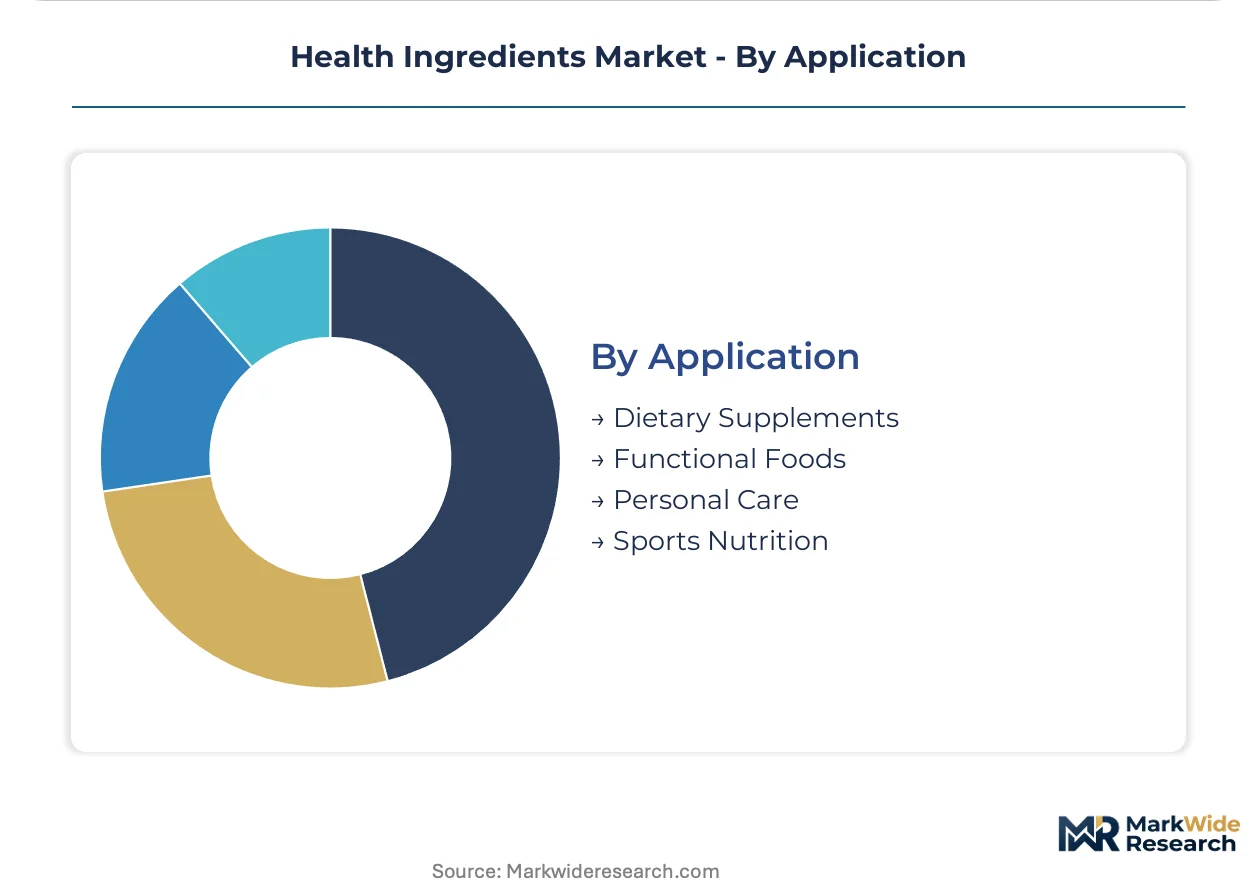
Ingredient formulators configure supply chains around stability requirements and dose precision needs. Segmentation reveals where premium positioning commands price premiums versus where commodity scale dominates procurement economics.
Product Type:
Volume concentration favors synthetic inputs with established fermentation infrastructure, while premium capture gravitates toward clinically substantiated live cultures and condition-specific amino acid ratios.
- Probiotics:Live microbial cultures standardized to CFU counts and strain-specific genomic identification. Demand clusters in Germany and Denmark around infant gut health and metabolic syndrome applications, where EFSA novel food pathways validate postbiotic derivatives for commercial deployment.
- Amino Acids:Crystalline compounds and peptide fractions with defined enantiomeric purity for sports recovery and medical nutrition. Branched-chain formulations with instantized dissolution profiles are capturing volume from recovery beverage manufacturers in Germany and the United States.
- Vitamins:Synthetic and fermentation-derived micronutrients standardized to USP or EP monographs.
- Minerals:Chelated and inorganic salt forms with defined bioavailability markers for fortification applications.
Mature deployment sits with Vitamins. Newer deployment is concentrated in Probiotics.
End User:
Procurement sophistication separates institutional buyers with pharmacovigilance infrastructure from direct-to-consumer channels with simpler stability documentation requirements.
- Nutraceutical Companies:Formulators of finished supplements with multi-ingredient premix needs and batch-to-batch consistency requirements. These buyers consolidate procurement through modular bundling arrangements that demand single-source accountability for bioactive stability and traceability documentation.
- Food Manufacturers:Industrial-scale fortification operations integrating health actives into mass-market processed foods. German and Dutch dairy processors lead European adoption of probiotic strains with validated survival through pasteurization and shelf-life testing.
- Healthcare Professionals:Clinical prescribers of medical foods and condition-specific nutrition protocols.
- Fitness Enthusiasts:Direct purchasers of sports nutrition products with dose precision and portability priorities.
Established procurement frameworks dominate Nutraceutical Companies. Emerging specification complexity is concentrated in Healthcare Professionals.
Form:
Processing economics and stability profiles create divergent margin structures across solid and liquid delivery systems.
- Powder:Bulk intermediates and finished sachets with moisture-protected packaging for beverage and food integration. Kerry Group's taste-masked delivery systems compete on palatability in pediatric and geriatric formats where powder reconstitution dominates administration.
- Liquid:Emulsion and suspension formats with preservative systems or aseptic processing for functional beverages. Cargill's backward integration into botanical extraction sustains margin control over specialty liquid extracts for beverage fortification.
- Capsule:Two-piece hard gelatin and HPMC shells with powder or liquid fill for dose precision.
- Tablet:Compressed solids with coating systems for moisture protection and controlled release.
Scale manufacturing gravitates toward Powder. Premium positioning concentrates in Capsule.
Application:
Regulatory pathway complexity separates food-adjacent categories from borderline pharmaceutical claims with substantiation burdens.
- Sports Nutrition:Protein, amino acid, and ergogenic aid formulations for athletic performance and recovery. Branched-chain amino acid premixes with instantized dissolution profiles are capturing volume from recovery beverage manufacturers in Germany and the United States.
- Functional Foods:Mass-market processed foods with added bioactive ingredients beyond basic nutrition. Powder and liquid forms capture disproportionate share as German and Dutch formulators integrate fermentation-derived actives into dairy and bakery applications.
- Dietary Supplements:Concentrated bioactive delivery in discrete dose formats with structure-function claims.
- Personal Care:Topical and ingestible beauty applications with collagen, antioxidants, and microbiome-targeting ingredients.
Established claim frameworks support Dietary Supplements. Steepest expansion trajectory appears in Sports Nutrition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany, China, and the United States concentrate health ingredient manufacturing through targeted tax incentives and streamlined regulatory pathways for novel bioactive production.
Germany
Precision fermentation capacity clusters around Ludwigshafen and Hamburg, driven by pharmaceutical-grade vitamin synthesis and postbiotic commercialization. EFSA novel food approvals shape substantiation requirements for bioactive claims. The Frankfurt-Rhine-Main corridor integrates fermentation science with finished-form manufacturing for nutraceutical exporters.
United States
FDA GRAS notification requirements drive clinical validation investment for bioactive ingredient suppliers targeting functional food applications. Sports nutrition formulation demand concentrates in the Pacific Northwest beverage cluster, where direct-to-manufacturer digital procurement platforms disintermediate traditional distributors for standardized vitamin premixes.
China
Synthetic vitamin production capacity dominates global supply of pharmaceutical-grade ascorbic acid and tocopherol, eroding margins for European fermentation-based producers. NMPA regulatory harmonization with international standards accelerates domestic novel food ingredient approvals. The Yangtze River Delta anchors extraction and chemical synthesis operations for botanical actives.
Netherlands
Continuous fermentation technology adoption unifies upstream biomass production with downstream purification in single-site configurations. Dutch nutraceutical contract manufacturers reduce cross-contamination risk between probiotic strains through integrated bioprocess engineering. The Randstad region hosts taste-masked delivery system development for pediatric and geriatric formats.
India
Climate-driven harvest failures in turmeric-growing regions force 12-18 month forward contracting to secure standardized curcumin supply for extract processors. FSSAI tightening of purity thresholds for botanical imports aligns with EU MDR spillover into ingestible medical foods. Maharashtra and Gujarat concentrate backward-integrated botanical extraction operations serving European formulators.
Health Ingredients Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The supplier base fragments between agricultural commodity processors with captive extraction infrastructure and pharmaceutical-grade synthesis specialists with fermentation science capabilities. Three archetypes dominate: backward-integrated agricultural traders, pharmaceutical-grade vitamin manufacturers, and taste-technology formulators. Competitive moves center on modular premix bundling arrangements and blockchain-enabled traceability certification.
Within the diversified conglomerate tier, Cargill, Incorporated and Archer Daniels Midland Company represent agricultural commodity processors with captive botanical extraction infrastructure. BASF SE anchors the pharmaceutical-grade synthesis archetype through Ludwigshafen-based fermentation capacity. Kerry Group exemplifies the taste-technology specialist positioning through palatability-focused delivery systems.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| DSM-Firmenich AG |
| Kerry Group |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| DuPont de Nemours, Inc. |
| Associated British Foods plc |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification divergence separates fermentation-derived actives from synthetic chemical alternatives, compressing margins for European producers while concentrating procurement power among German and Dutch formulators with dedicated supply lines. This bifurcation manifests in contract structures that reward batch-to-batch consistency documentation with premium positioning, while spot-market botanical extracts face price erosion from climate-driven harvest volatility.
Pricing Analysis
Short lead-time premiums command substantial markups for EFSA novel food-compliant postbiotics with validated stability profiles, while extended forward contracting secures discounted rates for standardized vitamin premixes. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels anchors differentiation, with REACH registration status and USP monograph compliance as primary price drivers. Cost compression in synthetic vitamin categories is intensifying because Chinese ascorbic acid and tocopherol capacity has flooded European markets. Nutraceutical formulators with modular bundling arrangements demonstrate lowest price sensitivity, whereas mid-tier extract processors face acute margin pressure from dual regulatory compliance burdens.
Supply Chain Analysis
EFSA novel food qualification and FDA GRAS notification gating restrict viable supplier pools to established fermentation science operators with documented pharmacovigilance infrastructure. Germany, China, and India concentrate upstream capacity, with Ludwigshafen pharmaceutical-grade synthesis, Yangtze River Delta chemical production, and Maharashtra botanical extraction as anchor nodes. Raw material flows draw from Indian turmeric cultivars, Chinese ginseng harvests, and European cereal fermentation feedstocks. Single-source vulnerability persists for saffron-derived crocins and rare resveratrol analogues where precision fermentation scale-up remains incomplete. Distribution runs through direct-to-manufacturer digital procurement platforms for standardized inputs, while specialty extracts maintain traditional distributor relationships for technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous fermentation technology is displacing batch-process legacy infrastructure, compressing development timelines for next-generation gut health actives while demanding capital redeployment toward integrated bioprocess engineering capabilities.
For Market Incumbents: Extend pharmaceutical-grade vitamin synthesis capacity at Ludwigshafen and Hamburg fermentation clusters to defend against Chinese synthetic price compression. Secure backward integration into regenerative agriculture sourcing with blockchain-enabled traceability to meet CSRD disclosure mandates and capture premium positioning from sustainability-verified buyers.
For New Entrants and Emerging Players: Launch via direct-to-manufacturer digital procurement platforms targeting Pacific Northwest beverage formulators with instantized branched-chain amino acid premixes. Pediatric palatability gaps in Southeast Asian infant gut health markets offer the most penetrable white space, with taste-masked probiotic sachets as the specific go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with precision fermentation specialists given EFSA novel food pathway acceleration for postbiotic commercialization. Long-term viability over the next decade favors microbial production platforms with validated strain libraries and single-site continuous processing infrastructure. Watch for FDA GRAS notification backlog clearance as the inflection indicator for bioactive ingredient valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial production of rare botanical actives collapses cost curves for saffron-derived crocins previously constrained by agricultural supply. |
| Backward Integration into Botanical Extraction | Cargill's captive supply of specialty liquid extracts sustains margin control over beverage fortification applications. |
| CSRD-Driven Traceability Certification | Blockchain-enabled regenerative agriculture sourcing creates premium positioning for suppliers serving European sustainability-mandated buyers. |
| Taste-Technology Delivery System Development | Kerry Group's palatability-focused formulations penetrate underdeveloped pediatric and geriatric powder reconstitution markets. |
| Continuous Fermentation Technology Adoption | Dutch contract manufacturers reduce cross-contamination risk between probiotic strains through integrated single-site bioprocess engineering. |
Methodological Framework
Independent corroboration across fermentation science executives, regulatory affairs specialists at EFSA and FDA, nutraceutical procurement directors, and botanical extract processors underwrites the qualitative findings. Secondary validation draws from EFSA novel food submission databases, FDA GRAS notification filings, REACH substance registration records, and CSRD sustainability disclosure frameworks. Bottom-up volume modeling across strain-specific probiotic categories and top-down value reconciliation through premix bundling arrangements ensure analytical consistency.
Rate-of-change decomposition separates volume expansion from price trajectory across the projection horizon, with segmentation dimensions spanning product type, end-user procurement sophistication, delivery form stability requirements, and application regulatory pathway complexity. CAGRs derive from cohort progression analysis of clinically validated bioactive commercialization timelines. Fermentation capacity utilization rates and EFSA approval velocity serve as industry-specific forecast inputs.
Regulatory scope expansion, climate-driven botanical harvest disruption, and precision fermentation yield breakthroughs are the dominant revision risks. Forecasts reflect documented assumptions regarding strain stability validation and novel food substantiation burden trajectories. A model refresh is warranted upon material change in EFSA novel food evaluation timelines or FDA pharmacovigilance database integration mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Zinc Gluconate Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Apo-8 Carotenal Market