
 US Ingredients Market | 2026-2036
US Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
US Ingredients Market Insights
Subscription-based technical service layers for clean-label reformulation is pivoting how ingredient suppliers monetize relationships beyond commodity volumes. Cargill leverages its vertical integration across oilseeds and starches to anchor supply security for major food manufacturers. Kerry Group differentiates through flavor-integrated nutrition systems that combine taste modulation with functional health claims. DSM specializes in fermentation-derived vitamins and enzymes that command premium positioning in fortified applications.
Ingredients encompass functional and sensory additives—sweeteners, emulsifiers, colorants, preservatives, and their derived forms—that modify taste, texture, stability, or nutritional profile in processed foods and beverages, typically specified by purity grades, particle size distributions, and heat-stability thresholds for industrial-scale incorporation. The sweeteners category dominates volume flows through high-fructose corn syrup and alternative polyol demand, while the emulsifiers segment leads margin capture as clean-label lecithin and plant-based stabilizers displace synthetic options. Beverage applications are pulling the fastest growth in preservative and colorant demand as RTD and functional drink portfolios expand.
The FDA governs ingredient safety through GRAS determinations and Food Safety Modernization Act compliance, while USDA organic certification and EPA biofuel mandates intersect with agricultural input sourcing. State-level regulations in California's Proposition 65 warning requirements and New York's emerging packaging disclosure rules add compliance layers that favor domestic suppliers with traceable supply chains. Stakeholders must monitor how FSMA traceability mandates and evolving state chemical disclosure laws will reshape supplier qualification timelines and reformulation investment cycles.
Market Dynamics
Clean-label reformulation mandates from major food manufacturers are compressing supplier qualification timelines while simultaneously fragmenting procurement across specialty ingredient portfolios. This structural pressure is forcing ingredient suppliers to embed technical service capabilities directly into customer relationships rather than competing on commodity volume alone.
Growth Catalysts
- GRAS Notification Modernization:The FDA's streamlined safety determination process accelerates novel ingredient commercialization timelines for fermentation-derived proteins and alternative sweeteners.
- Plant-Based Protein Technology:Precision fermentation and extrusion advances enable functional meat and dairy analogues that replicate texture profiles previously unattainable with conventional soy or pea isolates.
- California Food-Tech Corridor Concentration:Venture-backed formulation labs in San Francisco and Los Angeles generate concentrated demand pull for clean-label emulsifiers and natural colorants.
Market Restraints
- Input Cost Volatility:Corn and soybean price swings directly compress margins for high-fructose corn syrup and lecithin producers dependent on Midwest grain belt supply.
- Supplier Concentration Risk:Domestic starch and oilseed processing capacity clusters among vertically integrated agribusinesses with captive origination networks.
- Technical Limitation:Natural preservative alternatives struggle to match synthetic benzoate and sorbate efficacy in neutral-pH beverage applications.
Strategic Opportunities
- Midwest Grain Belt Expansion:Nebraska and Iowa processing hubs offer underutilized capacity for specialty maltodextrin and modified starch production serving clean-label markets.
- FSMA Traceability Mandates:Lot-level digital tracking requirements create service revenue streams for suppliers with integrated blockchain or ERP-enabled supply chain visibility.
- Precision Fermentation Convergence:Combining synthetic biology with traditional food processing opens novel ingredient categories including animal-free collagen and customized protein isolates.
Industry Challenges
- Reformulation Talent Scarcity:Food scientists with dual expertise in sensory science and regulatory navigation command premium compensation and extend customer project timelines.
- Clean-Label Certification Complexity:USDA Organic, Non-GMO Project, and emerging carbon-neutral standards require parallel documentation systems that strain mid-tier supplier compliance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Ingredients Market |
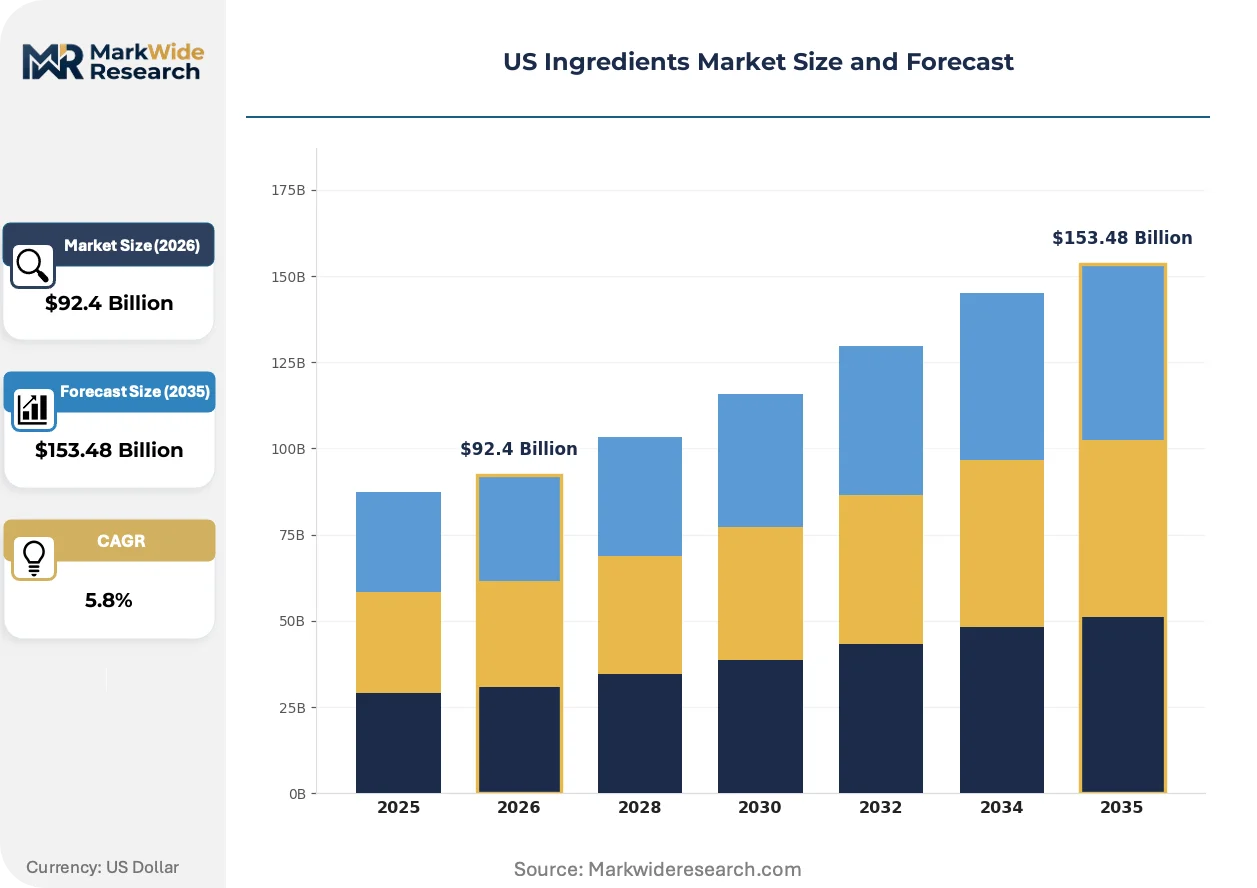
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $153.48 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweeteners, Emulsifiers, Colorants, Preservatives Application: Beverages, Bakery, Dairy, Snacks Form: Powder, Liquid, Granular, Paste End User: Food Manufacturers, Beverage Producers, Restaurants, Retailers |
| Companies Covered | Cargill, Archer Daniels Midland, Ingredion Incorporated, DSM, Kerry Group, International Flavors & Fragrances, Sensient Technologies Corporation, Chr. Hansen, Tate & Lyle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Ingredients Market Trends and Innovations
Bioprocessing advances and regulatory transparency mandates are converging to reshape how ingredient suppliers differentiate beyond commodity specifications. Technical service integration and digital traceability are becoming primary competitive battlegrounds.
Precision fermentation is electrifying protein ingredient supply chains by enabling animal-free whey and casein production with identical functional properties to dairy-derived equivalents. Beverage and nutrition bar manufacturers are accelerating adoption timelines from pilot-scale to commercial volumes within compressed 18-month windows. This biotechnology is compressing traditional dairy ingredient procurement relationships and forcing established suppliers to develop in-house fermentation capabilities or risk displacement.
The FDA's updated GRAS notification framework and accompanying Food Safety Modernization Act traceability mandates are restructuring supplier qualification protocols. Ingredient buyers now require documented supply chain mapping and hazard analysis documentation as table stakes for contract eligibility. Small and mid-sized suppliers in California and the Pacific Northwest face the steepest compliance investment curves relative to their revenue bases.
Subscription-based technical service contracts are displacing traditional spot purchasing for complex reformulation projects. Major food manufacturers in the Midwest and Southeast are locking multi-year agreements that bundle ingredient supply with sensory testing and regulatory filing support. This purchasing evolution concentrates relationship value among suppliers with integrated R&D facilities and is most visible in the clean-label beverage and bakery segments where reformulation cycles have compressed to six-month intervals.
US Ingredients Market Segmentation
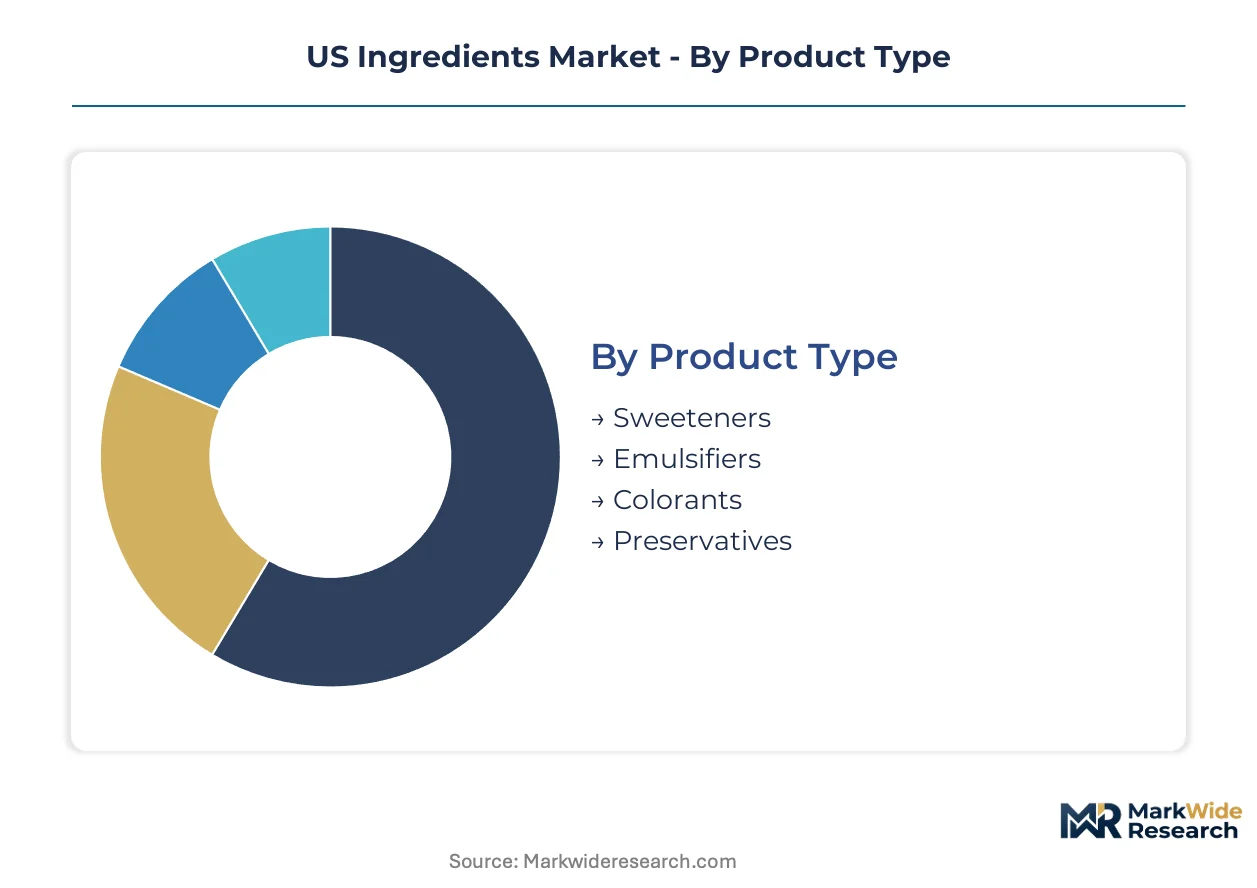
Ingredient suppliers configure production assets around specification intensity rather than volume throughput. Segmentation reveals where technical service investments concentrate and which procurement relationships command premium positioning.
Product Type:
Standardization dominates commodity-grade sweeteners and emulsifiers, while colorants and preservatives demand batch-level customization for clean-label compliance.
- Sweeteners:High-fructose corn syrup and polyol blends supply beverage and bakery reformulation at industrial scale. Demand clusters in Midwest corn-processing corridors where captive origination networks anchor supply security for major food manufacturers.
- Emulsifiers:Lecithin and plant-based stabilizers displace synthetic alternatives in clean-label applications. California's food-tech corridor pulls specialty lecithin for RTD beverage texture modulation, with Kerry Group and Cargill anchoring technical service relationships.
- Colorants:Natural extracts and fermentation-derived pigments serve bakery and dairy visual standards. FDA GRAS notification requirements extend qualification timelines for novel natural sources.
- Preservatives:Benzoate alternatives and cultured dextrose solutions address neutral-pH beverage stability challenges. Technical limitations in efficacy versus synthetic benchmarks constrain adoption velocity.
Most installed capacity flows through sweeteners. Expansion is steepest in emulsifiers.
Application:
Volume scale separates beverage and snack applications from specification intensity in dairy and bakery.
- Beverages:RTD and functional drink portfolios drive preservative and colorant procurement with compressed six-month reformulation cycles. Subscription-based technical service contracts concentrate here.
- Bakery:Emulsifier and sweetener specifications balance shelf-life extension with clean-label positioning. Midwest grain-processing belt suppliers dominate volume relationships.
- Dairy:Precision fermentation-derived proteins enable animal-free analogues with identical functional properties. California formulation labs accelerate commercial adoption timelines.
- Snacks:Coating and flavor-delivery systems rely on powder and granular form factors with moderate customization requirements.
Beverages capture the steepest service premium layering. Dairy is climbing the fastest on biotechnology disruption.
Form:
Handling economics and dissolution kinetics dictate form selection across heat-processing and cold-fill applications.
- Powder:Dominates bakery and dry-mix applications with extended shelf stability and freight efficiency. Midwest distribution hubs optimize bulk handling infrastructure.
- Liquid:Preferred for beverage integration and continuous processing lines. Tanker-delivered high-fructose corn syrup anchors sweetener volume flows.
- Granular:Serves snack coating and controlled-release applications where particle size distribution affects mouthfeel.
- Paste:Concentrated flavor and color systems for artisan bakery and restaurant manufacturing with small-batch flexibility.
Liquid form holds the largest processing footprint. Powder is gaining share fastest on clean-label dry-mix demand.
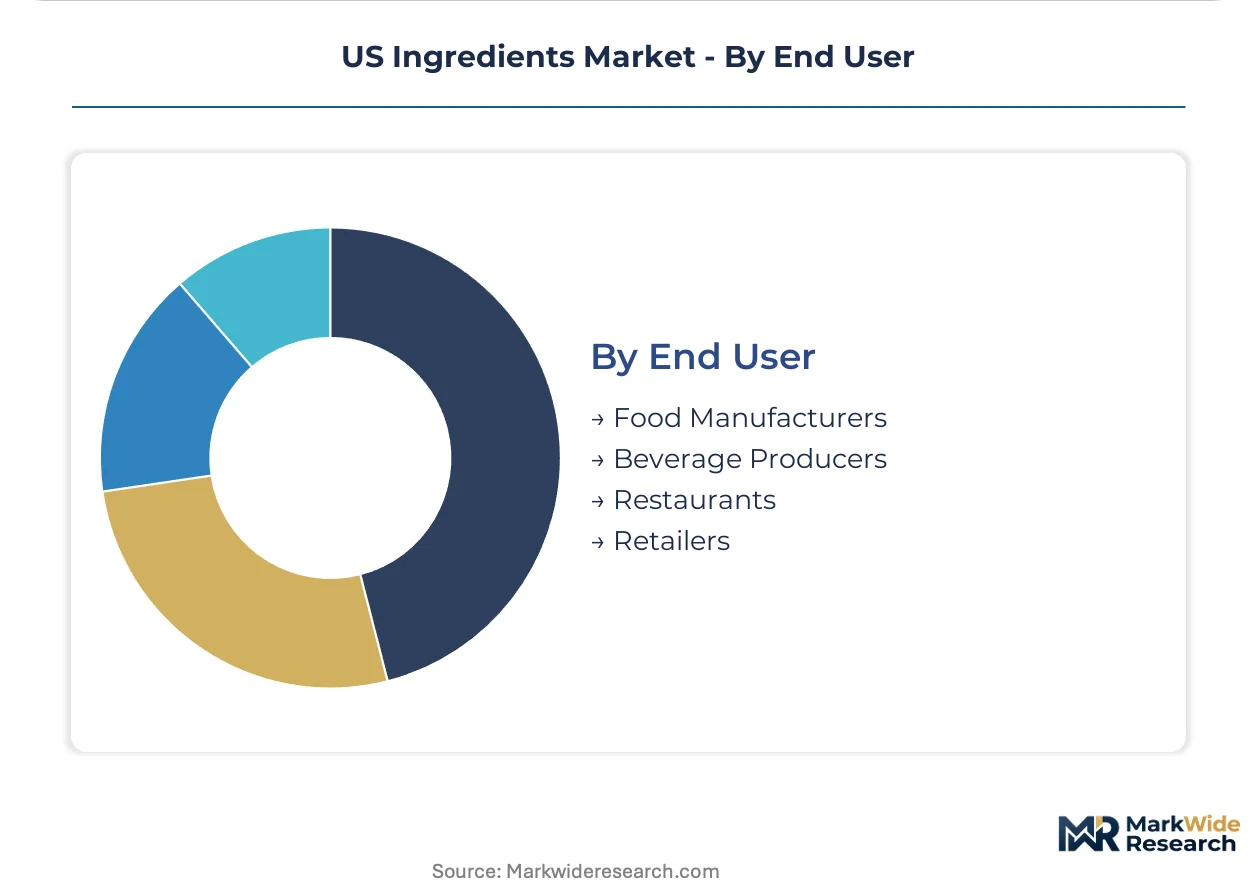
End User:
Procurement sophistication tiers from multinational food manufacturers with integrated R partnerships to fragmented restaurant and retail channels.
- Food Manufacturers:Multi-year technical service agreements bundle ingredient supply with sensory testing and regulatory filing support. FSMA traceability mandates require lot-level digital documentation.
- Beverage Producers:Accelerating reformulation cycles compress supplier qualification timelines. California and Pacific Northwest venture-backed brands generate concentrated demand pull.
- Restaurants:Distributed procurement through broadline distributors with limited specification control. Menu labeling transparency requirements drive clean-label interest.
- Retailers:Private-label formulation relies on co-manufacturer ingredient selection with emerging carbon-neutral certification requirements.
Food manufacturers command the deepest supplier integration. Beverage producers are expanding procurement most quickly on functional drink proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity migrates toward jurisdictions with lower compliance friction, creating arbitrage between California's stringent disclosure requirements and Midwest states with streamlined permitting. FDA's GRAS modernization and FSMA traceability mandates reshape where suppliers locate processing assets.
California
Venture-backed formulation labs in San Francisco and Los Angeles generate concentrated demand for clean-label emulsifiers and natural colorants. Proposition 65 warning requirements extend supplier qualification timelines and favor domestic suppliers with traceable supply chains. The state's food-tech corridor anchors precision fermentation commercialization for animal-free proteins.
Midwest Grain Belt
Nebraska and Iowa processing hubs leverage underutilized capacity for specialty maltodextrin and modified starch production. Corn and soybean price swings directly compress margins for high-fructose corn syrup and lecithin producers dependent on captive origination networks. Chicago distribution infrastructure optimizes bulk handling for powder and liquid form factors.
Texas
Gulf Coast petrochemical corridors supply synthetic preservative precursors and emulsifier feedstocks with integrated logistics advantages. EPA biofuel mandates intersect with agricultural input sourcing for ethanol-derived ingredient streams. Houston's chemical processing cluster supports modified starch and polyol production for beverage applications.
Pacific Northwest
Oregon and Washington fermentation facilities specialize in enzyme and vitamin production through precision bioprocessing. State-level chemical disclosure rules add compliance layers that strain mid-tier supplier bandwidth relative to revenue bases. Seattle-area technical service providers anchor subscription-based reformulation support for clean-label beverage brands.
Southeast
Georgia and Florida distribution hubs serve restaurant and retail channels with moderate specification control through broadline networks. Menu labeling transparency requirements drive clean-label interest without the qualification intensity of West Coast markets. Atlanta's logistics infrastructure supports granular and paste form factors for snack coating applications.
US Ingredients Market Competitive Landscape
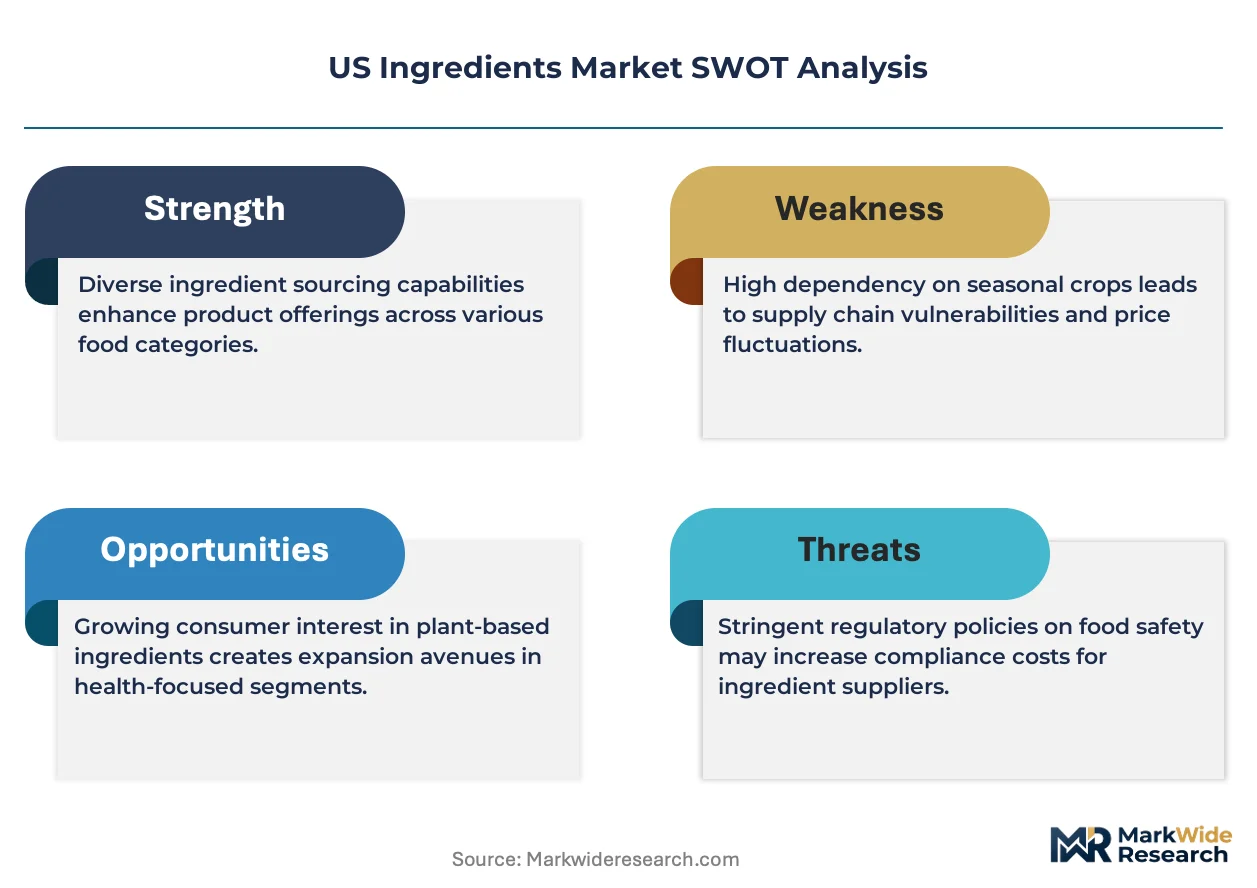
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated agribusinesses anchoring commodity sweetener flows while technical service providers capture premium positioning in clean-label reformulation. The supplier base clusters into three strategic archetypes: grain-origin processors with captive origination networks, fermentation specialists commanding biotechnology premiums, and flavor-integrated nutrition system providers. M&A activity concentrates on precision fermentation capabilities, while capacity expansion targets Midwest specialty starch and modified protein isolates.
Within the grain-processing tier, Cargill and Archer Daniels Midland exemplify vertically integrated structures with oilseed and starch origination networks. Among biotechnology-focused players, DSM occupies a position in fermentation-derived vitamins and enzymes. Kerry Group represents the flavor-integrated nutrition archetype, bundling taste modulation with functional health claims. These three anchors demonstrate how supplier qualification timelines and technical service depth determine relationship value beyond commodity volumes.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland |
| Ingredion Incorporated |
| DSM |
| Kerry Group |
| International Flavors & Fragrances |
| Sensient Technologies Corporation |
| Chr. Hansen |
| Tate & Lyle |
| Others |
Pricing and Supply Chain Analysis
Chicago Board of Trade corn futures cascade through the US Ingredients Market supply chain, compressing margins for Midwest sweetener processors while amplifying pricing power for coastal fermentation specialists with de-risked input profiles. This commodity-price transmission mechanics splits the market into volume-driven grain-origin tiers and premium biotechnology positioning.
Pricing Analysis
Distributor margin layers absorb 12-18 points on specialty emulsifiers and natural colorants before reaching California beverage formulators, while direct-to-OEM contracts on high-fructose corn syrup trade closer to processor netbacks. Three-tier pricing structure across premium fermentation-derived, standard plant-based, and economy synthetic grades anchors differentiation, with USDA Organic and Non-GMO Project certifications commanding 15-25 point premia. Cost compression in commodity sweeteners is intensifying because captive origination networks at major agribusinesses limit supplier switching. Food manufacturers with multi-year technical service agreements show lowest price sensitivity; fragmented restaurant distributors exhibit highest.
Supply Chain Analysis
Domestic-content mandates under the Food Safety Modernization Act are reshaping sourcing toward traceable US and Canadian grain corridors, displacing spot-market South American corn alternatives. Raw material flows draw from Iowa and Nebraska oilseed processing, Illinois corn wet-milling, and Oregon fermentation feedstocks. Tariff exposure on imported natural colorant extracts from India and Peru creates single-source vulnerability for West Coast formulators. Distribution runs through Chicago bulk terminals for liquid sweeteners and Pacific Northwest cold-chain logistics for temperature-sensitive enzymes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Ingredients Market functions as a regulatory compounder where FDA's GRAS notification modernization and FSMA traceability mandates continuously revalue supplier relationships toward compliance-capable incumbents.
For Market Incumbents: Cement defensible positioning by embedding blockchain-enabled lot tracking ahead of mandatory FSMA implementation, and acquire precision fermentation capabilities before venture-backed biotech firms scale commercial volumes. Substitute technology from synthetic biology startups threatens commodity protein margins; backward integration into enzyme production and captive organic grain origination serve as critical levers. For New Entrants and Emerging Players: Enter via white-space gaps in California's food-tech corridor demand for clean-label emulsifiers with sub-24-month qualification timelines, and target underutilized Midwest specialty maltodextrin capacity serving reformulating bakery manufacturers. The most penetrable segment sits at the intersection of natural preservative alternatives and neutral-pH beverage stability. A technical service subscription model bundling sensory testing with regulatory filing support offers the strongest go-to-market angle against established spot-purchase relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier suppliers face disproportionate compliance investment curves relative to revenue bases under evolving state chemical disclosure rules. Long-term viability favors fermentation specialists with platform biology IP and grain-origin processors with locked origination networks. The acquisition target archetype combines precision fermentation assets with existing GRAS determination portfolios. Watch FDA novel ingredient approval velocity as the critical inflection signal for biotechnology valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Buildout | Enables animal-free whey production with identical functional properties to dairy-derived equivalents. |
| Backward Integration into Organic Grain Origination | Locks supply security for clean-label maltodextrin and modified starch production serving reformulation demand. |
| Blockchain-Enabled Lot Tracking Implementation | Creates service revenue streams under FSMA traceability mandates for mid-sized beverage manufacturers. |
| Technical Service Subscription Launch | Bundles ingredient supply with sensory testing and regulatory filing support in compressed reformulation cycles. |
| Joint Venture with California Food-Tech Labs | Accelerates commercial adoption timelines for novel natural colorants and emulsifier systems. |
Research Methodology
Direct dialogue with ingredient procurement directors at major food manufacturers, fermentation R&D leads at biotechnology firms, regulatory affairs specialists navigating FDA GRAS submissions, and broadline distribution category managers grounded the qualitative foundation. Secondary validation drew from FDA GRAS notification databases, USDA organic certification records, SEC 10-K filings of publicly traded agribusinesses, and customs trade data on natural colorant imports. Bottom-up volume modeling across product type, application, and form factor segments triangulated against top-down market sizing from processor capacity assessments.
Segment-level value outputs derived from pricing stratification across premium fermentation-derived, standard plant-based, and economy synthetic tiers, with growth trajectories modeled over the projection horizon through 2035. The analytical framework incorporated sweetener, emulsifier, colorant, and preservative categories crossed with beverage, bakery, dairy, and snack applications. CAGRs emerged from regression against corn and soybean price volatility indices, clean-label reformulation cycle compression rates, and precision fermentation commercialization curves.
Inputs from FDA GRAS notification filings and state-level chemical disclosure rulemakings were available through the study window; gaps in private biotechnology firm production capacity data introduce uncertainty bands around fermentation-derived protein adoption velocity. Forecasts reflect assumptions on regulatory enforcement intensity and grain price mean-reversion patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Germany Protein Market
Ingredients
Mung Bean Protein Market
Ingredients
Africa Fats and Oil Market
Ingredients
Bean Flour Market
Ingredients
South America Clean Ingredients Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Asia-Pacific Plant Protein Ingredients Market
Ingredients
Europe Phytosterols Market
Ingredients
USA Yeast Extracts Market
Ingredients
Ahiflower Oil Market
Ingredients
Sodium Caseinate Market
Ingredients
Icing Shortening Market
Ingredients
Hydrolyzed Starch Market
Ingredients
Bouillon Market
Ingredients
Native Starch Market
Ingredients
India Gelatin Market