
 Lupine Peptides Market | 2026-2036
Lupine Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Lupine Peptides Market Foresight
Specialty ingredient distribution is rewriting access patterns for lupine peptide suppliers across European cosmetic and nutrition channels. Roquette Frères leverages its extensive plant protein infrastructure to sustain bulk supply contracts with formulators in France and Belgium. Prolupin GmbH anchors its position through dedicated lupine breeding programs and controlled extraction capabilities. Ceapro Inc. differentiates by integrating proprietary pressurized gas extraction technology that preserves peptide bioactivity.
Lupine peptides comprise short-chain amino acid sequences derived from Lupinus species protein hydrolysis, typically containing 2-20 residues with molecular weights below 10 kDa, and function primarily as functional actives in anti-aging cosmeceuticals and high-protein nutrition systems. Hydrolysates dominate current volume due to established enzymatic processing infrastructure and broader formulation compatibility across skincare and nutraceutical matrices. Isolates command premium positioning in pharmaceutical-grade applications where defined peptide fractions must meet stringent batch consistency requirements. Nutritional Supplements and Cosmetics represent the twin demand poles, with the former driven by sports nutrition fortification and the latter by clinically substantiated collagen-boosting claims.
EMA cosmetic ingredient guidelines, REACH substance registration protocols, and EFSA novel food assessments collectively govern market access and product positioning for lupine peptide suppliers serving European buyers. These frameworks elevate compliance costs for entrants while rewarding incumbent operators with documented safety dossiers and established regulatory relationships. Stakeholders must track evolving EFSA opinions on protein hydrolysate allergenicity thresholds and anticipate how forthcoming CSRD disclosure requirements will reshape supply chain transparency expectations from downstream cosmetic and food manufacturers.
Market Dynamics
REACH compliance in the European Union is tightening purity thresholds for plant-based peptide imports, forcing suppliers to reconfigure extraction protocols and batch documentation systems to maintain market access.
Growth Catalysts
- Collagen-boosting cosmeceutical demand:Cosmetic formulators in France and Germany are accelerating procurement of lupine-derived actives for anti-aging skincare, creating sustained volume pull through specialty ingredient channels.
- EFSA novel food pathway maturation:Clarified protein hydrolysate assessment frameworks are reducing regulatory uncertainty for nutritional supplement applications, enabling faster product launches across European markets.
- Enzymatic processing infrastructure:Established bioreactor networks in Germany's active ingredient manufacturing corridor are lowering unit economics for hydrolysate production at commercial scale.
Market Restraints
- Lupin allergenicity classification:EFSA-maintained thresholds for protein hydrolysate allergenicity create labeling burdens and limit formulation flexibility in food-grade applications.
- Single-crop dependency:European lupine cultivation concentrates in Germany and France, exposing supply continuity to regional weather volatility and crop rotation constraints.
- Synthetic peptide substitution:Laboratory-produced collagen peptides from fermentation platforms compete on batch consistency and molecular definition for premium cosmetic positioning.
Strategic Opportunities
- Sports nutrition fortification:Untapped demand for plant-derived protein hydrolysates in Germany's athletic recovery segment offers white-space expansion beyond cosmetic channels.
- CSRD-aligned supply chain transparency:Forthcoming corporate sustainability reporting requirements will reward suppliers with documented regenerative agriculture partnerships and carbon-accounted extraction processes.
- Pressurized gas extraction convergence:Integration of supercritical CO2 systems with enzymatic hydrolysis is enabling pharmaceutical-grade isolate production with preserved bioactivity profiles.
Industry Challenges
- Peptide characterization expertise:Shortage of analytical chemists proficient in mass spectrometry-based sequence verification is extending R&D timelines for defined-fraction products.
- Multi-jurisdiction dossier compilation:Simultaneous EMA cosmetic ingredient, REACH substance registration, and EFSA novel food assessments demand specialized regulatory affairs capacity that mid-scale suppliers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lupine Peptides Market |
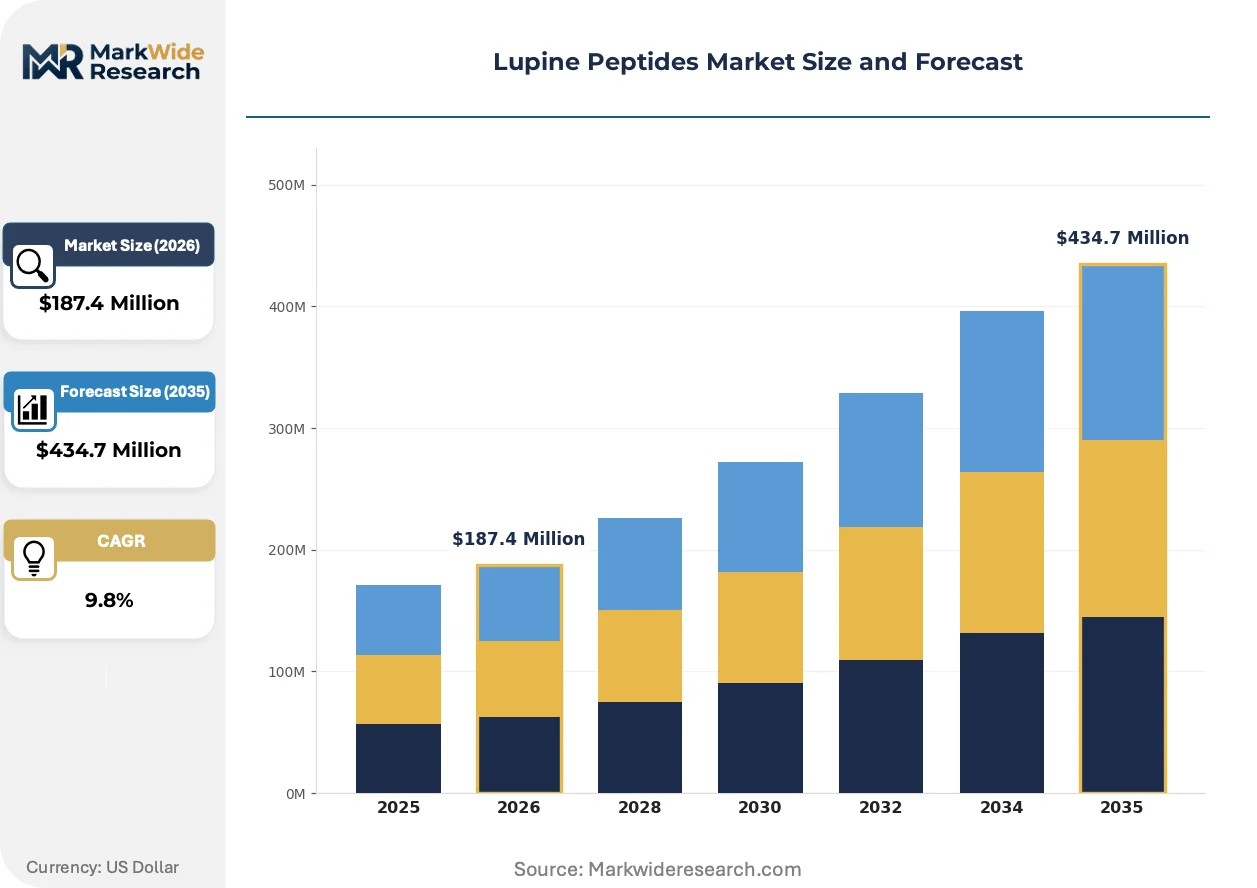
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolysates, Isolates, Concentrates, Powders Application: Food & Beverages, Nutritional Supplements, Cosmetics, Animal Feed End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Health Enthusiasts Distribution Channel: Online Retail, Supermarkets, Health Stores, B2B Sales |
| Companies Covered | Roquette Frères, Cargill Incorporated, Lupina, Ceapro Inc., Celsie Limited, Austrade Inc., Lup'ingredients, Prolupin GmbH, Sotexpro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lupine Peptides Market Shifts & Advancements
Computational protein design and precision fermentation are converging with traditional plant extraction, creating hybrid production architectures that redefine competitive boundaries between natural and biotechnology-derived peptide suppliers.
Supercritical fluid extraction technology is virtualizing conventional solvent-based peptide recovery. Cosmetic formulators in France are adopting pressurized CO2 systems at pilot scale to preserve heat-labile bioactive fractions. This virtualization is compressing yield gaps between artisanal batch processing and industrial throughput while elevating premium positioning for cold-processed isolates.
REACH substance registration protocols are tightening documentary requirements for plant-derived biopolymers imported into the European Union. ECHA's expanded data demands on ecotoxicity and biodegradation are extending pre-market preparation timelines by 12-18 months for non-incumbent suppliers. German contract manufacturers are responding by consolidating supplier relationships with dossier-complete incumbents rather than qualifying new entrants.
Direct procurement from extraction technology owners is displacing traditional specialty chemical distribution for high-volume cosmetic peptide buyers. Large French skincare houses are establishing captive supply agreements with German toll manufacturers equipped with in-house analytical capabilities. This channel compression is most visible in the anti-aging serum segment, where defined peptide fractions command specification-driven purchasing rather than catalog-based ordering.
Lupine Peptides Market Segmentation
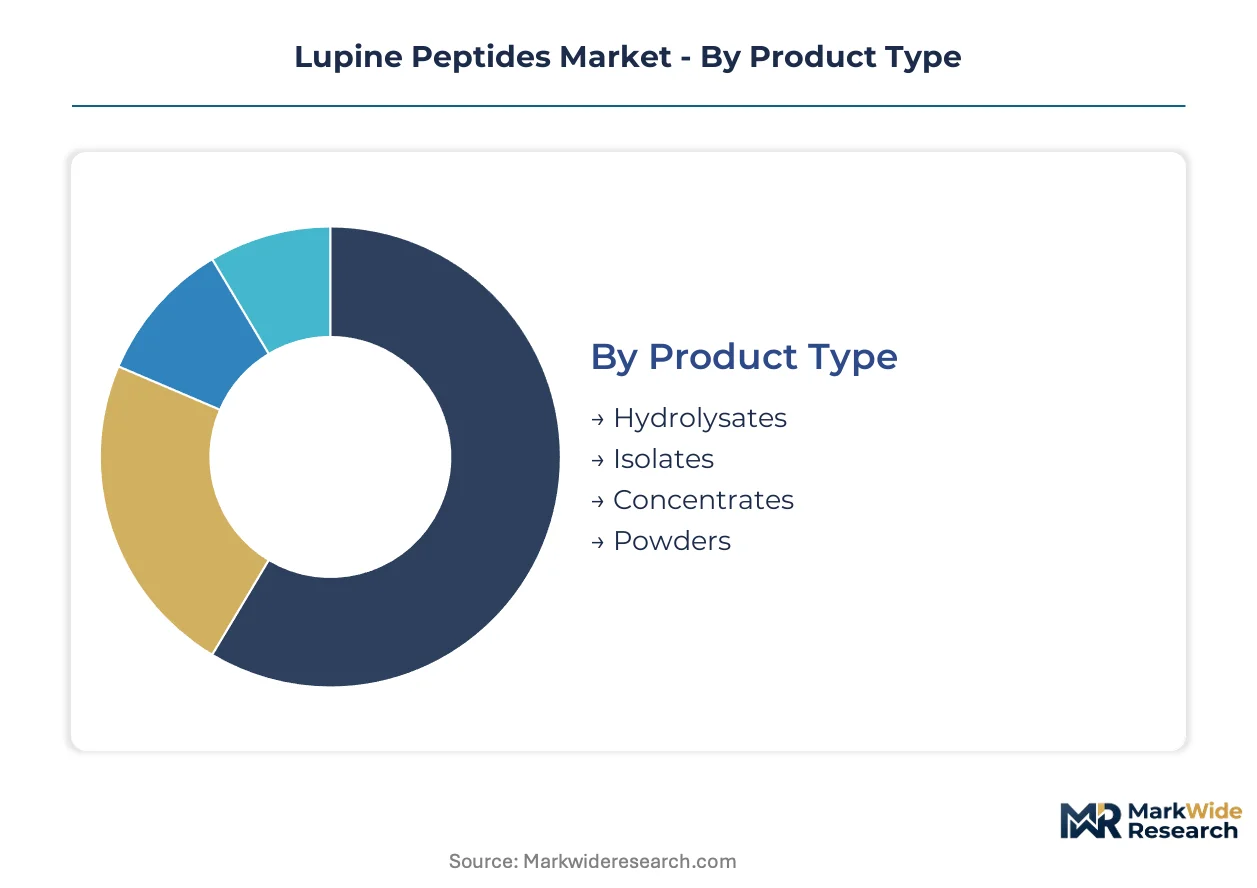
Peptide molecular configuration and downstream formulation requirements create distinct value tiers across extraction technologies. Application-specific regulatory pathways in Europe further stratify procurement patterns between food-grade hydrolysates and pharmaceutical-grade isolates.
Product Type:
Use-case spectrum spans bulk nutritional fortification to precision cosmetic actives, with extraction methodology determining purity thresholds and price positioning.
- Hydrolysates:Enzymatically cleaved protein fragments containing 2-20 amino acid residues with molecular weights below 10 kDa. Demand concentrates in Germany's sports nutrition manufacturing corridor, where established bioreactor networks lower unit economics for high-volume fortification applications.
- Isolates:Defined peptide fractions meeting pharmaceutical-grade batch consistency requirements through controlled chromatographic separation. French cosmetic formulators in the anti-aging serum segment drive premium procurement, requiring documented bioactivity preservation and REACH-compliant purity dossiers.
- Concentrates:Intermediate protein fractions with standardized peptide content serving animal feed fortification and mid-tier nutraceutical applications.
- Powders:Spray-dried formats optimized for shelf stability and dry-blend compatibility across bakery and powdered beverage matrices.
Established volume favors Hydrolysates; emerging adoption favors Isolates.
Application:
Margin structure varies sharply across regulatory complexity tiers, with cosmetic and nutritional pathways demanding divergent safety documentation investments.
- Cosmetics:Collagen-boosting cosmeceutical formulations in France and Germany require EMA cosmetic ingredient compliance and clinically substantiated bioactivity claims. REACH substance registration protocols extend pre-market timelines but reward dossier-complete suppliers with preferred vendor status.
- Nutritional Supplements:Sports recovery and protein fortification applications leverage EFSA novel food pathway maturation to accelerate European market entry. German contract manufacturers consolidate procurement with extraction technology owners rather than traditional distributors.
- Food & Beverages:Bakery, dairy, and beverage fortification facing EFSA allergenicity labeling thresholds that constrain formulation flexibility.
- Animal Feed:Aquaculture and livestock protein supplementation with lower purity requirements but volume-driven pricing pressure.
Cosmetics commands premium pricing; Nutritional Supplements offers steepest expansion trajectory.
End User:
Customer technical sophistication determines specification stringency and supplier relationship depth across the procurement spectrum.
- Cosmetic Brands:Large French skincare houses establish captive supply agreements with German toll manufacturers, compressing traditional distribution channels through direct analytical capability requirements.
- Pharmaceutical Companies:Defined-fraction peptide demand for therapeutic and clinical nutrition applications with mass spectrometry-based sequence verification requirements.
- Food Manufacturers:Industrial-scale hydrolysate procurement for processed food fortification prioritizing batch scale and cost efficiency.
- Health Enthusiasts:Direct-to-consumer peptide supplementation through online channels with label-claim transparency expectations.
Cosmetic Brands drive specification innovation; Pharmaceutical Companies represent emerging high-margin demand.
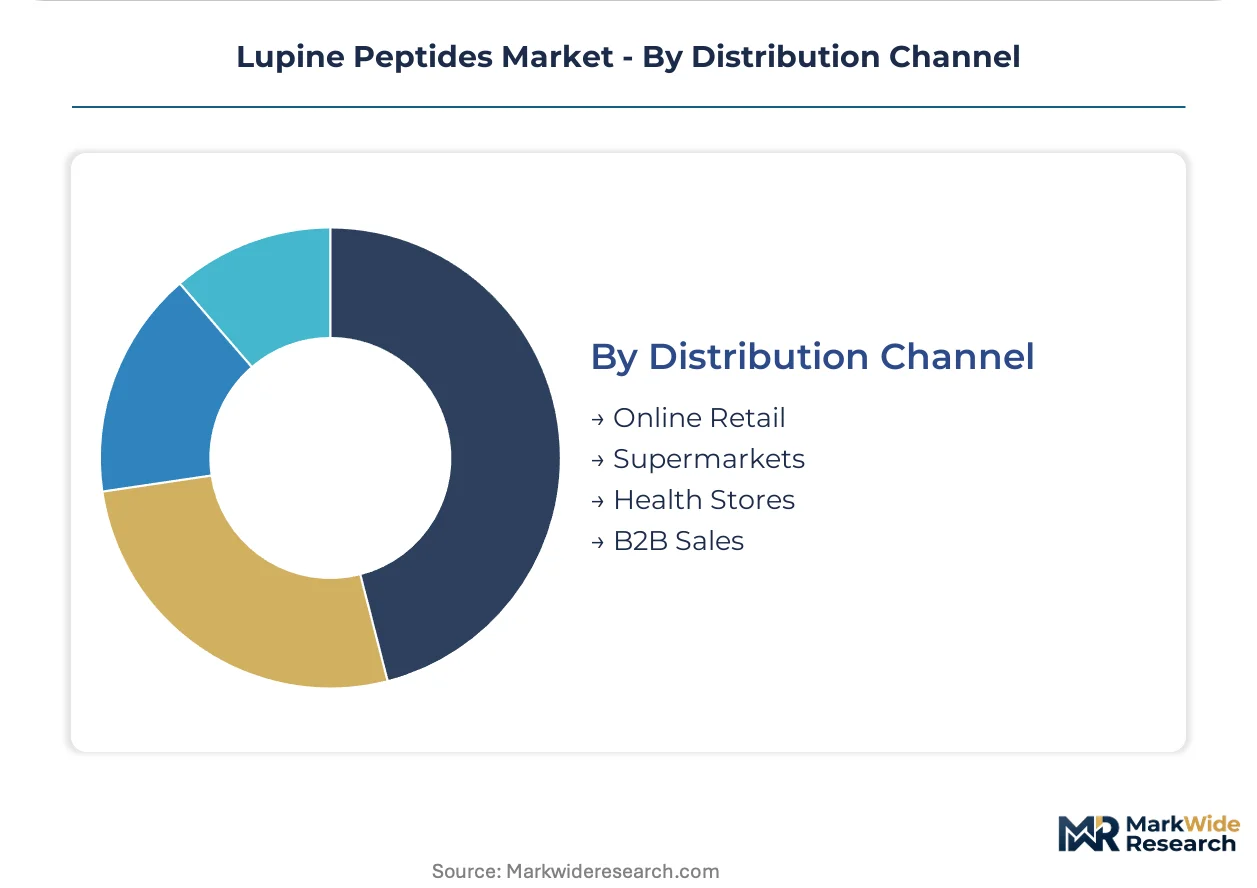
Distribution Channel:
Channel economics reflect order scale, technical service requirements, and regulatory documentation bundling.
- B2B Sales:Direct procurement from extraction technology owners displaces specialty chemical distribution for high-volume buyers, with German contract manufacturers consolidating supplier relationships around dossier-complete incumbents.
- Online Retail:E-commerce platforms serving health enthusiasts and small cosmetic formulators with lower minimum order quantities but higher customer acquisition costs.
- Health Stores:Brick-and-mortar specialty retail for premium nutritional supplement positioning with educated staff requirements.
- Supermarkets:Mass-market food and beverage peptide products with private-label concentration and price-driven procurement.
B2B Sales anchors industrial volume; Online Retail gains share fastest in fragmented demand segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA novel food pathway maturation is accelerating European market entry timelines for lupine peptide suppliers. REACH substance registration protocols are extending pre-market preparation windows for non-incumbent suppliers entering EU cosmetic and nutrition channels. Procurement consolidation around dossier-complete operators is reshaping competitive access across key demand centers.
Germany
Sports nutrition fortification and active ingredient manufacturing anchor peptide hydrolysate demand in Germany's industrial corridor. ECHA's expanded REACH data demands on ecotoxicity and biodegradation are extending preparation timelines for imported biopolymers. The Baden-Württemberg and North Rhine-Westphalia clusters concentrate enzymatic bioreactor capacity serving contract manufacturers.
France
Anti-aging cosmeceutical procurement from large skincare houses drives premium isolate demand through direct toll manufacturing agreements. ANSM cosmetic ingredient guidelines and EMA compliance frameworks elevate documentation requirements for bioactive peptide suppliers. The Île-de-France region hosts formulation R&D centers establishing captive supply relationships with extraction technology owners.
Belgium
Specialty ingredient distribution hubs and plant protein processing infrastructure position Belgium as a transit point for bulk hydrolysate flows. EU Green Deal sustainability reporting requirements are elevating supply chain transparency expectations from downstream manufacturers. The Flanders region concentrates toll manufacturing capacity for cosmetic peptide refinement.
Netherlands
Food-grade hydrolysate applications in bakery and beverage fortification leverage Rotterdam's logistics infrastructure for raw material import. CSRD disclosure requirements are pressuring mid-scale suppliers to document regenerative agriculture partnerships and carbon-accounted extraction processes. The Randstad area hosts ingredient trading operations consolidating procurement for Northern European food manufacturers.
Switzerland
Pharmaceutical-grade peptide demand for clinical nutrition and therapeutic applications emphasizes batch consistency and mass spectrometry-based sequence verification. Swissmedic therapeutic product regulations and EU alignment protocols create dual compliance pathways for precision isolates. The Basel region anchors pharmaceutical peptide sourcing relationships with defined-fraction suppliers.
Lupine Peptides Market Competitive Landscape
On the supply side, the industry is consolidating around extraction technology owners with documented regulatory dossiers and established bioreactor networks. Mid-scale suppliers face capability gaps in multi-jurisdiction compliance staffing while incumbent operators deepen preferred vendor relationships with high-volume buyers. Three archetypes dominate: integrated plant protein processors with captive raw material access, specialized toll manufacturers with analytical verification capabilities, and precision extraction technology licensors. Competitive moves center on direct procurement compression eliminating traditional distribution layers and strategic partnerships aligning regenerative agriculture sourcing with forthcoming CSRD transparency mandates.
Among European-integrated processors, Roquette Frères and Prolupin GmbH exemplify the raw-material-anchored archetype, leveraging dedicated breeding programs and controlled cultivation to secure supply continuity. Ceapro Inc. occupies a position within the technology-differentiated tier, representing pressurized gas extraction capabilities that preserve peptide bioactivity for pharmaceutical-grade applications. These three operators illustrate how competitive positioning increasingly depends on regulatory dossier completeness and documented sustainability partnerships rather than scale alone.
| Leading Market Players |
|---|
| Roquette Frères |
| Cargill Incorporated |
| Lupina |
| Ceapro Inc. |
| Celsie Limited |
| Austrade Inc. |
| Lup'ingredients |
| Prolupin GmbH |
| Sotexpro |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's enzymatic bioreactor cluster concentrates extraction capacity for lupine peptide hydrolysates, granting German toll manufacturers outsized leverage in contract negotiations with French cosmetic formulators seeking REACH-compliant isolates. This geographic concentration compresses margin capture for mid-scale suppliers while rewarding incumbent operators with documented regulatory dossiers and preferred vendor status.
Pricing Analysis
Certification level creates the primary spread across lupine peptide tiers, with pharmaceutical-grade isolates commanding substantial premiums over food-grade hydrolysates due to EMA cosmetic ingredient compliance and mass spectrometry-based sequence verification requirements. Three-tier pricing structure across premium, standard, and economy levels reflects batch consistency thresholds, with cosmetic brands in France showing least price sensitivity and animal feed manufacturers most responsive to volume discounts. Cost compression in standard-grade hydrolysates is intensifying because German contract manufacturers are consolidating procurement around dossier-complete incumbents rather than qualifying new entrants.
Supply Chain Analysis
EU dual-use export controls on pressurized gas extraction technology limit transfer of supercritical CO2 systems to non-affiliated processors, constraining capacity expansion outside established European networks. Supply concentrates in Germany, France, and Belgium, with raw material flows drawing from dedicated lupine breeding programs and controlled cultivation partnerships. Single-crop dependency on German and French agricultural output creates vulnerability to regional weather volatility and crop rotation constraints. Distribution runs through direct B2B procurement channels that displace traditional specialty chemical distribution for high-volume cosmetic peptide buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lupine peptide demand tracks the cyclical recovery in European sports nutrition and anti-aging cosmeceutical consumption, with EFSA novel food pathway maturation serving as the primary cyclical accelerator normalizing regulatory timelines.
For Market Incumbents: Harden regulatory dossier completeness against REACH substance registration protocol expansions by investing in ECHA-aligned ecotoxicity documentation and biodegradation assessments. Deepen captive supply relationships with French skincare houses through integrated pressurized gas extraction capabilities that preserve peptide bioactivity for premium isolate positioning.
For New Entrants and Emerging Players: Mid-market nutritional supplement applications in Germany's athletic recovery segment represent the most penetrable entry point, given established bioreactor infrastructure and clarified EFSA protein hydrolysate assessment frameworks. Sports nutrition fortification offers white-space expansion beyond saturated cosmetic channels, with private-label partnerships serving as the optimal go-to-market mechanism for volume scale.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because multi-jurisdiction dossier compilation demands specialized capacity that mid-scale suppliers struggle to staff, creating consolidation opportunities around EMA, REACH, and EFSA-aligned operators. Target extraction technology owners with documented regenerative agriculture partnerships and carbon-accounted processes ahead of CSRD disclosure requirements. The signal to watch is EFSA opinions on protein hydrolysate allergenicity thresholds that could reshape labeling burdens and formulation flexibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Controlled lupine breeding programs in Germany secure supply continuity against weather volatility. |
| Pressurized Gas Extraction Scale-Up | Supercritical CO2 deployment preserves bioactivity for pharmaceutical-grade isolate production. |
| REACH Dossier Expansion | ECHA-aligned ecotoxicity documentation extends preferred vendor status with cosmetic formulators. |
| CSRD-Aligned Partnerships | Regenerative agriculture documentation meets forthcoming supply chain transparency mandates. |
| Direct Procurement Compression | Captive supply agreements with French skincare houses eliminate traditional distribution layers. |
Research Methodology
Operator-level perspectives from extraction technology licensors, enzymatic bioreactor operators, cosmetic formulation R&D directors, and specialty ingredient procurement managers anchored the qualitative base. Primary fieldwork combined with secondary validation from EFSA novel food assessments, ECHA REACH registration databases, and EU customs trade flows. Bottom-up volume modeling across hydrolysate and isolate product tiers triangulated against top-down market sizing from plant protein processing capacity disclosures.
Scenario-bracketing around regulatory timeline variations and crop yield volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include peptide molecular configuration, application regulatory pathway, end-user technical sophistication, and distribution channel structure. CAGRs derived from installed bioreactor capacity expansion rates, EFSA approval velocity assumptions, and cosmetic peptide incorporation trends in anti-aging formulations.
Macroeconomic conditions sit as an overlay; deviation in European consumer discretionary spending on premium skincare and sports nutrition would shift the trajectory. Forecasts reflect assumptions on EMA cosmetic ingredient guideline stability and EFSA allergenicity threshold maintenance. Material shifts in REACH substance registration protocol stringency or lupin allergenicity reclassification would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Casein and Caseinates Market
Ingredients
Horny Goat Weed Extract Market
Ingredients
Chickpea Fiber Market
Ingredients
Dried Beet Pulp Market
Ingredients
Cheese Ripening Enzymes Market
Ingredients
Dry Blended Products Market
Ingredients
Food Amino Acids Market
Ingredients
Mung Bean Protein Market
Ingredients
Cheese Cultures Market
Ingredients
Plant Extracts Market
Ingredients
Global Dietary Fibers Market
Ingredients
Oat Grass Powder Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
PDO/PGI-Linked Mediterranean Ingredient Collections Market
Ingredients
Europe Dairy Ingredients Market