
 Global Distillers Grains Market | 2026-2036
Global Distillers Grains Market Size, Share, and Industry Trends Forecast 2026-2036
Global Distillers Grains Market Analysis
Maintenance-linked nutritional advisory services is shifting how distillers grains get sold, bundling feed formulation expertise with commodity delivery. Green Plains Inc. leverages its network of biorefineries to sustain captive supply agreements with large-scale cattle feeders. CropEnergies AG anchors European supply through its Wanze facility, competing on proximity to Benelux livestock operations. Archer Daniels Midland Company dominates origination logistics, extending its advantage in containerized export channels.
Distillers grains are the nutrient-rich co-products remaining after starch fermentation for ethanol production, typically containing 27-30% crude protein, 7-10% fat, and variable fiber content depending on the source grain and drying process. These materials serve primarily as protein and energy supplements in animal feed rations, displacing higher-cost oilseed meals in dairy, beef, and swine diets. DDGS from corn sources leads volume globally, while wheat-based distillers grains command premium positioning in European aquaculture and poultry formulations where mycotoxin specifications tighten. Pellet form captures the fastest growth trajectory, driven by mechanized feeding systems in concentrated animal feeding operations and reduced dust handling losses during ocean freight.
The EPA enforces Renewable Fuel Standard blending mandates that directly determine U.S. ethanol plant operating rates and thus distillers grains supply volumes, while the FDA's BSE feed rule governs ruminant protein restrictions that shape permissible end-use applications. EFSA and EU Green Deal sustainability criteria are tightening import specifications for non-EU distillers grains entering European feed channels, pressuring suppliers on carbon intensity documentation and mycotoxin thresholds. Stakeholders must monitor how evolving biofuel policy in Washington and Brussels recalibrates the co-product economics that underpin this market's supply foundation.
Market Dynamics
The EPA's Renewable Fuel Standard mandates directly tether distillers grains supply to ethanol blending volumes, creating a co-product market structurally dependent on biofuel policy rather than feed demand alone. This regulatory anchoring forces livestock nutritionists to optimize around variable DDGS availability rather than static formulation protocols.
Growth Catalysts
- Ethanol mandate compliance:The EPA's annual renewable volume obligations sustain baseline operating rates at U.S. dry-mill facilities, guaranteeing DDGS output regardless of feed commodity price cycles.
- Protein displacement economics:Dairy operations in Wisconsin and California are reformulating rations to maximize DDGS inclusion when soybean meal basis widens at Gulf export terminals.
- Pellet technology maturation:Pelleting systems originally developed for aquaculture feed are crossing into beef and swine channels, reducing handling losses at export elevators.
Market Restraints
- Corn price volatility:Input cost swings at Midwest grain elevators compress ethanol plant margins, forcing production curtailments that abruptly constrict DDGS supply to contracted feedlots.
- Single-region supply concentration:Iowa, Nebraska, and Illinois facilities generate the majority of exportable volume, exposing buyers to localized weather disruptions and rail logistics bottlenecks.
- Moisture specification limits:Ocean freight insurers and destination port authorities enforce strict moisture ceilings that disqualify wet distillers grains from trans-Pacific container routes.
Strategic Opportunities
- Vietnam aquaculture penetration:Mekong Delta shrimp and pangasius producers are trialing wheat-based DDGS from European originators as fishmeal prices escalate.
- Carbon intensity scoring:The EU Green Deal's feed sustainability criteria reward lower-carbon DDGS with preferential import quotas, advantaging producers with documented supply chain emissions data.
- Digital nutrition platforms:Real-time ration optimization software is integrating DDGS pricing feeds, enabling automated substitution decisions at integrated cattle feeding operations.
Industry Challenges
- Mycotoxin testing capacity:Elevated aflatoxin and vomitoxin screening requirements at EU border inspection posts are straining laboratory throughput at Rotterdam and Hamburg.
- Legacy silo infrastructure:Older feed mills lack pneumatic handling systems compatible with dusty DDGS, requiring capital retrofit programs that delay adoption.
- Cross-species formulation expertise:Nutritionists trained in monogastric diets lack ruminant fiber management skills needed to optimize DDGS inclusion without acidosis risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Distillers Grains Market |
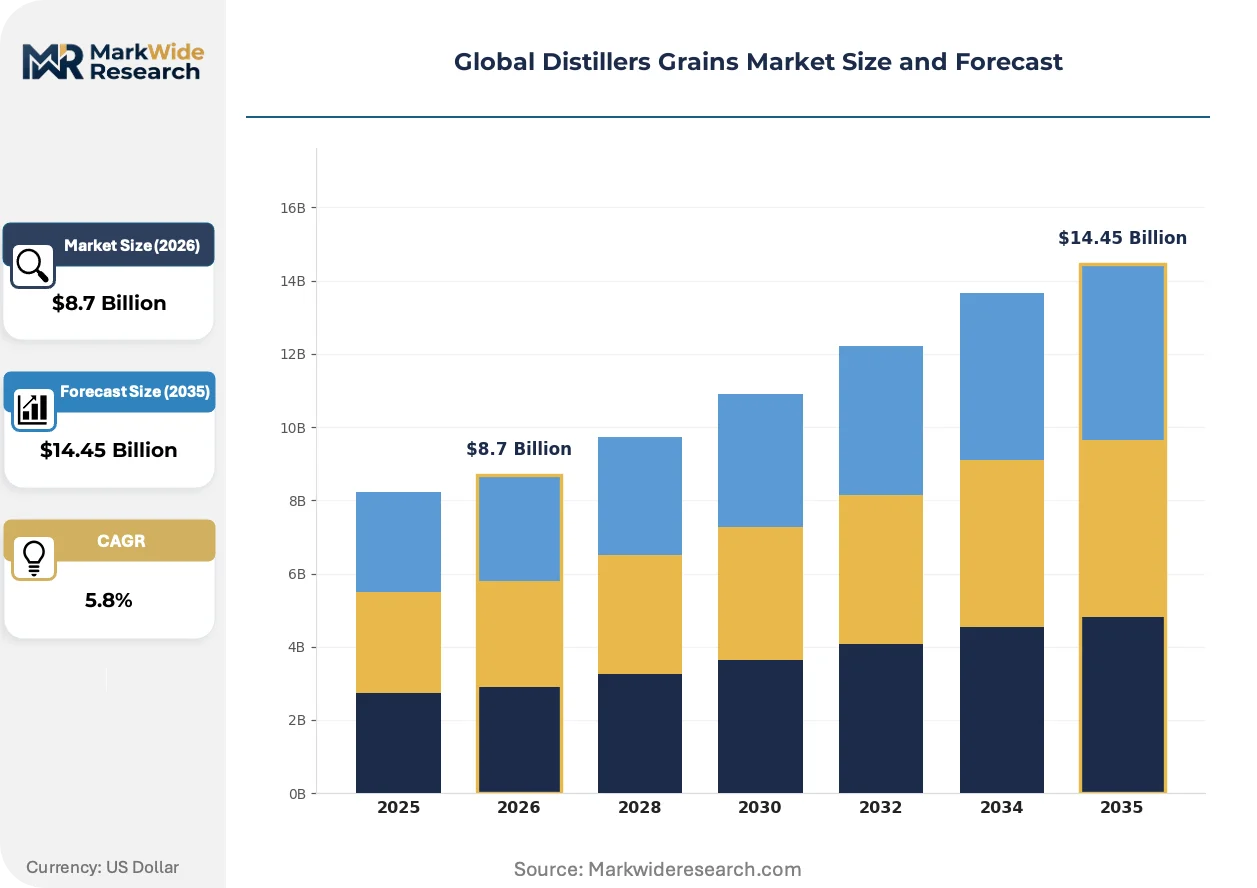
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
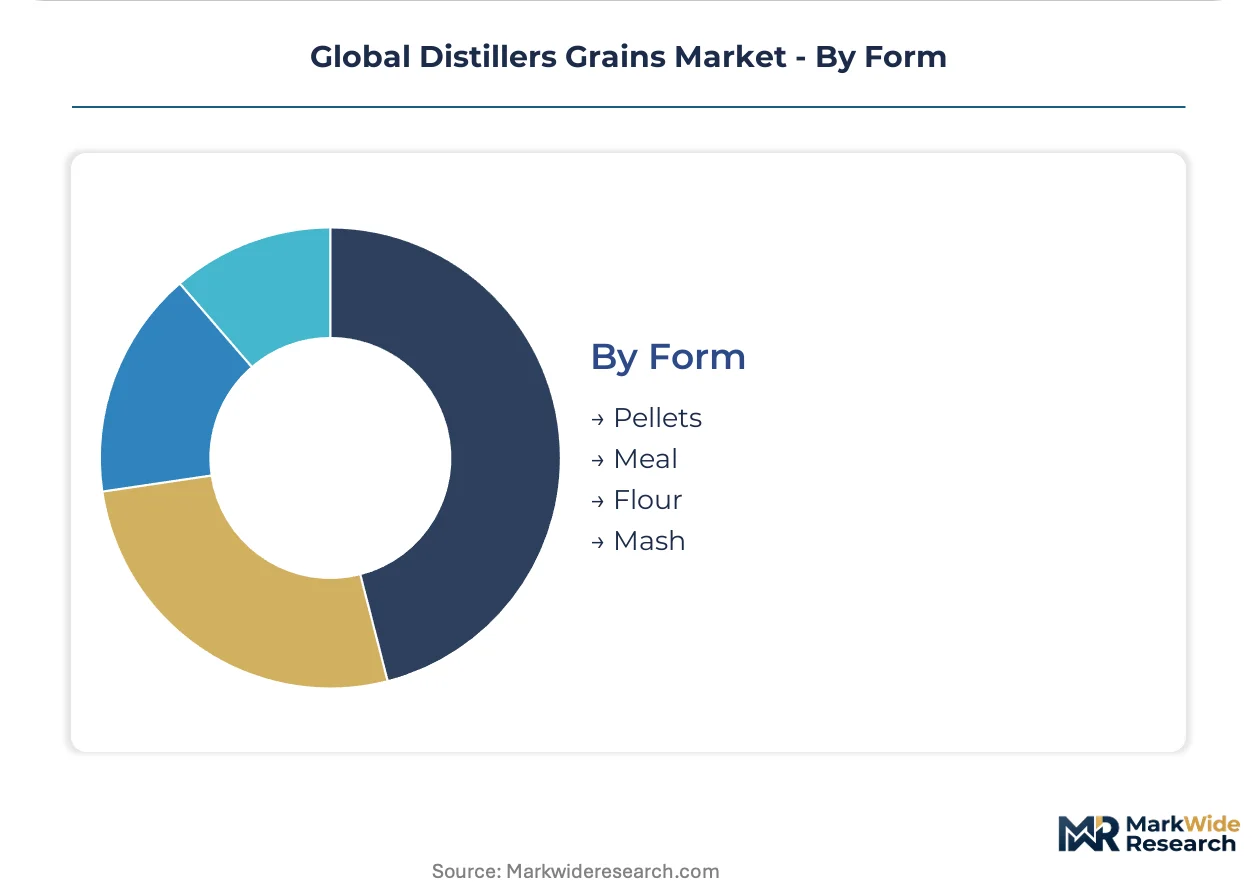
| Segmentation | Product Type: DDGS, WDGS, CDGS, SGG End User: Animal Feed, Biofuels, Food & Beverage, Fertilizers Source: Corn, Wheat, Barley, Sorghum Form: Pellets, Meal, Flour, Mash |
| Companies Covered | Green Plains Inc., CropEnergies AG, Archer Daniels Midland Company, Pacific Ethanol, Bunge Limited, Valero Energy Corporation, Flint Hills Resources, CHS Inc., Poet LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Distillers Grains Market Emerging Trajectories
Processing technology advances and regulatory recalibration are compressing the traditional separation between ethanol co-product handling and precision animal nutrition. These forces are redrawing competitive boundaries between commodity processors and formulated feed suppliers.
Fractionation technology is separating DDGS into protein concentrate and fiber streams for species-specific applications. Swine nutritionists in Denmark and the Netherlands are adopting these refined ingredients at accelerating rates. This processing advance is expanding into dairy ration formulation, enabling precise amino acid balancing that raw DDGS cannot achieve.
The EU Green Deal's carbon border adjustment mechanism is imposing documentation requirements on imported feed ingredients. European compound feed manufacturers must now certify upstream emissions for DDGS entering their supply chains. Wheat-based originators in Belgium and Germany are responding by investing in supply chain traceability systems that corn-based competitors lack.
Large-scale cattle feeders are consolidating procurement decisions through centralized nutrition teams rather than decentralized commodity buyers. This organizational shift concentrates volume commitments with suppliers offering technical advisory services alongside physical delivery. The practice is most visible in Texas Panhandle feedyards, where captive supply agreements now bundle formulation expertise with long-term price contracts.
Global Distillers Grains Market Segmentation
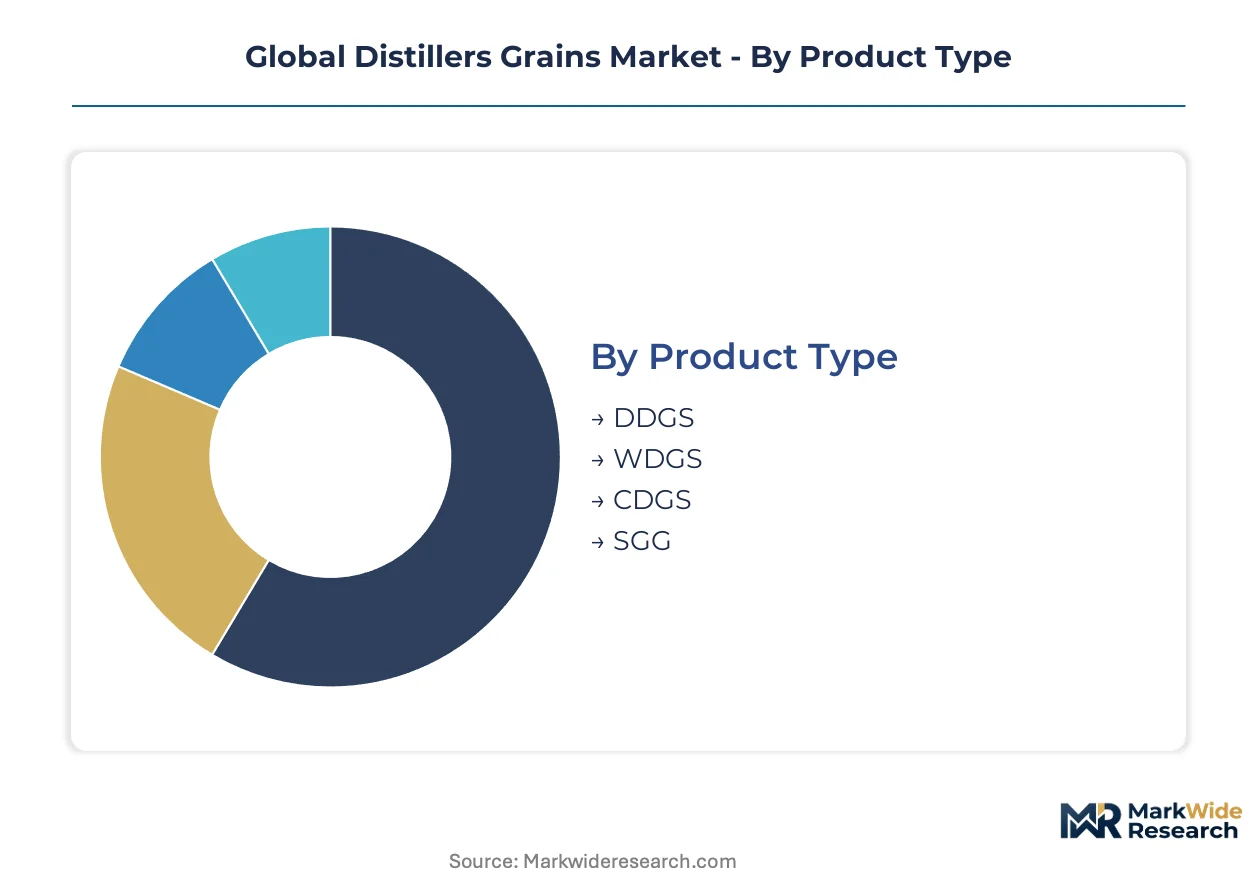
Distillers grains segmentation reflects divergent regulatory burdens across product types and end-use channels. EPA biofuel mandates and FDA feed safety rules create tiered compliance costs that reshape supplier economics and buyer procurement patterns.
Product Type:
EPA Renewable Fuel Standard enforcement and FDA BSE feed regulations impose distinct documentation and handling requirements on each product category.
- DDGS:Dried distillers grains with solubles contain 27-30% crude protein and 10-12% moisture after thermal dehydration. Dairy operations in Wisconsin and California maximize DDGS inclusion during soybean meal price spikes at Gulf export terminals. DDGS sits at the top of the volume ranking, with WDGS climbing the fastest.
- WDGS:Wet distillers grains with solubles retain 65-70% moisture, limiting transport radius to 150 miles from ethanol facilities. Texas Panhandle feedyards source WDGS through captive supply agreements with adjacent biorefineries to minimize spoilage losses.
- CDGS:Condensed distillers solubles offer concentrated protein and fat fractions for liquid feed supplementation in Midwest dairy operations.
- SGG:Syrup-grain blends command niche positioning in ruminant finishing rations requiring palatability enhancement.
Moisture specification ceilings enforced by ocean freight insurers disqualify WDGS from trans-Pacific routes, compressing its addressable market.
End User:
Customer procurement sophistication varies sharply, with integrated cattle feeders demanding bundled nutrition advisory services while fertilizer buyers prioritize commodity pricing.
- Animal Feed:Ruminant, swine, poultry, and aquaculture channels consume the majority of distillers grains volume. EFSA mycotoxin thresholds and EU Green Deal carbon intensity documentation requirements filter non-EU suppliers from European compound feed formulations. Animal Feed dominates absolute consumption, with Biofuels gaining share fastest.
- Biofuels:Anaerobic digestion facilities convert residual organic matter into biogas, creating circular energy recovery pathways at integrated ethanol-biogas plants.
- Food & Beverage:Human-grade protein extraction applications remain constrained by FDA GRAS certification timelines and limited processing infrastructure.
- Fertilizers:Agricultural runoff regulations in Iowa and Illinois restrict land application rates for nutrient-heavy stillage byproducts.
Feed channel concentration in the US Corn Belt contrasts with fertilizer demand dispersal across Midwest grain-growing counties.
Source:
Grain origin determines protein content, fiber profile, and mycotoxin risk, shaping end-use suitability and regional supply patterns.
- Corn:Yellow corn DDGS delivers consistent 27-30% protein and 7-10% fat, anchoring global trade flows from Iowa, Nebraska, and Illinois ethanol clusters. Corn-based supply concentrates near Midwest rail terminals serving Gulf and Pacific Northwest export elevators.
- Wheat:European wheat DDGS commands premium positioning in Benelux aquaculture and poultry formulations where EFSA aflatoxin specifications tighten. Wheat-based originators invest in supply chain traceability systems to satisfy EU Green Deal carbon border documentation.
- Barley:Scottish and Canadian malt whisky distilleries generate specialized barley DDGS for regional livestock markets.
- Sorghum:Texas and Kansas sorghum ethanol facilities serve localized cattle feeding operations with distinct amino acid profiles.
Corn anchors global volume, with wheat expanding most quickly in European premium feed channels.
Form:
Physical processing state dictates handling infrastructure requirements, dust management protocols, and ocean freight economics.
- Pellets:Densified DDGS pellets reduce dust losses during containerized export and enable mechanized feeding system integration. Texas Panhandle feedyards and Vietnam aquaculture operations adopt pellets to minimize handling labor and improve flow characteristics in pneumatic delivery systems. Pellets represent the steepest expansion trajectory among physical forms.
- Meal:Standard ground DDGS requires dust suppression systems and enclosed storage silos compatible with pneumatic handling infrastructure.
- Flour:Fine-milled fractions serve specialized aquaculture and pet food applications requiring particle size uniformity.
- Mash:Unprocessed wet grains limit distribution radius but minimize drying energy costs for localized ruminant operations.
Pellet technology maturation is compressing price premiums as scale economies emerge across Midwest pelleting facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's ethanol policy pivots reshape distillers grains trade flows, while the United States sustains co-product export dominance through Renewable Fuel Standard enforcement. Regulatory divergence between Washington and Brussels creates tiered compliance costs for cross-border suppliers.
United States
Iowa and Nebraska ethanol clusters supply DDGS to Texas Panhandle feedyards through captive rail agreements. The EPA's annual renewable volume obligations sustain baseline plant operating rates regardless of feed commodity cycles. Green Plains Inc. leverages its biorefinery network to bundle nutrition advisory services with physical delivery.
Germany
Wheat-based DDGS from CropEnergies AG's Wanze facility commands premium positioning in Benelux aquaculture formulations. The EU Green Deal's carbon border adjustment mechanism imposes documentation requirements on imported feed ingredients. Belgian compound feed manufacturers prioritize European-origin supply with verified supply chain emissions data.
China
State ethanol blending mandates determine co-product availability for domestic livestock operations in Shandong and Henan provinces. The country's national biofuel regulator adjusts grain processing quotas based on food security priorities. Yangtze River Delta feed mills integrate DDGS during soybean meal price spikes at Dalian futures terminals.
Brazil
Sugarcane ethanol dominance limits corn-based DDGS scale, though São Paulo state mills serve localized poultry and swine operations. The central biofuel authority maintains flex-fuel blending requirements that indirectly sustain co-product output. Southern Brazil feed compounders trial imported U.S. DDGS during domestic protein meal shortages.
Vietnam
Mekong Delta shrimp and pangasius producers pilot wheat-based DDGS from European originators as fishmeal prices escalate. The national fisheries regulator tightens mycotoxin screening protocols at Ho Chi Minh City port inspection posts. Aquaculture feed mills in Cần Thơ province invest in pelleting infrastructure compatible with mechanized pond delivery systems.
Global Distillers Grains Market Vendor Landscape
Top-tier vendors anchor integrated ethanol-biorefinery operations, while mid-scale regional processors compete on proximity to livestock clusters. The market exhibits tiered concentration with dominant players controlling origination logistics and export elevator capacity. Three archetypes prevail: captive supply integrators, containerized export specialists, and nutrition service bundlers. Capacity expansion and backward integration into grain origination represent the dominant competitive vectors.
Among U.S.-based ethanol operators, Green Plains Inc., Valero Energy Corporation, and Poet LLC exemplify the captive supply integrator archetype, anchoring volume commitments through long-term feeder agreements. CropEnergies AG represents the European premium-positioning model, while Archer Daniels Midland Company occupies the logistics-dominant tier controlling containerized export channels.
| Leading Market Players |
|---|
| Green Plains Inc. |
| CropEnergies AG |
| Archer Daniels Midland Company |
| Pacific Ethanol |
| Bunge Limited |
| Valero Energy Corporation |
| Flint Hills Resources |
| CHS Inc. |
| Poet LLC |
| Others |
Supply Flow & Price Mechanics
Livestock nutritionist consolidation into centralized procurement teams is forcing ethanol facilities to bundle technical advisory services with physical delivery, compressing spot-market premiums and elevating long-term contract structures with embedded formulation support.
Pricing Analysis
Capacity additions in Iowa and Nebraska are reshaping price floors for standard DDGS grades, while wheat-based European originators maintain premium positioning through EFSA mycotoxin certification tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by protein content, moisture specification, and carbon intensity documentation. Pricing pressure stems from soybean meal basis volatility at Gulf export terminals, which accelerates buyer substitution toward DDGS during protein meal spikes. Integrated cattle feeders show lowest price sensitivity due to captive supply agreements, while independent Midwest dairy operations exhibit highest elasticity to spot price swings.
Supply Chain Analysis
EU Green Deal carbon border documentation requirements are gating non-European supply from Rotterdam and Hamburg entry points, advantaging originators with verified supply chain emissions data. Production concentrates in the United States, Belgium, and Germany, with Iowa-Nebraska ethanol clusters feeding Gulf and Pacific Northwest export elevators. The supply chain draws from corn, wheat, and sorghum feedstock streams, with drying energy costs and rail logistics representing major variable components. Single-region concentration in the US Corn Belt exposes buyers to localized weather disruptions and BNSF-UP rail bottlenecks. Distribution runs through captive rail agreements for domestic ruminant operations and containerized ocean freight for Vietnam aquaculture channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA-mandated US ethanol output and EU Green Deal carbon intensity requirements that filter lower-documentation suppliers from premium European feed channels.
For Market Incumbents: Anticipate fractionation technology maturation by investing in protein concentrate separation capabilities before Danish and Dutch swine nutritionists lock in refined ingredient supply contracts. Defend margin position through backward integration into grain origination near Midwest rail terminals, countering the threat of containerized export specialists capturing Vietnam aquaculture volume with pelleting infrastructure investments.
For New Entrants and Emerging Players: Digital nutrition platforms offering real-time DDGS pricing feeds and automated ration optimization represent the most penetrable white-space target, particularly for independent Texas Panhandle feedyards lacking in-house formulation expertise. Target Mekong Delta shrimp producers with wheat-based DDGS trials as fishmeal price escalation accelerates. A go-to-market angle anchored in carbon intensity scoring documentation unlocks EU Green Deal preferential quota access.
For Investors and Strategic Acquirers: Asymmetric upside sits with biorefinery operators possessing integrated pelleting infrastructure and verified supply chain emissions data, as these capabilities become mandatory for EU market participation. Long-term viability rests on regulatory durability of biofuel mandates across Washington and Brussels. The acquisition target archetype is mid-scale ethanol processors with underutilized pelleting capacity and proximity to export elevators. Watch for EPA renewable volume obligation adjustments as the inflection indicator triggering supply recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Fractionation Technology Investment | Protein concentrate separation enables species-specific formulation precision that raw DDGS cannot achieve. |
| Carbon Intensity Documentation Systems | Supply chain traceability investments satisfy EU Green Deal border adjustment requirements for preferential quota access. |
| Pelleting Infrastructure Expansion | Densified form reduces dust losses during Vietnam containerized export and enables mechanized feeding integration. |
| Captive Supply Agreement Structuring | Long-term feeder contracts with embedded nutrition advisory services lock in volume commitments against spot market volatility. |
| Backward Integration into Grain Origination | Upstream control over corn supply secures margin protection against Midwest elevator price swings and rail logistics disruptions. |
Methodological Framework
Direct dialogue with ethanol plant operations managers, livestock nutritionists at integrated feeding operations, compound feed procurement directors, and EU border inspection officials grounded this analysis in operational reality. Secondary validation drew from EPA renewable volume obligation filings, EFSA mycotoxin surveillance reports, USDA grain transportation data, and EU Green Deal implementing regulation texts. Bottom-up capacity modeling across Iowa, Nebraska, and Illinois ethanol facilities triangulated against top-down feed demand projections from Wisconsin and California dairy operations.
Bottom-up segmentation modeling by product type, source grain, physical form, and end-use channel generated volume and value outputs across the projection horizon. Analytical frameworks incorporated protein displacement economics against soybean meal futures, pelleting technology adoption curves, and regulatory compliance cost differentials between EPA and EFSA jurisdictions. CAGRs derived from facility operating rate assumptions tied to biofuel mandate enforcement and feed inclusion rate optimization by species.
EPA renewable volume obligation adjustments, EFSA mycotoxin threshold modifications, and Vietnam fisheries regulator screening protocol changes are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding biofuel policy durability and feed formulation software adoption curves. A model refresh is warranted upon material change in EU Green Deal carbon border adjustment implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Almond Flour Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
White Mulberry Leaves Extract Market
Ingredients
Textured Soy Protein Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Potato Fiber Market
Ingredients
Salt Market
Ingredients
North America Gelatin Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
Fruit Pectin Market
Ingredients
Mung Bean Protein Market
Ingredients
Tryptose Market
Ingredients
Europe Gelatin Market
Ingredients
Corn Oil Cake Market
Ingredients
Bromelain Ingredient Market
Ingredients
Africa Food Ingredients Market