
 North America Cocoa Products Market | 2026-2036
North America Cocoa Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cocoa Products Market Analytics
The EU Deforestation Regulation is shifting sourcing requirements for cocoa entering North American supply chains, compelling processors to verify traceability. Cargill, Incorporated leverages its integrated supply network from bean to industrial cocoa butter. Barry Callebaut AG anchors its competitive stance through specialized chocolate and compound manufacturing capabilities. The Hershey Company dominates branded confectionery channels with extensive retail distribution across the United States.
North America cocoa products encompass processed derivatives of Theobroma cacao beans, including cocoa liquor containing 50-57% cocoa butter, cocoa powder with 10-12% residual fat content, and pressed cocoa butter used for confectionery coatings. Cocoa butter and chocolate command the deepest margin pools due to premium formulation requirements in confectionery and baking applications. Cocoa powder competes primarily on volume in dairy and beverage formulations where cost efficiency determines procurement decisions. The food service distribution channel is expanding fastest as restaurants and bakeries seek consistent industrial chocolate supplies.
The FDA maintains strict standards of identity for chocolate products under 21 CFR 163, while CFIA enforces parallel compositional requirements in Canada, both shaping permissible ingredient declarations and processing methods. USDA organic certification and Rainforest Alliance sourcing protocols increasingly filter market access for cocoa butter and chocolate positioned toward premium household and bakery end users. Stakeholders must monitor evolving deforestation-linked due diligence obligations and their cascading impact on bean procurement economics.
Market Dynamics
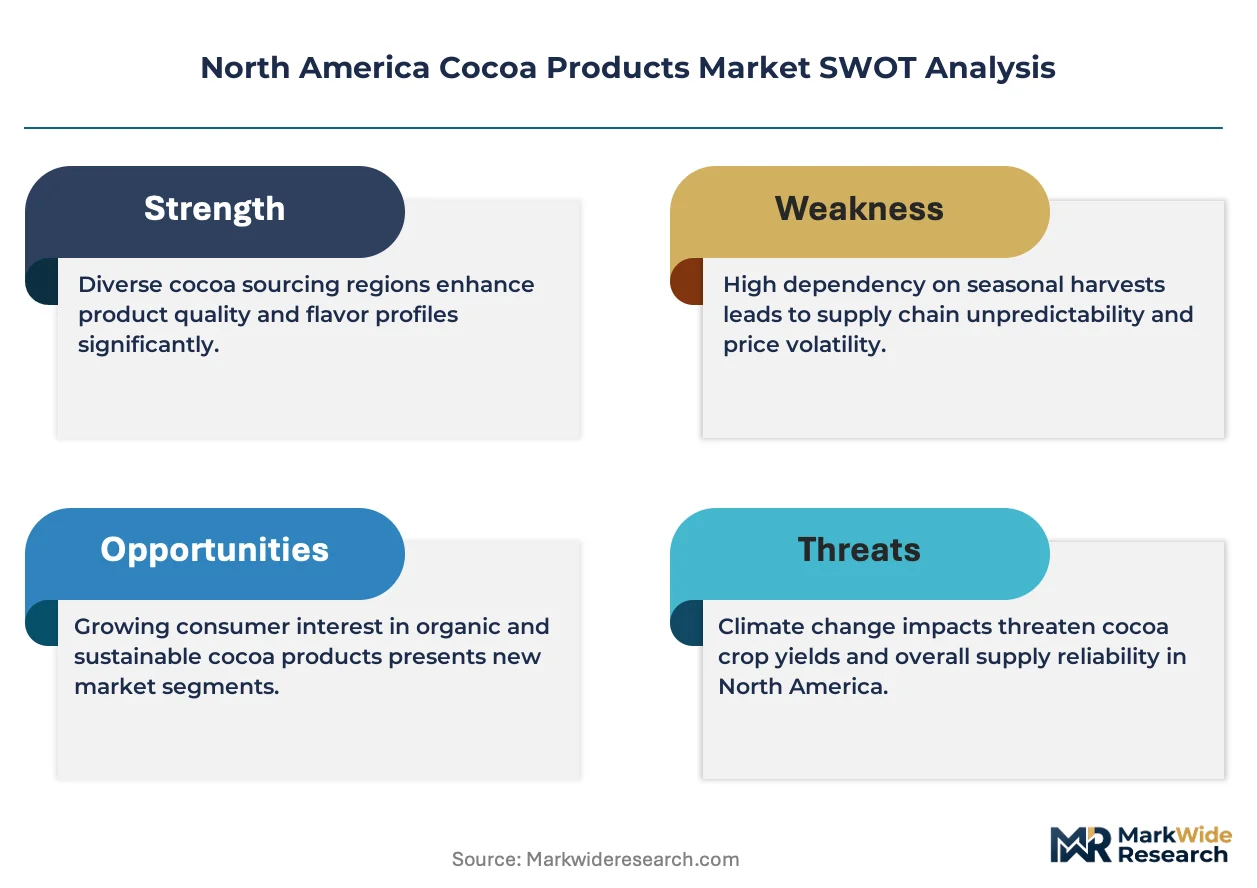
The EU Deforestation Regulation's extraterritorial reach is forcing North American cocoa processors to rebuild traceability infrastructure from bean origin through industrial processing, compressing margins for non-compliant supply chains while advantaging verified-sourcing networks.
Growth Catalysts
- FDA Labeling Mandates:Updated added-sugar disclosure requirements under 21 CFR 101 are compelling confectionery manufacturers to reformulate with higher cocoa content, expanding industrial cocoa liquor demand.
- Artisan Bakery Concentration:Metropolitan clusters in New York and Toronto are driving premium chocolate consumption through specialized patisserie and craft bakery channels.
- Rainforest Alliance Certification:Retail procurement policies favoring verified sustainable sourcing are filtering market access toward credentialed cocoa butter suppliers.
Market Restraints
- Cocoa Butter Price Volatility:Pressed cocoa butter margins fluctuate with West African bean supply disruptions, constraining formulation budgeting for confectionery coatings.
- Traceability Compliance Costs:Deforestation-linked due diligence obligations require satellite-verified farm mapping, elevating procurement overhead for small-batch processors.
- Substitute Fat Competition:Palm oil and shea butter alternatives in compound coatings threaten cocoa butter volume in cost-sensitive dairy applications.
Strategic Opportunities
- Food Service Channel Expansion:Restaurant and bakery chains across the United States are consolidating industrial chocolate procurement through specialized distributors.
- USDA Organic Premium Tier:Certified organic cocoa powder commands price differentiation in specialty beverage and premium household segments.
- Bean-to-Bar Vertical Integration:Mid-scale processors are acquiring grinding capacity to capture margin pools previously ceded to commodity traders.
Industry Challenges
- Regulatory Convergence Complexity:Parallel FDA and CFIA standards of identity for chocolate products create dual-compliance burdens for cross-border manufacturers.
- Legacy System Integration:Blockchain traceability platforms require retrofitting into established ERP infrastructure, delaying real-time supply chain visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cocoa Products Market |
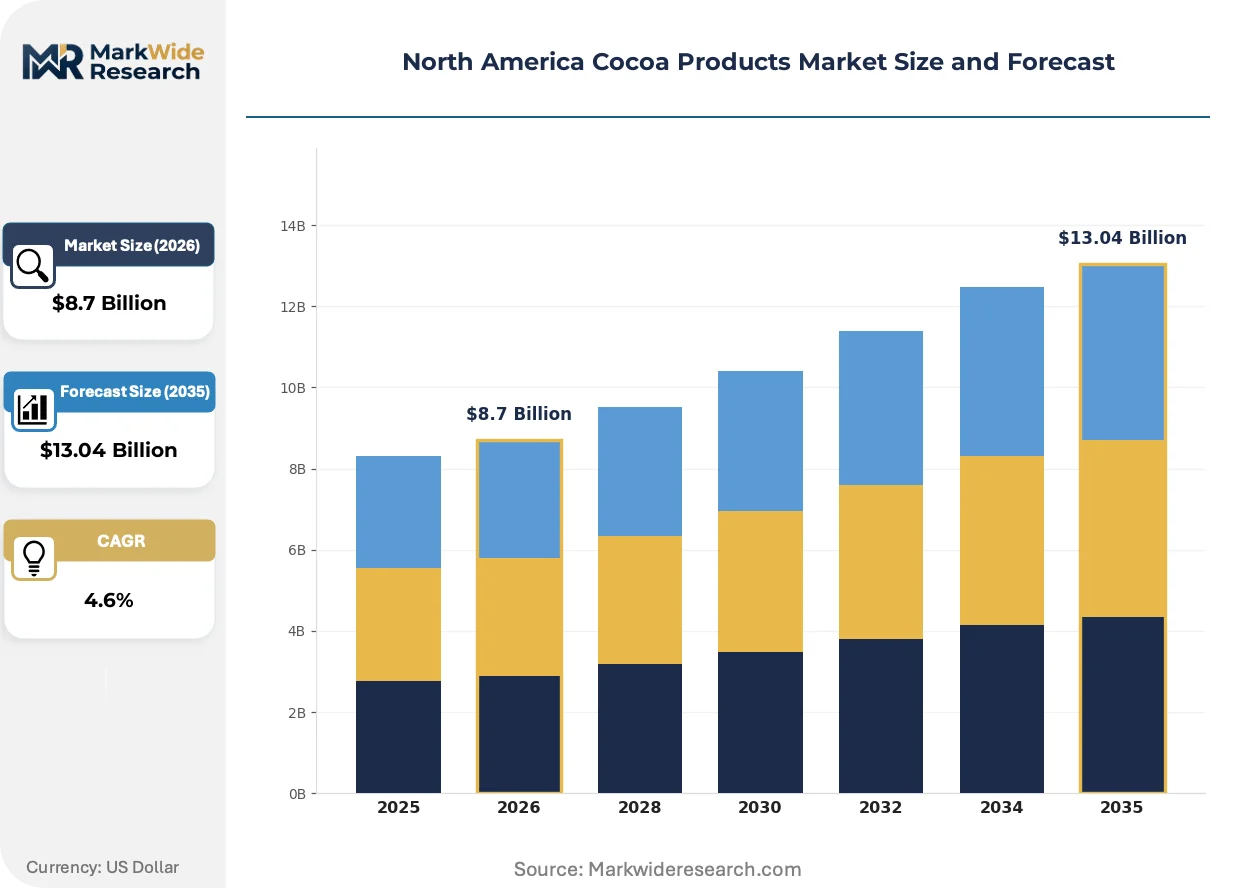
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cocoa Powder, Cocoa Butter, Chocolate, Cocoa Liquor Application: Baking, Confectionery, Beverage, Dairy Distribution Channel: Online, Supermarkets, Specialty Stores, Food Service End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Cargill, Incorporated, Barry Callebaut AG, Olam International, The Hershey Company, Blommer Chocolate Company, Nestlé SA, Mars Incorporated, Mondelēz International Inc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cocoa Products Market Evolving Landscape
Processing technology and procurement transparency are converging to reshape how cocoa derivatives move from origin verification to industrial formulation, with automation and regulatory alignment as dominant vectors of change.
Near-infrared spectroscopy is automating real-time cocoa butter content verification during liquor pressing, enabling processors to optimize extraction yields. Mid-scale confectionery manufacturers in the Midwest United States are adopting these inline sensors to reduce laboratory testing delays. This shift is compressing batch-to-batch variation tolerance and forcing equipment suppliers to integrate predictive calibration algorithms.
The FDA's enforcement discretion on "chocolate" nomenclature for products with alternative fats is tightening under revised industry guidance petitions. This regulatory friction is compelling compound coating manufacturers to reformulate or relabel, diverting R&D expenditure toward cocoa butter enrichment. Canadian processors under CFIA jurisdiction are preemptively aligning with stricter identity standards to maintain cross-border shipment eligibility.
Direct-origin contracting is displacing spot-market bean procurement for premium chocolate lines, with processors establishing multi-year purchase agreements with Ecuadorian and Peruvian cooperatives. Specialty roasters and craft confectioners in California and British Columbia are driving this shift, prioritizing flavor-profile consistency over commodity exchange liquidity. This behavioral pivot is visible most acutely in single-origin dark chocolate segments where provenance narrative commands retail price premiums.
North America Cocoa Products Market Segmentation
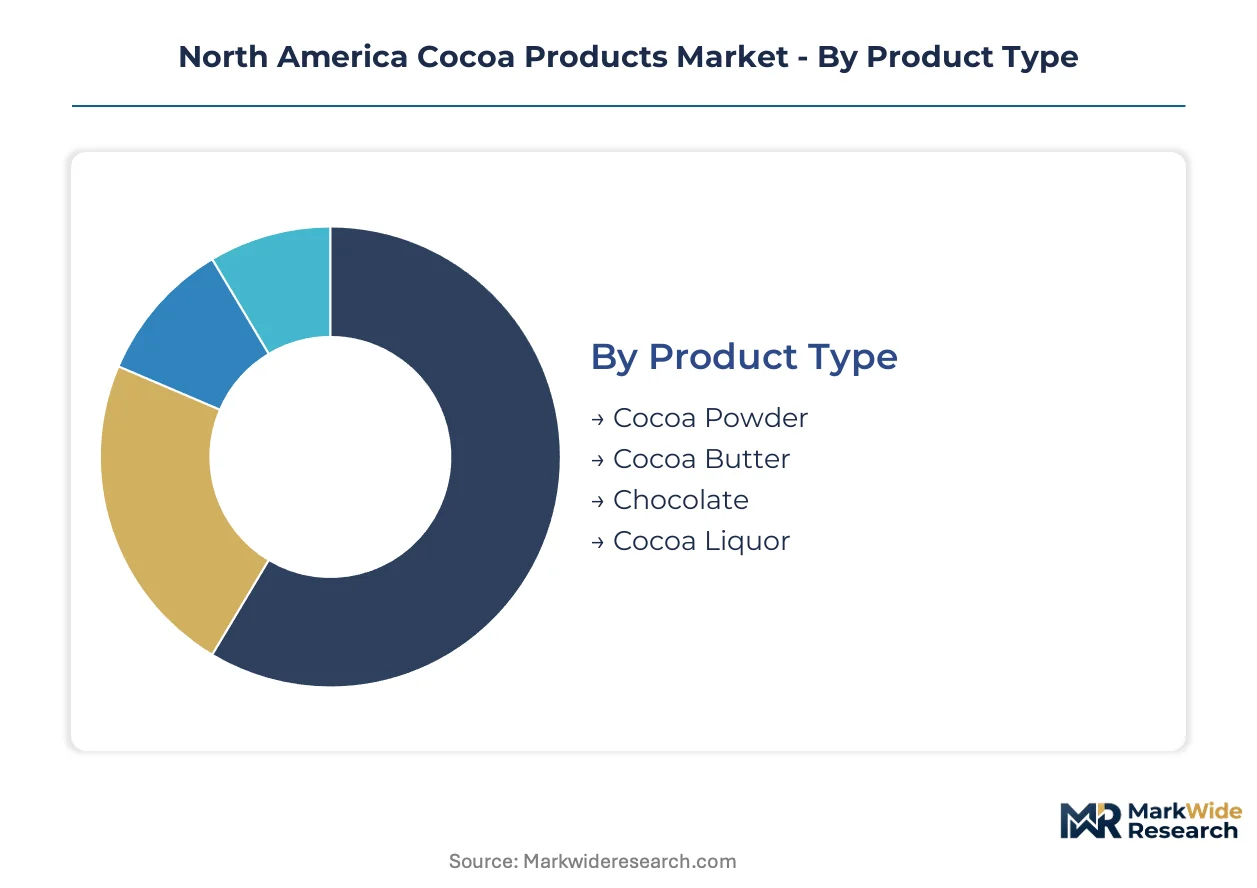
Cocoa derivatives move through North American supply chains along distinct value tiers. Product specifications, application requirements, and procurement channel preferences create natural segmentation boundaries that processors must navigate.
Product Type:
Volume concentrates in commodity powders while premium margins pool in butter and chocolate formulations.
- Cocoa Butter:Pressed fat containing 50-57% natural triglycerides serves confectionery coatings and premium chocolate formulations. Demand clusters in artisan bakeries across New York and Toronto where FDA labeling mandates are pushing higher cocoa content recipes. West African supply disruptions continue compressing formulation budgets for industrial users.
- Chocolate:Refined liquor combined with sugar and milk solids spans industrial couverture to consumer bars. Household consumption in the United States and Canada is intensifying through premium positioning, with Rainforest Alliance certification filtering retail access for sustainable lines.
- Cocoa Powder:10-12% residual fat powder dominates cost-sensitive dairy and beverage applications. Procurement decisions prioritize volume efficiency over provenance narrative.
- Cocoa Liquor:Ground nib paste containing 50-57% cocoa butter serves as the base input for downstream processing. Inline spectroscopy adoption is automating real-time butter content verification during pressing.
Today's leader: Chocolate. Tomorrow's challenger: Cocoa Butter.
Application:
Cost tier separation runs deepest between artisan craft segments and mass-market industrial formulations.
- Confectionery:Enrobed chocolates, pralines, and compound coatings require precise tempering properties. FDA standards of identity under 21 CFR 163 shape permissible fat substitutions, compelling reformulation toward cocoa butter enrichment.
- Baking:Premium patisserie and craft bakery channels in metropolitan clusters drive specialized chocolate demand. Direct-origin contracting with Ecuadorian cooperatives is displacing spot procurement for flavor consistency.
- Beverage:Hot chocolate mixes and malted drinks utilize cocoa powder for cost efficiency. USDA organic certification commands price differentiation in specialty segments.
- Dairy:Ice cream and flavored milk applications face substitute fat competition from palm oil and shea butter alternatives in cost-sensitive formulations.
Confectionery holds margin concentration. Baking climbs fastest on artisan channel expansion.
Distribution Channel:
Customer type dictates channel selection between consolidated procurement and fragmented spot purchasing.
- Food Service:Restaurant and bakery chains across the United States are consolidating industrial chocolate procurement through specialized distributors. This channel is expanding most quickly as operators seek consistent supply.
- Supermarkets:Mass retail dominates branded household chocolate volume. CFIA parallel standards in Canada create dual-compliance burdens for cross-border manufacturers.
- Specialty Stores:Single-origin and craft confectionery lines reach premium consumers through curated retail. California and British Columbia roasters are driving direct-origin contracting behavioral shifts.
- Online:Direct-to-consumer channels serve niche provenance narratives and subscription chocolate services. Blockchain traceability platforms are retrofitting into established ERP infrastructure.
Food Service leads expansion velocity. Specialty Stores challenge on margin capture.
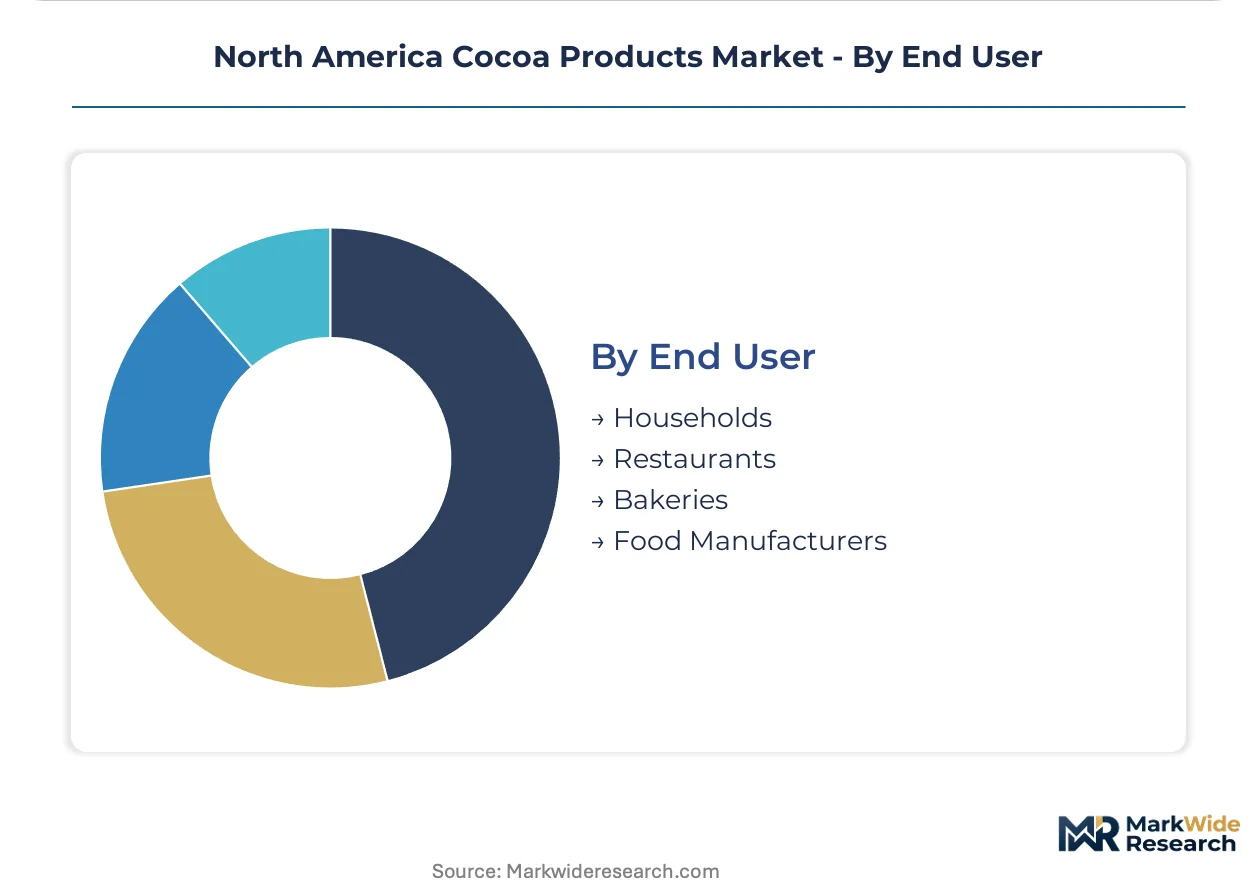
End User:
Supply concentration varies between consolidated food manufacturers and fragmented artisan operators.
- Food Manufacturers:Industrial scale processors drive cocoa liquor and powder volume. Near-infrared spectroscopy adoption is compressing batch-to-batch variation tolerance.
- Bakeries:Metropolitan craft operations in New York and Toronto prioritize consistent couverture supply. Bean-to-bar vertical integration is capturing margin pools previously ceded to commodity traders.
- Households:Premium chocolate consumption is intensifying across the United States and Canada. The FDA's updated added-sugar disclosure requirements are reshaping product formulation strategies.
- Restaurants:Dessert program differentiation drives specialized procurement through food service distributors. Traceability compliance costs including satellite-verified farm mapping elevate overhead for smaller operators.
Food Manufacturers anchor volume. Bakeries gain share on artisan channel premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan food manufacturing clusters across the continent anchor cocoa processing talent and infrastructure. FDA and CFIA regulatory frameworks shape cross-border operational requirements. Bean-to-bar craft movements concentrate in coastal urban centers.
United States
Premium chocolate consumption intensifies through household and artisan bakery channels. FDA standards of identity under 21 CFR 163 govern permissible fat content and labeling declarations. New York City's patisserie district drives specialized couverture procurement for high-end dessert programs.
Canada
CFIA compositional requirements create parallel compliance obligations for confectionery manufacturers. The updated food labeling regime for added sugars mirrors FDA disclosure mandates. Toronto's craft bakery cluster demands consistent industrial chocolate supply from verified-sourcing networks.
Mexico
Domestic cocoa cultivation in Tabasco and Chiapas supplies regional processors with flavor-diverse bean profiles. COFEPRIS food safety standards align with North American import protocols. Mexico City Metro anchors chocolate manufacturing for Central American distribution channels.
North America Cocoa Products Market Competitive Landscape
Capital-heavy processors compete with asset-light brand marketers across tiered margin pools. Integrated bean-to-butter operators hold supply security advantages. Three archetypes dominate: multinational traders with origin infrastructure, specialized chocolate manufacturers with formulation expertise, and branded confectioners with retail channel control. Competitive moves concentrate on traceability platform investments and direct-origin contracting to secure deforestation-compliant supply.
Within the integrated processor tier, Cargill, Incorporated and Barry Callebaut AG represent capital-intensive models with captive grinding and pressing capacity. The Hershey Company exemplifies brand-dominated positioning through retail distribution density. These three entities occupy distinct competitive spaces: commodity supply security, industrial formulation services, and household brand equity respectively.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Barry Callebaut AG |
| Olam International |
| The Hershey Company |
| Blommer Chocolate Company |
| Nestlé SA |
| Mars Incorporated |
| Mondelēz International Inc. |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Near-infrared spectroscopy adoption is compressing batch-to-batch variation tolerance while simultaneously reducing laboratory overhead and concentrating procurement power among processors with inline calibration capabilities. This automation shift rewards capital-intensive operators who can absorb equipment costs, widening the gap between integrated bean-to-butter facilities and small-batch artisan competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Rainforest Alliance-certified cocoa butter from conventional industrial grades and commodity powder alternatives. Price differentiation rests on certification tier and volume scale, with organic cocoa powder commanding premiums in specialty beverage channels. Cost compression in standard-tier cocoa butter is intensifying because West African supply disruptions constrain formulation budgets. Mass-market dairy applications exhibit highest price sensitivity, while artisan bakeries in New York and Toronto absorb premium tier increases for provenance-verified couverture.
Supply Chain Analysis
Transoceanic freight cost volatility from West African ports to US Gulf and East Coast terminals is elevating landed costs for bean shipments, compressing margins for non-integrated processors. Supply concentrates in Côte d'Ivoire, Ghana, and Ecuador, with Ecuadorian specialty grades drawing from distinct flavor-profile cooperatives. Raw material dependencies include fermented cocoa beans, caustic soda for alkalization, and packaging films for moisture barrier protection. Single-source vulnerability runs through Abidjan and San Pedro port chokepoints. Distribution runs through specialized food service distributors consolidating restaurant and bakery chain procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cocoa products market functions as a geographic-arbitrage play between FDA-regulated US formulations and CFIA-aligned Canadian labeling requirements, where compliance cost differentials favor dual-certified processors.
For Market Incumbents: Hedge against EU Deforestation Regulation compliance cost inflation by acquiring satellite-verified farm mapping capabilities or partnering with Ecuadorian cooperatives holding established traceability infrastructure. Prioritize backward integration into pressing capacity to capture cocoa butter margin pools threatened by West African supply volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting California and British Columbia craft confectionery segments where provenance narrative commands retail price premiums. Exploit underpenetrated USDA organic cocoa powder demand in specialty beverage channels, leveraging food service distributor consolidation to bypass supermarket slotting fee barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors lacking traceability infrastructure but holding established grinding capacity and artisan bakery customer relationships. Long-term viability favors operators with captive Ecuadorian or Peruvian cooperative contracts insulating against commodity exchange liquidity constraints. Monitor FDA enforcement discretion tightening on "chocolate" nomenclature for alternative-fat products as inflection signal for reformulation-driven cocoa butter demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Traceability Platform Investment | Satellite-verified farm mapping satisfies EU Deforestation Regulation requirements for North American import eligibility. |
| Direct-Origin Contracting | Multi-year purchase agreements with Ecuadorian cooperatives secure flavor-profile consistency for premium chocolate lines. |
| Inline Spectroscopy Adoption | Real-time cocoa butter content verification during liquor pressing optimizes extraction yields for Midwest confectionery manufacturers. |
| Food Service Channel Expansion | Specialized distributor relationships consolidate procurement for restaurant chains seeking consistent industrial chocolate supply. |
| USDA Organic Certification | Certified organic cocoa powder commands price differentiation in specialty beverage and premium household segments. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market through structured interviews with cocoa processing plant managers, artisan bakery procurement leads, food service distribution channel partners, and confectionery brand R&D directors. Secondary validation draws from FDA 21 CFR 163 standards filings, CFIA food labeling guidance documents, USDA organic certification databases, and Rainforest Alliance supply chain audit reports. Bottom-up volume modeling triangulates against top-down value estimates across product type, application, and distribution channel dimensions.
Rate-of-change decomposition separates volume growth from price movement across the projection horizon, with CAGRs derived from segment-level trend extrapolation moderated by regulatory impact assessment. Segmentation dimensions modeled include product type tier, end-use application, distribution channel structure, and certification status. Forecast inputs incorporate West African bean supply disruption frequency, FDA labeling mandate compliance cost trajectories, and food service channel consolidation velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained EU Deforestation Regulation enforcement escalation or prolonged West African port logistics disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Pork Skin Gelatin Market
Ingredients
Marine Ingredients Market
Ingredients
Asparagus Extract Market
Ingredients
Bean Pasta Market
Ingredients
Global Malt Extracts and Ingredients Market
Ingredients
Soy Hydrolysates Market
Ingredients
Potato Granules Market
Ingredients
Africa Food Ingredients Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Avocado Oil Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Bakery Ingredients Market
Ingredients
North America Corn Starch Market
Ingredients
Pea Hull Fiber Market
Ingredients
Palm Mid-Fraction Market
Ingredients
Coconut Cream Powder Market