
 Yeast Autolysates Market | 2026-2036
Yeast Autolysates Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Autolysates Market Analytics
Market Context
Plant-based hydrolyzed proteins is realigning cost structures across flavor and nutrition applications, pressuring traditional autolysate positioning. Lallemand Inc leverages captive yeast strain banks to sustain North American supply security. Lesaffre Group anchors European volume through integrated fermentation infrastructure. Angel Yeast Co Ltd dominates Asian production scale with backward integration into molasses sourcing.
Technical Definition and Segment Structure
Yeast autolysates comprise intracellular proteins, nucleotides, peptides, and B-vitamins released through controlled enzymatic self-digestion of Saccharomyces cerevisiae, functioning primarily as natural flavor enhancers and nutrient-dense feed additives. Dry yeast autolysates occupy the largest revenue share due to extended shelf stability and lower logistics burden, while liquid yeast autolysates represent the fastest-expanding form driven by beverage fermentation demand. Animal nutrition applications lead volume consumption, though flavoring agent applications in savory foods command superior margin pools.
Regulatory Environment
EFSA and FDA oversight governs yeast-derived ingredient safety assessments, with REACH and F-Gas Regulation constraining solvent extraction pathways in Europe. USDA organic certification and EU organic regulation create parallel qualification tracks that bifurcate supplier bases. Stakeholders must monitor evolving novel food status determinations and carbon intensity thresholds for fermentation feedstocks.
Market Dynamics
Clean-label reformulation mandates are forcing savory food manufacturers to replace synthetic flavor enhancers with yeast-derived alternatives, compressing qualification timelines and concentrating procurement among certified suppliers.
Growth Catalysts
- EU F-Gas Regulation:Solvent-based extraction methods face phase-down schedules, redirecting investment toward enzymatic autolysis pathways that qualify as process-derived natural flavors under EFSA guidance.
- Pet food premiumization:Humanization trends in companion animal nutrition are absorbing yeast autolysates as palatability enhancers and nucleotide sources for immune development formulations.
- Molasses supply integration:Fermentation feedstock backward integration in India and Brazil is stabilizing input costs for regional autolysate production.
Market Restraints
- Input cost volatility:Molasses pricing fluctuates with sugar beet harvest cycles and ethanol policy shifts in the European Union and United States.
- Supply concentration:Three integrated fermentation groups control the majority of pharmaceutical-grade yeast strain banks, creating qualification bottlenecks for new market entrants.
- Technical limitation:Autolysate bitterness from excessive RNA hydrolysis limits application rates in delicate flavor systems such as white sauces and dairy alternatives.
Strategic Opportunities
- Precision fermentation convergence:CRISPR-edited Saccharomyces strains combined with metabolomic screening are enabling custom nucleotide profiles for targeted umami intensity.
- USDA organic certification:Parallel organic supply chains command 15-30% price premiums in North American retail and foodservice channels.
- Cell-culture media:Underpenetrated biotechnology applications in Singapore and South Korea are absorbing yeast autolysates as low-cost nitrogen sources for microbial fermentation.
Industry Challenges
- Enzymologist talent scarcity:Formulation science expertise in controlled autolysis kinetics concentrates among legacy European and Japanese research institutes.
- Dual certification timelines:Simultaneous EU organic regulation and USDA organic qualification require 18-24 month parallel documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Autolysates Market |
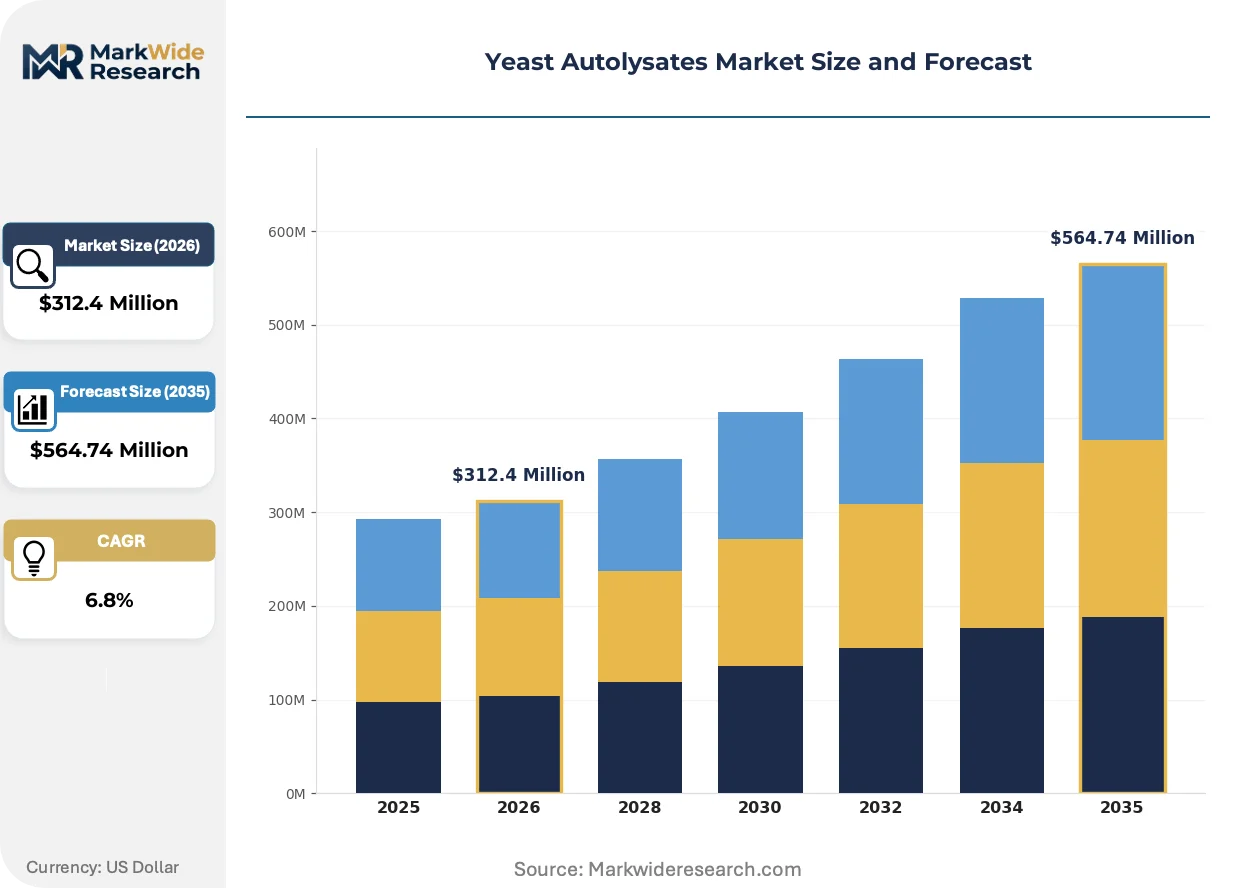
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Yeast Autolysates, Liquid Yeast Autolysates, Powdered Yeast Autolysates, Concentrated Yeast Autolysates End User: Food Industry, Beverage Industry, Animal Nutrition, Pharmaceutical Industry Application: Fermentation, Flavoring Agent, Nutritional Supplement, Preservative Form: Granular, Powder, Liquid, Paste |
| Companies Covered | Lallemand Inc, Chr. Hansen Holding A/S, Lesaffre Group, Biorigin, Kerry Group plc, Associated British Foods plc, Archer Daniels Midland Company, Kemin Industries Inc, Angel Yeast Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Autolysates Market Evolving Landscape
Process intensification and regulatory chemistry constraints are redirecting R&D investment from extraction efficiency toward strain-specific metabolite engineering and carbon-accounted fermentation systems.
Continuous enzymatic autolysis with immobilized cell reactors is absorbing capital allocation from batch processing equipment. Mid-scale savory ingredient manufacturers in Germany and the Netherlands are piloting these systems to reduce water usage and thermal degradation of heat-labile B-vitamins. The technology is absorbing demand from clean-label soup and sauce producers seeking shorter ingredient declarations.
REACH authorization requirements for solvent-based nucleotide extraction are compressing process economics for European producers. ECHA sunset dates for several polar aprotic solvents are forcing reformulation toward aqueous enzymatic methods with higher capital intensity but lower regulatory risk. Yeast extract manufacturers serving infant nutrition and clinical applications are absorbing the compliance burden fastest due to existing toxicology dossiers.
Direct procurement relationships between savory food manufacturers and fermentation operators are displacing traditional ingredient distributor networks. Large bakery and snack producers in France and the United States are negotiating toll-manufacturing agreements with captive molasses supply. This channel restructuring is most visible in high-volume applications where specification standardization reduces technical service requirements.
Yeast Autolysates Market Segmentation
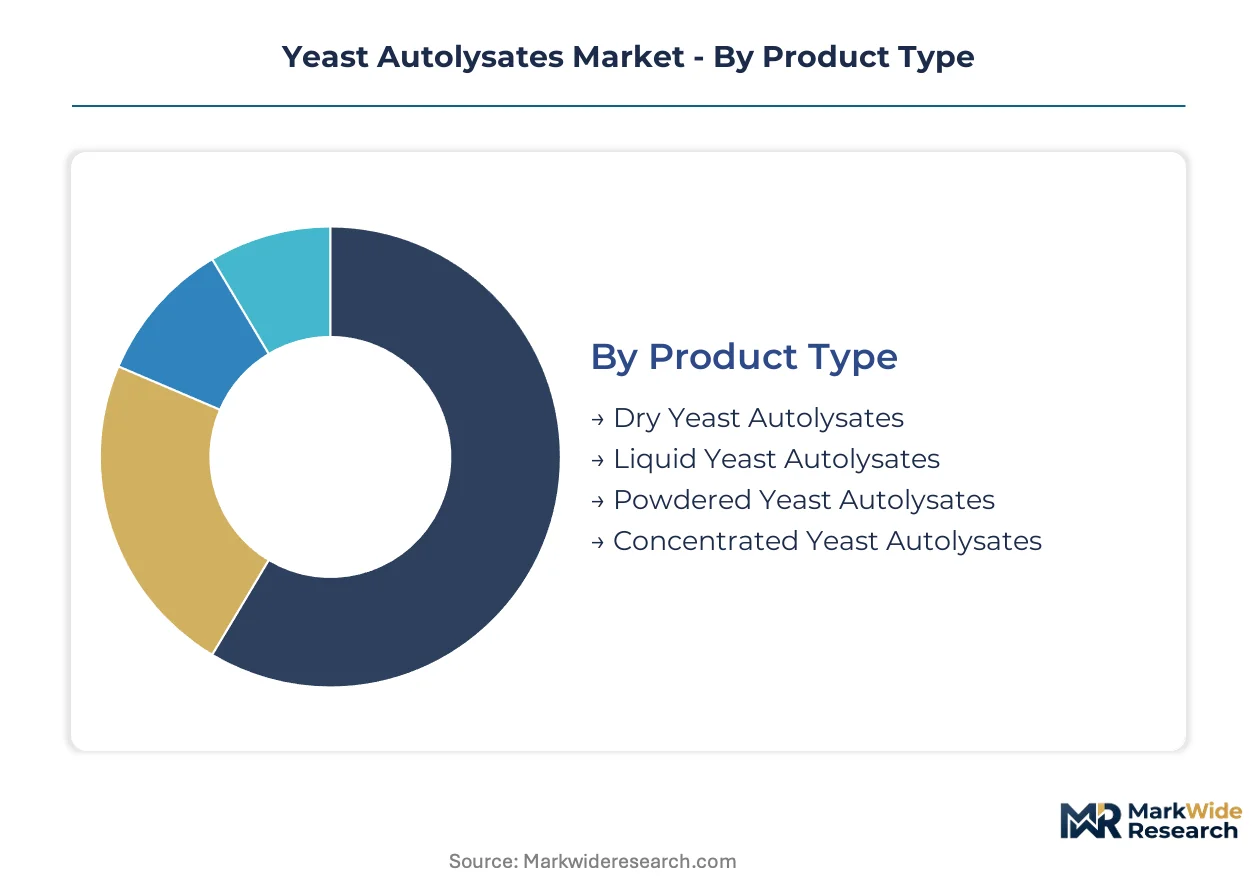
Segmentation in yeast autolysates reveals how technical specifications align with diverging margin structures across food, feed, and pharmaceutical channels. Procurement patterns split sharply between high-volume commodity grades and qualification-intensive specialty tiers.
Product Type:
Upgrade cycles in processing equipment are shifting manufacturer preferences toward formats that reduce handling costs and extend distribution reach.
- Dry Yeast Autolysates:Low-moisture granules or flakes with 12-month shelf stability dominate long-haul logistics. Demand concentrates in German and French savory ingredient manufacturing where extended supply chains require ambient storage tolerance.
- Liquid Yeast Autolysates:Aqueous suspensions with immediate solubility bypass rehydration steps in beverage fermentation. Expansion concentrates in United States craft brewing and kombucha production where process integration values pumpable inputs.
- Powdered Yeast Autolysates:Fine-milled particles suit dry-blend nutritional applications. Pet food premixers in the Midwest United States specify this format for homogeneous distribution in kibble coatings.
- Concentrated Yeast Autolysates:High-solids pastes reduce freight costs for regional food processors. Brazilian meat flavoring compounders absorb this grade for proximity to molasses fermentation clusters.
Volume placements concentrate in Dry Yeast Autolysates; the faster expansion belongs to Liquid Yeast Autolysates.
End User:
Cost tier differentiation separates commodity feed applications from pharmaceutical-grade nucleotide sourcing with 10-15x price multiples.
- Food Industry:Clean-label savory formulations in soups, sauces, and snacks absorb yeast autolysates as natural MSG replacements. EFSA process-derived natural flavor qualifications command premium positioning in French and Italian prepared meals.
- Animal Nutrition:Swine and poultry feed formulations consume the largest tonnage, with nucleotide supplementation for gut development in weaning piglets. United States integrators specify autolysates for antibiotic-free production protocols.
- Beverage Industry:Fermentation nutrition for ethanol and craft beer production values yeast-derived nitrogen sources. Brazilian bioethanol plants integrate autolysate dosing for consistent fermentation kinetics.
- Pharmaceutical Industry:Cell culture media and probiotic fermentation require endotoxin-controlled grades. Singapore biomanufacturing clusters source pharmaceutical-grade autolysates for microbial platform development.
Feed applications anchor volume consumption; food industry positioning captures the steepest margin expansion.
Application:
Application maturity curves separate established fermentation nutrition from emerging clinical and preservation uses.
- Flavoring Agent:Umami-active nucleotides and peptides enhance savory profiles without synthetic additive labeling. Japanese ramen seasoning and United States snack coating manufacturers specify autolysates for reduced-sodium formulations.
- Fermentation:Nitrogen and B-vitamin supplementation supports industrial ethanol, enzyme, and organic acid production. Indian distilleries integrate autolysates to stabilize molasses-based fermentation yields.
- Nutritional Supplement:B-complex fortification and immune-modulating nucleotides target dietary supplement and functional food channels. South Korean beauty-from-within formulations absorb yeast-derived ribonucleotides.
- Preservative:Antimicrobial peptides extend shelf life in clean-label meat and dairy applications. Emerging European research evaluates autolysate fractions for bioprotective cultures.
Fermentation claims the largest absolute volumes; flavoring applications gain share fastest on clean-label reformulation mandates.
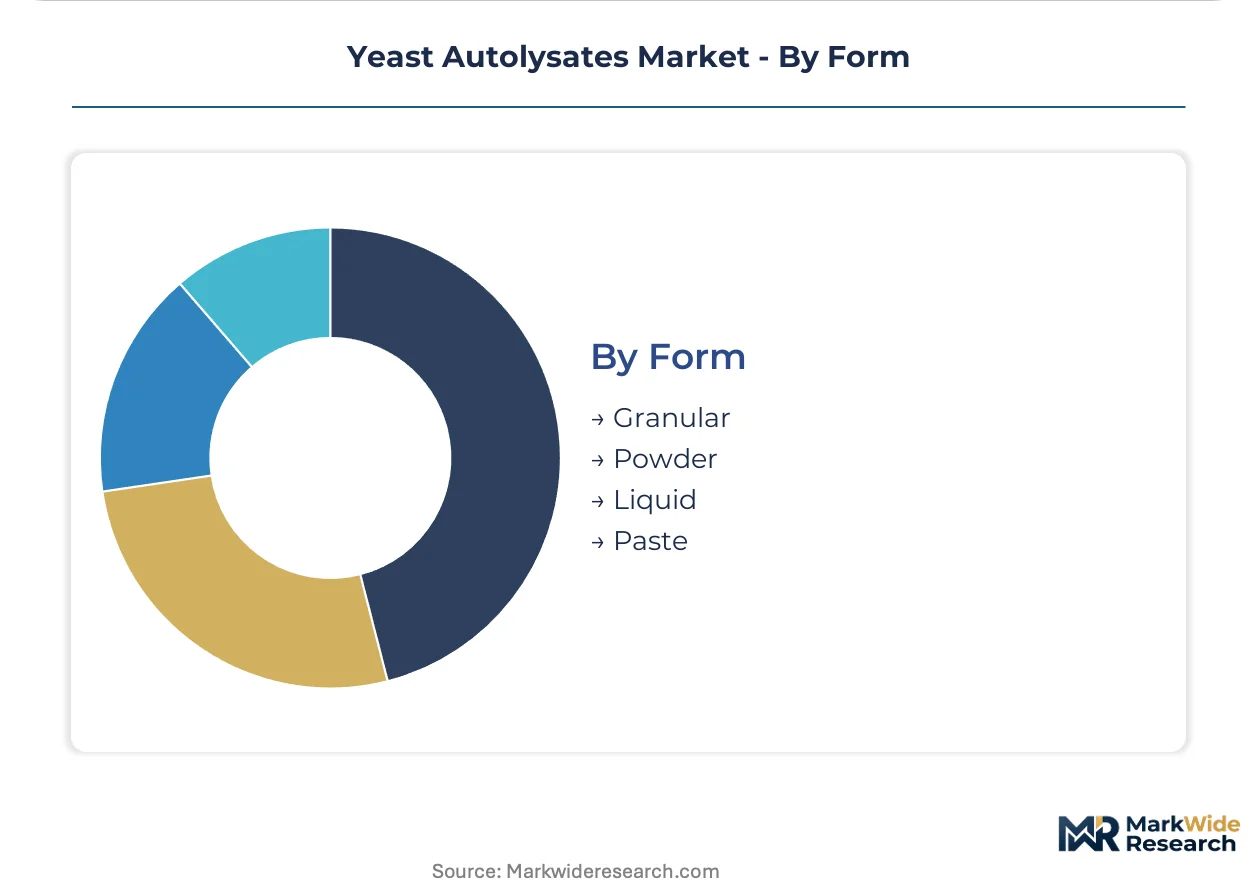
Form:
Supply concentration among integrated fermentation groups dictates available form factors through captive processing infrastructure.
- Granular:Free-flowing particles with controlled particle size distribution suit automated dosing in feed mills. United States poultry operations specify granular formats for pneumatic conveying systems.
- Powder:Fine dispersibility supports dry-blend uniformity in nutritional premixes. German supplement contract manufacturers prefer powder for tablet compression and capsule filling compatibility.
- Liquid:Pumpable consistency enables continuous dosing in beverage and fermentation processes. French dairy alternatives producers specify liquid autolysates for seamless integration into HTST lines.
- Paste:High-viscosity concentrates minimize water content for regional distribution. Brazilian savory compounders utilize paste formats for proximity to fermentation sites.
Powder and granular forms dominate current procurement; liquid formats are climbing fastest on process integration demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for yeast autolysates concentrates in Germany, France, and the United States, where bakery and savory flavor applications anchor procurement volumes. Clean-label reformulation mandates in these markets are compressing qualification timelines and redirecting sourcing toward certified suppliers.
United States
Pet food premiumization and antibiotic-free livestock protocols absorb substantial yeast autolysate volumes for palatability enhancement and gut health formulations. FDA oversight governs ingredient safety assessments for animal nutrition applications. Midwest poultry operations and Great Lakes pet food manufacturers specify granular formats for pneumatic conveying compatibility.
Germany
Savory ingredient manufacturing for soups, sauces, and prepared meals drives demand for dry yeast autolysates with extended ambient storage tolerance. EFSA process-derived natural flavor qualifications and REACH solvent restrictions redirect investment toward enzymatic autolysis pathways. Bavarian and North Rhine-Westphalia fermentation clusters pilot continuous enzymatic systems to reduce water usage.
France
Bakery applications and clean-label snack coatings absorb yeast autolysates as reduced-sodium flavor enhancers. EU F-Gas Regulation constrains solvent extraction methods, favoring aqueous enzymatic production routes. Paris Basin and Lyon-area savory compounders negotiate direct toll-manufacturing agreements with captive molasses supply.
Brazil
Bioethanol fermentation nutrition and regional meat flavoring compounders stabilize demand for concentrated yeast autolysate pastes. ANVISA governs ingredient safety for food and feed applications. São Paulo state fermentation clusters leverage backward integration into regional molasses sourcing to stabilize input costs.
China
Industrial enzyme and organic acid fermentation absorb yeast autolysates as nitrogen supplementation for microbial platforms. SAMR and GB standards govern food ingredient safety and quality specifications. Yangtze River Delta biomanufacturing clusters source pharmaceutical-grade autolysates for cell culture media applications.
Yeast Autolysates Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated fermentation groups scale enzymatic autolysis infrastructure to meet clean-label demand. The vendor base concentrates among three tiers: multinational biotechnology conglomerates with captive strain banks, regional fermentation specialists with molasses supply integration, and contract manufacturers serving niche pharmaceutical-grade applications. Strategic archetypes include backward-integrated feedstock controllers, precision fermentation technology licensors, and toll-manufacturing operators. M&A activity and geographic expansion through distribution partnerships represent the dominant competitive moves reshaping market structure.
Within the integrated fermentation tier, Lallemand Inc and Lesaffre Group exemplify archetypes of strain bank control and continental supply security. Angel Yeast Co Ltd occupies a position representing Asian production scale with upstream molasses integration. These three entities anchor the competitive landscape through their respective positions in North American, European, and Asian supply corridors.
| Leading Market Players |
|---|
| Lallemand Inc |
| Chr. Hansen Holding A/S |
| Lesaffre Group |
| Biorigin |
| Kerry Group plc |
| Associated British Foods plc |
| Archer Daniels Midland Company |
| Kemin Industries Inc |
| Angel Yeast Co Ltd |
| Others |
Value Network & Pricing Analysis
Clean-label procurement mandates from French and United States savory food manufacturers are compressing qualification timelines for yeast autolysate suppliers, forcing backward integration into molasses sourcing and enzymatic processing upgrades that widen price spreads between certified and commodity grades.
Pricing Analysis
Volume placements in animal nutrition anchor the lower margin tier while food-grade flavoring applications capture premium positioning. Three-tier pricing structure across pharmaceutical-grade, food-certified, and feed-commodity levels separates buyers by endotoxin control and organic certification requirements. Cost compression in the feed tier is intensifying because Brazilian and Indian molasses supply integration is stabilizing input costs for regional producers. Poultry integrators in the United States Midwest exhibit the highest price sensitivity, whereas Singapore biomanufacturing clusters absorb pharmaceutical-grade premiums with minimal elasticity.
Supply Chain Analysis
Direct-to-savory-compounder channels handle high-volume demand from French and German prepared meal manufacturers, displacing traditional ingredient distributor networks. Production gravity centers on China, Brazil, and France, with Yangtze River Delta fermentation clusters supplying pharmaceutical grades and São Paulo state facilities feeding regional meat flavoring compounders. Raw material flows draw from sugar beet molasses in Europe, cane molasses in Brazil and India, and captive yeast strain banks controlled by integrated fermentation groups. Single-source vulnerability concentrates in pharmaceutical-grade strain repositories held by three multinational biotechnology conglomerates. Distribution runs through toll-manufacturing agreements for high-volume bakery and snack applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Yeast autolysate supply security has become a vertical-integration race, with control over molasses fermentation feedstocks and captive Saccharomyces strain banks emerging as the decisive upstream lever separating margin leaders from price-takers.
For Market Incumbents: Cement supply security through toll-manufacturing agreements with Brazilian and Indian molasses suppliers, while accelerating enzymatic autolysis capacity additions in Germany and the United States to meet REACH and FDA qualification demands. Precision fermentation technology licensing represents a critical defensive lever against CRISPR-edited strain entrants. Organic certification investment in parallel EU and USDA tracks defends premium positioning against regional specialists. For New Entrants and Emerging Players: Launch via contract manufacturing relationships with mid-scale savory ingredient producers in the Netherlands and United States craft brewing clusters, where process integration demands for liquid autolysates outpace incumbent capacity expansion. Cell-culture media applications in Singapore and South Korea offer the most penetrable white-space, with endotoxin-controlled grades commanding 10-15x feed-commodity multiples. A go-to-market angle centered on custom nucleotide profiles for targeted umami intensity bypasses entrenched flavor house relationships. For Investors and Strategic Acquirers: The window for entry favors regional fermentation specialists with backward-integrated molasses supply and existing EFSA or FDA toxicology dossiers. Over the projection horizon, consolidation around enzymatic processing infrastructure and strain bank control will determine long-term viability. Acquisition targets should display captive feedstock relationships and qualification-intensive end-user concentration. The signal to watch is toll-manufacturing agreement announcements between savory compounders and fermentation operators, indicating channel restructuring velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Brazilian and Indian cane sourcing stabilizes input cost volatility against sugar beet harvest cycles. |
| Continuous Enzymatic Autolysis Scale-Up | German and Dutch pilot systems reduce water usage and thermal B-vitamin degradation for clean-label producers. |
| Pharmaceutical-Grade Strain Bank Acquisition | Endotoxin-controlled repositories unlock Singapore biomanufacturing and cell-culture media applications. |
| Parallel Organic Certification Investment | Simultaneous EU regulation and USDA qualification captures 15-30% North American retail premiums. |
| Precision Fermentation Technology Licensing | CRISPR-edited Saccharomyces platforms enable custom nucleotide profiles for targeted umami intensity. |
Research Methodology
Document review covered EFSA guidance documents, FDA GRAS notifications, REACH authorization records, and customs trade data, complemented by interviews with fermentation R&D directors, savory ingredient procurement leads, pet food formulators, and molasses supply specialists. Secondary validation drew from SEC filings of integrated biotechnology groups, ANVISA regulatory databases, and industry association production statistics. Bottom-up volume modeling triangulated against top-down value estimates derived from end-user consumption patterns.
Cross-referencing historical capacity expansion patterns against panel input from plant managers and technical directors anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product form, end-use industry, application function, and regional regulatory cluster. CAGRs were synthesized from production capacity buildout schedules and clean-label reformulation adoption curves. Forecast inputs incorporated molasses pricing volatility indices and enzymatic processing yield improvements.
Regulatory determination delays, molasses supply disruption from ethanol policy shifts, and precision fermentation yield breakthroughs are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding EFSA process-derived natural flavor qualification stability and REACH solvent phase-down adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Halal Ingredients Market
Ingredients
Ingredients Market
Ingredients
Yeast Derivatives Market
Ingredients
Fruit Powder Market
Ingredients
Salad Oil Market
Ingredients
Malted Wheat Flour Market
Ingredients
Mexico Avocado Oil Market
Ingredients
Sunflower Protein Market
Ingredients
India Sodium Reduction Ingredients Market
Ingredients
North America Soybean Oil Market
Ingredients
Virginiamycin Market
Ingredients
Sweet Almond Oil Market
Ingredients
Global Cocoa Products Market
Ingredients
Avocado Powder Market
Ingredients
Horny Goat Weed Extract Market
Ingredients
Colombia Food Ingredients Market