
 Middle East and Africa Feed Antioxidants Market | 2026-2036
Middle East and Africa Feed Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Feed Antioxidants Market Foresight
Commercial poultry integrators are collapsing the historical dominance of smallholder ruminant feed channels across North Africa. Cargill Incorporated leverages its port-adjacent blending facilities in Morocco to control import logistics for bulk antioxidant concentrates. Kemin Industries differentiates through heat-stable formulation expertise tailored to Gulf Cooperation Council climate conditions. BASF SE anchors synthetic antioxidant supply through established BHT and ethoxyquin distribution networks spanning Cairo to Johannesburg.
Feed antioxidants comprise synthetic and natural compounds—typically phenolic derivatives, quinoline-based stabilizers, or tocopherol concentrates—engineered to inhibit lipid peroxidation in compounded feeds exposed to elevated temperature and humidity. These additives preserve fat-soluble vitamins and essential fatty acids during storage, transit, and prolonged feeding cycles in subtropical climates. Tocopherols command premium positioning as natural-source alternatives gain traction among Saudi dairy and aquaculture operations seeking reduced synthetic load. Powder formulations dominate volume flows through Egyptian and Nigerian distributor channels, while liquid emulsions penetrate large-scale integrated poultry systems requiring automated dosing precision. Poultry applications outpace ruminant and swine segments across the region, though aquaculture antioxidant demand is accelerating in Oman and Tunisia as marine feed milling consolidates.
South Africa's Department of Agriculture enforces strict mycotoxin and feed additive registration protocols that shape import approval timelines and local blending requirements. Egypt's Ministry of Agriculture and Land Reclamation regulates ethoxyquin maximum residue thresholds, directly influencing formulation choices by multinational suppliers. The Saudi Food and Drug Authority aligns with Gulf Standardization Organization feed safety benchmarks, creating compliance complexity for cross-border antioxidant shipments. Stakeholders must monitor evolving natural-source certification pathways and heat-stability performance standards as climate adaptation becomes central to procurement decisions.
Market Dynamics
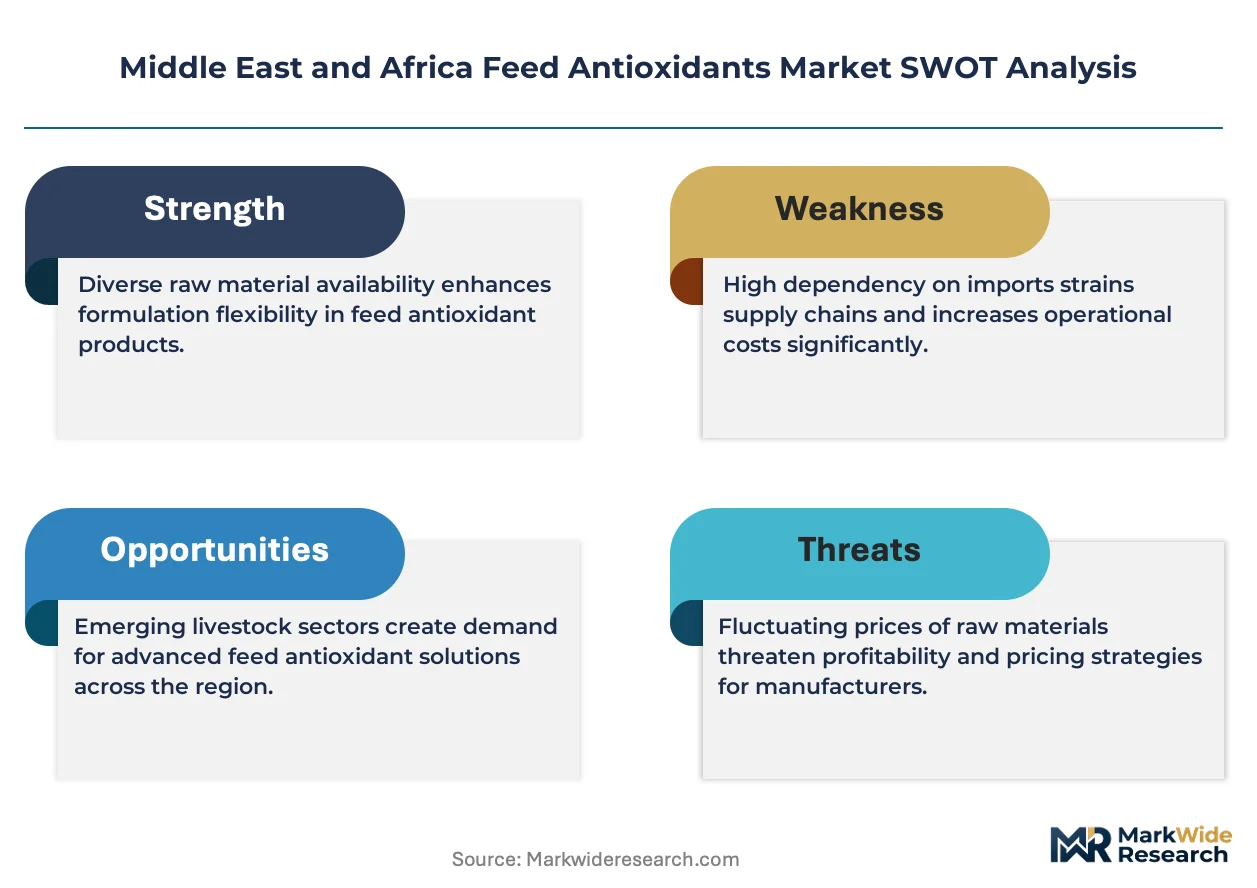
Heat-stress formulation demand from North African poultry integrators is compressing traditional ruminant feed channels and forcing antioxidant suppliers to reconfigure distribution networks around automated dosing systems and climate-adapted stabilizer portfolios.
Growth Catalysts
- Gulf Cooperation Council climate adaptation mandates:Saudi Arabia's SFDA alignment with Gulf Standardization Organization feed safety benchmarks creates procurement urgency for heat-stable antioxidant formulations across integrated poultry operations.
- Egypt's Nile Delta poultry belt expansion:Large-scale broiler operations in Sharqia and Dakahlia governorates drive concentrated volume procurement of lipid stabilizers for extended storage cycles in subtropical humidity.
- South African mycotoxin control tightening:The Department of Agriculture, Land Reform and Rural Development's stricter residue thresholds pressure feed mills toward synthetic antioxidant blend adoption.
Market Restraints
- Ethoxyquin regulatory friction:Egypt's Ministry of Agriculture and Land Reclamation enforces maximum residue thresholds that constrain formulation flexibility for multinational suppliers serving the Nile Delta corridor.
- Natural-source tocopherol cost volatility:Premium positioning of vitamin E concentrates limits penetration among price-sensitive Nigerian and Kenyan distributor channels serving smallholder feed compounders.
- Import logistics concentration:Port-adjacent blending facility control in Morocco and Egypt creates bottleneck vulnerability for bulk antioxidant concentrate flows into North African markets.
Strategic Opportunities
- Oman and Tunisia aquaculture consolidation:Marine feed milling centralization in Muscat and Sfax creates first-mover positioning for marine-grade antioxidant formulations targeting fish oil stabilization.
- Saudi dairy natural-source transition:Reduced synthetic load preferences among Almarai and Nadec supply chains open premium positioning for tocopherol and rosemary extract alternatives.
- Automated dosing system integration:Liquid emulsion penetration into large-scale integrated poultry systems displaces manual powder handling and creates service-attachment revenue streams.
Industry Challenges
- Heat-stability performance certification timelines:Gulf Standardization Organization compliance validation for new formulations extends product launch cycles by 8-14 months.
- Cross-border shipment documentation complexity:Divergent ethoxyquin registration requirements between Egypt, Saudi Arabia, and South Africa fragment inventory pooling and increase working capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Feed Antioxidants Market |
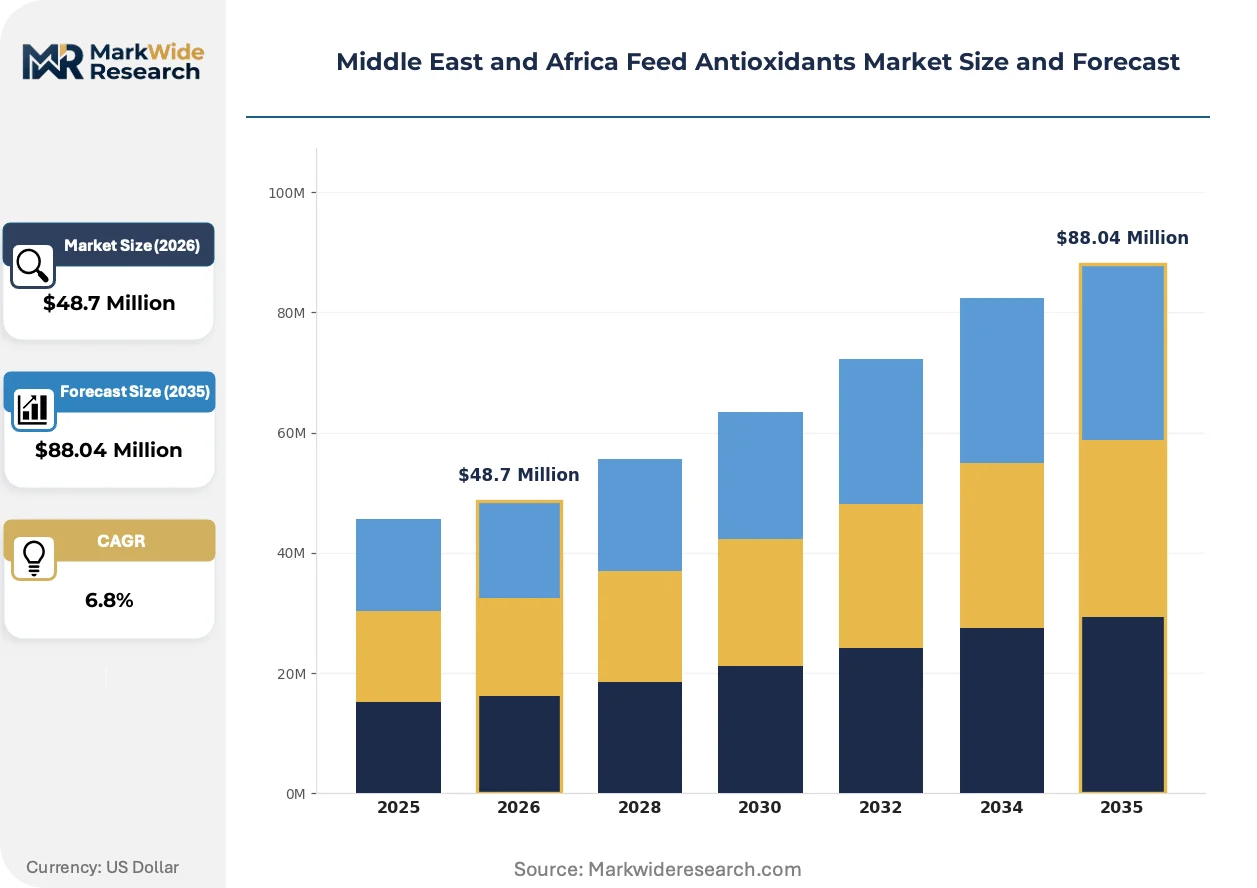
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: BHA, BHT, Tocopherols, Ethoxyquin Formulation: Powder, Liquid, Granular, Emulsion Livestock Type: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | BASF SE, Cargill Incorporated, Kemin Industries, Alltech Inc., Novus International, Layn Natural Ingredients Corp., Nutreco NV, EW Nutrition, Solvay S.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Feed Antioxidants Market Shifts & Advancements
Formulation chemistry and procurement systems are diverging simultaneously as climate pressures force technical innovation while buyer consolidation restructures channel economics across Middle Eastern and African feed markets.
Encapsulated antioxidant delivery systems are fragmenting conventional powder and liquid dichotomies. These polymer-coated microspheres protect phenolic compounds from premature degradation during pelleting temperatures exceeding 85°C. Moroccan and Egyptian poultry integrators are piloting these systems in heat-stress corridors where traditional BHT volatilization rates exceed 40 percent. The technology is fragmenting supplier tiers by requiring co-development partnerships between antioxidant houses and feed equipment manufacturers.
South Africa's Department of Agriculture is tightening mycotoxin and feed additive registration protocols that reshape import approval timelines. The new framework mandates local stability testing for all synthetic antioxidant blends, effectively blocking fast-track entry for established EU-registered products. Large-scale feed mills in Gauteng and Western Cape provinces are responding by verticalizing blending capabilities to compress regulatory exposure windows.
Buyer concentration among North African poultry integrators is compressing traditional distributor networks. Cargill, Cairo Poultry, and Wadi Group now procure antioxidants through direct manufacturer contracts with automated replenishment triggers. Independent distributors in Alexandria and Casablanca are losing volume to these captive supply arrangements. This pattern is most visible in Egypt's Nile Delta where three integrators control over 60 percent of broiler feed production.
Middle East and Africa Feed Antioxidants Market Segmentation
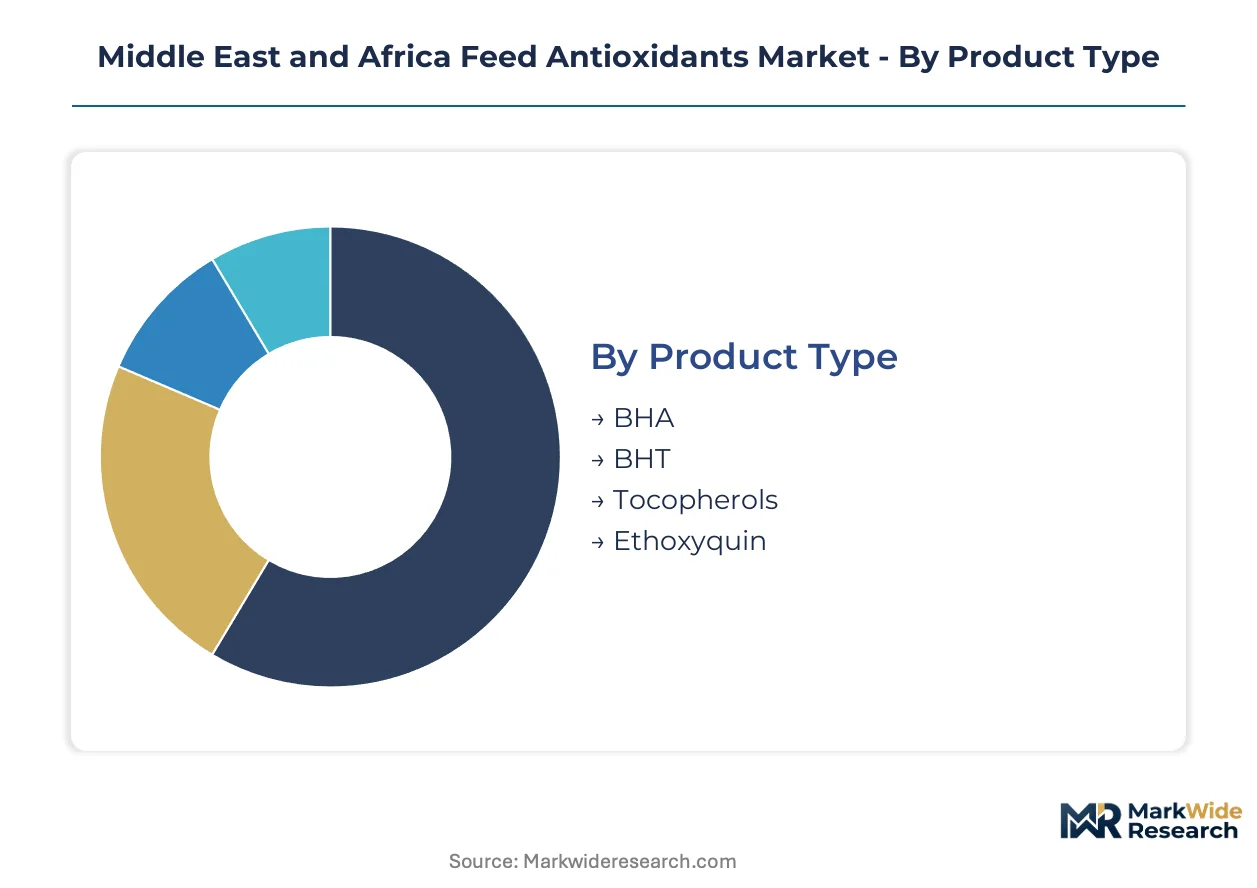
Antioxidant procurement patterns diverge sharply across the Middle East and Africa depending on livestock concentration, climate exposure, and regulatory stringency. Understanding these segment boundaries reveals where formulation investments concentrate and which channels retain pricing power.
Product Type:
Domestic demand concentrates on synthetic phenolic stabilizers across North African poultry belts, while tocopherol volumes track Saudi dairy and aquaculture export corridors serving Gulf markets.
- Ethoxyquin:Quinoline-based stabilizer dominates lipid preservation in Egyptian and Moroccan broiler operations exposed to extended storage cycles in subtropical humidity. Nile Delta integrators procure ethoxyquin through direct manufacturer contracts to manage residue compliance under Egypt's Ministry of Agriculture thresholds.
- Tocopherols:Vitamin E concentrates command premium positioning as natural-source alternatives gain regulatory preference in Saudi dairy supply chains. Almarai and Nadec operations in Riyadh and Al-Kharj drive concentrated demand for reduced synthetic load formulations.
- BHT:Synthetic phenolic antioxidant anchors volume procurement through established distribution networks spanning Cairo to Johannesburg feed mills.
- BHA:Butylated hydroxyanisole serves as secondary stabilizer in blended formulations targeting ruminant feed channels across South Africa's Gauteng province.
Ethoxyquin commands the established base across North African poultry corridors. The steepest expansion runs through tocopherols as Saudi natural-source mandates tighten.
Formulation:
Physical form selection tracks automation maturity and dosing infrastructure investment across integrated versus independent feed mill tiers.
- Powder:Dominates volume flows through Egyptian and Nigerian distributor channels serving smallholder compounders with manual handling systems. Alexandria and Lagos trading houses stock bulk powder concentrates for fragmented ruminant and backyard poultry feed producers.
- Liquid:Emulsion formats penetrate large-scale integrated poultry systems requiring automated dosing precision. Cargill's port-adjacent Moroccan facilities and Wadi Group's Nile Delta mills specify liquid delivery for continuous production lines.
- Granular:Free-flowing granules reduce dust exposure during handling in South African feed mills under stricter occupational safety protocols.
- Emulsion:Specialized liquid suspensions enable homogenous distribution in high-moisture aquaculture feeds produced in Omani and Tunisian marine milling clusters.
Powder formulations retain volume leadership across distributor-dependent channels. Liquid systems are climbing the fastest as automation investments concentrate among North African integrators.
Livestock Type:
Species-specific demand maps directly onto geographic production clusters and export orientation across the regional feed economy.
- Poultry:Broiler and layer operations in Egypt's Sharqia and Dakahlia governorates drive concentrated antioxidant procurement for heat-stress formulations. Commercial integrators now control over sixty percent of Nile Delta feed production, collapsing traditional smallholder supply channels.
- Aquaculture:Marine feed milling consolidation in Muscat and Sfax creates specialized demand for fish oil stabilizers. Omani and Tunisian operations target European export markets requiring extended shelf-life guarantees.
- Ruminants:Cattle and sheep feed channels across South Africa's Western Cape and Kenya's Rift Valley retain fragmented procurement through agricultural cooperatives.
- Swine:Limited demand concentrates in non-Muslim majority markets with South African and Ethiopian operations representing primary consumption pockets.
Poultry applications anchor regional volume. Aquaculture is gaining share fastest as Gulf marine export corridors mature.
Distribution Channel:
Channel structure is bifurcating between captive direct arrangements and eroding independent distributor networks.
- Direct Sales:Cargill, Cairo Poultry, and Wadi Group procure through manufacturer contracts with automated replenishment triggers, bypassing traditional Alexandria and Casablanca trading houses.
- Distributors:Independent networks retain relevance in Nigerian and Kenyan smallholder corridors where fragmented compounders lack volume leverage.
- Retail:Agricultural supply stores serve backyard poultry producers across Morocco's Atlas foothills and Ethiopia's highland regions.
- Online:Digital procurement platforms emerge in South African and UAE markets serving mid-scale feed operations seeking price transparency.
Direct sales channels are consolidating control among integrated operators. Distributor networks face steepest compression as buyer concentration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egyptian feed antioxidant exports flow primarily to Saudi Arabia and UAE poultry integrators, establishing a north-south trade corridor that shapes procurement patterns across the Middle East and Africa region.
Egypt
Nile Delta broiler operations in Sharqia and Dakahlia governorates drive concentrated demand for ethoxyquin-based lipid stabilizers. The Ministry of Agriculture and Land Reclamation enforces maximum residue thresholds that constrain formulation flexibility for multinational suppliers. Cairo Poultry and Wadi Group control over sixty percent of regional feed production, collapsing traditional distributor networks through direct manufacturer contracts.
Saudi Arabia
Almarai and Nadec dairy supply chains generate premium demand for tocopherol alternatives to synthetic antioxidant loads. The Saudi Food and Drug Authority aligns with Gulf Standardization Organization feed safety benchmarks, creating compliance urgency for heat-stable formulations. Riyadh and Al-Kharj processing clusters anchor procurement concentration for natural-source stabilizers serving export-oriented dairy operations.
South Africa
Gauteng and Western Cape feed mills respond to stricter mycotoxin control rules with synthetic antioxidant blend adoption. The Department of Agriculture, Land Reform and Rural Development mandates local stability testing for all imported antioxidant formulations, blocking fast-track entry for EU-registered products. Large-scale mills verticalize blending capabilities to compress regulatory exposure windows.
Morocco
Commercial poultry integrators expand antioxidant procurement through port-adjacent facilities controlling import logistics for bulk concentrates. Cargill leverages Casablanca-adjacent blending infrastructure to manage North African distribution flows. Heat-stress formulations gain priority as climate adaptation drives technical specification changes across integrated broiler operations.
United Arab Emirates
Digital procurement platforms emerge in Dubai and Abu Dhabi serving mid-scale feed operations seeking price transparency. MOHAP feed safety protocols create compliance complexity for cross-border antioxidant shipments from Egyptian and Saudi suppliers. The emirates function as a re-export hub for antioxidant formulations destined for Omani and Tunisian aquaculture milling clusters.
Middle East and Africa Feed Antioxidants Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and distribution reach, producing a tiered structure where scale-driven multinationals anchor synthetic antioxidant supply while regional specialists capture natural-source niches. Three archetypes dominate: integrated chemical conglomerates with backward control into phenolic feedstock production, crop-science specialists leveraging plant-extraction expertise for tocopherol concentrates, and port-adjacent blenders controlling import logistics for bulk concentrate flows. Competitive moves concentrate on automated dosing system partnerships and heat-stability certification acceleration.
Within the integrated chemical tier, BASF SE anchors synthetic antioxidant supply through established BHT and ethoxyquin distribution networks spanning Cairo to Johannesburg. Cargill Incorporated exemplifies the port-adjacent blender archetype, leveraging Moroccan facilities to control North African import logistics. Kemin Industries occupies the specialist position, differentiating through heat-stable formulation expertise tailored to Gulf Cooperation Council climate conditions.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Kemin Industries |
| Alltech Inc. |
| Novus International |
| Layn Natural Ingredients Corp. |
| Nutreco NV |
| EW Nutrition |
| Solvay S.A. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Nile Delta poultry integrators and antioxidant manufacturers lock in supply access while fixing price visibility through multi-year volume commitments indexed to phenolic feedstock benchmarks. These arrangements insulate large-scale operators from spot market volatility in ethoxyquin concentrates while constraining formulation flexibility under Egypt's residue thresholds.
Pricing Analysis
Current-generation heat-stable formulations command 15-25% premia over prior-generation BHT-based stabilizers, while next-generation encapsulated delivery systems remain in pilot pricing with limited commercial scale. Three-tier pricing structure across premium, standard, and economy levels separates Gulf-certified natural-source tocopherols from North African synthetic blends and Nigerian powder concentrates. Cost compression in standard-tier phenolic antioxidants is intensifying because Moroccan port-adjacent blending facilities concentrate import leverage among three multinationals. Smallholder feed compounders through Lagos and Alexandria distributor channels exhibit highest price sensitivity, while Saudi dairy integrators show least elasticity for natural-source certifications.
Supply Chain Analysis
China and India anchor bulk phenolic feedstock production for synthetic antioxidant precursors, while Germany and Switzerland concentrate high-purity tocopherol extraction for natural-source formulations. The regional supply chain draws from Asian chemical intermediates, European vitamin concentrates, and local North African blending infrastructure. Single-source vulnerability runs through Casablanca and Alexandria port complexes where customs clearance delays cascade to feed mill production schedules. Distribution runs through direct manufacturer contracts with automated replenishment systems displacing traditional trading house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise in heat-stable antioxidant systems remains scarce relative to procurement demand from Gulf climate adaptation mandates, creating asymmetric returns for specialists who bridge technical performance with regulatory compliance acceleration.
For Market Incumbents: Secure backward integration into phenolic feedstock production to defend margin position against Asian chemical intermediate volatility. Accelerate Gulf Standardization Organization certification timelines for encapsulated delivery systems before Egyptian integrators complete automation retrofits, locking in service-attachment revenue streams that resist price commoditization. For New Entrants and Emerging Players: Lead with marine-grade antioxidant formulations targeting Omani and Tunisian aquaculture consolidation where established poultry-focused suppliers lack technical credibility. White-space concentration exists in automated dosing system integration partnerships, particularly for liquid emulsion formats serving mid-scale Egyptian feed mills below Wadi Group and Cairo Poultry procurement thresholds. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among port-adjacent blending specialists with captive logistics control and long-term offtake contracts. Long-term viability over the next decade hinges on heat-stability certification asset bases rather than commodity phenolic distribution. The signal to watch is Gulf Cooperation Council climate mandate acceleration triggering procurement urgency for next-generation formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Stability Certification Investment | SFDA alignment with GSO benchmarks creates 8-14 month first-mover windows for compliant suppliers. |
| Backward Integration into Phenolic Feedstocks | Captive supply of BHT and ethoxyquin precursors insulates margin compression from Asian intermediate volatility. |
| Encapsulated Delivery System Co-Development | Polymer-coated microsphere partnerships with feed equipment manufacturers fragment supplier tiers by technical capability. |
| Automated Dosing System Integration | Liquid emulsion service attachments displace manual powder handling in Nile Delta integrated poultry operations. |
| Aquaculture Formulation Specialization | Marine-grade fish oil stabilizers target Muscat and Sfax milling clusters serving European export shelf-life requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, feed additive registration filings with Egypt's Ministry of Agriculture and South Africa's Department of Agriculture, and Gulf Standardization Organization technical benchmarks. Primary interviews engaged feed mill procurement directors, antioxidant formulation chemists, and port logistics operators across Casablanca, Alexandria, and Durban corridors. Secondary validation drew from SEC filings of listed chemical conglomerates, ACC regional chemical trade reports, and import duty records. Bottom-up volume estimates from individual feed mill consumption patterns triangulate against top-down market sizing from regional livestock production statistics.
Segmentation dimensions modeled span product type (ethoxyquin, tocopherols, BHT, BHA), physical formulation (powder, liquid, granular, emulsion), livestock application (poultry, aquaculture, ruminant, swine), and distribution channel structure (direct sales, distributor networks, retail, digital platforms). CAGRs were derived from regression analysis of historical procurement volumes against livestock production forecasts and climate adaptation policy implementation timelines. Industry-specific forecast inputs include mycotoxin control regulatory stringency indices and automation penetration rates among North African poultry integrators.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Cooperation Council climate mandate enforcement or accelerated Egyptian ethoxyquin residue threshold tightening would require recalibration. Forecasts reflect assumptions about feed mill verticalization trends and natural-source certification pathway maturation. Recalibration cycles align with material shifts in SFDA regulatory alignment schedules and South African import approval framework revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Testosterone Booster Supplements Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Vitamins Gummies Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Selenium Yeast Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Insoluble Dietary Fibers Market