
 Apple Extract Market | 2026-2036
Apple Extract Market Size, Share, and Industry Trends Forecast 2026-2036
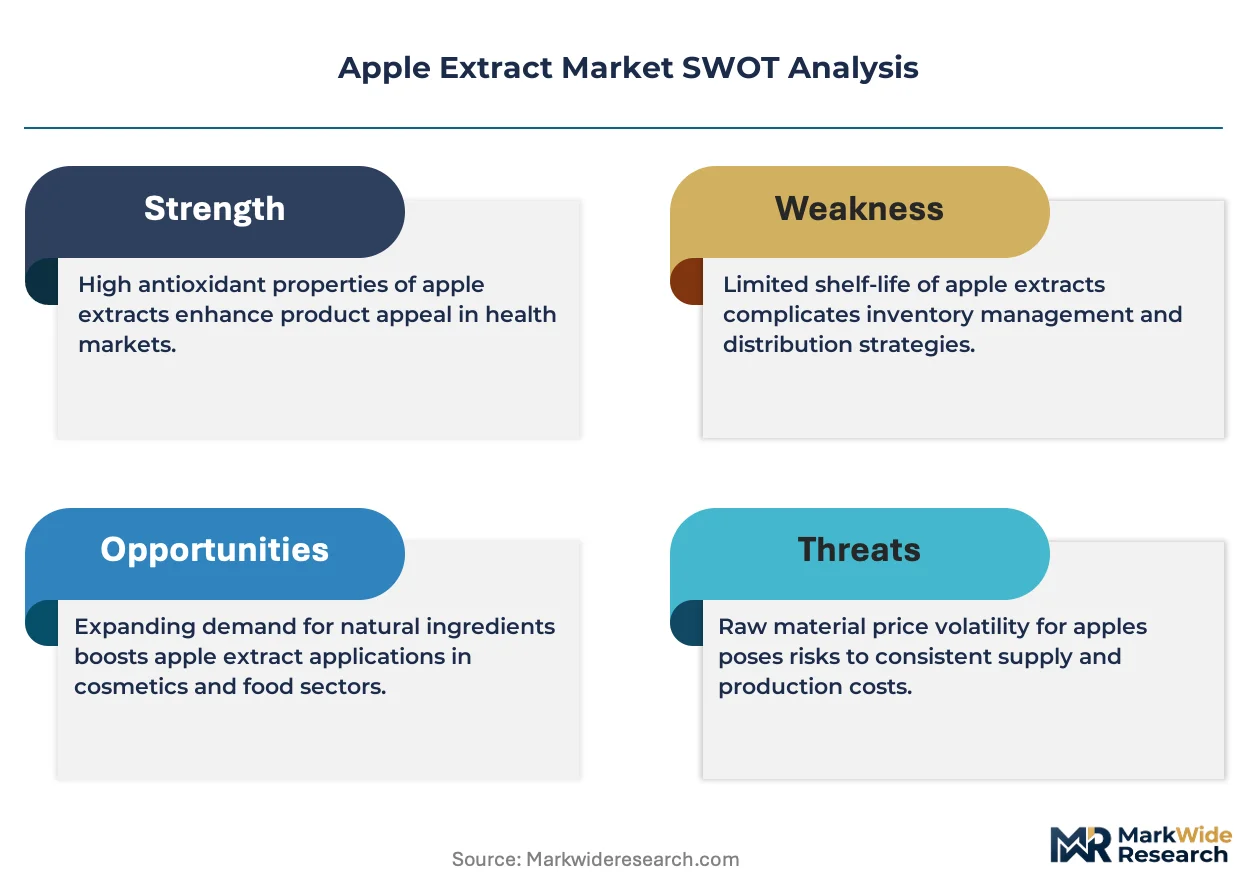
Apple Extract Market Analysis
Functional beverage formulators are unwinding legacy reliance on synthetic flavor systems, redirecting procurement toward polyphenol-standardized apple extracts. Kerry Group leverages its integrated taste and nutrition platform to supply clean-label extracts across European and North American bottling networks. Döhler GmbH anchors its position through captive orchards and proprietary gentle extraction processes that preserve volatile aromatic compounds. Tree Top Inc. competes on Washington State apple supply security and vertical control from concentrate through extract refinement.
Apple extract comprises bioactive concentrates derived from Malus domestica fruit through aqueous, ethanolic, or supercritical CO₂ extraction, yielding standardized polyphenol, chlorogenic acid, or procyanidin fractions for flavor, color stability, or antioxidant functionality. Powder extract commands premium positioning due to superior shelf stability and ease of dosing in dry-blend dietary supplements, while liquid extract dominates beverage applications where solubility and rapid dispersion matter. The nutraceuticals end-user channel represents the fastest-expanding margin pool as supplement brands seek substantiated polyphenol content for cardiovascular and metabolic positioning.
FDA GRAS self-affirmation pathways and EFSA Novel Food dossier requirements shape market access timelines and substantiation costs for new extract entrants. BIS FSSAI alignment on pesticide residue limits and heavy metal thresholds governs import eligibility for Indian suppliers serving domestic pharmaceutical and cosmetic compounders. Stakeholders must monitor evolving health claim enforcement intensity in Europe and emerging U.S. state-level clean-label legislation that could accelerate synthetic displacement timelines.
Market Dynamics
Functional beverage formulators are unwinding legacy reliance on synthetic flavor systems, redirecting procurement toward polyphenol-standardized apple extracts. This structural shift concentrates purchasing power among ingredient houses capable of delivering clean-label substantiation and supply security simultaneously.
Growth Catalysts
- EFSA Novel Food dossier pathways:Accelerated approvals for polyphenol-rich extracts are unlocking premium positioning in European nutraceutical channels, with standardized procyanidin content becoming a de facto quality gate.
- Supercritical CO₂ extraction adoption:German and Austrian equipment suppliers are deploying non-thermal processing that preserves volatile aromatic compounds, enabling flavor-house clients to reduce synthetic additive loads.
- Washington State orchard consolidation:Captive apple supply chains in the Pacific Northwest are securing year-round raw material availability for concentrate-to-extract verticals serving North American beverage networks.
Market Restraints
- Ethanol input cost volatility:Conventional ethanolic extraction remains dependent on grain alcohol pricing, squeezing margin structures for mid-tier suppliers without solvent recovery infrastructure.
- EU Novel Food Regulation compliance burden:EFSA dossier preparation costs and 18-month approval timelines create capital barriers for new extract entrants seeking polyphenol standardization claims.
- Green tea polyphenol substitution:Catechin-standardized extracts from Camellia sinensis compete directly on antioxidant positioning, particularly in Asian cosmetic and supplement formulator procurement.
Strategic Opportunities
- Indian pharmaceutical compounder channel:BIS FSSAI alignment on pesticide residue limits is streamlining import eligibility for extract suppliers targeting domestic Ayurvedic and allopathic formulation houses.
- Metabolic health positioning:Emerging clinical substantiation for chlorogenic acid fractions is opening cardiovascular and glycemic management applications in functional food segments.
- Direct-to-supplement-brand distribution:E-commerce platforms are disintermediating traditional ingredient broker networks, enabling extract houses to capture margin previously allocated to distribution intermediaries.
Industry Challenges
- Analytical chemistry capability gaps:Polyphenol quantification and procyanidin polymer characterization require HPLC-MS infrastructure that smaller extract houses struggle to maintain in-house.
- GRAS self-affirmation timeline compression:FDA notification preparation for new extract specifications demands toxicological and exposure assessment expertise that stretches regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apple Extract Market |
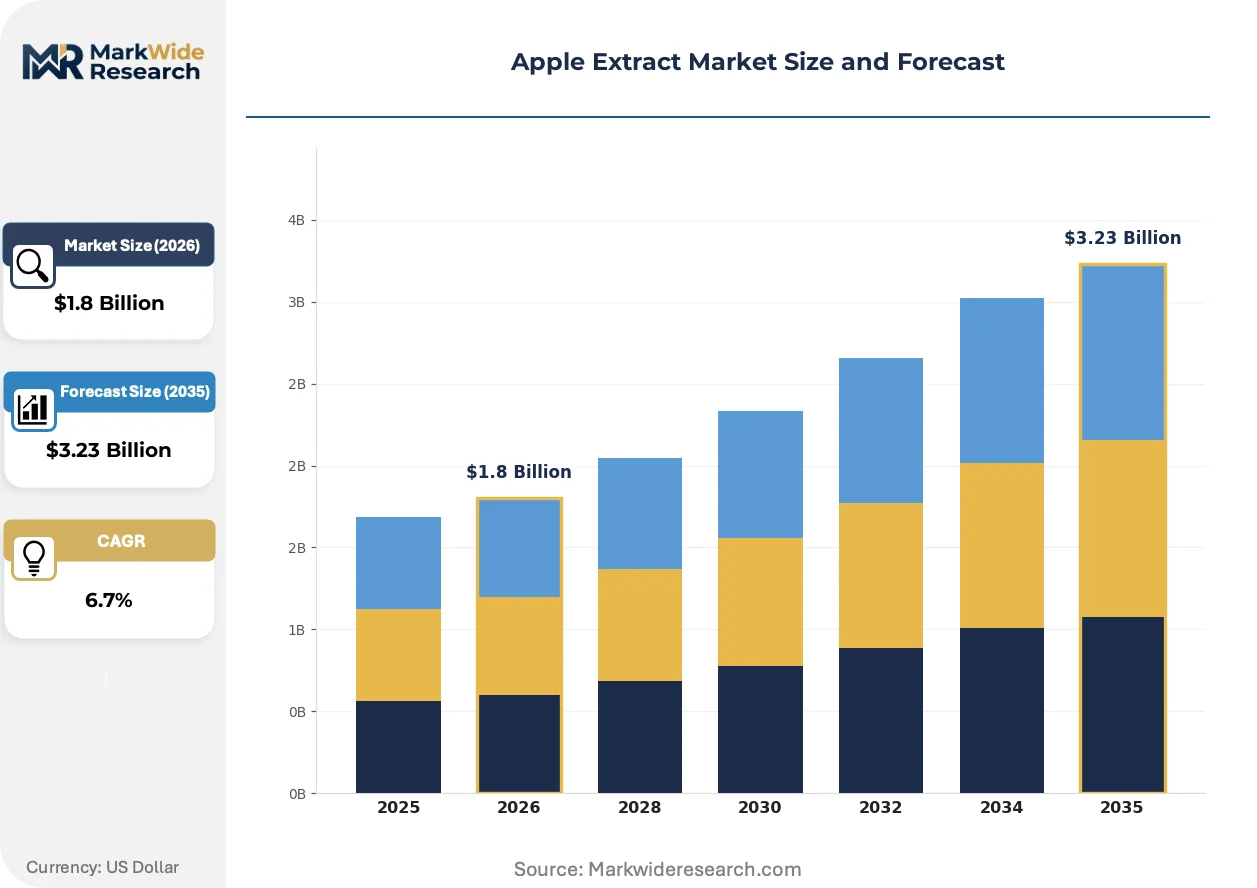
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Concentrate, Whole Fruit Powder End User: Cosmetics, Pharmaceuticals, Food & Beverage, Nutraceuticals Application: Skin Care, Dietary Supplements, Functional Foods, Beverages Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Kerry Group, Ingredion, Tree Top Inc., Glanbia Nutritionals, Naturex, Döhler GmbH, International Flavors & Fragrances, Kuber Impex, AGRANA Beteiligungs-AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apple Extract Market Emerging Trajectories
Extraction technology and regulatory substantiation requirements are actively reshaping competitive capabilities in apple-derived ingredients. Suppliers must now integrate gentle processing expertise with dossier-ready clinical data generation.
Supercritical CO₂ extraction is bifurcating the supplier base between capital-intensive specialists and conventional solvent operators. Premium beverage formulators in Germany and Switzerland are specifying non-thermal processed extracts for volatile compound retention. This technology compression is forcing mid-tier houses to outsource toll processing or exit high-margin aromatic extract segments entirely.
EFSA health claims enforcement intensity is tightening purity benchmarks for polyphenol standardization. Extract houses must now maintain batch-level chlorogenic acid certification to support antioxidant positioning in European supplement channels. Nutraceutical brands are responding by consolidating supplier relationships toward integrated taste-and-nutrition platforms with captive analytical laboratories.
Formulator procurement patterns are rotating toward outcome-based specification contracts. Supplement brands in North America are replacing commodity concentrate purchases with polyphenol-guaranteed extract agreements tied to finished-product stability performance. This shift is most visible among direct-to-consumer brands operating subscription models where batch consistency drives retention economics.
Apple Extract Market Segmentation
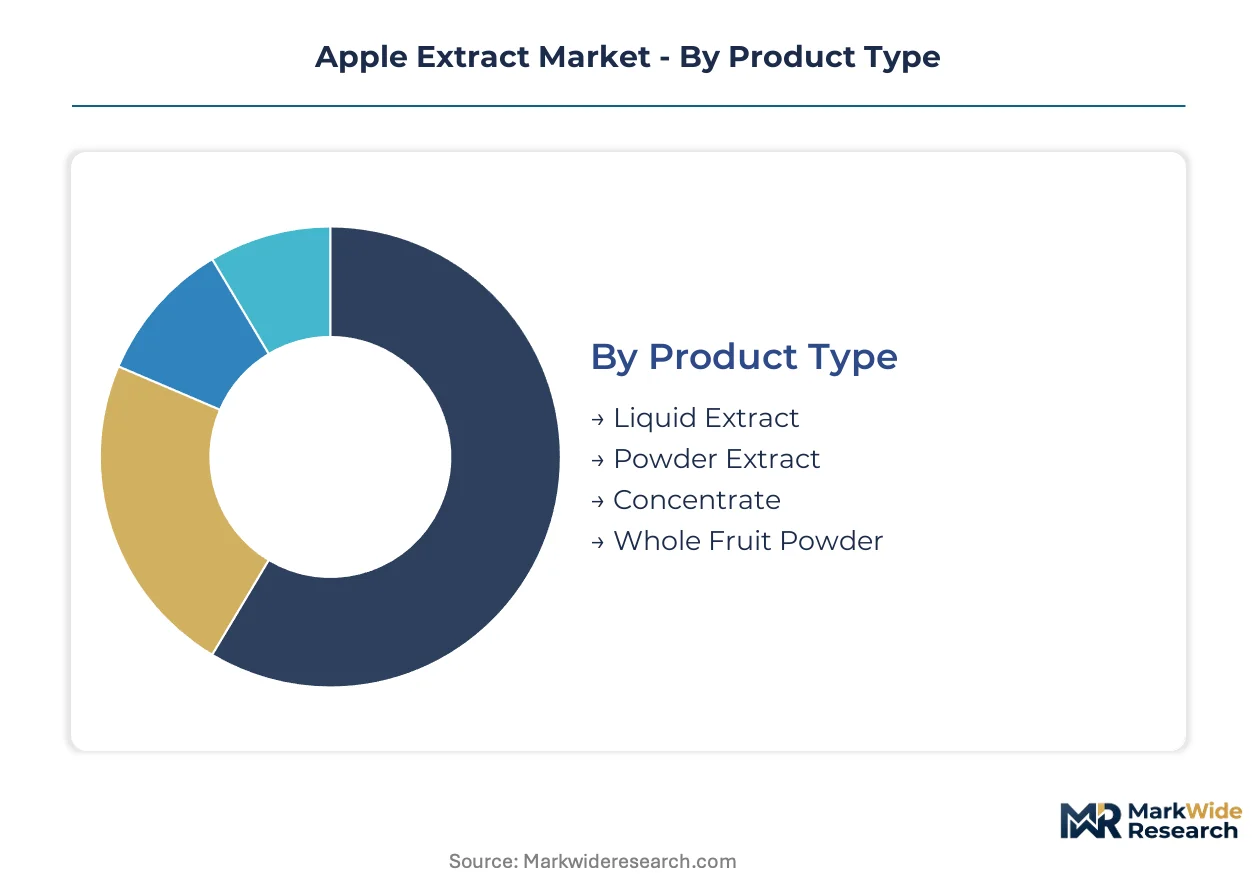
Apple extract procurement patterns diverge sharply across product formats and end-use channels, with regulatory substantiation requirements dictating supplier selection criteria. Formulators prioritize batch-level polyphenol certification in premium segments while cost-sensitive applications tolerate broader specification ranges.
Product Type:
EFSA Novel Food dossier requirements and FDA GRAS pathways create divergent compliance burdens across physical formats, with powder extracts commanding premium positioning due to analytical traceability advantages.
- Liquid Extract:Aqueous or ethanolic solutions standardized for chlorogenic acid content, optimized for rapid dispersion in beverage matrices. German beverage formulators specify supercritical CO₂ processed variants for volatile aromatic retention in clean-label sparkling applications.
- Powder Extract:Spray-dried or freeze-dried concentrates with defined procyanidin polymer distribution, preferred for dry-blend dietary supplements where dosing precision and shelf stability determine formulation economics. North American nutraceutical brands increasingly mandate HPLC-MS batch certification.
- Concentrate:High-Brix apple juice concentrates serving as cost-effective flavor and color substrates in conventional food processing, with limited polyphenol standardization.
- Whole Fruit Powder:Dehydrated Malus domestica fruit matrices retaining fiber and pectin fractions, positioned in functional food segments seeking whole-food ingredient claims.
Established volume favors Concentrate; emerging adoption favors Powder Extract.
End User:
Margin structures and specification intensity vary dramatically across customer categories, with pharmaceutical compounders imposing the most stringent analytical requirements.
- Cosmetics:Antioxidant and skin-brightening applications in topical formulations, with French and German dermocosmetic houses driving demand for chlorogenic acid standardized fractions.
- Pharmaceuticals:Active pharmaceutical ingredient precursors and excipient applications requiring full impurity profiling and ICH Q3D elemental compliance, particularly in Indian allopathic formulation houses.
- Food & Beverage:Clean-label flavor systems and natural color stabilization in processed foods, where EFSA health claim enforcement intensity shapes antioxidant positioning strategies.
- Nutraceuticals:Polyphenol-standardized extracts for cardiovascular and metabolic health positioning, climbing the fastest as direct-to-consumer subscription brands consolidate supplier relationships toward integrated platforms.
Current revenue concentration sits with Food & Beverage; steepest expansion trajectory belongs to Nutraceuticals.
Application:
Functional performance requirements and regulatory exposure determine extract specification tiers, with skin care and supplement channels demanding the most rigorous substantiation packages.
- Skin Care:Topical antioxidant and anti-aging formulations leveraging procyanidin fractions for collagen protection claims, with South Korean and French cosmetic laboratories specifying low-molecular-weight polyphenol profiles.
- Dietary Supplements:Capsule and tablet applications requiring precise polyphenol dosing per serving, where FDA GRAS self-affirmation and EFSA Novel Food status serve as procurement gates.
- Functional Foods:Bakery, dairy, and confectionery applications incorporating apple extract for natural sweetness modulation and shelf-life extension.
- Beverages:Functional and flavored drink applications where liquid extract solubility and rapid dispersion characteristics dominate supplier selection.
Volume leadership remains with Beverages; margin expansion concentrates in Dietary Supplements.
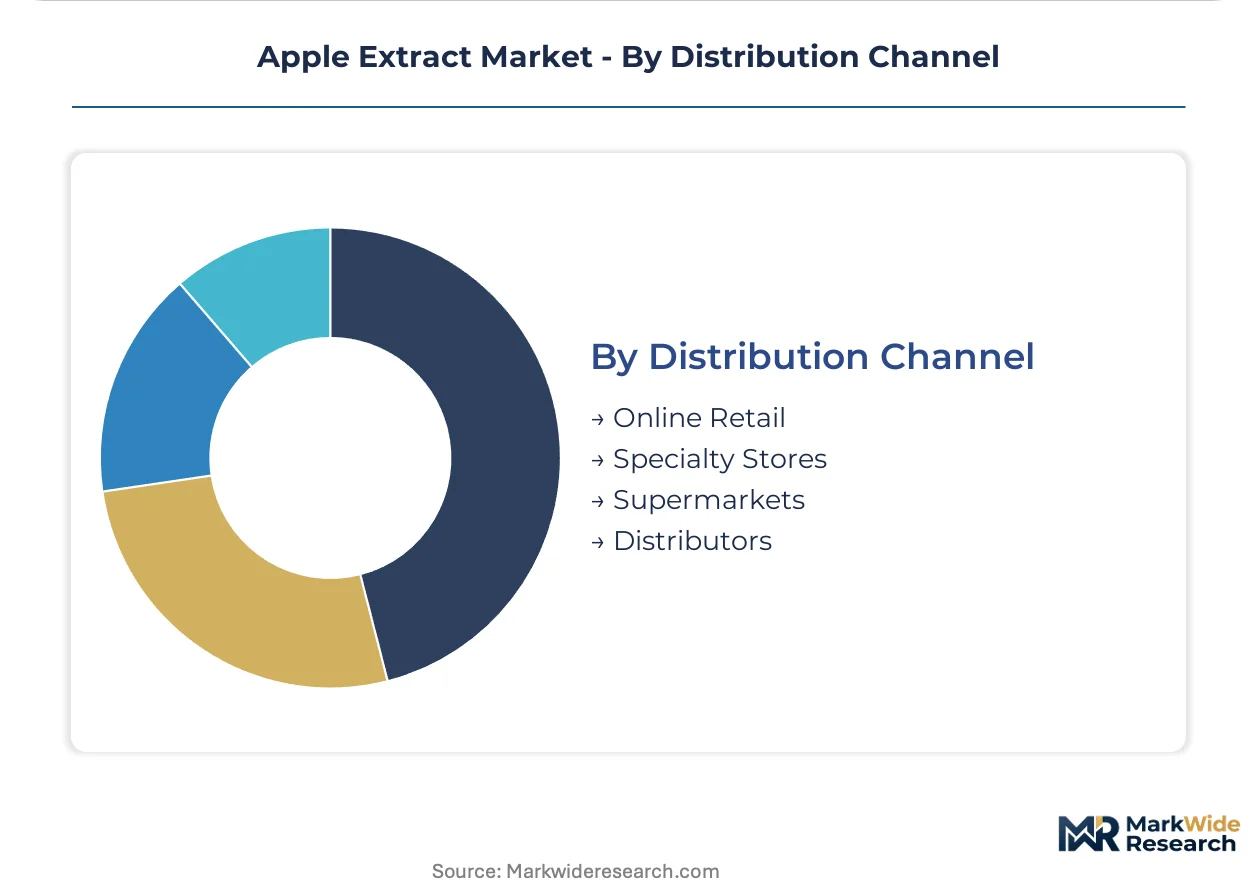
Distribution Channel:
Channel economics reflect customer scale and technical service intensity, with specialty intermediaries retaining importance for complex specification negotiations.
- Online Retail:Direct-to-consumer and small-scale formulator procurement, disintermediating traditional broker networks and enabling extract houses to capture margin previously allocated to distribution intermediaries.
- Specialty Stores:Regional ingredient distributors serving mid-tier supplement and cosmetic compounders with technical support and smaller minimum order quantities.
- Supermarkets:Mass-market retail procurement for consumer-facing whole fruit powder and basic concentrate products.
- Distributors:Traditional ingredient broker networks maintaining relevance for multinational food and beverage manufacturers requiring integrated supply chain services.
Legacy volume flows through Distributors; channel shift momentum favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Captive apple supply chains in the Pacific Northwest and Central European orchard belts concentrate extract processing capacity. EFSA Novel Food dossier requirements and FDA GRAS pathways create divergent compliance burdens across production zones. Formulator procurement patterns favor suppliers with integrated analytical laboratories and captive raw material security.
United States
Washington State orchard consolidation secures year-round raw material availability for concentrate-to-extract verticals. FDA GRAS self-affirmation pathways govern market access timelines for new polyphenol specifications. Yakima Valley processing clusters serve North American beverage networks with integrated taste-and-nutrition platforms.
Germany
Ingredient houses in Bavaria and Baden-Württemberg anchor Central European procurement for polyphenol-standardized extracts. EFSA Novel Food Regulation compliance and evolving health claims criteria tighten purity benchmarks for suppliers. Supercritical CO₂ equipment suppliers in the Stuttgart region deploy non-thermal processing for volatile aromatic retention.
India
Domestic pharmaceutical compounders in Maharashtra and Gujarat drive import demand for chlorogenic acid standardized fractions. BIS FSSAI alignment on pesticide residue limits and heavy metal thresholds governs extract eligibility. Mumbai-based formulation houses serve Ayurvedic and allopathic channels with tightening analytical requirements.
China
Provincial apple processing clusters in Shandong and Shaanxi supply cost-competitive concentrate intermediates. GB standards on food additive specifications and SAMR registration requirements shape export eligibility. Zhengzhou equipment fabricators supply supercritical extraction systems to domestic and Southeast Asian markets.
France
Dermocosmetic laboratories in the Île-de-France region specify chlorogenic acid fractions for antioxidant and skin-brightening applications. ANSM and CNIL oversight of cosmetic ingredient safety creates substantiation requirements for topical extract positioning. Lyon-based flavor houses procure gentle-processed extracts for clean-label sparkling beverage formulations.
Apple Extract Market Vendor Landscape
Concentration sits with integrated taste-and-nutrition platforms and orchard-backed extraction specialists. The supplier base stratifies between capital-intensive supercritical CO₂ operators and conventional solvent processors. Three archetypes dominate: integrated ingredient houses with captive analytical capabilities, orchard-controlled processors with vertical raw material security, and specialty distributors with technical service intensity. Competitive moves center on M&A for laboratory infrastructure and strategic partnerships for toll processing access.
Within the integrated platform tier, Kerry Group and Döhler GmbH exemplify the convergence of taste technology and nutritional substantiation capabilities. Among orchard-backed processors, Tree Top Inc. occupies a position tied to Pacific Northwest supply security. Specialty chemical distributors including Kuber Impex sit within the import-export intermediary layer serving mid-tier compounders with smaller minimum order quantities and regional regulatory navigation.
| Leading Market Players |
|---|
| Kerry Group |
| Ingredion |
| Tree Top Inc. |
| Glanbia Nutritionals |
| Naturex |
| Döhler GmbH |
| International Flavors & Fragrances |
| Kuber Impex |
| AGRANA Beteiligungs-AG |
| Others |
Supply Flow & Price Mechanics
EFSA Novel Food Regulation compliance gates both supply qualification and price differentiation in European apple extract procurement, forcing suppliers to absorb dossier preparation costs that stratify the competitive field between capitalized integrated platforms and conventional solvent operators.
Pricing Analysis
EFSA Novel Food dossier requirements dictate the pricing tier structure across the apple extract market, separating GRAS-affirmed North American suppliers from European novel food authorized houses. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, with HPLC-MS batch certification commanding substantial premia over basic concentrate offerings. Cost compression in mid-tier ethanolic extraction is intensifying because grain alcohol input volatility squeezes margin structures for operators lacking solvent recovery infrastructure. Nutraceutical brands exhibit the least price sensitivity due to subscription retention economics, while conventional beverage formulators remain highly price-sensitive and tolerate broader specification ranges.
Supply Chain Analysis
Strategic stockpiling of Washington State apple inventories dominates over just-in-time preferences, as Pacific Northwest orchard consolidation secures year-round raw material availability for concentrate-to-extract verticals. Supply concentrates in the United States, Germany, and China, with Shandong processing clusters feeding cost-competitive concentrate intermediates and Bavarian ingredient houses anchoring Central European procurement. The supply chain draws from apple pomace, grain alcohol, and supercritical CO₂ equipment as critical inputs. Single-source vulnerability around Washington State orchard ownership concentration poses structural risk. Distribution runs through integrated taste-and-nutrition platforms serving multinational beverage networks, supplemented by specialty chemical distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apple extract procurement is consolidating toward platform-economics dynamics where integrated taste-and-nutrition houses capture margin through analytical laboratory captivity and raw material security, displacing fragmented broker networks.
For Market Incumbents: Secure captive orchard supply through backward integration into Washington State or Central European growing regions, insulating against raw material volatility that threatens mid-tier competitors. Invest in supercritical CO₂ processing capacity to defend against green tea polyphenol substitution in antioxidant-positioned applications. Lock in long-term offtake agreements with direct-to-consumer nutraceutical brands whose subscription models prioritize batch consistency over spot pricing. For New Entrants and Emerging Players: Differentiate on chlorogenic acid standardization for metabolic health positioning, where emerging clinical substantiation creates white-space before incumbent dossier completion. Target Indian pharmaceutical compounders in Maharashtra and Gujarat, where BIS FSSAI alignment streamlines import eligibility and analytical requirements remain less stringent than European pharmaceutical channels. Pursue toll processing partnerships with German equipment suppliers to bypass capital barriers for supercritical CO₂ infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO₂ extraction segments, favoring acquisition of orchard-backed processors with existing gentle processing capabilities over greenfield capacity builds. Prioritize targets with captive analytical laboratories and EFSA Novel Food authorization status, as regulatory substantiation assets compound in scarcity value. Watch EFSA health claim enforcement intensity as the signal for premium tier margin expansion or compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Assets | Washington State consolidation secures year-round pomace supply for extract refinement. |
| Supercritical CO₂ Capacity Expansion | Stuttgart equipment suppliers enable non-thermal processing for volatile aromatic retention. |
| EFSA Novel Food Dossier Investment | Authorization unlocks premium positioning in European nutraceutical procurement channels. |
| Direct-to-Consumer Distribution Buildout | E-commerce platforms disintermediate broker networks and capture intermediate margin. |
| Analytical Laboratory Captivity | In-house HPLC-MS infrastructure supports batch-level polyphenol certification requirements. |
Methodological Framework
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings in this apple extract market analysis. Conversations with extraction technology directors, procurement leads at German beverage formulators, regulatory affairs specialists at Indian pharmaceutical compounders, and supply chain managers at Pacific Northwest orchard processors informed demand-side dynamics. Secondary validation drew from EFSA Novel Food register entries, FDA GRAS notification letters, BIS FSSAI circulars on pesticide residue limits, and customs trade data for apple concentrate flows. Bottom-up procurement pattern analysis triangulated against top-down value chain sizing across powder extract, liquid extract, concentrate, and whole fruit powder categories.
Sensitivity analysis around ethanol input cost volatility, EFSA approval timeline compression, and Washington State orchard ownership concentration tested forecast robustness across the projection horizon. The analytical framework modeled segmentation dimensions including product format physical state, end-user channel margin structure, application functional requirements, and distribution channel technical service intensity. CAGRs derived from polynomial trend fitting against historical procurement volumes, adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated supercritical CO₂ equipment deployment rates and direct-to-consumer nutraceutical brand subscription growth curves.
The analysis sits within stated boundaries; outcomes outside sustained EFSA health claim enforcement intensity or accelerated FDA GRAS pathway streamlining would require recalibration. Forecasts reflect documented assumptions regarding orchard yield stability and extraction technology diffusion rates. Revision becomes warranted when green tea polyphenol substitution rates in Asian cosmetic procurement cross thresholds that compress apple extract antioxidant positioning premia.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Milk Ingredients Market
Ingredients
North America Dairy Protein Market
Ingredients
Ahiflower Oil Market
Ingredients
North America Cocoa Products Market
Ingredients
Savory Ingredients Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Coconut Oil Market
Ingredients
Plant Based Ingredients Market
Ingredients
Cold Water Swelling Starch Market
Ingredients
High Oleic Oil Market
Ingredients
Marine Ingredients Market
Ingredients
Mannan-Oligosaccharide (MOS) Market
Ingredients
Pet Food Premix Market
Ingredients
Soy Hydrolysates Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Spain Fermentation Ingredients Market