
 Coconut Oil Based Products Market | 2026-2036
Coconut Oil Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Oil Based Products Market Insights
REACH compliance is pivoting the cost-of-entry calculus for coconut oil based products entering European personal care channels. Cargill leverages its integrated supply chain from Southeast Asian copra sourcing to refined oil output. Marico anchors its position through specialized hair oil formulations that dominate South Asian household consumption. Nutiva differentiates via organic certification and cold-pressed processing standards that command premium shelf placement.
Coconut oil based products encompass refined, virgin, and fractionated oils extracted from copra or fresh coconut meat, with lauric acid content typically ranging from 45% to 53% and melting points near 24°C determining application suitability. These products serve as functional ingredients in food preparation, emollient bases in topical formulations, and feedstocks for oleochemical derivatives. The personal care application segment leads value generation due to premium positioning of coconut-derived surfactants and moisturizers, while pharmaceutical-grade fractions represent the fastest-growing margin pool as compendial standards tighten. Edible oil remains the highest-volume product type though price compression intensifies in bulk commodity grades.
The FDA governs cosmetic ingredient safety through the Federal Food, Drug, and Cosmetic Act while the EPA oversees pesticide residue limits in imported copra. ECHA enforces REACH registration for oleochemical derivatives entering EU formulations, and BIS certification requirements in India affect export-ready refining investments. Stakeholders must monitor evolving MEE environmental discharge standards in China and dual carbon compliance timelines that will reshape processing energy costs across major supply bases. The critical decision horizon centers on whether to invest in fractionation capacity or outsource to established Southeast Asian refiners.
Market Dynamics
Processing capacity consolidation in Southeast Asian copra clusters is restructuring competitive access to lauric acid feedstocks, forcing formulators to secure offtake agreements or build captive refining capabilities.
Growth Catalysts
- REACH registration mandates:ECHA's expanded substance evaluation for oleochemical derivatives is accelerating compliant supplier qualification, locking in preferred vendor relationships for European personal care channels.
- Pharmaceutical-grade fractionation:Compendial standard tightening for lauric acid purity is opening dedicated capacity investments for injectable-grade coconut oil derivatives.
- Indonesia-Philippines processing clusters:Integrated copra crushing and refining infrastructure is concentrating cost-competitive supply for global surfactant manufacturers.
Market Restraints
- Copra price volatility:Weather-driven coconut harvest fluctuations in the Philippines and Indonesia transmit directly to raw material cost instability for refiners without backward hedging mechanisms.
- Fractionation yield ceilings:Technical limits on separating high-purity MCT fractions from standard coconut oil cap output rates at approximately 12-15%, constraining pharmaceutical-grade supply expansion.
- Palm kernel oil substitution:Malaysian and Indonesian palm kernel stearin offers equivalent lauric acid profiles at 15-20% lower input costs for commodity surfactant applications.
Strategic Opportunities
- Indian ayurvedic personal care:Domestic hair oil consumption patterns create formulation partnerships with BIS-certified refiners for export-ready ayurvedic positioning.
- China dual carbon compliance:MEE environmental discharge standards are incentivizing solvent-free cold-pressing investments that command premium positioning in domestic clean-label channels.
- E-commerce direct-to-consumer:Cold-pressed virgin oil brands are bypassing traditional retail slotting fees through subscription models targeting wellness-oriented households.
Industry Challenges
- Skilled fractionation engineering:Shortage of process engineers capable of optimizing molecular distillation for pharmaceutical-grade MCT purity is extending commissioning timelines for new capacity.
- Multi-jurisdiction certification sequencing:Simultaneous pursuit of USP-NF, EP, and JP compendial approvals requires 18-24 month regulatory timelines that strain working capital for mid-scale refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Oil Based Products Market |
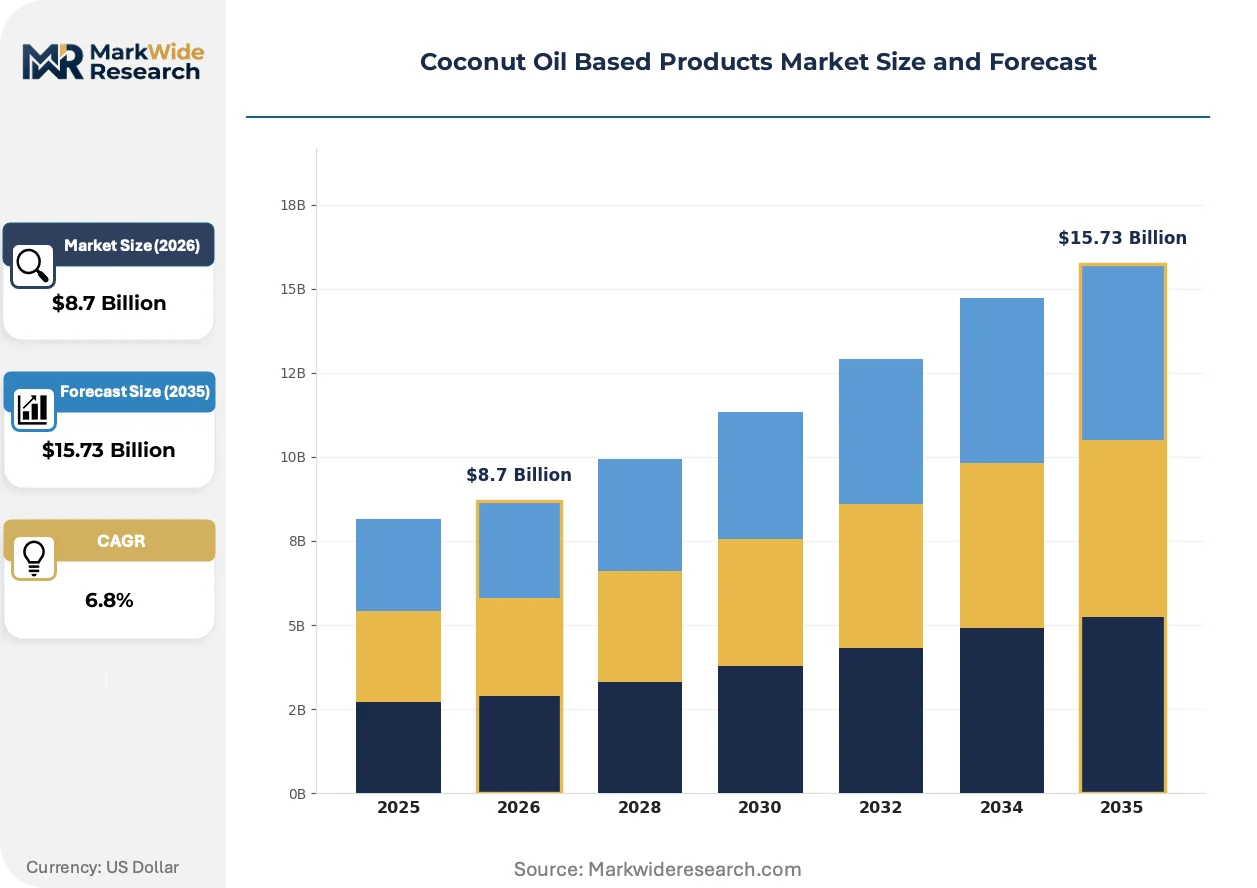
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Oil, Hair Care, Skin Care, Cooking Oil Application: Culinary, Personal Care, Pharmaceuticals, Cosmetics End User: Households, Hotels, Salons, Healthcare Providers Packaging Type: Plastic Bottles, Glass Jars, Tetra Packs, Bulk Containers |
| Companies Covered | Vita Coco, Cargill, Marico, Nutiva, The Coconut Company, Greenville Agro Corporation, Celebes Coconut Corporation, Thai Coconut Public Company Limited, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Oil Based Products Market Trends and Innovations
Cold-pressed extraction technologies are disrupting traditional copra-based processing economics while regulatory disclosure mandates and direct procurement channels reshape how coconut oil reaches end-formulators.
Supercritical CO2 extraction is decentralizing virgin coconut oil production away from centralized Southeast Asian refiners. Mid-scale processors in Kerala and Sri Lanka are adopting skid-mounted units that bypass conventional drying and pressing stages. This technology is decentralizing quality control authority from established trading houses toward origin-proximate cooperatives that capture organic certification premiums.
EU REACH Annex XIV authorization requirements for certain oleochemical process catalysts are forcing reformulation of ethoxylated surfactants derived from coconut feedstocks. Manufacturers must submit substitution plans or secure time-limited authorizations for continued use. Personal care contract manufacturers serving EU markets are accelerating qualification of catalyst-free enzymatic routes to preempt supply disruption.
Ingredient provenance verification has become a primary supplier selection criterion for North American clean beauty brands. Blockchain-enabled supply chain tracking from Philippine cooperatives to finished goods is displacing traditional paper-based organic certification as the trust mechanism. This shift is most visible in California-based direct-to-consumer skincare lines that publish supplier coordinates and harvest dates on product packaging.
Coconut Oil Based Products Market Segmentation
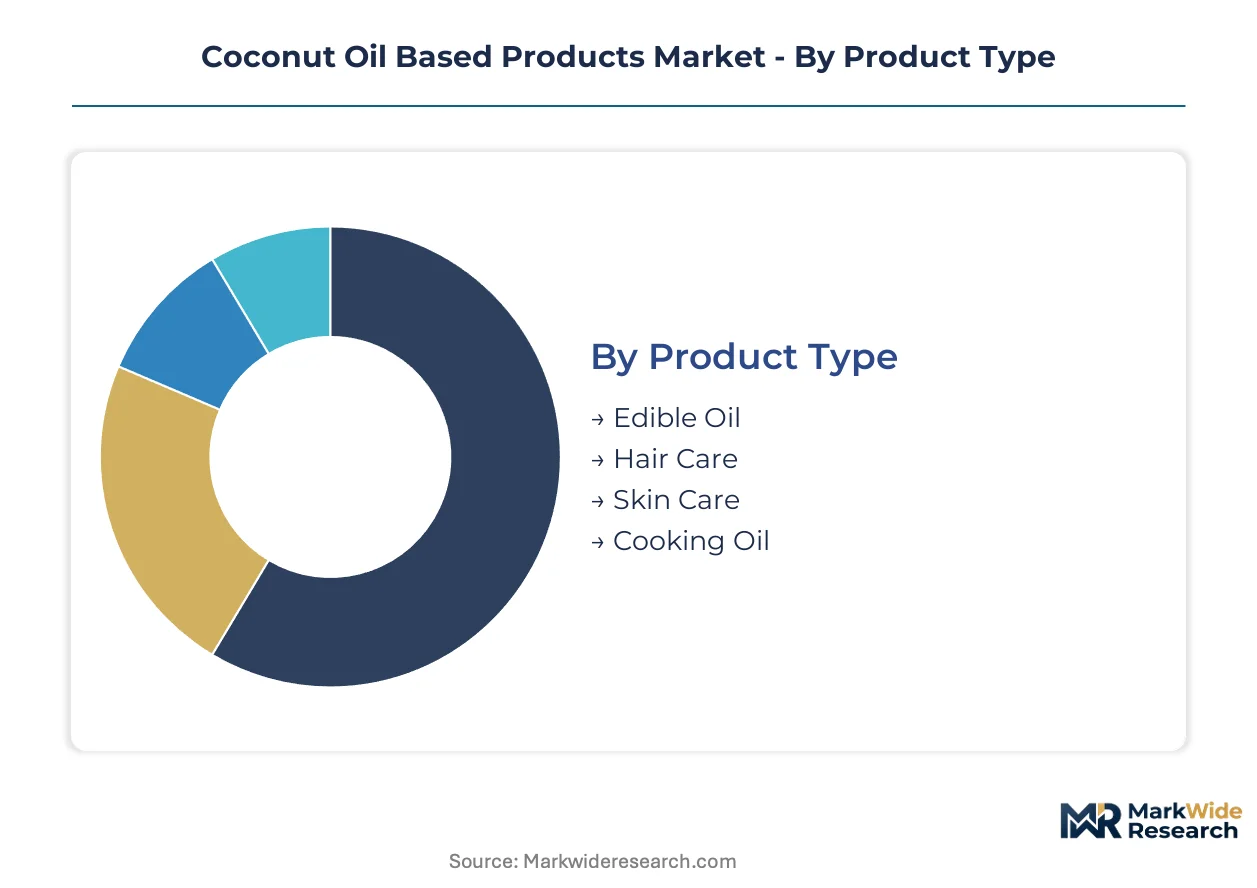
Segmentation in coconut oil based products reveals how regulatory pathways and formulation complexity fragment margin capture across the value chain. Certification requirements diverge sharply between food-grade and pharmaceutical-grade specifications, forcing parallel supply chain investments.
Product Type:
Certification burdens stratify sharply: edible and cooking oils face FSSAI or FDA food safety protocols, while hair and skin care formulations trigger REACH cosmetic ingredient registrations or BIS personal care standards.
- Edible Oil:Refined, bleached, and deodorized grades dominate institutional procurement for food manufacturing. Indian and Indonesian refiners supply bulk volumes to CPG conglomerates seeking lauric acid feedstocks for snack food applications.
- Hair Care:Specialized coconut oil formulations with added herbals command premium positioning in South Asian household consumption. Kerala-based processors partner with ayurvedic brands for BIS-certified export formulations targeting diaspora markets.
- Skin Care:Virgin and cold-pressed grades serve as emollient bases for clean beauty formulations. California direct-to-consumer brands source through blockchain-verified Philippine cooperatives.
- Cooking Oil:Standardized refined grades compete with palm kernel oil substitutes in price-sensitive Southeast Asian food service channels.
Leading the category by volume: Edible Oil. Growing fastest: Hair Care.
Application:
Cost tier separation tracks end-use sophistication, with pharmaceutical applications demanding compendial-grade fractionation that multiplies processing overhead versus commodity culinary grades.
- Culinary:Food preparation and industrial food manufacturing absorb the highest absolute volumes. Indonesian integrated refiners supply standardized lauric acid profiles to global bakery and confectionery manufacturers.
- Personal Care:Hair oils, moisturizers, and cleansers drive value concentration through premium positioning. Marico's specialized formulations anchor South Asian household penetration.
- Pharmaceuticals:Injectable-grade MCT fractions require molecular distillation purity that commands the steepest margin premiums. Compendial standard tightening is extending qualification timelines for new entrants.
- Cosmetics:Surfactant and emollient applications face REACH catalyst substitution mandates for ethoxylated derivatives. Enzymatic process routes are displacing traditional chemical ethoxylation.
Highest volume concentration: Culinary. Steepest expansion trajectory: Pharmaceuticals.
End User:
Customer type determines packaging format and distribution channel economics, with institutional buyers negotiating long-term offtake agreements while direct-to-consumer brands capture organic certification premiums.
- Households:Retail-packaged virgin and refined oils dominate through traditional trade and e-commerce subscription models. Nutiva's organic cold-pressed positioning targets wellness-oriented purchasing.
- Hotels:Food service procurement favors bulk refined grades with standardized specifications. Philippine refiners supply institutional volumes to Southeast Asian hospitality chains.
- Salons:Professional hair care applications require specialized formulations with consistent viscosity profiles. Indian ayurvedic brands supply BIS-certified professional lines.
- Healthcare Providers:Clinical nutrition and pharmaceutical compounding demand pharmaceutical-grade MCT fractions. USP-NF certification requirements limit qualified supplier pools.
Dominant volume: Households. Fastest channel expansion: Healthcare Providers.
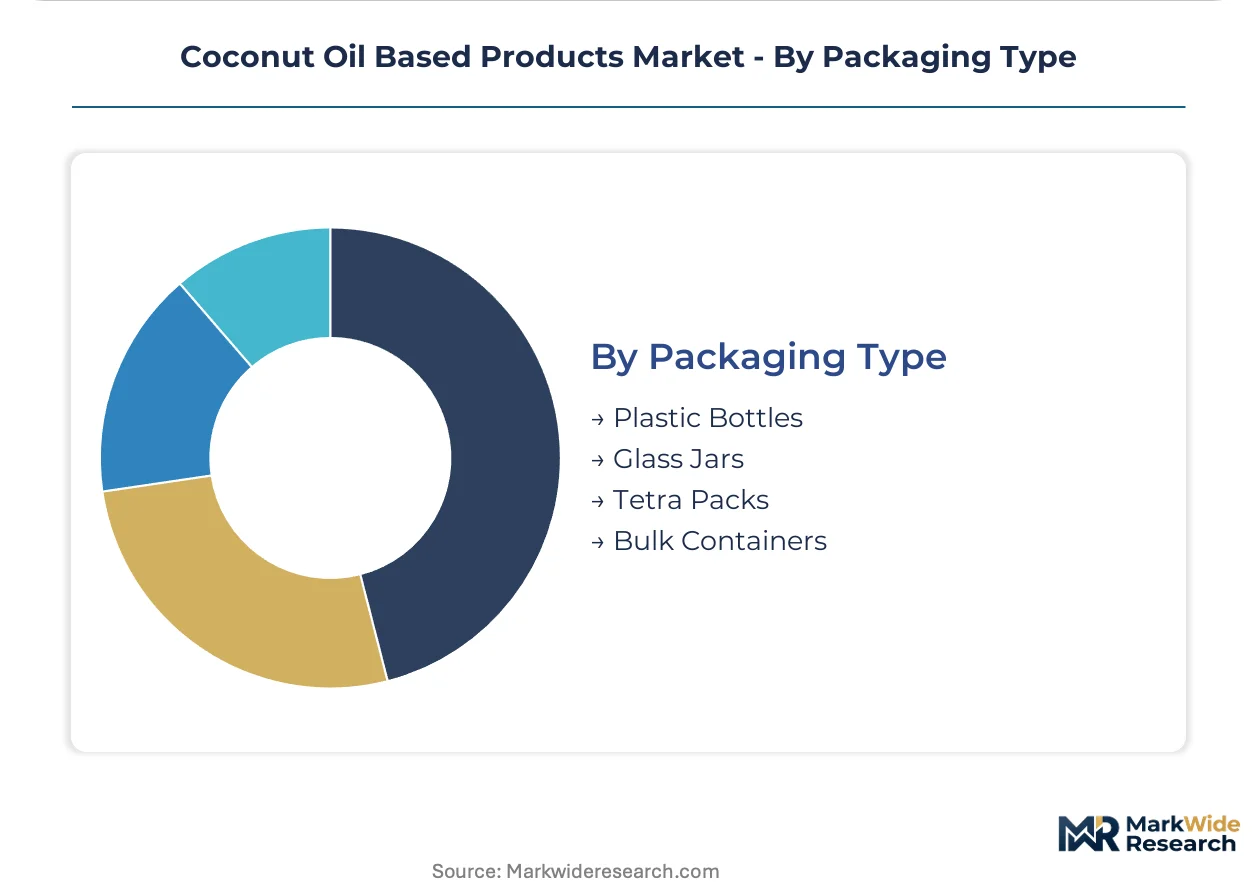
Packaging Type:
Supply concentration in Southeast Asian processing clusters shapes packaging format availability, with bulk infrastructure favoring industrial containers while cold-pressed virgin grades require oxygen-barrier protection.
- Plastic Bottles:Standard HDPE and PET formats dominate mass-market edible and cooking oil distribution. Indonesian refiners supply retail-ready packaging for domestic and export markets.
- Glass Jars:Premium virgin and organic grades leverage perceived quality signaling for clean beauty and specialty food channels. Sri Lankan processors favor glass for export-oriented organic certification.
- Tetra Packs:Aseptic formats extend shelf life for coconut milk and cream derivatives. Philippine manufacturers supply food service and retail UHT segments.
- Bulk Containers:Flexitanks and drums serve industrial surfactant and oleochemical manufacturers. Cargill's integrated supply chain optimizes bulk logistics from copra sourcing to refined oil delivery.
Highest throughput: Bulk Containers. Premium positioning: Glass Jars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philippine Economic Zone Authority incentives draw fractionation capacity to Batangas and Laguna provinces, concentrating pharmaceutical-grade MCT production near Manila port infrastructure.
Philippines
Specialized hair oil exports to South Asian diaspora markets drive formulation partnerships between Laguna-based refiners and ayurvedic brands. FDA registration requirements for cosmetic ingredient imports from Philippine facilities are tightening documentation standards for lauric acid certificates of analysis. Davao Region copra crushing clusters are upgrading to cold-pressing equipment to capture organic certification premiums for virgin oil exports.
Indonesia
Integrated palm-coconut refiners in North Sumatra leverage shared oleochemical infrastructure to optimize lauric acid output across feedstock types. ECHA REACH pre-registration for Indonesian oleochemical derivatives entering EU cosmetic channels requires authorized representative appointments in Rotterdam or Hamburg. Sulawesi copra collection networks are consolidating under processor-owned buying stations to reduce price volatility transmission.
India
Ayurvedic personal care consumption in Kerala and Maharashtra sustains dedicated coconut oil refining capacity for BIS-certified export formulations. FSSAI notification requirements for edible oil fortification are extending compliance timelines for bulk refined grades entering institutional food manufacturing. Tamil Nadu processing corridors near Coimbatore concentrate solvent-free extraction investments targeting domestic clean-label retail channels.
United States
California direct-to-consumer wellness brands drive virgin coconut oil procurement through blockchain-verified Philippine cooperative supply chains. FDA cosmetic ingredient safety assessments under the Federal Food, Drug, and Cosmetic Act require substance-specific toxicological data for new surfactant introductions. New Jersey and Illinois distribution hubs consolidate bulk refined oil imports for Midwest food manufacturing and Northeast personal care compounding.
China
Dual carbon compliance timelines under MEE environmental discharge standards are accelerating solvent-free cold-pressing retrofits in Hainan processing facilities. GB standards for edible oil quality parameters are tightening free fatty acid thresholds for imported coconut oil entering domestic retail channels. Yangtze River Delta oleochemical derivatives manufacturers are qualifying enzymatic process routes to preempt REACH-equivalent catalyst substitution mandates in EU-bound surfactant exports.
Coconut Oil Based Products Market Competitive Landscape
Southeast Asian integrated producers anchor the bulk refined tier; North American and European specialists hold premium virgin and organic certification positioning. The market structure reflects a bifurcation between commodity lauric acid suppliers serving industrial surfactant manufacturers and branded consumer goods companies capturing retail margin pools. Three archetypes dominate: plantation-integrated refiners with captive copra supply, contract manufacturers serving private-label personal care brands, and direct-to-consumer wellness marketers leveraging origin storytelling. Capacity expansion and strategic offtake agreements represent the dominant competitive moves, with processors securing long-term supply contracts to lock in raw material access ahead of price volatility.
Within the integrated refiner tier, Cargill and ADM exemplify commodity-scale operations with backward integration into Southeast Asian copra sourcing. Marico occupies a position representing specialized formulation expertise in South Asian hair care markets. Nutiva sits within the premium organic certification archetype, commanding shelf placement through cold-pressed processing standards. These three companies collectively illustrate how geographic origin, supply chain configuration, and certification positioning stratify competitive access across end-use segments.
| Leading Market Players |
|---|
| Vita Coco |
| Cargill |
| Marico |
| Nutiva |
| The Coconut Company |
| Greenville Agro Corporation |
| Celebes Coconut Corporation |
| Thai Coconut Public Company Limited |
| ADM |
| Others |
Pricing and Supply Chain Analysis
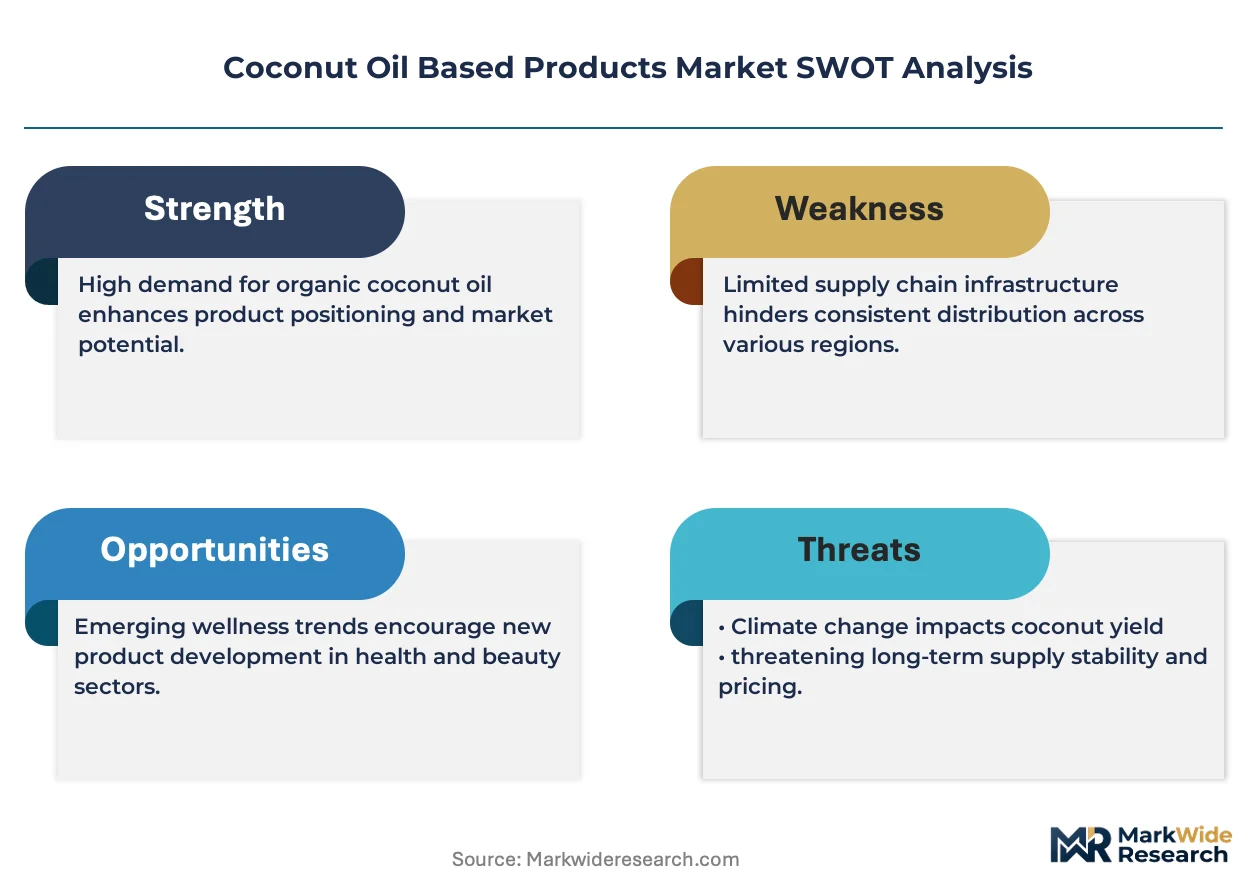
EU REACH Annex XIV authorization requirements for oleochemical process catalysts gate qualified supply access for European personal care channels, with compliant processors commanding premium pricing tiers while non-compliant suppliers face market exclusion. This regulatory filter concentrates pricing power among established Southeast Asian refiners who have secured time-limited authorizations or invested in enzymatic substitution routes.
Pricing Analysis
Short lead-time premiums of 15-25% apply to pharmaceutical-grade MCT fractions needed for injectable formulations, while spot inventory of standard refined grades trades at discounts to contract offtake rates. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in commodity edible oil grades is intensifying because Indonesian palm kernel oil substitutes offer equivalent lauric acid profiles at lower input costs. Institutional food manufacturers exhibit highest price sensitivity, while pharmaceutical compounders demonstrate lowest sensitivity due to compendial purity requirements.
Supply Chain Analysis
Direct-to-brand channels handle premium virgin and organic certification demand, while bulk flexitank shipments serve industrial surfactant manufacturers through Cargill's integrated logistics network. Raw material sourcing draws from Philippine and Indonesian copra crushing clusters, with Kerala and Sri Lankan processors adding cold-pressed virgin capacity. Sulawesi copra collection networks and Davao Region crushing infrastructure face weather-driven harvest volatility as the dominant supply chain risk. Distribution runs through Rotterdam and Hamburg as EU entry hubs for REACH-registered oleochemical derivatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration mandates and compendial standard tightening are forcing consolidation among mid-scale refiners lacking dedicated fractionation engineering capabilities or multi-jurisdiction certification resources.
For Market Incumbents: Hedge copra price exposure through processor-owned buying stations in Sulawesi and backward integration into Davao Region crushing infrastructure. Secure long-term offtake agreements with European personal care contract manufacturers before catalyst substitution deadlines eliminate non-compliant competitors. Prioritize USP-NF and EP compendial approvals to capture pharmaceutical-grade MCT margin pools. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers a defensible entry point into premium virgin coconut oil segments bypassing established trading house quality control authority. Target California direct-to-consumer wellness brands through blockchain-verified Philippine cooperative supply chains. Pursue BIS certification partnerships with Kerala-based ayurvedic processors for diaspora market access. For Investors and Strategic Acquirers: ECHA substance evaluation acceleration is the leading indicator that compliant supplier qualification timelines will extend, favoring incumbents with existing preferred vendor relationships. Over the medium-term horizon, acquisition targets should concentrate on Indonesian integrated refiners with shared palm-coconut oleochemical infrastructure and established REACH authorized representative appointments. Monitor MEE environmental discharge standard enforcement in Hainan as signal for solvent-free cold-pressing investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copra Sourcing | Processor-owned buying stations in Sulawesi reduce price volatility transmission to refiners. |
| Pharmaceutical-Grade Fractionation Investment | Molecular distillation capacity for injectable-grade MCT captures steepest margin premiums. |
| Enzymatic Process Route Adoption | Catalyst-free ethoxylation preempts REACH Annex XIV authorization disruption for EU surfactant exports. |
| Blockchain Supply Chain Verification | Origin-proximate cooperative tracking displaces paper-based certification for California clean beauty brands. |
| BIS Certification Partnership | Ayurvedic formulation alliances with Kerala processors unlock South Asian diaspora household penetration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews of Southeast Asian refinery plant managers, European personal care contract manufacturing procurement leads, and California direct-to-consumer brand supply chain directors. FDA cosmetic ingredient safety assessments, ECHA REACH registration databases, and Philippine Economic Zone Authority incentive disclosures provided regulatory boundary conditions. Bottom-up capacity modeling across Indonesian and Philippine processing clusters was triangulated against top-down demand estimates from food manufacturing and pharmaceutical compounding end-uses.
Product type, application, and end user dimensions were modeled at country-level granularity for Philippines, Indonesia, India, United States, and China, with packaging format and certification tier as cross-cutting attributes. CAGRs were derived through logarithmic trend fitting of historical volume trajectories adjusted for regulatory inflection points. Forecast inputs incorporated copra harvest cycle patterns, REACH authorization timeline assumptions, and MEE environmental discharge standard implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather events affecting Philippine and Indonesian coconut harvests or accelerated catalyst substitution mandates in EU cosmetic channels. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Centella Asiatica Extract Market
Ingredients
Middle East and Africa Lipids Market
Ingredients
India Gelatin Market
Ingredients
Hydrolyzed Corn Protein Market
Ingredients
Asparagus Extract Market
Ingredients
Europe Agar Market
Ingredients
Diastatic Malt Market
Ingredients
Potato Fiber Market
Ingredients
Glucosylglycerol Market
Ingredients
Cosmetic Ingredients Market
Ingredients
Plant Based Ingredients Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Medium-Chain Triglyceride (MCT) Fat Market
Ingredients
Oyster Shell Powder Market
Ingredients
Baobab Ingredient Market
Ingredients
Avocado Powder Market