
 South America Protein Market | 2026-2036
South America Protein Market Size, Share, and Industry Trends Forecast 2026-2036
South America Protein Market Analytics
Sports nutrition is restructuring the end-use vertical mix as Brazilian and Argentine fitness enthusiasts shift spending toward performance-oriented formulations. Cargill Incorporated leverages its oilseed processing infrastructure to anchor soy protein supply across the Mercosur trade zone. BRF S.A. competes through vertical integration from poultry farming to hydrolyzed collagen production, while Kerry Group plc differentiates via flavor-masked whey isolates targeted at Latin American palates.
South America protein encompasses amino acid chains derived from animal and plant biomass, typically processed through enzymatic hydrolysis, acid precipitation, or membrane filtration to achieve specified nitrogen content and digestibility scores for human consumption. Whey dominates value capture due to established dairy infrastructure in southern Brazil and Argentina, while pea protein grows fastest as Roquette Frères extends processing partnerships with Argentine pulse growers. Sports nutrition commands premium positioning, whereas fortified foods occupy volume-driven, margin-compressed tiers through supermarket channel penetration.
ANVISA governs protein content claims and novel ingredient approvals in Brazil, while Argentina's national food safety authority enforces Mercosur-aligned labeling standards that restrict certain hydrolyzed protein marketing. These frameworks elevate compliance costs for imported isolates but create protected terrain for locally certified manufacturers. Stakeholders must monitor regulatory divergence between Brazilian state-level sanitation enforcement and emerging Colombian protein fortification mandates to optimize regional production allocation.
Market Dynamics
ANVISA's tightening nutrition labeling standards are forcing reformulation across Brazil's protein manufacturing base, while Argentine pulse processing expansion creates new supply alternatives that compete with established whey infrastructure.
Growth Catalysts
- Fitness culture maturation:Brazilian gym memberships and competitive sports participation drive demand for performance-oriented protein formulations with enhanced amino acid profiles.
- Mercosur trade facilitation:Reduced tariff barriers between Argentina, Brazil, Paraguay, and Uruguay enable cross-border protein concentrate distribution at scale.
- Enzymatic hydrolysis advancement:Improved processing yields from membrane filtration systems lower production costs for high-purity isolates targeting clinical nutrition segments.
Market Restraints
- Soy price volatility:Argentine drought cycles and currency instability disrupt raw material costs for South America's dominant plant protein feedstock.
- Import dependency for specialized equipment:Membrane filtration and chromatography systems rely on European and North American suppliers, creating capex bottlenecks.
- ANVISA novel ingredient approval timelines:Extended safety evaluation periods for emerging protein sources delay product launches by 18-36 months versus comparable US FDA pathways.
Strategic Opportunities
- Colombian fortification mandates:New school nutrition and maternal health programs create institutional procurement channels for affordable protein concentrates.
- Cell-culture hybridization:Precision fermentation integration with traditional dairy processing offers pathway to novel protein categories without full infrastructure replacement.
- Direct-to-consumer subscription models:E-commerce platforms bypass supermarket margin compression for premium sports nutrition brands targeting São Paulo and Buenos Aires metro areas.
Industry Challenges
- Specialized food technologist scarcity:Protein formulation expertise combining sensory science with regulatory compliance commands premium wages in São Paulo's manufacturing corridor.
- Legacy dairy co-processing constraints:Existing whey fractionation plants require substantial retrofit investment to handle alternative substrates like pea or fava bean isolates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Protein Market |
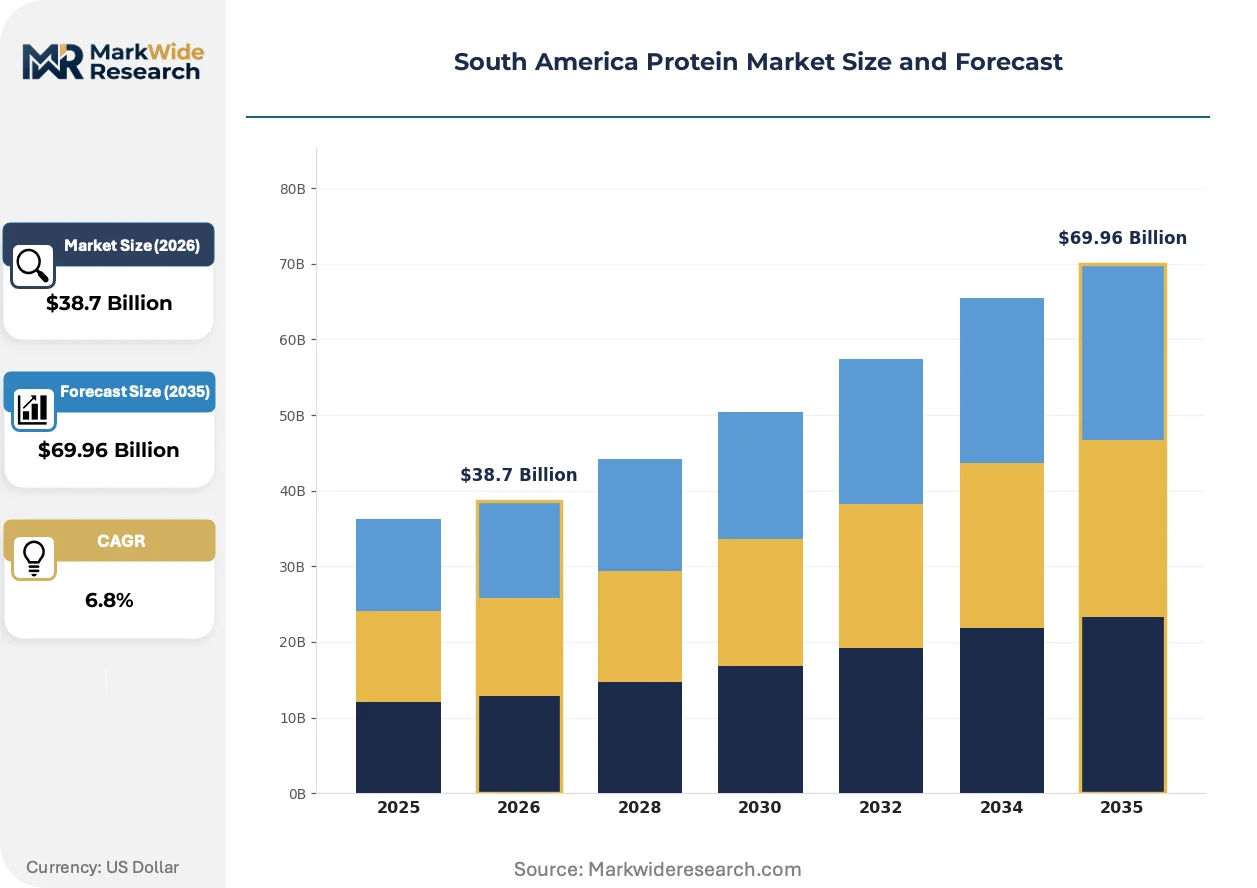
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey, Casein, Soy, Pea Application: Sports Nutrition, Fortified Foods, Dietary Supplements, Bakery End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Children Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Ingredion Incorporated, Kerry Group plc, BRF S.A., Arla Foods, Fonterra Co-operative Group, Roquette Frères, Caramuru Alimentos, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Protein Market Evolving Landscape
Processing technology convergence and regulatory stringency are compressing product development cycles while elevating the technical threshold for market entry across South American protein manufacturing.
Precision fermentation is absorbing capital allocation from traditional extraction methods as Argentine and Brazilian facilities pilot microbial protein production for hypoallergenic applications. Sports nutrition brands in São Paulo are absorbing early volumes to differentiate from commodity whey suppliers. This absorption pattern is compressing the addressable market for conventional soy isolates in premium positioning tiers.
ANVISA's updated nutrition labeling resolution mandates explicit amino acid scoring for protein content claims, effective across all packaged foods. Manufacturers must reformulate or downgrade label declarations, disproportionately impacting economy-tier products reliant on lower biological value sources. Brazilian states with stricter sanitation enforcement are seeing accelerated consolidation as smaller processors exit rather than absorb compliance costs.
Specialized distribution partnerships between ingredient suppliers and contract manufacturers are displacing spot-market purchasing for mid-scale brands. Argentine pulse processors and Brazilian dairy cooperatives now offer integrated formulation services, capturing margin that previously accrued to independent compounders. This bundling trend concentrates most visibly in Minas Gerais state's food technology cluster, where proximity reduces logistics friction for blended protein systems.
South America Protein Market Segmentation
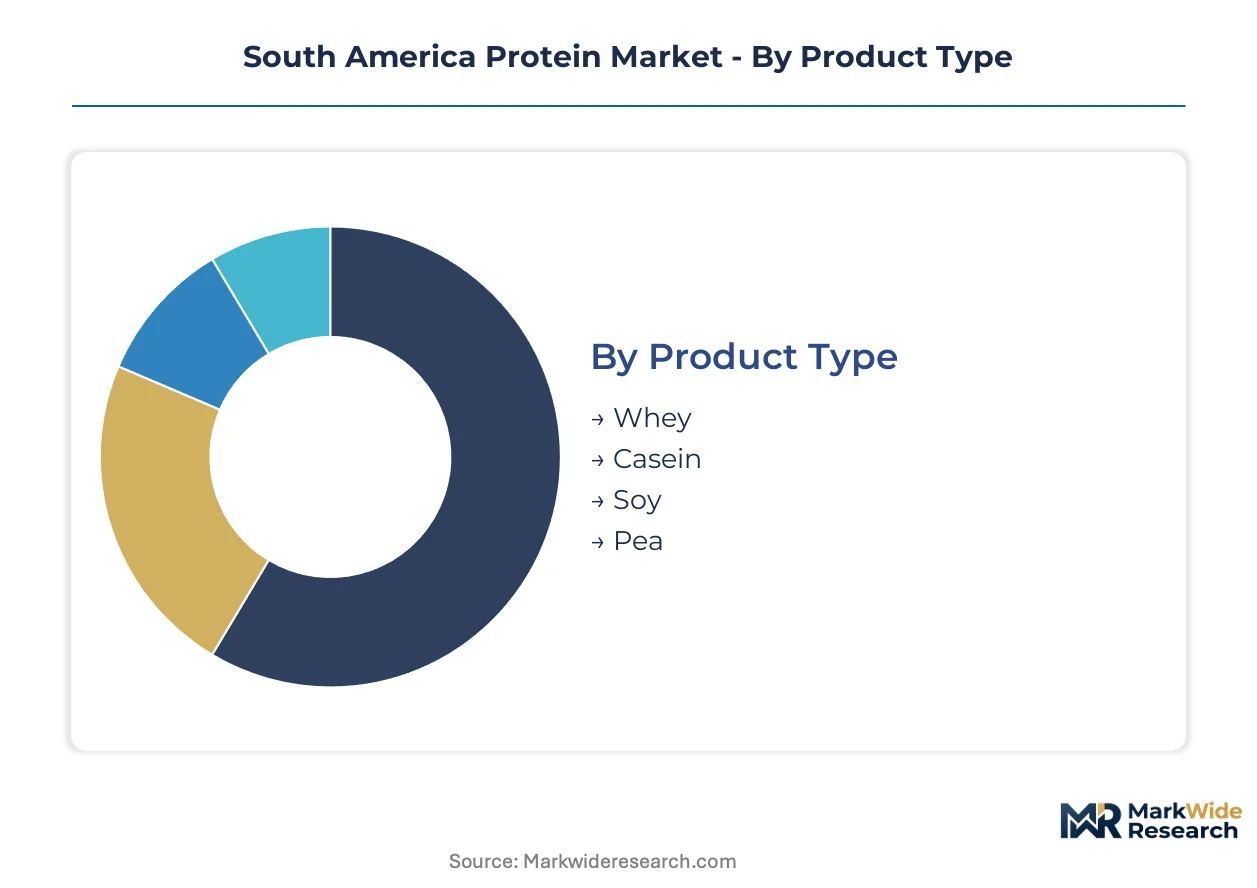
Segmentation in the South America protein market reveals how formulation requirements diverge across end-use contexts, from performance-driven sports applications to cost-sensitive fortification programs. Understanding these divides enables suppliers to align processing investments with margin structures and regulatory exposure.
Product Type:
Whey and soy isolates function as standalone ingredients requiring minimal formulation support, whereas pea and casein proteins increasingly embed into blended systems demanding technical integration services.
- Whey:Derived from cheese manufacturing byproducts through ultrafiltration and ion exchange, whey concentrates and isolates deliver complete amino acid profiles with rapid absorption kinetics. Demand clusters in São Paulo's sports nutrition manufacturing corridor, where ANVISA-certified facilities process imported Argentine dairy permeate alongside domestic supplies.
- Soy:Hexane-extracted or aqueous-processed defatted soy flour yields isolates with standardized nitrogen solubility indices for beverage applications. Argentine crushing capacity in Santa Fe province anchors supply, though drought-induced crop volatility forces Brazilian processors to maintain dual-sourcing relationships with Paraguayan growers.
- Pea:Air-classified and wet-fractionated yellow pea protein carries lower allergen burden than soy, positioning it for pediatric and clinical nutrition expansion in Colombian and Chilean markets.
- Casein:Micellar casein and calcium caseinates provide sustained amino acid release for overnight recovery formulations, with production concentrated in southern Brazil's dairy cooperative networks.
Volume placements concentrate in whey and soy; the faster expansion belongs to pea protein as Argentine processors scale wet-fractionation capacity.
Application:
Sports nutrition commands premium positioning through differentiated amino acid scoring, while fortified foods operate on procurement efficiency metrics tied to government program specifications.
- Sports Nutrition:Ready-to-mix powders, ready-to-drink beverages, and protein bars formulated for leucine threshold optimization dominate value capture. Brazilian gym culture maturation in Rio de Janeiro and Belo Horizonte metro areas drives demand for hydrolyzed whey and isolate blends with enzyme-enhanced digestibility claims.
- Fortified Foods:Bread, pasta, and dairy alternatives incorporate protein concentrates at 5-15% inclusion rates to meet school nutrition and maternal health program standards. Colombian government procurement channels prioritize cost-per-gram-protein metrics over sensory performance.
- Dietary Supplements:Capsule and tablet formats targeting aging populations and clinical recovery segments require low-moisture, high-density protein granulations with excipient compatibility.
- Bakery:Protein-enriched flour replacements demand modified hydration properties and Maillard reaction control, limiting viable sources to thermally stable soy and wheat-gluten hybrids.
Revenue concentration sits with sports nutrition; fortified foods claim the steepest volume expansion trajectory through institutional procurement scaling.
End User:
Athletes and fitness enthusiasts purchase through performance-oriented channels with technical specification demands, while health-conscious consumers and children reach protein through mainstream retail with taste and convenience priorities.
- Athletes:Competitive and recreational athletes in Brazil's southeastern states prioritize protein products with third-party certification for banned substance screening, accepting price premiums for batch-tested isolates.
- Fitness Enthusiasts:Regular gym attendees without competitive aspirations drive mass-market whey consumption through supermarket and e-commerce channels, sensitive to flavor masking quality and mixability.
- Health-Conscious Consumers:Middle-income urban households seeking general wellness benefits respond to protein fortification in conventional foods, particularly in Argentina's inflation-adjusted purchasing environment.
- Children:School feeding programs and parental nutrition decisions favor mild-flavored, highly soluble proteins with clean label positioning, creating demand for pea and rice protein blends in Brazilian and Colombian markets.
Spending intensity peaks with athletes; health-conscious consumers represent the broadest addressable base for volume scaling.
Distribution Channel:
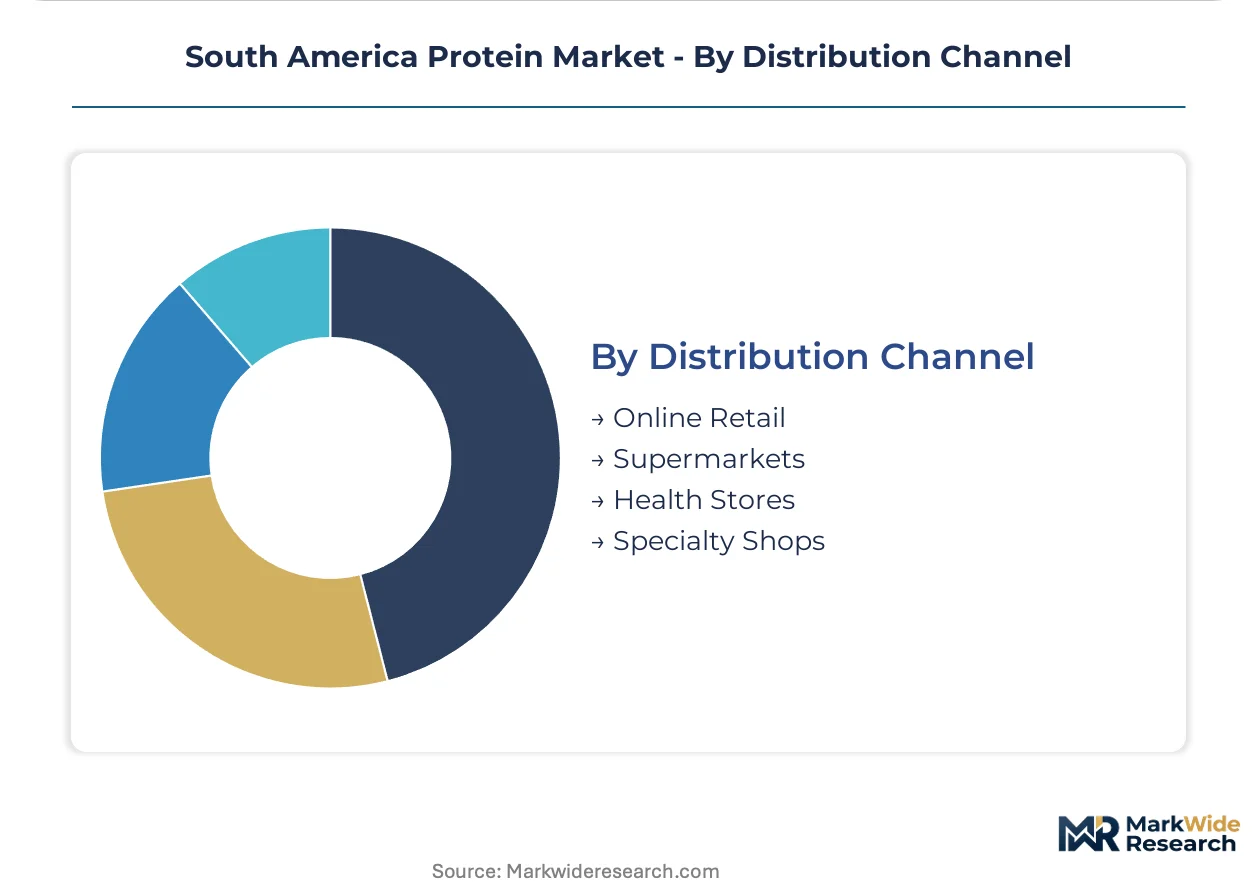
Online retail and specialty shops accommodate technical product education and subscription relationships, whereas supermarkets and health stores handle commodity replenishment with limited staff interaction.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription models and flavor customization for premium sports nutrition brands targeting São Paulo and Buenos Aires metropolitan concentrations.
- Supermarkets:Mass-market protein powders and fortified food placements compete for shelf space with conventional categories, requiring trade spend investment and promotional velocity commitments from suppliers.
- Health Stores:Pharmacy and dedicated nutrition retail chains in Brazil's southern states provide consultation-driven sales environments suited to clinical nutrition and specialized diet products.
- Specialty Shops:Gym-affiliated retail and bodybuilding-focused independents carry curated premium assortments with higher service intensity and product knowledge requirements.
Channel margin structures favor online retail for premium positioning; supermarkets dominate absolute volume throughput for economy-tier products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone incentives draw whey fractionation investment toward Amazonas state, while Mercosur tariff alignment funnels cross-border protein concentrate flows through São Paulo's logistics corridor.
Brazil
Southeastern manufacturing demand from São Paulo and Minas Gerais gym culture expansion drives whey isolate consumption. ANVISA's updated nutrition labeling resolution mandates amino acid scoring for all protein content claims. Campinas technology cluster hosts integrated formulation services bundling Argentine pulse proteins with domestic dairy derivatives.
Argentina
Santa Fe province crushing capacity anchors soy protein supply amid drought-induced crop volatility cycles. The national food safety authority enforces Mercosur-aligned labeling standards restricting certain hydrolyzed protein marketing. Buenos Aires metropolitan area concentrates precision fermentation pilot facilities targeting hypoallergenic microbial protein categories.
Colombia
School nutrition and maternal health procurement programs create institutional demand channels for affordable protein concentrates. Government fortification mandates prioritize cost-per-gram-protein metrics over sensory performance specifications. Bogotá processing corridors scale pea and rice protein blend capacity for pediatric nutrition applications.
Chile
Clinical nutrition segment expansion in Santiago metro area drives demand for low-allergen pea protein isolates. National health service procurement frameworks favor third-party certified products with documented digestibility scores. Valparaíso port infrastructure facilitates whey concentrate imports from southern Brazilian dairy cooperatives.
Uruguay
Cross-border dairy permeate processing agreements with Brazilian ANVISA-certified facilities leverage Mercosur trade facilitation protocols. Montevideo logistics hubs coordinate whey fractionation byproduct flows toward São Paulo sports nutrition manufacturers. Pasture-based dairy cooperative networks supply raw material streams for regional hydrolyzed collagen production.
South America Protein Market Competitive Landscape
Top-tier vendors anchor supply security through captive oilseed and dairy infrastructure, while mid-scale specialists compete on formulation integration services and flavor-masked isolates. The vendor base stratifies across three functional tiers: agricultural processors with backward integration into farming operations, dairy cooperatives with whey fractionation assets, and ingredient technology firms with sensory science capabilities. Dominant competitive moves include membrane filtration capacity expansion in Minas Gerais and strategic partnerships between Argentine pulse processors and Brazilian contract manufacturers.
Among agricultural processing conglomerates, Cargill Incorporated exemplifies the oilseed-anchored archetype with Mercosur trade zone supply coverage. Kerry Group plc occupies a position within the flavor-technology tier, while BRF S.A. represents vertical control from poultry farming through hydrolyzed collagen output. Roquette Frères anchors the plant-protein specialization vector through Argentine pulse grower partnerships.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Ingredion Incorporated |
| Kerry Group plc |
| BRF S.A. |
| Arla Foods |
| Fonterra Co-operative Group |
| Roquette Frères |
| Caramuru Alimentos |
| Others |
Value Network & Pricing Analysis
Captive whey fractionation infrastructure in southern Brazil and Argentine soy crushing capacity anchor both supply security and pricing power across the Mercosur protein corridor. ANVISA certification requirements for amino acid scoring claims create tiered cost structures that favor incumbent processors with in-house laboratory capabilities over spot-market dependent competitors.
Pricing Analysis
Short-lead-time premiums command fifteen to twenty percent markups over contract-scheduled deliveries for hydrolyzed isolates targeting São Paulo sports nutrition manufacturers. Three-tier pricing structure across premium, standard, and economy levels stratifies by biological value certification and third-party banned-substance testing. Pricing pressure stems from Argentine drought-induced soy price volatility forcing Brazilian processors to absorb margin compression or reformulate toward lower-cost pea blends. Health-conscious consumer segments exhibit highest price sensitivity, while competitive athletes accept substantial premiums for batch-tested, ANVISA-certified isolates.
Supply Chain Analysis
Single-source vulnerability sits with European membrane filtration equipment suppliers, creating capex bottlenecks for capacity expansion in Minas Gerais and Santa Fe processing corridors. Raw material flows concentrate in Argentina for soy and yellow pea feedstock, southern Brazil for dairy permeate, and Paraguay for drought-hedge pulse sourcing. Supply chain risk centers on import dependency for chromatography and ultrafiltration systems, with delivery timelines extending under currency volatility. Distribution runs through São Paulo logistics hubs for cross-border Mercosur concentrate flows, with Campinas technology cluster hosting integrated formulation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's amino acid scoring mandates erect a cost-of-compliance barrier that consolidates market share among certified incumbent processors while forcing smaller competitors toward private-label contract manufacturing. This regulatory moat rewards early certification investments with protected pricing tiers in premium sports nutrition segments.
For Market Incumbents: Extend membrane filtration capacity in Minas Gerais to capture margin from precision fermentation integration, while acquiring Argentine pulse processing partnerships to hedge against soy price volatility. ANVISA novel ingredient approval timelines threaten late-movers with eighteen to thirty-six month launch delays. Certification investment in third-party banned-substance testing laboratories reinforces channel control with competitive athlete segments. For New Entrants and Emerging Players: Enter via Colombian institutional procurement channels for school nutrition and maternal health fortification programs, where cost-per-gram-protein metrics prioritize volume scale over sensory performance. Direct-to-consumer subscription models in São Paulo and Buenos Aires metropolitan areas offer the most penetrable white-space for premium positioning. Flavor-masked pea protein isolates targeting pediatric applications provide a differentiated go-to-market angle with lower regulatory exposure than novel microbial categories. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by agricultural processing conglomerates seeking Mercosur protein supply coverage. Long-term viability favors targets with captive oilseed or dairy infrastructure plus ANVISA-certified formulation capabilities. Watch for ANVISA novel ingredient approval acceleration as the signal for inflection in microbial protein category viability.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Minas Gerais facilities capture margin from high-purity isolate demand in clinical nutrition segments. |
| Argentine Pulse Processor Partnerships | Wet-fractionation alliances with Santa Fe growers secure drought-hedged plant protein supply alternatives. |
| Precision Fermentation Pilot Integration | Buenos Aires microbial protein facilities target hypoallergenic applications with lower ANVISA regulatory exposure. |
| Direct-to-Consumer Subscription Launch | São Paulo e-commerce platforms bypass supermarket margin compression for premium sports nutrition brands. |
| ANVISA Certification Laboratory Investment | In-house amino acid scoring capabilities accelerate product launch timelines versus third-party dependency. |
Research Methodology
Multi-period observation of ANVISA regulatory filing timelines, Argentine crop yield cycles, and Brazilian gym membership penetration anchored the trend analysis, supplemented by interviews with protein formulation technologists, dairy cooperative procurement directors, sports nutrition brand managers, and ANVISA regulatory affairs consultants. Secondary validation drew from ANVISA resolution databases, Mercosur trade flow statistics, SEC filings of listed ingredient suppliers, and Brazilian supermarket scanner data. Bottom-up volume modeling triangulated against top-down macroeconomic projections across the analysis window.
Input-output matrices mapped protein isolate production capacity against end-use demand segments, with segmentation dimensions spanning product type, application, end user archetype, and distribution channel. CAGRs were derived from trend extrapolation adjusted for regulatory lag effects and agricultural commodity cycle phases. Forecast inputs incorporated enzymatic hydrolysis yield improvements and membrane filtration cost curves throughout the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Argentine drought severity and ANVISA novel ingredient approval delays. Model assumptions reflect documented regulatory frameworks and trade protocols, with revision triggers including Mercosur tariff renegotiation and Colombian fortification mandate expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Collagen Casings Market
Ingredients
United States Protein Market
Ingredients
African Brewing Enzymes Market
Ingredients
Fats and Oils Market
Ingredients
North America Fats and Oils Market
Ingredients
Date Syrup Market
Ingredients
Pork Skin Gelatin Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Europe Pea Starch Market
Ingredients
Pea Peptones Market
Ingredients
Caramel Malt Market
Ingredients
Textured Milk Protein Market
Ingredients
India Olive Oil Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Demineralized Whey Powder Ingredient Market
Ingredients
Non Meat Ingredients Market