
 Cosmetic and Perfume Glass Packaging Market | 2026-2036
Cosmetic and Perfume Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic and Perfume Glass Packaging Market Analysis
Lightweighting technology is tilting manufacturing economics toward thinner-walled, high-durability glass that preserves barrier performance while cutting material inputs. VERESCENCE leverages its French heritage glassworks to dominate luxury flacon production for European fragrance houses. Gerresheimer anchors its position through pharmaceutical-grade glass expertise that transfers into premium cosmetic vial manufacturing. Zignago Vetro sustains cost competitiveness via integrated sand-to-glass operations along Italy's Adriatic corridor.
Cosmetic and perfume glass packaging encompasses flacons, vials, jars, and bottles engineered from soda-lime, borosilicate, or lead-free crystal glass with wall thicknesses typically ranging from 2mm to 6mm, formed through blow-and-blow or press-and-blow processes to achieve precise dimensional tolerances for pump, spray, and dropper closure compatibility. The primary commercial purpose centers on preserving volatile fragrance compounds and active cosmetic ingredients from UV degradation, oxidation, and moisture ingress while delivering tactile and visual luxury cues that justify premium price positioning. Flacons and bottles occupy the dominant volume share, driven by fragrance house demand for iconic silhouettes that function as brand assets on retail counters. Luxury design styling commands the highest margin pools, where hand-finished crystal and limited-edition collaborations between glassmakers and fashion houses extract substantial value above commodity glass pricing. Minimalist styling is accelerating fastest among indie beauty brands seeking shelf differentiation through understated cylindrical and slab-sided forms that reduce decoration costs.
REACH and the EU Green Deal shape material compliance obligations across European glass packaging supply chains, while FDA cosmetic labeling requirements govern market access for imported glass containers in the United States. France's national environmental agency enforces extended producer responsibility schemes that push brands toward refillable and returnable glass programs. Stakeholders must monitor how tightening post-consumer recycled content mandates in glass manufacturing will reshape raw material sourcing strategies and furnace energy economics.
Market Dynamics
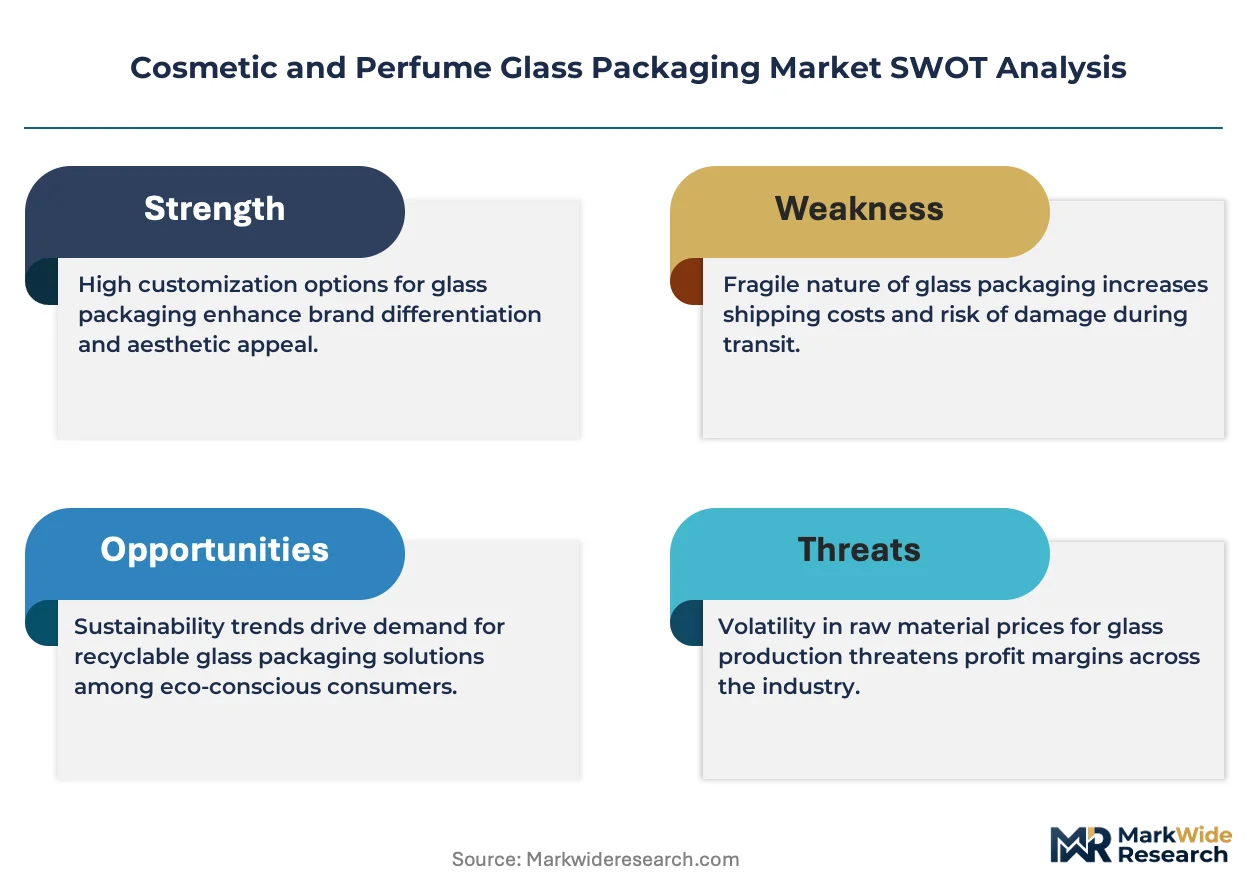
Sustainability mandates across the European Union are compressing design cycles for refillable glass flacons while simultaneously elevating material specifications toward borosilicate and lead-free crystal formulations that withstand repeated sterilization cycles.
Growth Catalysts
- REACH compliance deadlines:European fragrance houses accelerate glass packaging redesigns to meet ECHA substance restriction timelines, creating surge demand for certified borosilicate suppliers.
- Heritage glassmaking clusters:Concentrated artisan capacity in France and Italy enables rapid prototyping of limited-edition flacon silhouettes that function as brand equity assets.
- Lightweighting process innovation:Thinner-walled blow-and-blow techniques preserve barrier performance while cutting furnace energy consumption per unit.
Market Restraints
- Raw material concentration:High-purity silica sand deposits concentrate in limited geographies, exposing furnace operators to input cost volatility and geopolitical supply risk.
- Substitution by aluminum and bio-polymers:Indie beauty brands increasingly specify metal and plant-based alternatives for travel-size formats where glass weight disadvantages shipping economics.
- Extended producer responsibility schemes:France's ANSM-enforced take-back obligations impose compliance overhead that squeezes margin pools for mid-tier glass decorators.
Strategic Opportunities
- Post-consumer recycled content mandates:EU Green Deal targets for cullet integration create first-mover advantage for furnace operators investing in optical sorting and decontamination infrastructure.
- Pharmaceutical-grade crossover:Cosmetic brands seeking clinical credibility specifications can leverage existing borosilicate certification pathways established for drug vial applications.
- Direct-to-consumer refill channels:Luxury houses bypass wholesale distributors through branded subscription programs that capture lifetime value from returnable flacon deposits.
Industry Challenges
- Master glassblower scarcity:Hand-finishing techniques for crystal flacons require decades of apprenticeship; retirement waves in Murano and Normandy outpace training pipeline replenishment.
- Furnace reconfiguration timelines:Converting soda-lime production lines to borosilicate compatibility demands 18-24 month capital cycles with uncertain offtake commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic and Perfume Glass Packaging Market |
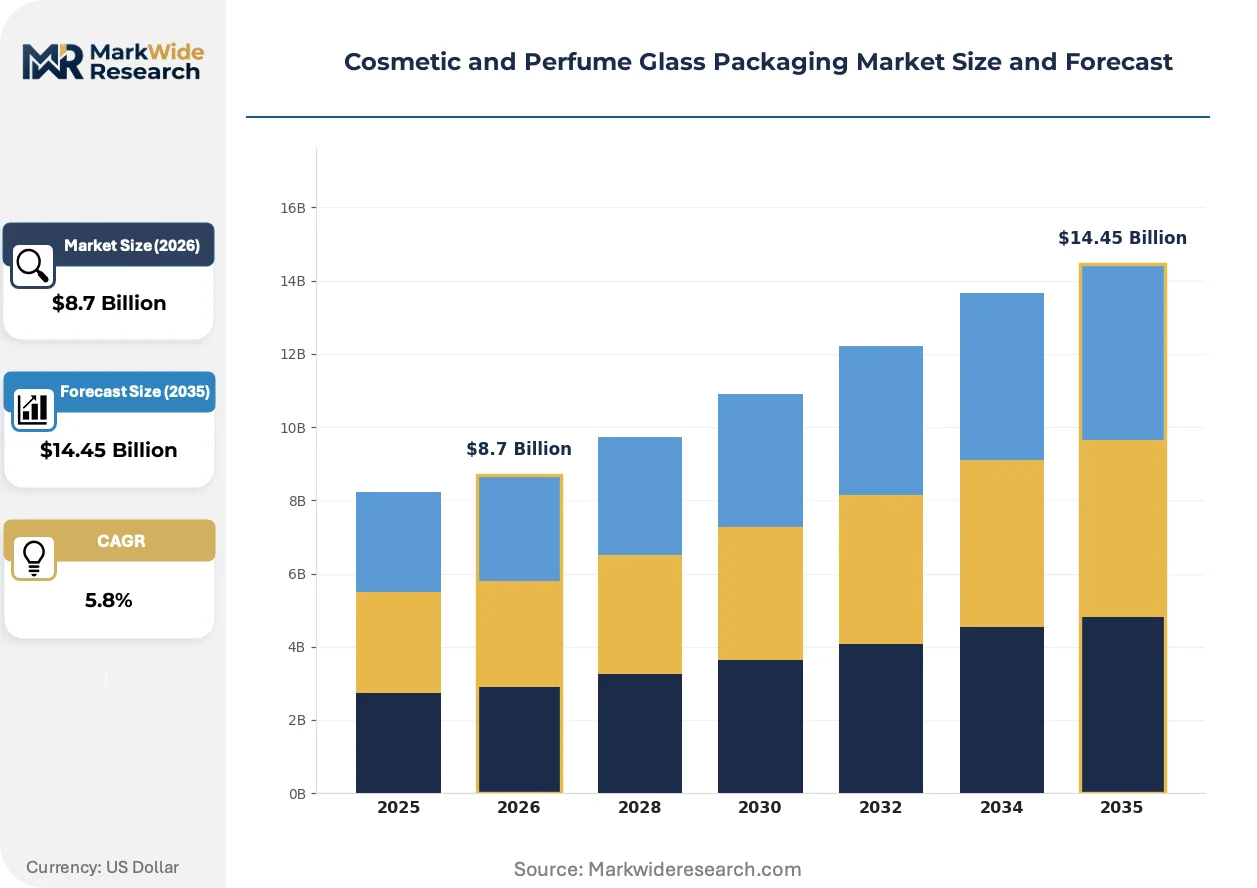
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flacons, Vials, Jars, Bottles Closure Type: Sprayers, Droppers, Screw Caps, Corks Design Style: Luxury, Minimalist, Vintage, Modern Capacity: Under 50ml, 50ml to 100ml, 100ml to 200ml, Over 200ml |
| Companies Covered | VERESCENCE, Zignago Vetro, Gerresheimer, Aptar Group, Bormioli Luigi, Saverglass sas., Heinz-Glas, Libo Cosmetics, Pochet SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic and Perfume Glass Packaging Market Emerging Trajectories
Digital decoration technologies and closed-loop material systems are redefining how glass packaging communicates brand identity while satisfying circular economy audit requirements.
Laser-etched surface treatments are rendering obsolete traditional silk-screen and hot-stamp decoration methods that require solvent-based inks and generate hazardous waste streams. Premium fragrance houses in France and Italy now specify direct-to-glass marking for limited editions that demand photographic detail and rapid design iteration. This shift compresses decoration lead times from weeks to days while eliminating consumables inventory.
EU Green Deal circularity mandates force glassmakers to document post-consumer recycled content percentages through mass-balance certification. Furnace operators in Germany and Italy invest in cullet preprocessing facilities to achieve food-contact-grade purity thresholds. High-end cosmetic vials now compete on verified recycled content ratios that appear directly on primary packaging labels.
Indie beauty brands consolidate purchasing through specialized distributors that aggregate small-batch orders across multiple glass decorators. This channel fragmentation weakens traditional direct relationships between fragrance houses and heritage glassworks. North American direct-to-consumer brands exhibit the most pronounced consolidation, negotiating collective specifications that standardize neck finishes and wall thicknesses across competing suppliers.
Cosmetic and Perfume Glass Packaging Market Segmentation
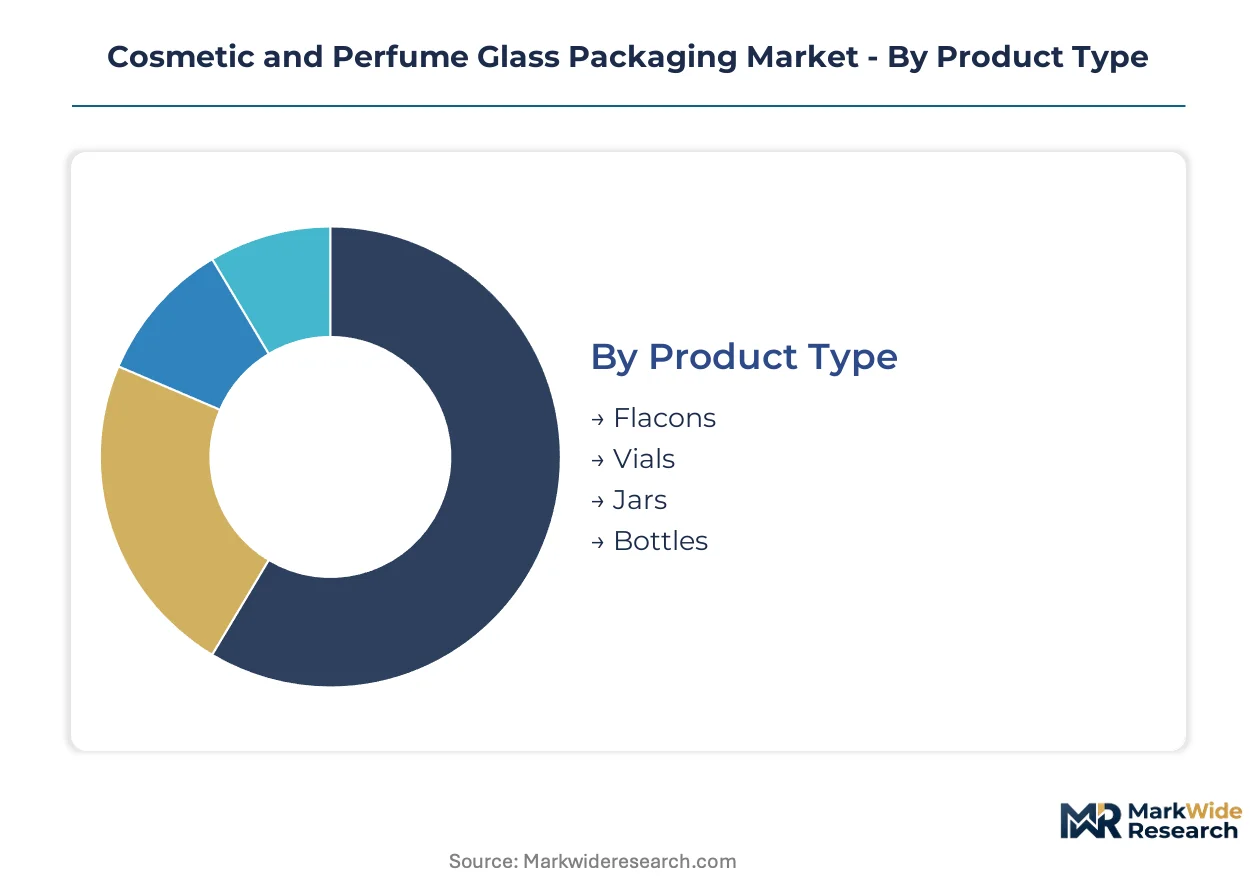
Glass packaging segmentation in cosmetics and fragrances tracks how form, function, and aesthetic positioning split demand across distinct manufacturing capabilities and margin pools. Each dimension carries specific tooling investments, decoration requirements, and customer procurement patterns that shape supplier specialization.
Product Type:
Cost tier splits the market into formats with radically different unit economics and brand equity contribution.
- Flacons:Precision-molded vessels with wall thickness tolerances under 0.5mm, engineered for fragrance oil stability and pump compatibility. Heritage glassworks in France and Italy concentrate production for luxury houses seeking iconic silhouettes as brand assets, with hand-finishing commanding substantial premiums above machine-formed alternatives.
- Vials:Small-format containers typically 5ml to 15ml, blow-molded from borosilicate for sample programs and travel retail. Pharmaceutical-grade certification pathways established by Gerresheimer enable cosmetic brands to leverage existing drug vial quality standards for clinical credibility positioning.
- Jars:Wide-mouth press-and-blow containers for cream and balm formulations, formed from soda-lime with 3mm to 5mm wall thickness for structural rigidity. VERESCENCE's French facilities dominate thick-walled cosmetic jar supply through dedicated press-and-blow furnace lines.
- Bottles:Cylindrical or slab-sided containers for lotion and serum applications, optimized for pump and flip-top closure integration. Zignago Vetro's integrated sand-to-glass operations along Italy's Adriatic corridor sustain cost competitiveness in mid-volume bottle programs.
Flacons command the established base. The steepest expansion runs through vials as sample economy and travel retail accelerate post-pandemic.
Closure Type:
Application requirements dictate precision tolerances and material compatibility that filter supplier qualification.
- Sprayers:Fine-mist pump mechanisms requiring neck finish tolerances within 0.1mm for leak-free crimp sealing. European fragrance houses specify aluminum-overcap sprayers for premium flacons, with crimping equipment investments limiting viable suppliers to established glass decorators.
- Droppers:Pipette assemblies with bulb and collar systems for serum and oil formulations. Indie beauty brands in North America consolidate dropper specifications through distributor aggregators, weakening direct relationships with heritage glassworks.
- Screw Caps:Threaded aluminum or phenolic closures for jars and bottles, with neck thread specifications standardized across ISO 8386 dimensions. German furnace operators maintain dedicated thread-forming tooling for cosmetic screw-cap compatibility.
- Corks:Natural or synthetic stopper systems for vintage-styled fragrance presentations, requiring ground-glass finish precision. Portuguese cork suppliers integrate with French glass decorators for heritage fragrance house programs.
Sprayers anchor the revenue base. Droppers gain share fastest as facial oil and serum categories expand.
Design Style:
Customer type and margin stratification separate commodity decoration from brand-equity-building craft.
- Luxury:Hand-finished crystal and limited-edition collaborations between glassmakers and fashion houses, extracting value through scarcity and provenance signaling. Murano and Normandy master glassblowers execute these programs, though retirement waves outpace apprenticeship pipeline replenishment.
- Minimalist:Understated cylindrical and slab-sided forms reducing decoration costs while achieving shelf differentiation. Indie beauty brands in North America and Europe drive specification growth through direct-to-consumer channels that bypass traditional wholesale markups.
- Vintage:Period-referenced silhouettes with ground stoppers, embossed typography, and amber or cobalt tinting. Niche fragrance houses commission small-batch vintage styling from Italian heritage glassworks for limited distribution.
- Modern:Geometric facets, gradient coatings, and asymmetric profiles enabled by digital decoration technologies. Laser-etched surface treatments from German equipment suppliers compress design iteration cycles from weeks to days.
Luxury styling commands margin concentration. Minimalist formats climb fastest as indie brand purchasing consolidates through distributor channels.
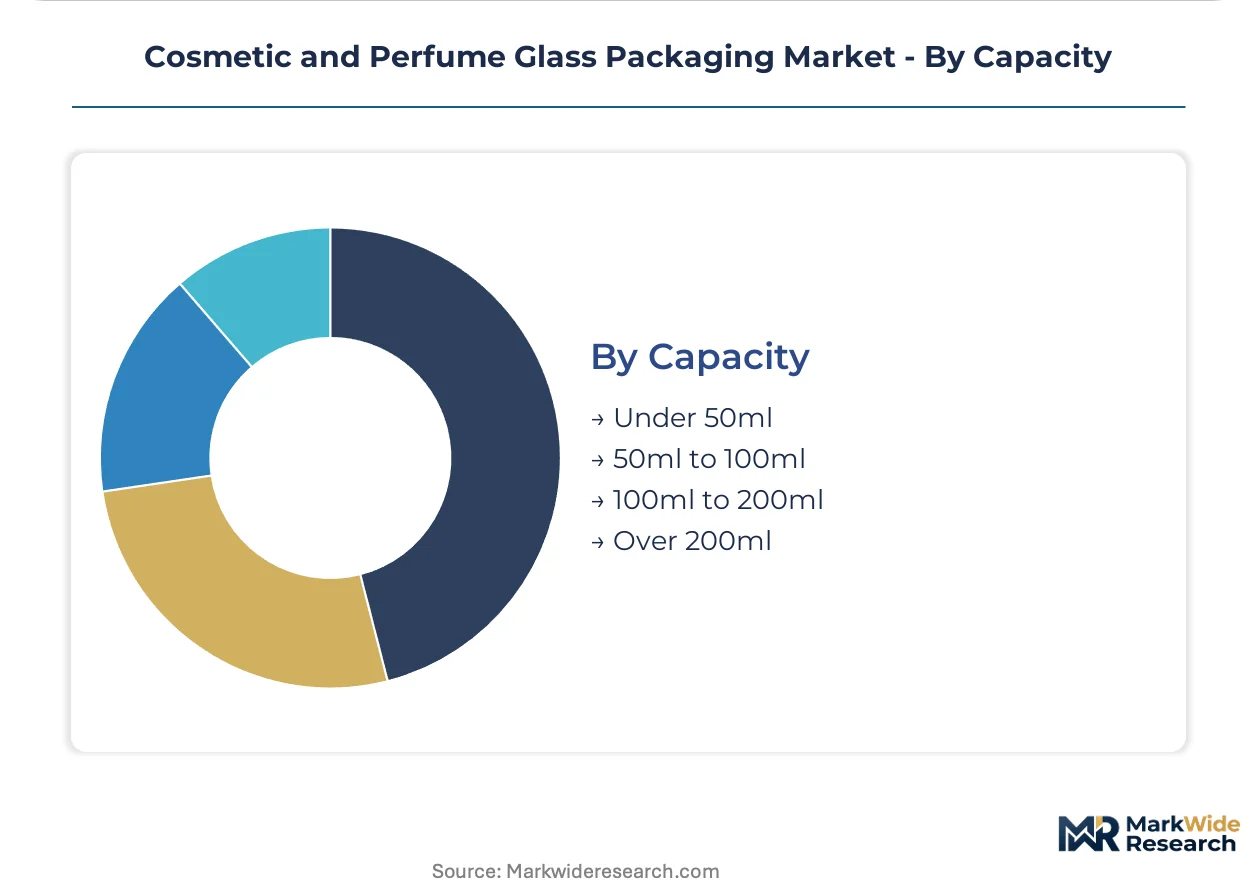
Capacity:
Volume segmentation tracks usage occasion economics from sample conversion to countertop display.
- Under 50ml:Sample and travel formats where aluminum and bio-polymer substitution pressures glass share due to shipping weight disadvantages. REACH compliance deadlines nonetheless push European fragrance houses toward certified glass for regulatory certainty.
- 50ml to 100ml:Standard personal-use fragrance and skincare volumes, representing the core procurement scale for mid-tier glass decorators. France's ANSM-enforced extended producer responsibility schemes impose compliance overhead that squeezes margin pools in this range.
- 100ml to 200ml:Premium household and gift formats with higher per-unit decoration budgets. German furnace operators invest in cullet preprocessing to achieve food-contact-grade purity thresholds for this capacity tier's quality positioning.
- Over 200ml:Countertop display and refill reservoir formats, requiring thicker wall construction for structural integrity. Direct-to-consumer refill subscription programs from luxury houses concentrate demand in this capacity band.
The 50ml to 100ml range holds volume concentration. Under 50ml formats expand most quickly as travel retail and sample economy recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France exports precision-molded flacons to fragrance houses across the United States and Asia, while Italy supplies borosilicate vials to European pharmaceutical-cosmetic crossover brands. This trade-flow pattern concentrates high-value glass packaging production in heritage glassmaking clusters along the Mediterranean basin.
France
Heritage fragrance houses in Paris and Grasse drive demand for hand-finished crystal flacons with sub-millimeter wall tolerances. ANSM enforces extended producer responsibility schemes that push brands toward refillable glass programs. Normandy glassworks clusters supply limited-edition silhouettes that function as brand equity assets for luxury houses.
Italy
Indie beauty brands across Europe procure minimalist cylindrical bottles through distributor-aggregated purchasing channels. EU Green Deal circularity mandates force Venetian glassmakers to document post-consumer recycled content through mass-balance certification. Murano master glassblowers execute vintage-styled programs for niche fragrance houses, though retirement waves strain apprenticeship pipelines.
Germany
Pharmaceutical-grade borosilicate demand from cosmetic brands seeking clinical credibility specifications accelerates furnace investment. ECHA REACH compliance deadlines compress design cycles for certified glass suppliers. Bavarian and Thuringian furnace operators invest in cullet preprocessing facilities to achieve food-contact-grade purity thresholds for premium vial production.
United States
FDA cosmetic labeling requirements govern market access for imported glass containers, creating compliance barriers for European suppliers. Direct-to-consumer indie brands consolidate purchasing through specialized distributors that aggregate small-batch orders. California-based beauty startups drive specification growth for dropper assemblies and minimalist slab-sided bottle formats.
China
Domestic fragrance houses expand glass packaging procurement as local luxury consumption rises. SAMR enforces national standards for cosmetic packaging materials that align with international barrier performance benchmarks. Yangtze River Delta manufacturing zones develop soda-lime bottle capacity for mid-tier skincare brands serving Southeast Asian export markets.
Cosmetic and Perfume Glass Packaging Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. The market structure consolidates around heritage glassworks with artisan finishing capabilities and furnace operators with pharmaceutical-grade certification pathways. Three strategic archetypes dominate: integrated sand-to-glass producers, precision-molded flacon specialists, and pharmaceutical-crossover suppliers. Competitive moves concentrate on furnace reconfiguration for borosilicate compatibility and digital decoration technology licensing.
Within the heritage glassworks archetype, VERESCENCE anchors French luxury flacon production through Normandy-based facilities, while Zignago Vetro exemplifies integrated cost competitiveness along Italy's Adriatic corridor. Gerresheimer occupies a position bridging pharmaceutical-grade borosilicate expertise and premium cosmetic vial manufacturing.
| Leading Market Players |
|---|
| VERESCENCE |
| Zignago Vetro |
| Gerresheimer |
| Aptar Group |
| Bormioli Luigi |
| Saverglass sas. |
| Heinz-Glas |
| Libo Cosmetics |
| Pochet SAS |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Italian soda-lime furnace operations is compressing spot pricing for mid-volume cosmetic bottles while simultaneously elevating premiums for borosilicate-certified capacity in Germany and France. This utilization divergence forces buyers to choose between cost-minimized commodity supply and compliance-assured premium sourcing.
Pricing Analysis
Current-generation soda-lime formulations trade at substantial discounts to prior-generation heavy-walled crystal and next-generation thin-walled borosilicate alternatives. Three-tier pricing structure across premium, standard, and economy levels separates hand-finished crystal flacons from machine-formed soda-lime bottles and distributor-aggregated minimalist formats. Price differentiation hinges on certification grade for REACH compliance and volume scale, with indie beauty brands exhibiting highest sensitivity while heritage fragrance houses absorb premiums for provenance signaling. Pricing pressure stems from aluminum and bio-polymer substitution in travel-size formats, eroding glass share in the under-50ml segment.
Supply Chain Analysis
High-purity silica sand deposits concentrate in Belgium, Turkey, and Egypt, with European furnace operators drawing from these sources for soda-lime batch formulations. Borosilicate production rests on specialized alumina and boron oxide inputs sourced from Germany and the United States. Single-source vulnerability runs through Turkish sand supply lines exposed to regional geopolitical disruption. Distribution runs through heritage glassworks direct channels for luxury houses and distributor-aggregated networks for indie brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refillable flacon platforms are redefining competitive economics as luxury houses capture lifetime value through deposit-based return systems rather than transactional bottle sales. This interoperability shift between packaging and direct-to-consumer subscription infrastructure is restructuring supplier-buyer power dynamics.
For Market Incumbents: Harden furnace reconfiguration timelines by securing offtake commitments from fragrance houses before committing 18-24 month capital cycles to borosilicate compatibility. Deepen backward integration into cullet preprocessing to meet EU Green Deal recycled content mandates ahead of smaller competitors. Aluminum substitution in travel retail and retirement waves among Murano master glassblowers represent parallel threats to volume and craft-positioned margin pools. For New Entrants and Emerging Players: Mid-market borosilicate vial supply for pharmaceutical-cosmetic crossover brands in Germany represents the most penetrable entry point, given Gerresheimer's capacity constraints and REACH compliance deadlines compressing procurement timelines. North American direct-to-consumer indie beauty brands seeking minimalist slab-sided formats offer secondary white-space, with distributor-aggregated purchasing lowering customer acquisition costs. A certification-first go-to-market angle leveraging existing drug vial quality standards accelerates qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across borosilicate furnace conversion projects, favoring incumbent balance sheets over venture-backed entrants. Long-term viability over the next decade centers on optical sorting and decontamination infrastructure for cullet preprocessing, positioning specialized equipment suppliers as acquisition targets. The signal to watch is French ANSM enforcement intensity for extended producer responsibility schemes, which would accelerate consolidation among mid-tier decorators unable to absorb compliance overhead.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Reconfiguration for Borosilicate | REACH compliance deadlines compress qualification timelines for certified suppliers serving European fragrance houses. |
| Cullet Preprocessing Infrastructure Investment | EU Green Deal mandates on post-consumer recycled content create first-mover advantage in mass-balance certification. |
| Direct-to-Consumer Refill Platform Launch | Luxury houses bypass wholesale markups while capturing lifetime value from returnable flacon deposit systems. |
| Laser-Etched Digital Decoration Licensing | German equipment suppliers compress design iteration cycles from weeks to days for limited-edition fragrance programs. |
| Pharmaceutical-Grade Certification Pathway | Cosmetic brands leverage existing drug vial quality standards for clinical credibility positioning in premium skincare. |
Methodological Framework
Cross-validation between furnace operator production disclosures and fragrance house procurement director interviews anchors the qualitative findings. Primary fieldwork encompassed glassworks plant managers, luxury brand packaging directors, distributor category buyers, and ECHA regulatory affairs specialists. Secondary sources included EU REACH substance restriction databases, ANSM extended producer responsibility filings, Italian glass federation trade statistics, and SEC disclosures from listed packaging suppliers. Bottom-up volume modeling triangulated against top-down market sizing from customs trade flows.
Calibration against historical furnace capacity utilization and borosilicate price differentials informed the projection framework across the analysis window. Segmentation dimensions encompassed product type, closure mechanism, design styling, and capacity tier, with regional regulatory cluster as an additional modeled variable. CAGRs derived from weighted average of demand-side procurement forecasts and supply-side capacity expansion announcements. Key inputs included REACH compliance timeline acceleration scenarios and indie brand distributor consolidation rates.
Stress conditions across raw material cost volatility, furnace fuel price spikes, and aluminum substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and brand sustainability commitment durability. Cross-checking against European glass federation production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
India Glass Packaging Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Chile Container Glass Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
Glass Bottles Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Container Glass Coatings Market