
 Hermetic Jars Market | 2026-2036
Hermetic Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Hermetic Jars Market Foresight
Glassblower apprenticeship shortfalls across Central Europe is reorganizing output timelines for premium hermetic jar suppliers. Owens-Illinois sustains manufacturing scale across multiple continents through its furnace network. Ardagh Group differentiates via lightweighting technology that reduces glass mass without compromising seal integrity. Weck Jars leverages its proprietary rubber gasket and wire bail system to anchor loyalty among home-preserving enthusiasts.
Hermetic jars are rigid containers engineered to maintain an airtight seal through precisely matched closure interfaces, typically achieving sub-5 mbar leakage rates under standardized testing. Glass variants dominate food storage applications due to inertness and thermal shock resistance, while plastic jars compete in laboratory use where breakage risk and weight reduction matter. Screw cap closures retain the largest volume share across supermarket and wholesale channels, though snap lid formats are gaining traction in cosmetic packaging where consumer convenience shapes repurchase behavior. Online retail is expanding fastest among distribution channels as direct-to-consumer preserve brands bypass traditional wholesale distributors.
FDA food contact substance regulations govern seal materials and migration limits for jars sold into U.S. food storage applications, while REACH compliance in Europe restricts certain plasticizers and rubber accelerators in gasket compounds. The EU Green Deal's packaging reuse targets are pressuring manufacturers to design for disassembly and material recovery. Stakeholders must weigh capital allocation between glass furnace refurbishment and alternative material pilot lines as regulatory thresholds for recycled content tighten unpredictably across jurisdictions.
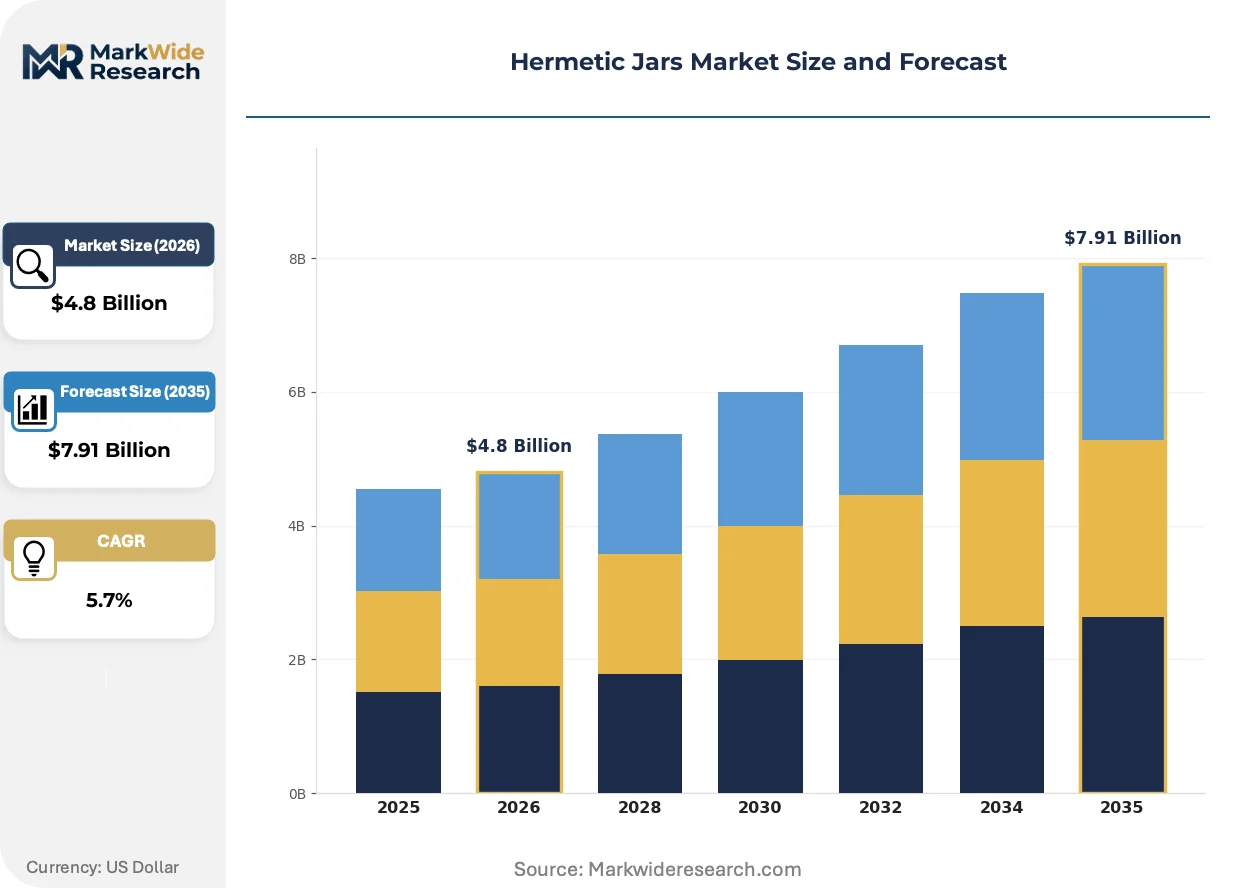
Market Dynamics
The EU Green Deal's packaging reuse targets are compressing design cycles for hermetic jar manufacturers, forcing simultaneous investment in disassembly-friendly closures and furnace efficiency upgrades to meet tightening recycled content thresholds.
Growth Catalysts
- Artisanal food preservation:Specialty producers in Germany and France are expanding glass jar procurement for fermented goods, creating pull-through demand for wire-bail and screw-cap formats.
- REACH compliance migration:ECHA restrictions on phthalate plasticizers in gasket compounds are accelerating substitution toward natural rubber and silicone seal materials.
- Direct-to-consumer channels:Online retail expansion among preserve brands is bypassing traditional wholesale distributors, reshaping volume allocation toward smaller batch sizes.
Market Restraints
- Natural gas price volatility:Glass furnace operations in Central Europe face input cost swings that compress margin predictability for mid-tier converters.
- Glassblower apprenticeship shortfalls:Skill pipeline gaps across the Czech Republic and Slovakia are extending lead times for premium hand-finished jar variants.
- Plastic substitution in laboratory use:Polypropylene and fluoropolymer containers are displacing glass in breakage-sensitive research environments.
Strategic Opportunities
- Cosmetic packaging convenience:Snap-lid formats are gaining traction in skincare and apothecary segments where single-hand opening drives repurchase behavior.
- Indian FSSAI alignment:Food safety modernization in India creates entry pathways for hermetic jar exporters meeting migration-tested seal standards.
- Lightweighting technology convergence:Advanced forming techniques paired with thin-wall glass chemistry enable mass reduction without seal integrity compromise.
Industry Challenges
- Thermal shock certification timelines:ASTM C149 testing protocols for oven-safe glass jars extend product validation cycles by 8-14 weeks.
- Multi-jurisdictional compliance stacking:Simultaneous FDA food contact substance reviews and EU REACH dossier updates strain regulatory affairs bandwidth at mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hermetic Jars Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Jars, Plastic Jars, Metal Jars, Ceramic Jars Market Application: Food Storage, Laboratory Use, Cosmetic Packaging, Chemical Storage Closure Type: Screw Cap, Twist-off Lid, Snap Lid, Cork Stopper Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | Ball Corporation, Owens-Illinois, Ardagh Group, Newell Brands, Bormioli Rocco, Kilner, Weck Jars, Le Parfait, Anchor Hocking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hermetic Jars Market Shifts & Advancements
Closure interface engineering and material traceability systems are the dominant innovation vectors, with manufacturers racing to integrate smart packaging elements while maintaining sub-5 mbar seal performance under standardized testing protocols.
Precision-molded silicone gasket systems are replacing traditional rubber compounds in high-performance hermetic seals. Pharmaceutical packaging buyers in Switzerland and Japan are adopting these formats for moisture-sensitive APIs. The technology is miniaturizing seal footprints while maintaining barrier properties, enabling smaller neck finishes that reduce glass mass per container.
EU Packaging and Packaging Waste Regulation traceability mandates are forcing converters to implement batch-level digital passports for closures and jars. Industrial consequence includes mandatory material composition disclosure to waste sorting facilities. German household brands are responding fastest, embedding QR-linked provenance data directly into lid embossing.
Subscription-based preserve kit services are compressing traditional retail replenishment cycles for home-preserving enthusiasts. Direct-to-consumer channels in France and the UK are displacing supermarket seasonal purchasing with year-round automated delivery. This pattern is most visible among urban millennial households seeking fermentation hobby infrastructure.
Hermetic Jars Market Segmentation
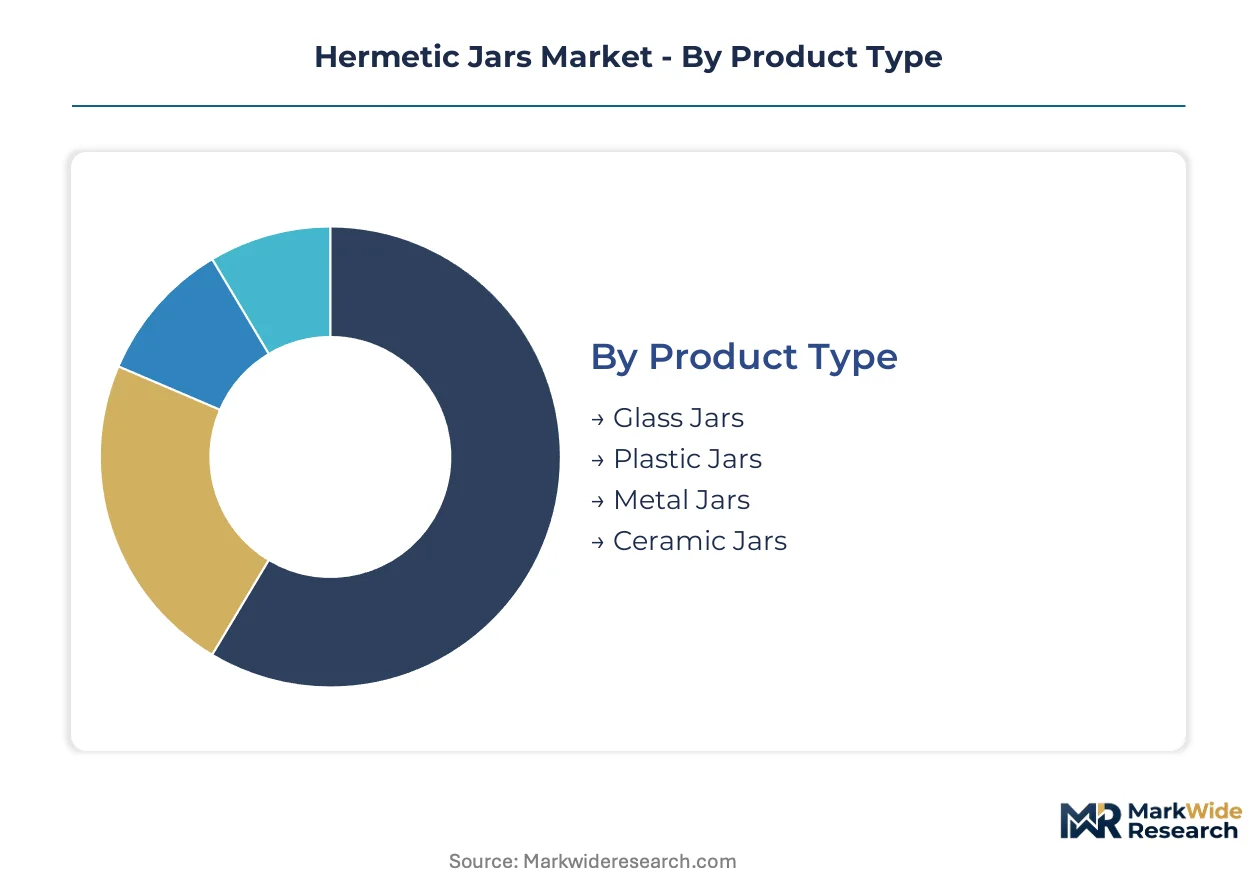
Hermetic jar procurement patterns diverge sharply across material chemistry, end-use specification, and channel access. Segment-level analysis reveals where pricing power concentrates and which technical requirements lock in supplier relationships.
Product Type:
Glass variants dominate export-led procurement from Germany and France, while plastic formats serve cost-sensitive domestic markets in India and Southeast Asia.
- Glass Jars:Borosilicate and soda-lime formulations deliver thermal shock resistance above 150°C differential. German household brands and French artisanal producers anchor demand through certified recyclable closure systems mandated by EU Packaging and Packaging Waste Regulation traceability rules.
- Plastic Jars:Polypropylene and fluoropolymer construction reduces breakage risk in laboratory environments. Indian FSSAI-aligned food safety modernization is accelerating migration-tested seal adoption for domestic pharmaceutical packaging.
- Metal Jars:Tinplate and aluminum substrates serve military and aerospace logistics where impact resistance overrides weight penalties.
- Ceramic Jars:Stoneware and porcelain variants retain niche positioning in premium apothecary and traditional fermentation cultures across Japan and Korea.
Glass Jars commands the established base. The steepest expansion runs through Plastic Jars.
Market Application:
Cost tier stratification separates commodity food storage from validated laboratory and pharmaceutical segments where certification overhead creates margin buffers.
- Food Storage:Fermented goods and artisanal preserves drive specification toward sub-5 mbar leakage rates. German Weck Jars and French Le Parfait systems anchor household penetration alongside commercial kitchen adoption.
- Laboratory Use:ASTM C149 thermal shock certification and USP Class VI biocompatibility testing extend validation cycles. Swiss and Japanese pharmaceutical buyers are adopting precision-molded silicone gasket systems for moisture-sensitive APIs.
- Cosmetic Packaging:Single-hand opening convenience shapes repurchase behavior in skincare segments. Snap-lid formats are gaining traction among urban millennial households in France and the UK.
- Chemical Storage:UN-certified containment for corrosive and flammable substances requires specialized closure torque specifications and gasket material traceability.
Food Storage retains volume leadership. Laboratory Use is climbing the fastest on pharmaceutical packaging demand.
Closure Type:
Volume concentration favors screw-cap commodity production, while margin capture concentrates in proprietary wire-bail and precision-snap systems.
- Screw Cap:Threaded aluminum and phenolic resin closures dominate supermarket and wholesale channels. REACH-compliant gasket substitution toward natural rubber and silicone compounds is accelerating across European converter operations.
- Twist-off Lid:Vacuum-sealing lug finishes serve high-acid food preservation. Owens-Illinois furnace network sustains manufacturing scale across multiple continents for this standardized format.
- Snap Lid:Convenience-driven adoption in cosmetic and apothecary segments where one-handed access drives brand loyalty. Ardagh Group lightweighting technology enables mass reduction without seal integrity compromise.
- Cork Stopper:Traditional sealing for wine, spirits, and specialty vinegar applications where oxygen transmission rates shape aging profiles.
Screw Cap holds the volume base. Snap Lid is gaining share fastest on cosmetic packaging convenience.
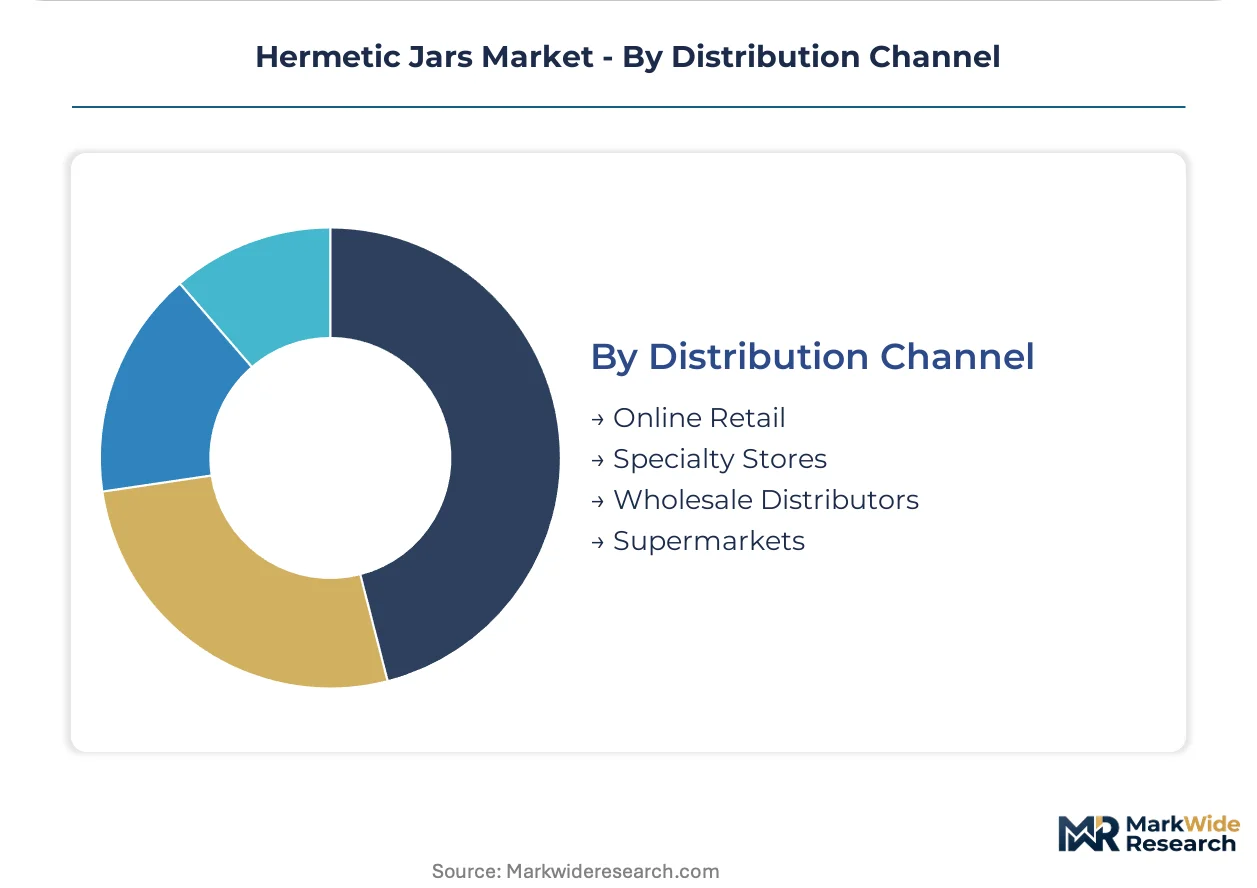
Distribution Channel:
Customer type stratification separates institutional procurement through wholesale distributors from direct-to-consumer subscription models reshaping replenishment cycles.
- Online Retail:Direct-to-consumer preserve brands bypass traditional wholesale intermediaries. Subscription-based kit services in France and the UK compress seasonal purchasing into year-round automated delivery.
- Specialty Stores:Curated fermentation and home-preserving equipment retailers in Germany and Austria serve enthusiast segments with technical guidance and batch-sized inventory.
- Wholesale Distributors:Volume aggregation for commercial food producers and institutional kitchens across Central Europe.
- Supermarkets:Mass-market seasonal purchasing for home canning supplies with private-label penetration in North American and European retail chains.
Wholesale Distributors anchor the established base. Online Retail shows the steepest expansion trajectory on direct-to-consumer channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes hermetic jars primarily for artisanal food preservation, while India deploys them for pharmaceutical packaging compliance and Japan sources precision-sealed formats for moisture-sensitive APIs. This consumption-mix differential shapes distinct procurement specifications across major demand centers.
Germany
Artisanal preserve producers in Baden-Württemberg and Rhineland-Palatinate drive specification toward wire-bail and screw-cap formats with certified recyclable closures. The EU Packaging and Packaging Waste Regulation mandates batch-level traceability, forcing converters in the Stuttgart industrial corridor to embed QR-linked provenance data into lid embossing.
United States
Direct-to-consumer preserve brands in the Pacific Northwest and New England bypass traditional wholesale channels, compressing replenishment cycles through subscription models. FDA food contact substance regulations govern seal materials and migration limits, while specialty retailers in Portland and Burlington serve fermentation hobbyists with technical guidance.
India
Domestic pharmaceutical packaging modernization accelerates demand for migration-tested seals as FSSAI alignment tightens material safety protocols. Maharashtra and Gujarat host the primary converter clusters, with Mumbai-based manufacturers scaling polypropylene jar output for cost-sensitive laboratory markets.
Japan
Swiss and Japanese pharmaceutical buyers adopt precision-molded silicone gasket systems for moisture-sensitive APIs. METI standards and PMDA biocompatibility requirements extend validation cycles, with Osaka and Nagoya serving as the primary procurement hubs for high-performance hermetic seals.
France
Urban millennial households in Île-de-France and Auvergne-Rhône-Alpes drive snap-lid adoption in cosmetic and apothecary segments where single-hand opening shapes repurchase behavior. ECHA REACH restrictions on phthalate plasticizers accelerate substitution toward natural rubber compounds among Lyon-based gasket suppliers.
Hermetic Jars Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with furnace-scale glass manufacturers commanding volume share while proprietary closure designers capture margin premiums. The market structure rewards backward integration into raw material sourcing and forward integration into branded consumer goods. Strategic archetypes include scale-driven furnace operators, lightweighting technology specialists, and heritage-branded closure system owners. Competitive moves center on furnace efficiency upgrades and digital traceability system deployment.
Within the heritage-branded tier, Weck Jars and Le Parfait occupy positions anchored by proprietary rubber gasket and wire bail systems. Owens-Illinois represents scale-driven furnace network consolidation across multiple continents. Ardagh Group exemplifies lightweighting technology convergence, with thin-wall glass chemistry enabling mass reduction without compromising seal integrity.
| Leading Market Players |
|---|
| Ball Corporation |
| Owens-Illinois |
| Ardagh Group |
| Newell Brands |
| Bormioli Rocco |
| Kilner |
| Weck Jars |
| Le Parfait |
| Anchor Hocking |
| Others |
Supply & Pricing Matrix
Furnace network scale across Owens-Illinois's multi-continent footprint anchors both supply concentration and price floors for commodity-grade hermetic jars, while hand-finished premium variants from Central European glassblowers command structural premiums due to apprenticeship pipeline constraints.
Pricing Analysis
Long-term offtake contracts dominate procurement between German artisanal preserve producers and glass converters, insulating volume buyers from natural gas price volatility while spot-market exposure concentrates among smaller cosmetic packaging buyers. Three-tier pricing structure across certified oven-safe, standard food-grade, and economy laboratory tiers separates buyers by ASTM C149 thermal shock certification status. Cost compression in mid-tier soda-lime glass is intensifying because lightweighting technology diffusion erodes mass-based pricing premiums. Private-label supermarket buyers exhibit highest price sensitivity, while Swiss pharmaceutical packers show least sensitivity due to USP Class VI validation requirements.
Supply Chain Analysis
Natural rubber gasket sourcing from Southeast Asian plantations creates a chokepoint for European wire-bail closure manufacturers dependent on REACH-compliant compound traceability. Glass furnace operations concentrate in Germany, Czech Republic, and United States, with borosilicate raw material supply anchored in specialty sand deposits across Bavaria and Ohio. Single-source vulnerability runs through Ukrainian soda ash supply corridors disrupted by regional conflict. Distribution runs through wholesale distributor networks for institutional food producers, while direct-to-consumer subscription channels bypass traditional intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
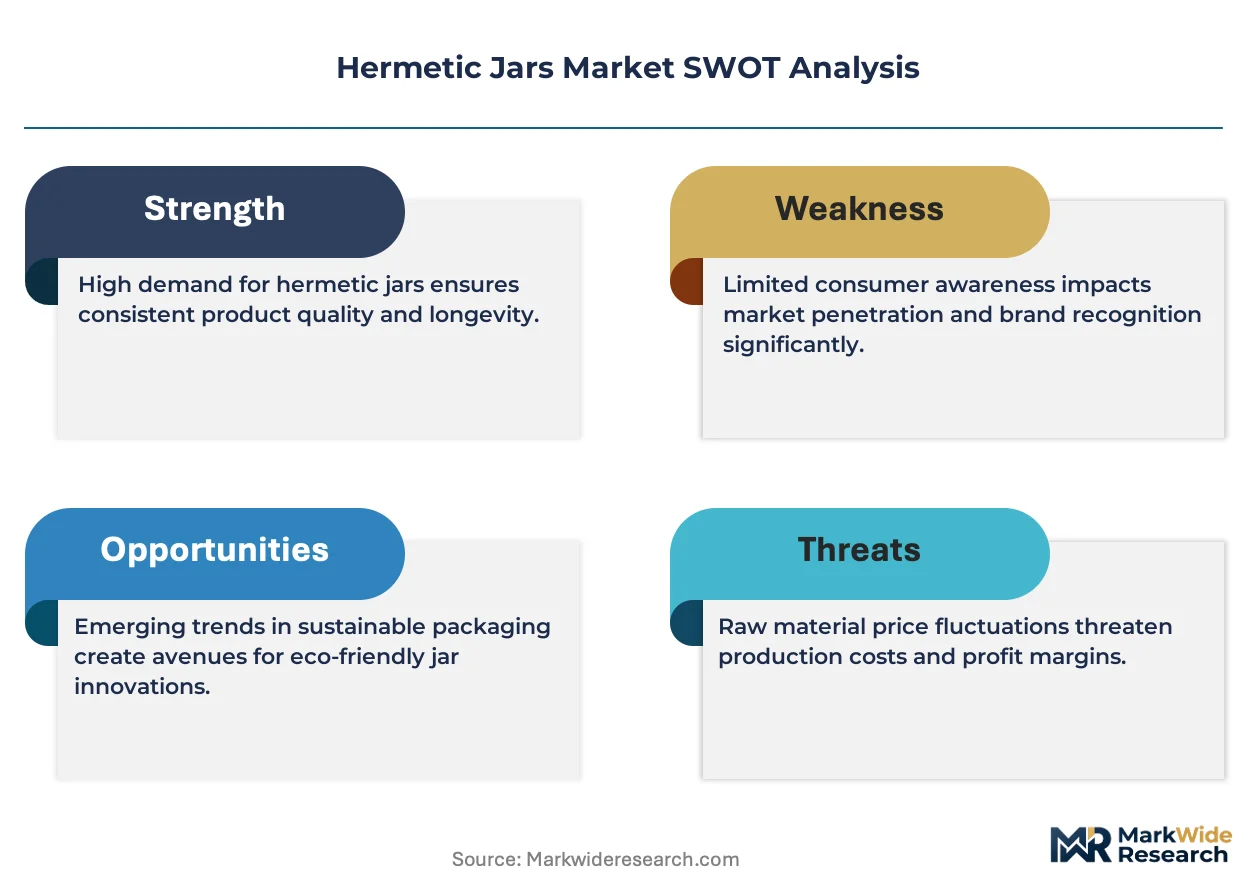
This market functions as a defensive-moat arena where regulatory entrenchment through FDA food contact substance and EU REACH dossier compliance creates switching costs that lock in incumbent positions.
For Market Incumbents: Shield market position by deepening backward integration into certified recyclable closure manufacturing and embedding QR-linked batch traceability systems ahead of EU Packaging and Packaging Waste Regulation mandates. Accelerate furnace efficiency upgrades in Stuttgart and Ohio corridors to offset natural gas price volatility. Prioritize apprenticeship pipeline investments in Czech Republic and Slovakia to defend premium hand-finished jar lead times against capacity constraints. For New Entrants and Emerging Players: FSSAI migration-tested seal certification fast-track offers the most penetrable entry pathway for exporters targeting Maharashtra and Gujarat pharmaceutical packaging clusters. Cosmetic packaging snap-lid segments in France and UK present white-space opportunity where single-hand convenience specifications remain underdeveloped. Pursue direct-to-consumer subscription partnerships with urban millennial fermentation hobby brands to bypass entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage-branded closure system owners with proprietary wire-bail and rubber gasket platforms. Long-term viability over a multi-year horizon favors targets with captive furnace networks and established EU regulatory dossiers. Monitor ECHA restrictions on phthalate plasticizers as inflection indicator for natural rubber and silicone seal material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Deployment | Ardagh Group's thin-wall glass chemistry enables mass reduction without compromising sub-5 mbar seal integrity. |
| Digital Traceability Integration | German household brands embed QR-linked provenance data into lid embossing to satisfy EU Packaging and Packaging Waste Regulation mandates. |
| Direct-to-Consumer Channel Expansion | Subscription-based preserve kit services in France and UK compress seasonal purchasing into year-round automated delivery. |
| Certified Recyclable Closure Investment | Converters toward natural rubber and silicone compounds to meet ECHA REACH phthalate restrictions. |
| Furnace Network Consolidation | Owens-Illinois sustains manufacturing scale across multiple continents through multi-continent furnace footprint. |
Research Methodology
Operator-level perspectives from glass furnace plant managers, procurement leads at German artisanal food producers, cosmetic packaging brand managers, and pharmaceutical regulatory affairs directors anchored the qualitative base. Primary interview findings triangulated against secondary sources including FDA food contact substance filings, ECHA REACH dossier updates, EU Packaging and Packaging Waste Regulation implementation guidance, and customs trade data for borosilicate glass imports. Bottom-up volume modeling across material chemistry and closure type segments converged with top-down market sizing derived from furnace capacity utilization disclosures.
Sensitivity analysis tested forecast outputs against natural gas price volatility scenarios and apprenticeship pipeline recovery trajectories across the projection horizon. Segmentation dimensions modeled include material chemistry, end-use application, closure interface specification, and distribution channel access. CAGRs derived from trend-line extrapolation of volume and value data points, with pharmaceutical packaging demand and direct-to-consumer channel expansion serving as primary growth inputs.
Decision-makers should treat outputs as directional under assumptions of stable EU regulatory enforcement and uninterrupted soda ash supply chains; material deviation would warrant model refresh. Forecasts reflect base-case assumptions around REACH compliance migration timelines and lightweighting technology adoption curves. Practitioners should keep alternative scenarios live as ECHA restriction expansion and FSSAI alignment trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Canada Glass Bottles and Containers Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Russia Glass Packaging Market
Glass Packaging
Switzerland Container Glass Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Nigeria Container Glass Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Germany Container Glass Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Glass Bottle Molds Market