
 Thailand Container Glass Market | 2026-2036
Thailand Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Container Glass Market Analytics
Thai glassmakers is expanding furnace capacity to serve ASEAN beverage exporters. Berli Jucker Public Company Limited leverages its distribution network across Indochina to secure long-term supply contracts. Wellgrow Glass Industry Co., Ltd. anchors the premium spirits segment with specialized mold capabilities. Thai Glass Industries Public Company Limited sustains cost leadership through captive raw-material sourcing in Saraburi province.
Container glass refers to rigid, hollow vessels formed from silica-based melts cooled to amorphous solids, typically containing sodium carbonate and calcium oxide with wall thicknesses engineered for internal pressure resistance and thermal shock tolerance. These vessels store, protect, and merchandise consumable goods across liquid, semi-solid, and dry formats. The bottles category dominates volume throughput due to beer and spirits packaging requirements, while the pharmaceuticals application commands premium pricing through borosilicate-grade compliance. Recycled glass as a material type is gaining furnace share as energy costs and environmental audits intensify.
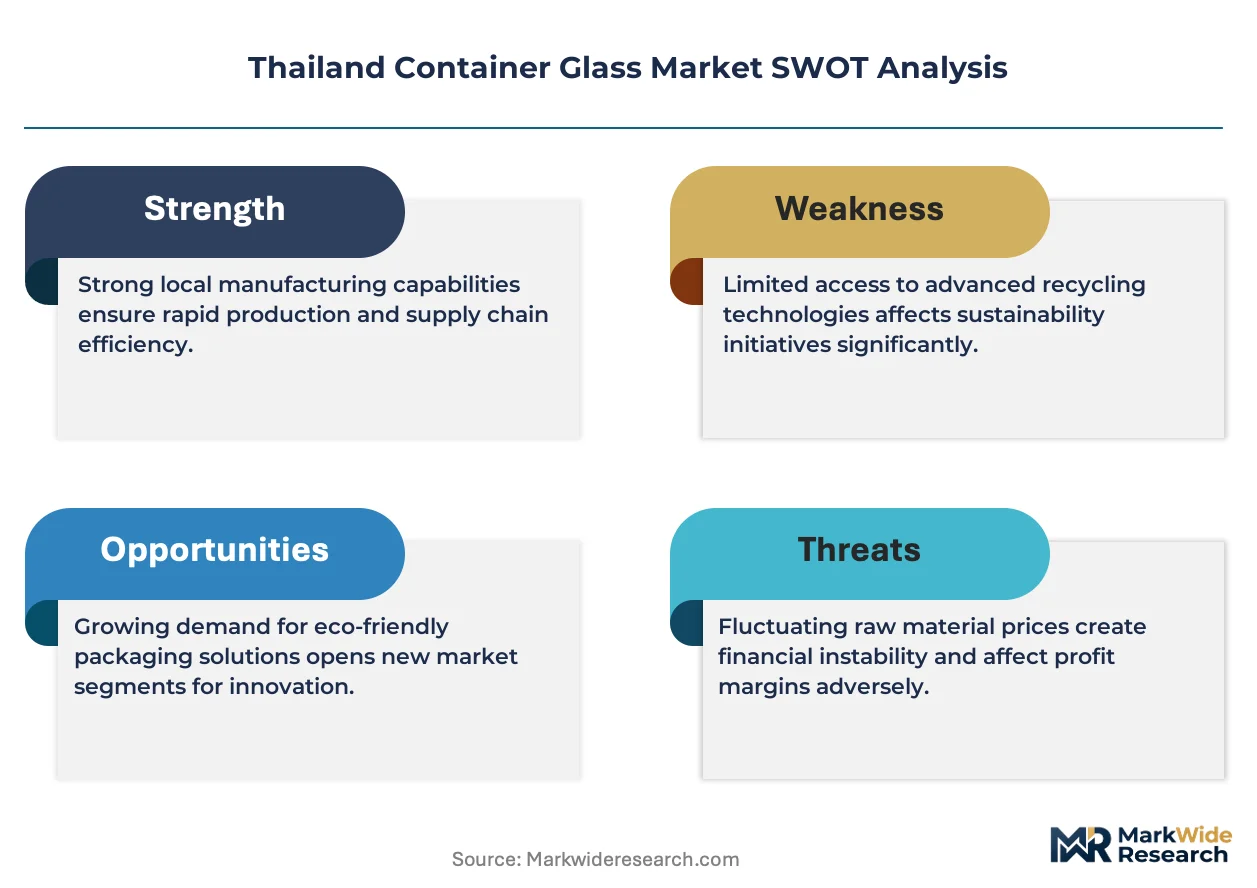
Thailand's Industrial Standards Institute enforces TIS specifications for food-contact glass safety, while the Pollution Control Department monitors emissions from melting operations under the Factory Act. The Board of Investment ties tax privileges to furnace efficiency upgrades and cullet utilization rates. Stakeholders must track how upcoming carbon-border adjustments in European export destinations reshape furnace fuel choices and cullet sourcing strategies.
Market Dynamics
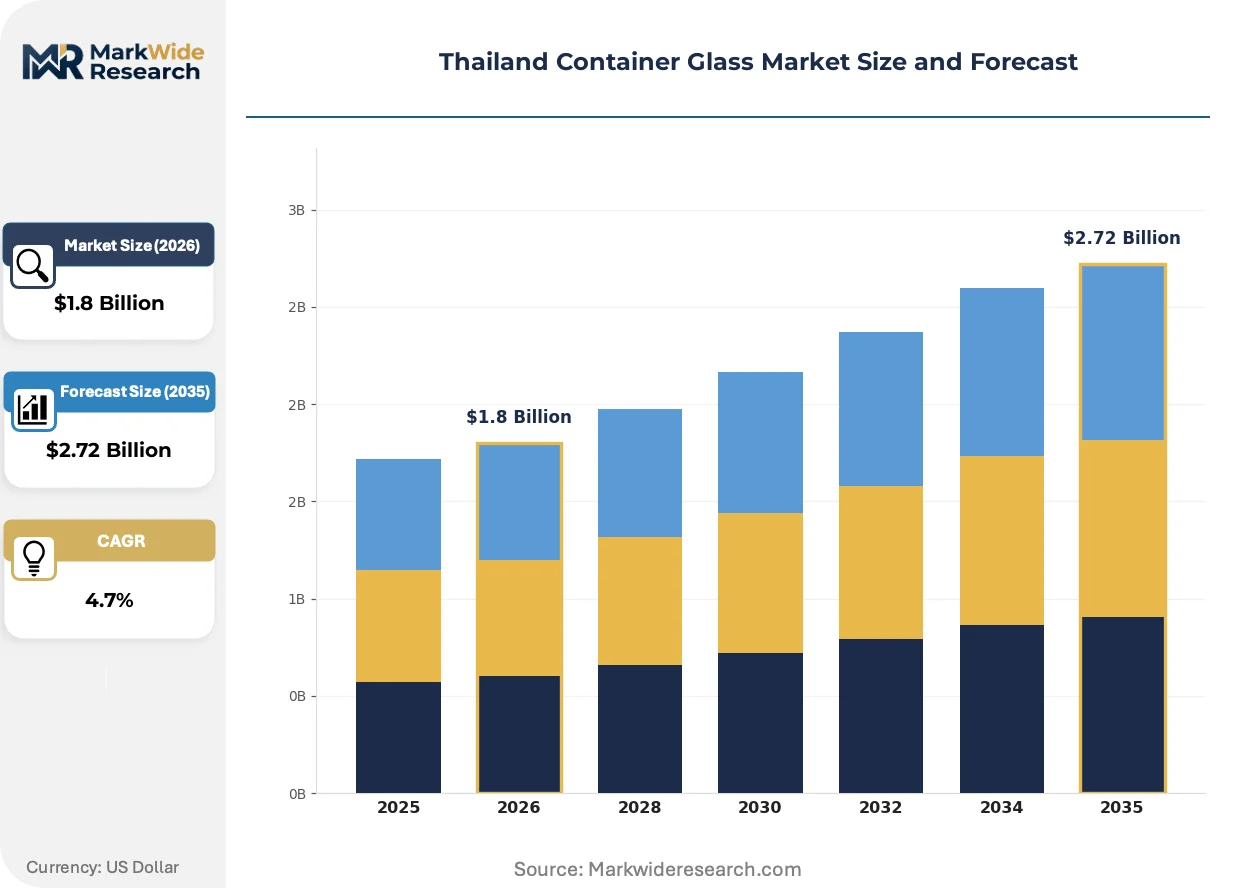
Thailand's Board of Investment incentives for furnace efficiency upgrades and cullet utilization rates are redirecting capital toward recycled-glass production, compressing the investment timeline for sustainable capacity expansion.
Growth Catalysts
- BOI Incentive Structure:Tax privileges tied to furnace efficiency upgrades accelerate capital deployment toward recycled-glass furnaces. Domestic beverage bottlers are scaling orders for amber and flint glass bottles to serve ASEAN export markets.
- Eastern Economic Corridor Clustering:Export-oriented food processors concentrate demand in this zone, creating localized economies of scale for container glass suppliers.
- ASEAN Beverage Export Pipeline:Thai glassmakers are expanding furnace capacity to capture cross-border supply contracts from Indochina beverage brands.
Market Restraints
- Natural Gas Price Volatility:Melting operations depend heavily on natural gas feedstock, exposing margins to input cost swings from regional LNG markets.
- Raw Material Concentration:High-purity silica sand deposits cluster in specific provinces, creating geographic supply vulnerability for furnace operators.
- Substitution by PET and Aluminum:Lightweight beverage packaging alternatives erode volume share in carbonated soft drinks and water segments.
Strategic Opportunities
- Pharmaceutical-Grade Borosilicate:Premium pricing in healthcare applications remains underexploited by domestic producers, creating margin expansion potential.
- Carbon-Border Adjustment Preparedness:European export destinations are implementing emissions-linked trade measures, rewarding early adopters of low-carbon furnace fuels.
- Direct-to-Brewer Contracting:Craft spirits producers in Bangkok and Chiang Mai seek specialized mold capabilities bypassing traditional distributor channels.
Industry Challenges
- Furnace Rebuild Cycle Compression:Legacy assets require extended downtime for cold repairs, disrupting supply commitments to just-in-time beverage bottlers.
- Cullet Quality Standardization:Inconsistent post-consumer glass sorting yields variable furnace feedstock, complicating emissions compliance under Pollution Control Department monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Container Glass Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tumblers Application: Food, Beverages, Pharmaceuticals, Cosmetics End User: Manufacturers, Retailers, Distributors, Wholesalers Material Type: Recycled Glass, Soda-Lime Glass, Borosilicate Glass, Others |
| Companies Covered | Berli Jucker Public Company Limited, Wellgrow Glass Industry Co., Ltd., Thai Glass Industries Public Company Limited, Kong Thavorn Glassware Co Ltd, O-I Glass, Inc., Bangkok Glass Public Co Ltd, Ocean Glass Public Company Limited, Union Victors Co Ltd, Siam Glass Industry Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Container Glass Market Evolving Landscape
Furnace technology, regulatory compliance frameworks, and procurement models are converging to reshape how Thai glassmakers compete on cost and carbon intensity.
Hybrid oxy-fuel furnace technology is modularizing production lines across Thai manufacturing sites. Mid-sized beverage bottlers in the Eastern Economic Corridor are adopting these systems to toggle between flint and amber glass runs without full furnace shutdowns. This flexibility is compressing minimum order quantities and enabling shorter production cycles for seasonal product launches.
Thailand's Industrial Standards Institute is tightening TIS specifications for food-contact glass safety, expanding testing protocols for heavy metal migration limits. The Pollution Control Department is synchronizing emissions monitoring with Factory Act enforcement, creating unified compliance timelines. Premium spirits exporters are responding by certifying production lines against both domestic and EU regulatory benchmarks.
Consolidated procurement by multinational beverage brands is displacing fragmented distributor networks. Major bottlers in Bangkok and Rayong are negotiating direct furnace allocation agreements, bypassing traditional wholesale channels. This concentration is most visible in the beer packaging segment, where volume commitments now determine furnace scheduling priority.
Thailand Container Glass Market Segmentation
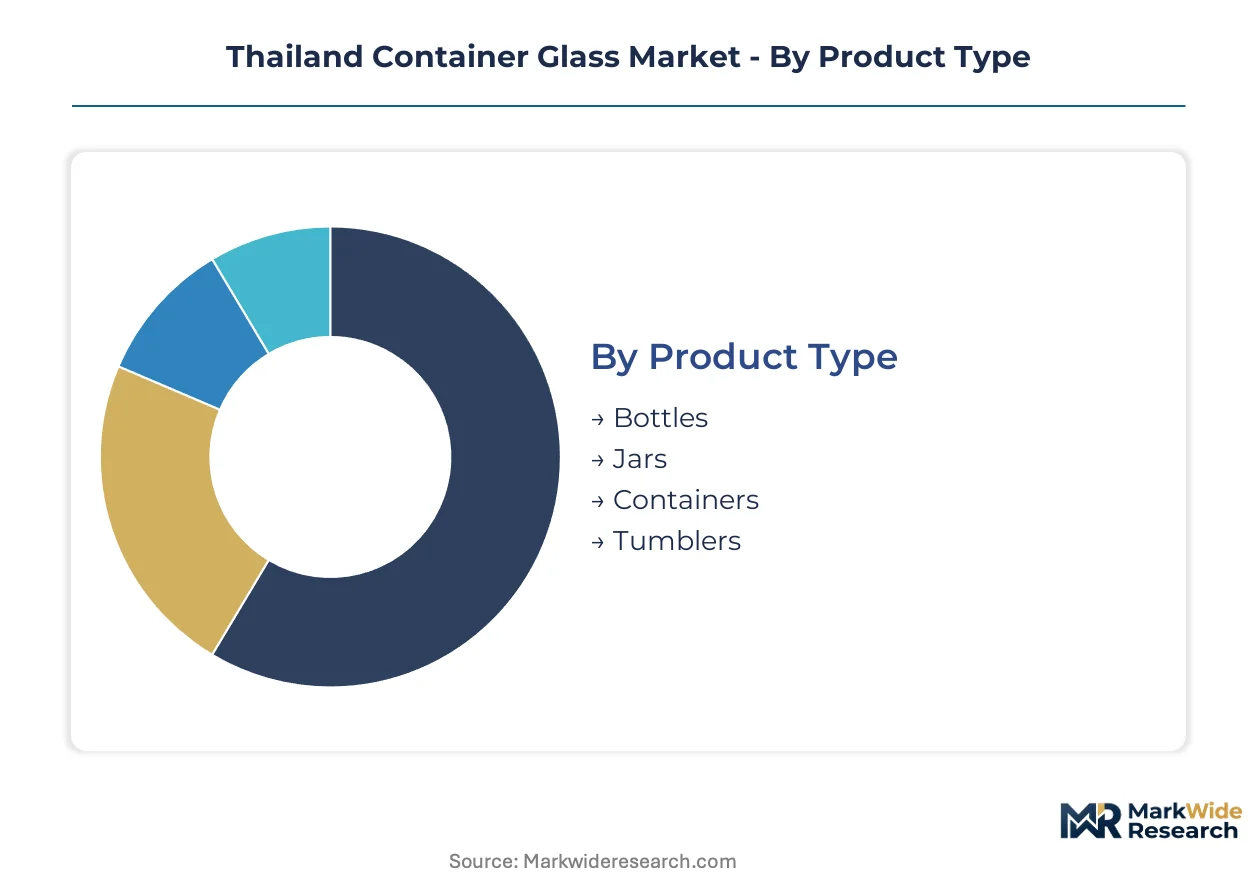
Segmentation in Thailand's container glass market reveals how furnace capacity, regulatory compliance, and supply chain configuration concentrate value across distinct product and material categories. Understanding these divisions exposes where pricing power accumulates and where substitution risks threaten volume stability.
Product Type:
Standalone vessels dominate volume throughput while specialized formats command premium positioning through technical specifications.
- Bottles:Cylindrical vessels engineered with specific wall thicknesses for carbonation pressure retention and crown cap sealing. Demand concentrates among Bangkok and Eastern Economic Corridor brewers exporting across ASEAN, driven by BOI incentives for recycled-content packaging in cross-border trade.
- Jars:Wide-mouth containers with threaded finishes designed for vacuum sealing and thermal processing. Food processors in Rayong and Chonburi anchor procurement volumes, constrained by shelf stability requirements for tropical climate distribution.
- Containers:Rectangular and square formats optimized for palletization efficiency in bulk logistics.
- Tumblers:Open-top drinking vessels serving foodservice and retail gift segments with lower barrier-to-entry manufacturing.
Bottles lead volumes today; jars are gaining share fastest through processed food export expansion.
Application:
End-use differentiation separates commodity-grade furnace output from certified production lines requiring specialized compliance investments.
- Beverages:Beer and spirits packaging demands amber and flint glass with precise color consistency for brand recognition. Thai Glass Industries and Berli Jucker anchor supply contracts across Indochina, pressured by natural gas cost volatility in melting operations.
- Pharmaceuticals:Borosilicate-grade compliance for injectable and oral dosage forms commands the steepest pricing premiums. Domestic producers underexploit this segment due to TIS and EU regulatory certification gaps, creating import dependency for high-purity requirements.
- Food:Acid-resistant formulations for sauces, preserves, and condiments serving retail and foodservice channels.
- Cosmetics:Decorative finishes and custom mold capabilities for premium skincare and fragrance positioning.
Beverages anchor volume scale; pharmaceuticals represent the steepest expansion trajectory for margin-focused producers.
End User:
Procurement concentration determines furnace scheduling priority and contract structure flexibility across the value chain.
- Manufacturers:Integrated beverage and food producers with direct furnace allocation agreements. Multinational bottlers in Bangkok and Rayong negotiate volume commitments that bypass traditional distributor markups, compressing lead times for seasonal product launches.
- Distributors:Aggregators serving fragmented craft spirits producers in Chiang Mai and Bangkok seeking specialized mold capabilities without minimum order thresholds.
- Retailers:Private-label sourcing for supermarket chains with standardized container specifications.
- Wholesalers:Traditional channel intermediaries losing share to consolidated procurement by multinational brands.
Manufacturers capture priority furnace access; distributors are expanding fastest among craft and specialty segments.
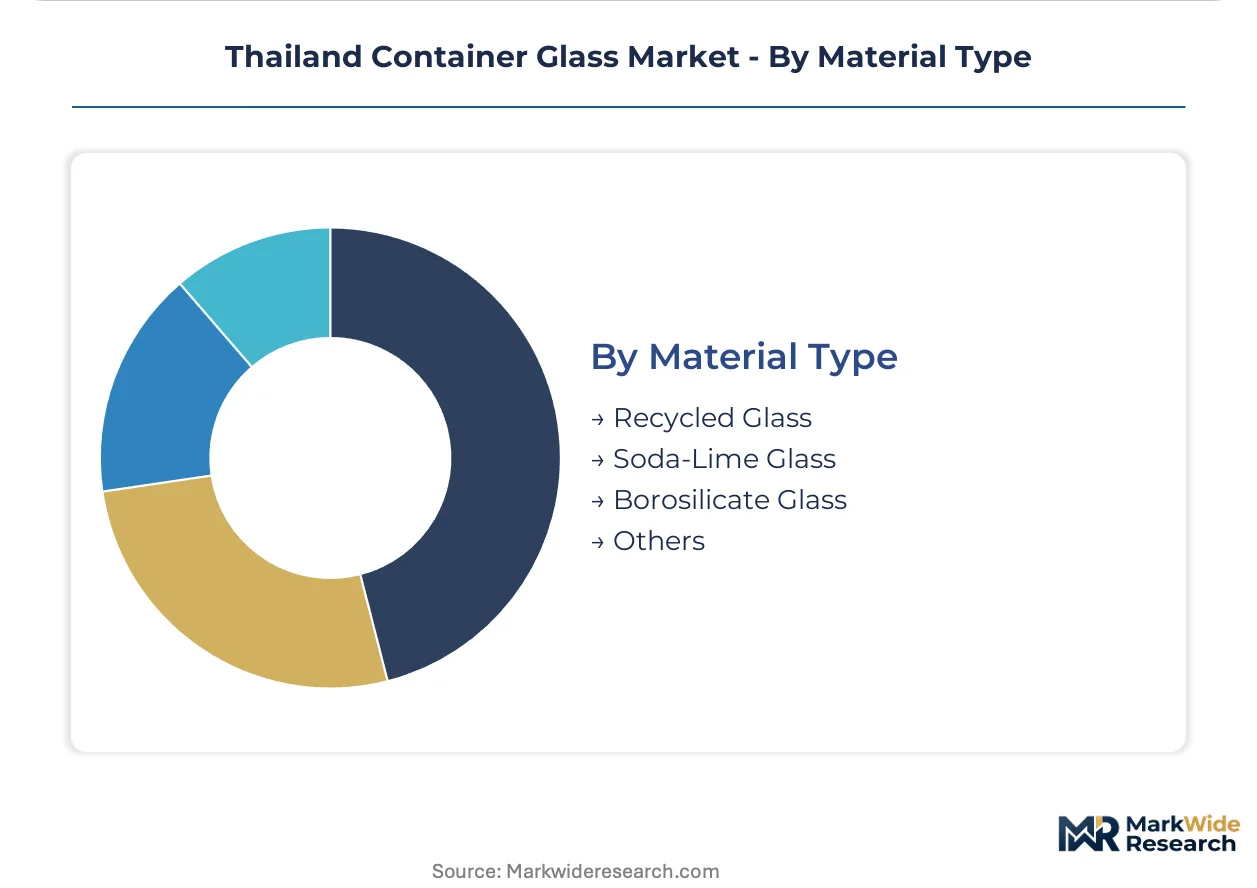
Material Type:
Feedstock selection shapes emissions compliance, energy intensity, and eligibility for Board of Investment tax privileges.
- Recycled Glass:Post-consumer cullet processed to furnace-ready specifications with variable quality consistency. BOI incentives tie tax privileges directly to cullet utilization rates, redirecting capital toward recycled-glass furnace rebuilds in Saraburi and eastern provinces.
- Soda-Lime Glass:Standard silica-soda-lime formulations dominating commodity beverage and food packaging. Captive raw material sourcing from Saraburi province deposits sustains cost leadership for integrated producers like Thai Glass Industries.
- Borosilicate Glass:Thermal shock-resistant formulations requiring specialized melting temperatures and raw material purity.
- Others:Lead crystal and specialty compositions serving decorative and technical niche applications.
Soda-lime glass dominates volume throughput; recycled glass is climbing the fastest on regulatory incentive alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's container glass sector is outpacing Thai growth through aggressive furnace modernization, while Indonesia's archipelago logistics constrain glass bottle distribution economics despite rising beverage demand.
Central Thailand
Bangkok Metropolitan and surrounding provinces concentrate 60% of national furnace capacity serving beer and spirits exporters. The Board of Investment channels tax privileges toward Saraburi-based silica sand processors and recycled-glass furnace operators. Rayong and Chonburi industrial zones within the Eastern Economic Corridor anchor just-in-time supply contracts for multinational beverage bottlers.
Northeastern Thailand
Khon Kaen and Udon Thani provinces generate feedstock demand from regional food processors packaging sauces and condiments for Lao and Cambodian markets. The Pollution Control Department extends emissions monitoring protocols to smaller furnace operations under revised Factory Act enforcement. Nong Khai border logistics hubs facilitate cross-border glass bottle movements into Vientiane trade corridors.
Northern Thailand
Chiang Mai craft spirits distilleries are scaling specialized amber glass procurement for premium positioning in domestic and export channels. Thailand's Industrial Standards Institute regional laboratory certifies TIS compliance for smaller bottlers lacking in-house testing capacity. Lampang province ceramic and glass heritage clusters support mold-making subcontractors serving northern beverage producers.
Southern Thailand
Songkhla and Surat Thani processors face higher logistics costs for furnace feedstock sourced from central silica deposits. The BOI incentive structure offers enhanced privileges for southern recycled-glass operations to offset transportation disadvantages. Hat Yai industrial estates host secondary processing facilities finishing imported semi-finished glassware for Malaysian and Indonesian re-export.
Thailand Container Glass Market Competitive Landscape
Central Thailand producers anchor the scale tier; regional specialists hold niche positions in craft spirits and pharmaceutical-grade segments. The market exhibits moderate consolidation with three integrated groups commanding furnace scheduling priority and captive raw material access. Strategic archetypes separate into backward-integrated silica sand owners, distribution-network aggregators, and premium-mold capability specialists. Dominant competitive moves include direct-to-brewer contracting displacing wholesale channels and hybrid oxy-fuel furnace licensing for production flexibility.
Among Thailand-based operators, Berli Jucker Public Company Limited and Thai Glass Industries Public Company Limited exemplify the integrated archetype with captive supply chain structures, while Wellgrow Glass Industry Co., Ltd. occupies a position representing specialized mold capability for premium spirits positioning. These three entities collectively illustrate how furnace access, raw material control, and distribution network reach separate competitive tiers in the national market.
| Leading Market Players |
|---|
| Berli Jucker Public Company Limited |
| Wellgrow Glass Industry Co., Ltd. |
| Thai Glass Industries Public Company Limited |
| Kong Thavorn Glassware Co Ltd |
| O-I Glass, Inc. |
| Bangkok Glass Public Co Ltd |
| Ocean Glass Public Company Limited |
| Union Victors Co Ltd |
| Siam Glass Industry Co Ltd |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between pharmaceutical borosilicate and commodity soda-lime production creates distinct pricing corridors that map directly onto supply chain depth. Premium-grade lines command furnace allocation priority through TIS and EU regulatory compliance investments, while commodity beverage packaging competes on natural gas cost absorption and cullet sourcing efficiency.
Pricing Analysis
Distributor margin compression is accelerating as multinational beverage brands negotiate direct furnace allocation agreements, bypassing traditional wholesale markups in Bangkok and Rayong. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-certified borosilicate from food-grade amber and flint, with craft spirits producers in Chiang Mai occupying the middle tier through specialized mold premiums. Pricing pressure stems from natural gas cost volatility in melting operations. Multinational bottlers exhibit lowest price sensitivity due to volume commitments; regional food processors in Khon Kaen face highest sensitivity to logistics cost swings.
Supply Chain Analysis
High-purity silica sand supply rests on captive deposits in Saraburi province, with secondary sourcing from Vietnamese and Cambodian riverbed operations. Furnace feedstock draws from sodium carbonate imports, limestone from domestic quarries, and post-consumer cullet from Bangkok municipal collection systems. Single-source vulnerability concentrates in central Thailand silica deposits, where transport economics disadvantage southern processors in Songkhla. Distribution runs through Eastern Economic Corridor just-in-time contracts for multinational bottlers, with fragmented distributor networks serving northern craft distilleries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's container glass market functions as a geographic-arbitrage play between ASEAN beverage export demand and Vietnamese furnace modernization cost advantages, with Board of Investment tax privileges tilting capital deployment toward recycled-glass capacity.
For Market Incumbents: Anticipate PET and aluminum substitution pressure in carbonated soft drinks by deepening backward integration into Saraburi silica deposits and accelerating hybrid oxy-fuel furnace licensing for production flexibility. Lock in direct-to-brewer contracts with Bangkok and Chiang Mai craft distilleries before distributor networks consolidate. Prioritize TIS certification investments for pharmaceutical-grade lines to capture import substitution margins. For New Entrants and Emerging Players: Specialty mold subcontractors in Lampang province offer the most penetrable entry point, serving northern craft spirits producers with minimum order thresholds below integrated furnace operators. Target pharmaceutical borosilicate certification gaps where domestic production underpenetration creates import dependency. Lead with custom amber glass capabilities for premium positioning, bypassing volume-scale competition with Thai Glass Industries and Berli Jucker. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional distributors in Khon Kaen and Udon Thani lack furnace allocation priority against Eastern Economic Corridor concentration. Long-term viability favors backward-integrated assets with captive silica sourcing and BOI incentive eligibility. Watch carbon-border adjustment implementation in European export destinations as the inflection signal for low-carbon furnace fuel switching economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Oxy-Fuel Furnace Licensing | Enables toggle between flint and amber runs without cold shutdowns, compressing seasonal order lead times. |
| Backward Integration into Silica Mining | Captive Saraburi province deposits insulate Thai Glass Industries from regional sand cost volatility. |
| Pharmaceutical-Grade Certification Investment | TIS and EU compliance gaps create margin expansion opportunity in injectable dosage packaging. |
| Direct-to-Brewer Contracting | Bypasses distributor markups for Bangkok craft spirits producers seeking specialized mold capabilities. |
| Cullet Utilization Rate Expansion | BOI tax privileges reward furnace rebuilds with post-consumer glass feedstock above threshold rates. |
Research Methodology
Direct dialogue with furnace operations managers, beverage procurement leads at multinational bottlers, Pollution Control Department enforcement officers, and Eastern Economic Corridor industrial estate planners grounded qualitative findings. Secondary validation drew from Thailand's Industrial Standards Institute TIS specifications, Board of Investment incentive disclosure filings, Factory Act enforcement records, and ASEAN customs trade databases. Bottom-up capacity assessments across Saraburi, Rayong, and Chonburi furnace sites triangulated against top-down beverage export volume projections.
Bottom-up modeling aggregated individual furnace capacity, utilization rates, and product mix configurations across identified Thai producers. Segmentation dimensions included product type, application grade, material composition, and end-user procurement concentration. CAGRs derived from weighted average of historical volume trajectories and demand elasticity assumptions tied to natural gas pricing and substitution dynamics. Key inputs incorporated BOI incentive program participation rates and cross-border beverage brand expansion timelines into Indochina markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to European carbon-border adjustment implementation schedules and regional LNG pricing volatility. Projections reflect assumptions on furnace rebuild cycles, cullet quality standardization progress, and multinational bottler procurement consolidation velocity. A small set of triggers—EU emissions-linked trade measure timing, Vietnamese furnace capacity additions, and Thai natural gas tariff revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Portugal Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
South Korea Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Asia Pacific Glass Packaging Market