
 Beveled Edge Jars Market | 2026-2036
Beveled Edge Jars Market Size, Share, and Industry Trends Forecast 2026-2036
Beveled Edge Jars Market Outlook
Buyer concentration among premium cosmetics houses is restructuring procurement patterns across the beveled edge jars supply base. Ardagh Group leverages its European furnace network to serve fragrance houses with customized rim profiles. Gerresheimer anchors pharmaceutical-grade beveled edge capacity through dedicated clean-room finishing lines. Saver Glass competes on decorative depth, offering multilayer silk-screening that turns the beveled shoulder into a branding surface.
Beveled edge jars are rigid containers featuring an angled or chamfered rim transition between the body and closure land, typically manufactured through press-and-blow or blow-and-blow glass forming with secondary fire-polishing to achieve precise edge geometry. The angled rim distributes clamping forces evenly across closure gaskets, making these jars suitable for vacuum-sealed food preserves, hygroscopic pharmaceuticals, and oxygen-sensitive cosmetics. Glass jars dominate premium positioning where thermal stability and chemical inertness command priority, while plastic jars occupy cost-driven segments in mass retail condiments and household chemicals. The cosmetics end-user channel generates the highest margin pools, particularly for small-capacity uniquely shaped contours that signal artisanal formulation. Medium-capacity standard contours in food industry applications represent a mature volume base with limited pricing power.
The EU Packaging and Packaging Waste Regulation and REACH compliance requirements shape material choices and recycling obligations for glass and plastic jar producers across European member states. FDA standards govern pharmaceutical jar specifications for U.S. export-bound production lines, while EMA guidelines on primary packaging stability influence acceptance criteria for drug-contact glass surfaces. Stakeholders must monitor evolving extended producer responsibility fee structures and decide whether to absorb compliance costs or pass them through premium positioning strategies.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing recycled glass availability while premium cosmetics houses concentrate procurement around Rhine-Main decorators, forcing furnace networks to reconfigure batch chemistry and finishing capacity.
Growth Catalysts
- Rhine-Main Cluster Specialization:Germany's packaging corridor hosts concentrated silk-screening and fire-polishing capabilities that serve Paris-based fragrance houses with 48-hour turnaround on custom rim profiles.
- REACH Compliance Premium:ECHA substance restrictions on plastic additives redirect pharmaceutical primary packaging demand toward borosilicate beveled edge formats with certified drug-contact surfaces.
- Fire-Polishing Automation:Robotic flame-treatment systems reduce edge-geometry variance below 0.1mm, enabling vacuum-seal reliability for hygroscopic skincare formulations.
Market Restraints
- Cullet Supply Volatility:Post-consumer recycled glass availability fluctuates with municipal collection rates, forcing Ardagh and Gerresheimer to maintain dual-batch furnace configurations.
- Energy Cost Exposure:Natural gas prices govern melting economics; German furnace operators face particularly acute input cost pressure from pipeline supply reconfiguration.
- Plastic Substitution Threat:Polypropylene jars with molded-in beveled shoulders capture mass-market condiment volumes where oxygen barrier requirements permit polymer migration.
Strategic Opportunities
- Pharmaceutical-Grade Expansion:EMA stability guidelines for primary packaging create acceptance pathways for drug-contact beveled edge formats in oncology and biologic delivery systems.
- Decorative Surface Convergence:Multilayer digital printing fused with traditional fire-polishing transforms the angled shoulder into a substrate for serialized authentication and brand storytelling.
- Clean-Room Finishing:Dedicated ISO 14644-1 Class 7 lines for pharmaceutical customers command 40-60% price premiums over standard cosmetic-grade output.
Industry Challenges
- Skilled Fire-Polishing Labor Scarcity:The craft-dependent finishing stage lacks apprenticeship pipeline depth; German decorators compete for aging specialist workforces.
- Batch Certification Timelines:US FDA drug master file approvals for new glass compositions extend 18-24 months, freezing formulation innovation cycles for export-bound pharmaceutical lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beveled Edge Jars Market |
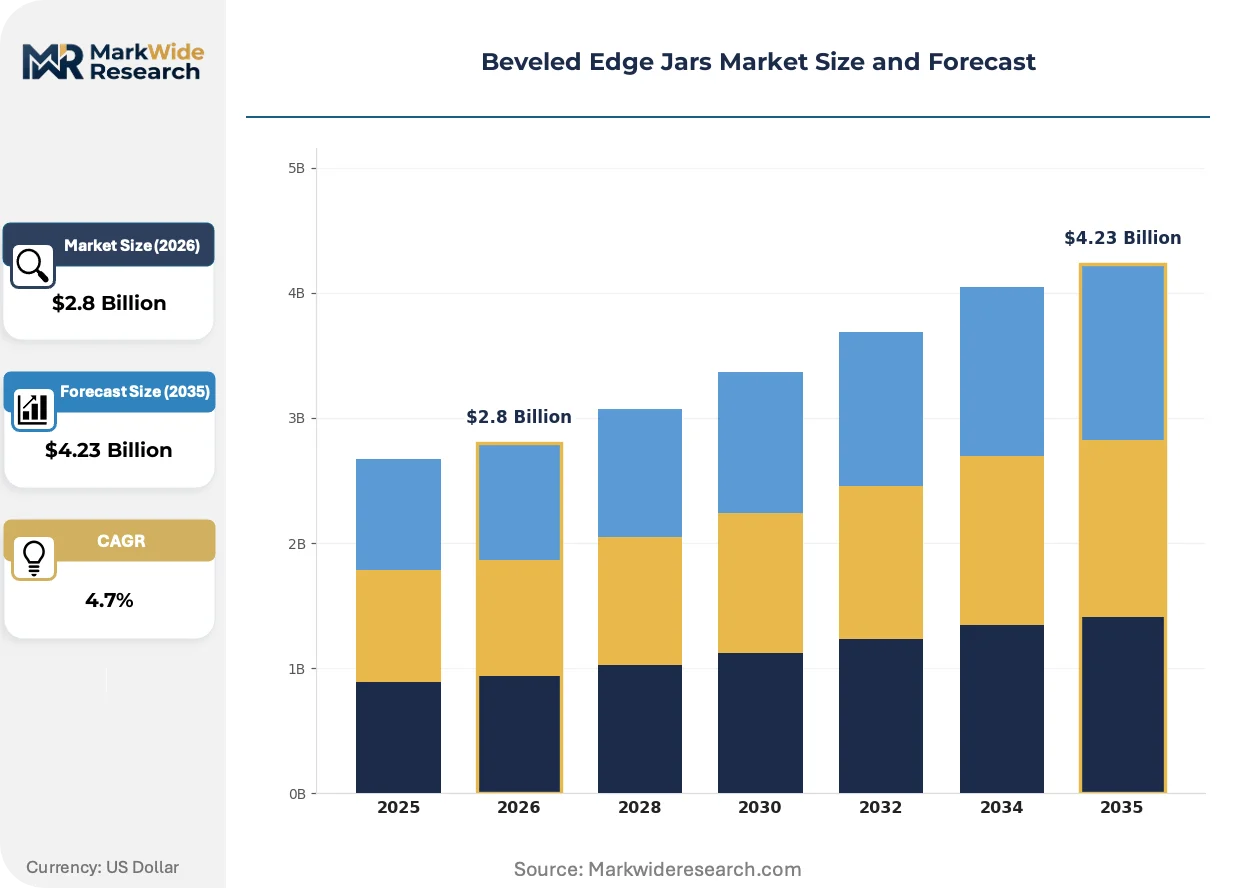
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
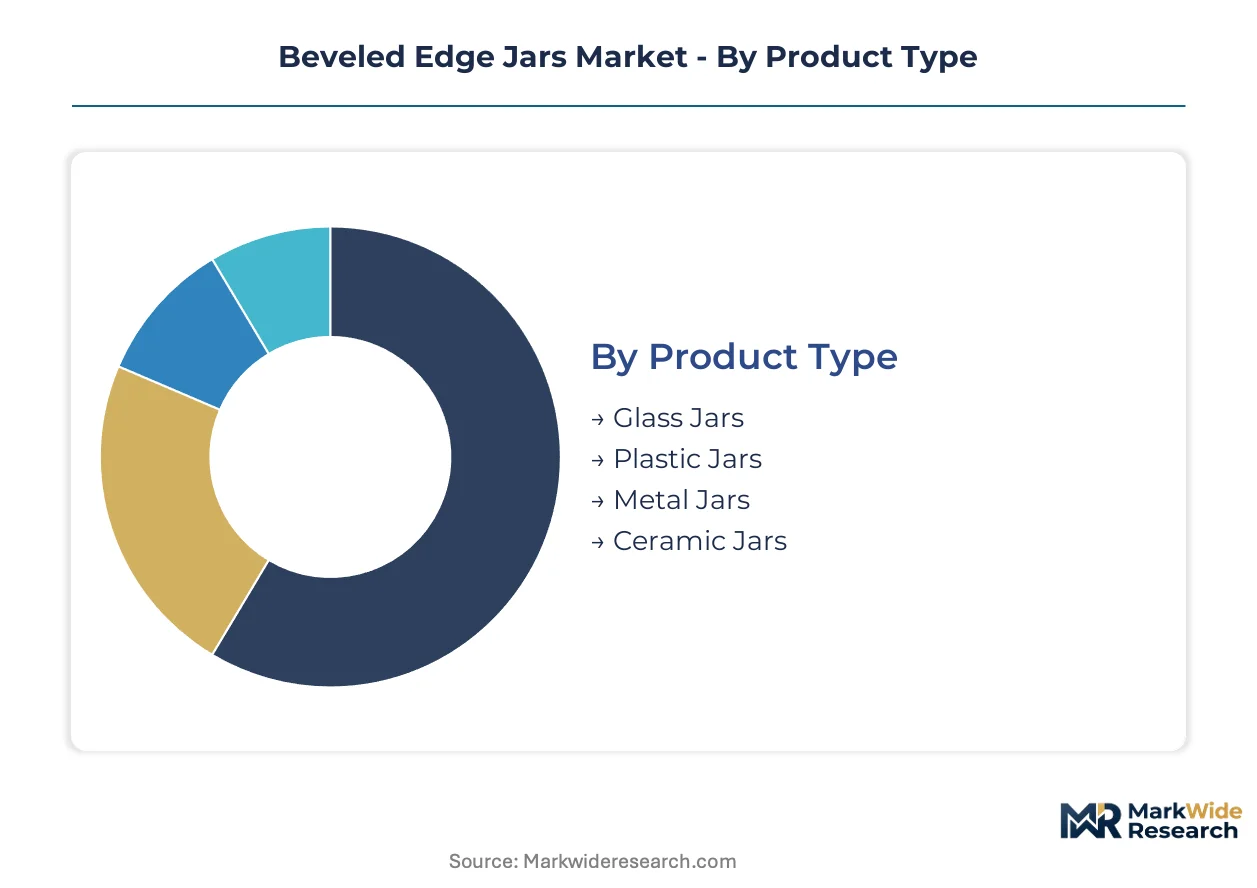
| Segmentation | Product Type: Glass Jars, Plastic Jars, Metal Jars, Ceramic Jars Capacity: Small, Medium, Large, Extra Large End User: Retail, Food Industry, Cosmetics, Pharmaceuticals Contour: Standard, Tall, Wide, Uniquely Shaped |
| Companies Covered | Berlin Packaging, Ardagh Group, Verallia, Owens-Illinois, Gerresheimer, PakTech, Vitro Packaging, Saver Glass, Stoelzle Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beveled Edge Jars Market Strategic Shifts
Digital decoration technologies and regulatory batch-traceability requirements are converging to transform the beveled shoulder from a functional seal surface into an active information layer and brand authentication zone.
Laser-etched microstructures is rewriting how authentication integrates with primary packaging. The technology embeds machine-readable diffractive patterns directly into fire-polished glass surfaces without compromising seal integrity. Swiss fragrance houses and German pharmaceutical contract manufacturers are piloting these formats for anti-counterfeiting and supply-chain provenance tracking.
EU Green Deal packaging mandates are tightening recycled content thresholds for glass containers placed on the European market. ECHA is evaluating additional substance restrictions on colorants and surface treatments used in decorative finishing. German furnace operators are responding by qualifying alternative decolorizing agents and investing in cullet pre-treatment infrastructure to meet 2030 circularity targets.
Buyer consolidation among luxury beauty conglomerates is compressing supplier rosters and extending contract durations. Procurement teams at LVMH and Kering-affiliated houses now demand dedicated finishing line capacity with guaranteed volume allocations rather than spot-market purchasing. This shift concentrates margin capture with decorators who can commit capital to captive production modules.
Beveled Edge Jars Market Segmentation
Beveled edge jar procurement splits sharply between mass-market standardization and premium customization, with furnace networks and decorators configuring entirely different production economics for each tier. Understanding where buyers sit on this spectrum determines supplier selection, lead times, and margin capture across the value chain.
Product Type:
Customization intensity varies from fully bespoke fire-polished rims to injection-molded commodity shoulders, with material chemistry dictating both functional performance and decorative latitude.
- Glass Jars:Soda-lime and borosilicate compositions undergo press-and-blow or blow-and-blow forming followed by robotic flame-treatment to achieve sub-0.1mm edge geometry variance. Premium cosmetics houses in France and Germany concentrate procurement here for thermal stability and oxygen barrier performance in fragrance balms and skincare serums.
- Plastic Jars:Polypropylene and PET formats with molded-in beveled shoulders capture mass-market condiment volumes where cost compression outweighs barrier requirements. Polypropylene substitution is accelerating in household chemicals as ECHA evaluates additional additive restrictions that redirect some pharmaceutical demand back toward glass.
- Metal Jars:Aluminum and tinplate containers with rolled or crimped beveled edges serve specialty food preserves and industrial sealants requiring electromagnetic shielding or extreme temperature cycling.
- Ceramic Jars:Stoneware and porcelain formats with glazed beveled rims occupy artisanal food and home fragrance niches where tactile weight and kiln-fired aesthetics command positioning premiums.
Most installed capacity flows through Glass Jars. Expansion is steepest in Plastic Jars.
Capacity:
Volume scale determines furnace batch economics, decorator setup amortization, and whether buyers qualify for dedicated line allocation or spot-market scheduling.
- Small:Sub-100ml formats dominate luxury skincare and fragrance balm applications where unit margins absorb complex contour tooling and multilayer silk-screening costs. Rhine-Main decorators achieve 48-hour turnaround on custom rim profiles for Paris-based fragrance houses at this scale.
- Medium:Standard 100-500ml capacities anchor mature food industry demand for vacuum-sealed preserves and condiments, with limited pricing power and high volume sensitivity to polypropylene substitution.
- Large:500ml-2L formats serve institutional food service and bulk pharmaceutical compounding where palletization efficiency and closure torque consistency outweigh decorative investment.
- Extra Large:Above-2L containers address industrial chemical storage and foodservice bulk dispensing, with beveled edge geometry ensuring gasket distribution under heavy content loads and thermal expansion stress.
Medium capacity commands the largest production footprint. Small capacity is climbing the fastest.
End User:
Application-specific certification requirements and aesthetic demands fragment the supplier base into pharmaceutical-grade, cosmetic-premium, and food-industrial tiers with minimal overlap.
- Retail:Mass-market condiments and household chemicals drive high-volume, low-margin demand where polypropylene beveled shoulders displace glass on cost grounds.
- Food Industry:Vacuum-sealed preserves and oxygen-sensitive sauces require precise edge geometry for gasket compression, with German and French processors specifying borosilicate for thermal shock resistance in pasteurization lines.
- Cosmetics:Small-capacity uniquely shaped contours generate the highest margin pools, with LVMH and Kering-affiliated houses demanding dedicated finishing line capacity and guaranteed volume allocations rather than spot purchasing.
- Pharmaceuticals:EMA stability guidelines for primary packaging and FDA drug master file requirements govern borosilicate beveled edge acceptance for oncology and biologic delivery systems, commanding 40-60% price premiums over cosmetic-grade output.
Food Industry absorbs the majority of standard capacity. Cosmetics is gaining share fastest.
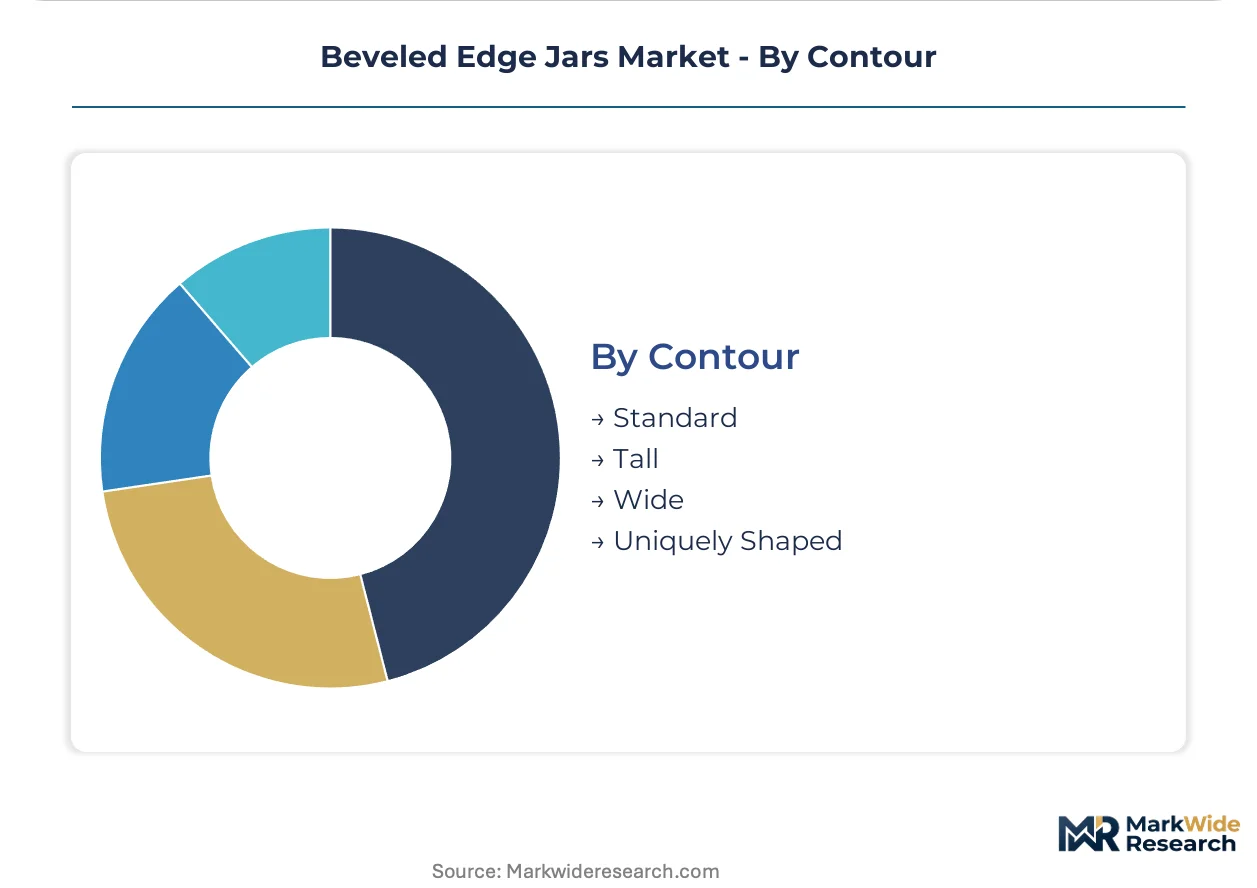
Contour:
Geometric complexity determines tooling amortization, decorator setup time, and whether the beveled shoulder serves as functional seal surface or active branding substrate.
- Standard:Cylindrical or slight taper profiles minimize tooling investment and maximize furnace throughput, serving commodity food and industrial chemical applications.
- Tall:Elongated aspect ratios optimize shelf presence for premium spirits and fragrance balms while maintaining stable center of gravity for automated filling lines.
- Wide:Low-profile broad shoulders maximize label real estate and access aperture for thick formulations in skincare masks and pharmaceutical ointments.
- Uniquely Shaped:Asymmetric or biomorphic contours require custom press-and-blow tooling and dedicated fire-polishing fixtures, with multilayer digital printing transforming the angled shoulder into serialized authentication and brand storytelling surfaces.
Standard contour dominates installed furnace capacity. Uniquely Shaped shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specialized finishing capacity along the Rhine-Main corridor, while France drives premium cosmetics demand through Paris-based fragrance houses. Italy and Spain anchor Mediterranean food preservation applications. The United States maintains pharmaceutical-grade export production for FDA-regulated markets.
Germany
Rhine-Main packaging clusters host concentrated silk-screening and fire-polishing capabilities serving fragrance houses with 48-hour turnaround on custom rim profiles. ECHA substance restrictions under REACH redirect pharmaceutical demand toward borosilicate formats with certified drug-contact surfaces. Hesse-based furnace operators maintain dual-batch configurations to manage cullet supply volatility from municipal collection fluctuations.
France
Paris-based luxury beauty conglomerates concentrate procurement around dedicated finishing line capacity with guaranteed volume allocations rather than spot purchasing. ANSM stability guidelines for primary packaging influence acceptance criteria for drug-contact glass surfaces. The Île-de-France region anchors artisanal formulation demand where small-capacity uniquely shaped contours signal premium positioning.
Italy
Vacuum-sealed food preserves and oxygen-sensitive sauces drive medium-capacity standard contour demand with precise edge geometry for gasket compression. EU Packaging and Packaging Waste Regulation mandates compress recycled glass availability while tightening circularity targets for 2030. Emilia-Romagna processors specify borosilicate thermal shock resistance for pasteurization line compatibility.
Spain
Mass-market condiment volumes face accelerating polypropylene substitution where oxygen barrier requirements permit polymer migration. ECHA evaluations of colorant and surface treatment restrictions prompt qualification of alternative decolorizing agents. Catalonia-based decorators compete on multilayer digital printing fused with traditional fire-polishing for brand authentication surfaces.
United States
Pharmaceutical-grade borosilicate production serves export-bound lines governed by FDA drug master file requirements with 18-24 month approval timelines. EPA and OSHA standards intersect with state-level extended producer responsibility fee structures. New Jersey and Pennsylvania corridor facilities specialize in oncology and biologic delivery system packaging with clean-room finishing capabilities.
Beveled Edge Jars Market Competitive Environment
Rhine-Main producers anchor the premium customization tier; North American specialists hold pharmaceutical-grade capacity. The supplier base organizes around furnace network scale, decorator specialization depth, and clean-room certification tiers. Three archetypes dominate: integrated glass manufacturers with European furnace networks, dedicated pharmaceutical finishers with ISO 14644-1 lines, and regional decorators competing on silk-screening velocity. Competitive moves concentrate on dedicated line allocations for beauty conglomerates and backward integration into cullet pre-treatment infrastructure.
Among integrated manufacturers, Ardagh Group and Verallia exemplify furnace-network scale archetypes with cross-border batch chemistry flexibility. Gerresheimer occupies a position within pharmaceutical-grade specialization, representing the clean-room finisher tier with borosilicate drug-contact surface certification. Saver Glass sits within the decorative depth segment, anchoring multilayer silk-screening capabilities that transform beveled shoulders into branding substrates.
| Leading Market Players |
|---|
| Berlin Packaging |
| Ardagh Group |
| Verallia |
| Owens-Illinois |
| Gerresheimer |
| PakTech |
| Vitro Packaging |
| Saver Glass |
| Stoelzle Glass |
| Others |
Value Chain & Pricing Dynamics
Buyer consolidation among Paris-based fragrance houses and LVMH-affiliated luxury conglomerates is compressing supplier rosters toward dedicated finishing line capacity, forcing Rhine-Main decorators to absorb capital commitments for captive production modules and pass through portions via extended contract durations with volume guarantees.
Pricing Analysis
Capacity additions in Germany's Rhine-Main corridor are reshaping price floors for premium cosmetic-grade beveled edge jars. Three-tier pricing structure across pharmaceutical-grade, cosmetic-premium, and mass-market standard levels separates certified drug-contact surfaces commanding clean-room premiums from commodity food-industry volumes. Cost compression in polypropylene substitution tiers is intensifying because ECHA additive evaluations redirect some pharmaceutical demand back toward borosilicate, tightening mid-market pricing elasticity. Mass-market condiment buyers exhibit highest price sensitivity; oncology packaging procurement teams show least.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation recycled content mandates are reshaping sourcing patterns toward cullet pre-treatment infrastructure investment. Manufacturing gravity centers on Germany, France, and Italy, with Hesse-based furnace operators maintaining dual-batch configurations. Raw material flows draw from post-consumer recycled glass cullet, natural gas melting inputs, and borosilicate sand deposits. Single-source vulnerability concentrates in skilled fire-polishing labor pools where German decorators compete for aging specialist workforces. Distribution runs through Rhine-Main silk-screening clusters serving fragrance houses with 48-hour turnaround logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The beveled edge jars market compounds steadily as premium cosmetics houses expand procurement of small-capacity uniquely shaped contours for artisanal formulation signaling, creating durable demand for specialized decorator capabilities.
For Market Incumbents: Anticipate polypropylene substitution acceleration in mass-market condiments by securing backward integration into cullet pre-treatment infrastructure that satisfies EU Green Deal circularity targets. Invest in robotic flame-treatment automation to reduce edge-geometry variance below 0.1mm, defending pharmaceutical-grade certification tiers against emerging clean-room finishers. Prioritize dedicated line allocations for beauty conglomerates over spot-market exposure. For New Entrants and Emerging Players: Mid-cap pharmaceutical contract manufacturers in oncology and biologic delivery systems represent an underserved buyer archetype seeking ISO 14644-1 Class 7 finishing capacity with shorter qualification timelines than incumbent pharmaceutical giants. Target Spain and Italy where EMA stability guideline compliance creates acceptance pathways without FDA drug master file delays. Pursue white-label clean-room finishing partnerships with established furnace networks rather than greenfield capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized decorators possessing multilayer digital printing fused with fire-polishing capabilities that transform beveled shoulders into brand authentication substrates. Long-term viability hinges on captive relationships with LVMH and Kering-affiliated houses extending contract durations. Monitor ECHA substance restriction announcements as inflection indicators for glass-versus-plastic demand recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cullet Pre-treatment | Secures recycled glass supply for EU Packaging and Packaging Waste Regulation compliance. |
| Robotic Fire-polishing Automation | Reduces edge-geometry variance below 0.1mm for vacuum-seal reliability in hygroscopic formulations. |
| Clean-room Finishing Line Certification | Unlocks 40-60% price premiums for pharmaceutical-grade borosilicate drug-contact surfaces. |
| Dedicated Line Allocation Contracts | Captures volume guarantees from LVMH and Kering-affiliated luxury beauty conglomerates. |
| Multilayer Digital Printing Capability | Transforms beveled shoulders into serialized authentication surfaces for anti-counterfeiting. |
Study Parameters
Direct dialogue with furnace network operators, silk-screening decorators, pharmaceutical packaging procurement managers, and luxury beauty house supply chain directors grounded the qualitative foundation. Secondary validation drew from ECHA substance restriction filings, EU Packaging and Packaging Waste Regulation impact assessments, FDA drug master file submission databases, and Rhine-Main industrial cluster trade association reports. Bottom-up capacity estimates from individual furnace operators triangulated against top-down demand segmentation from end-user channel analysis.
Segmented outputs across product type, capacity tier, end-user channel, and contour complexity fed into the analytical framework over the projection horizon. CAGRs emerged from regression analysis against glass container production indices, cosmetics packaging spend patterns, and pharmaceutical primary packaging approval timelines. Forecast inputs incorporated REACH compliance redirection effects and EU Green Deal recycled content threshold escalations without year-specific anchoring.
Underlying measurement precision varies by segment; pharmaceutical-grade and cosmetic-premium tiers carry tighter precision than mass-market standard volumes where polypropylene substitution volatility introduces wider confidence intervals. Forecasts reflect documented assumptions regarding ECHA evaluation timelines and municipal cullet collection rate stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Sweden Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Hermetic Jars Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Colombia Container Glass Market
Glass Packaging
Saudi Arabia Glass Packaging Market
Glass Packaging
Global Container Glass Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Glass Veil Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Brazil Container Glass Market