
 Cosmetic Bottles Packaging Market | 2026-2036
Cosmetic Bottles Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Bottles Packaging Market Analysis
Packaging engineering talent is reorganizing around polymer science and circular design capabilities as brands demand lighter-weight bottles with validated recycled content. Berry Global leverages its North American blow-molding scale to supply major skincare labels with rPET cosmetic bottles. HCP Packaging anchors Asian production networks for luxury fragrance houses seeking precision-molded glass and plastic hybrid formats. Albea SA differentiates through specialized pump and dispenser assemblies that integrate with its own bottle manufacturing lines.
Cosmetic bottles packaging encompasses rigid primary containers engineered from glass, polyethylene terephthalate, polypropylene, or aluminum, typically ranging from 15 mL to 500 mL in fill volume, designed to protect formulations from oxidation, UV degradation, and microbial ingress while enabling controlled dispensing. The primary commercial purpose is to extend product shelf life, ensure dosage precision, and transmit brand positioning through tactile and visual design cues. Pump bottles and dropper bottles command premium positioning in skincare as serum and treatment formats proliferate, while glass maintains dominance in fragrance due to chemical inertness and weight perception. Eco-friendly materials represent the fastest-growing structural segment as mono-material constructions and chemically recycled polymers attract investment from brands with net-zero commitments.
The European Chemicals Agency enforces REACH substance restrictions that limit certain plasticizers and colorants in cosmetic contact materials, directly influencing resin selection and supplier qualification timelines. The FDA regulates cosmetic packaging under the Federal Food, Drug, and Cosmetic Act, requiring material safety documentation for all substances with potential migration into formulations. BIS certification requirements in India mandate testing protocols for plastic containers used in personal care applications, creating compliance thresholds for imported packaging. Stakeholders must monitor evolving extended producer responsibility frameworks and chemical recycling certification standards to secure preferred supplier status with multinational beauty conglomerates.
Market Dynamics
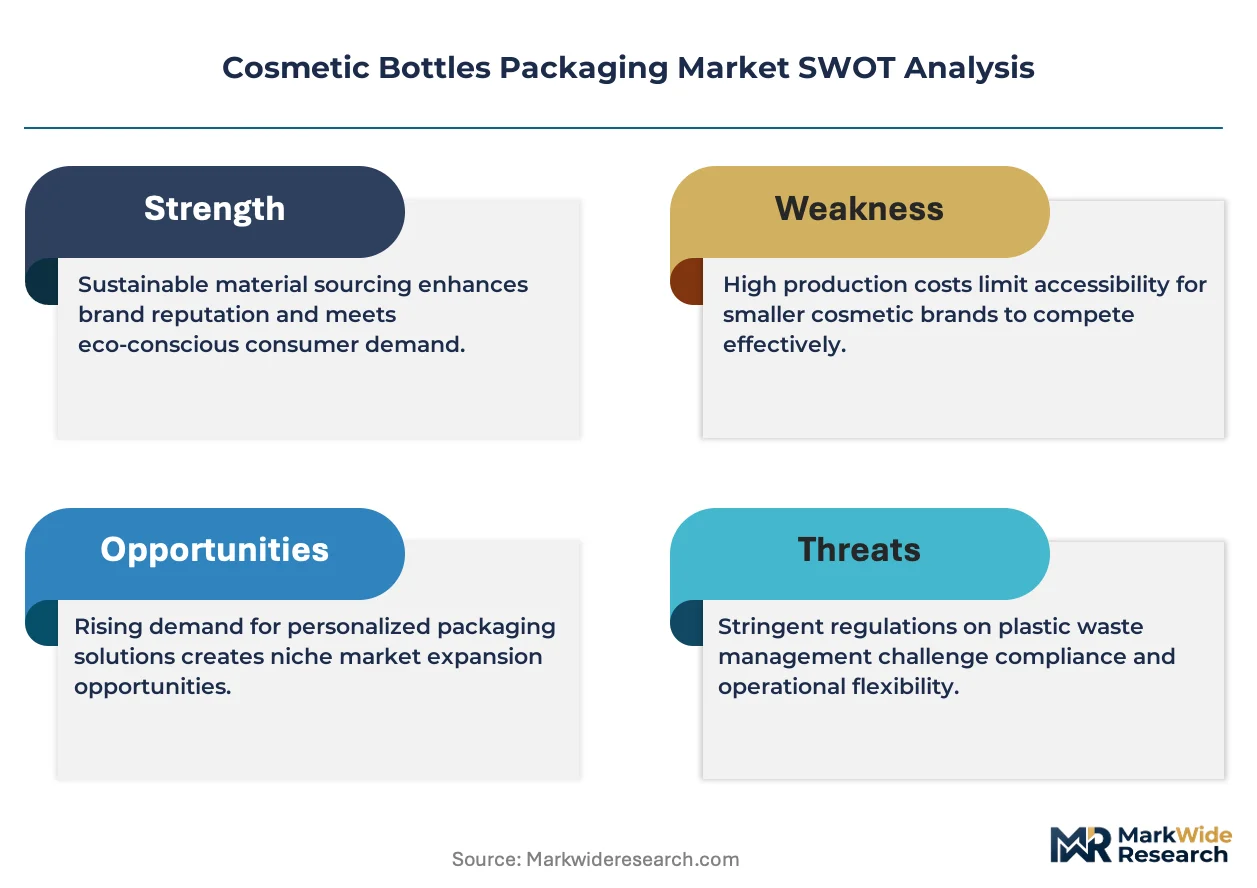
The EU Green Deal's packaging waste directive is compressing design cycles as brands demand mono-material formats with validated post-consumer recycled content. This regulatory pressure is restructuring supplier qualification timelines and resin selection protocols across the value chain.
Growth Catalysts
- REACH substance restrictions:ECHA limits on plasticizers and colorants in cosmetic contact materials are accelerating supplier consolidation toward certified polymer compounders with documented migration testing capabilities.
- Pump and dropper format proliferation:Skincare serum brands are specifying precision-dispensing assemblies that integrate dosage control with tactile brand differentiation.
- France, Germany, Italy:European beauty houses are extending sustainable packaging mandates across their supply chains, concentrating demand for rPET and chemically recycled polypropylene in these three markets.
Market Restraints
- rPET feedstock volatility:Post-consumer bottle flake availability fluctuates with regional collection rates, creating input cost instability for cosmetic-grade recycled resin.
- Asian blow-molding concentration:Precision cosmetic bottle production clusters in Guangdong and Zhejiang provinces, exposing brands to logistics disruption and tariff exposure.
- Multi-layer barrier incompatibility:Existing EVOH and nylon oxygen barriers complicate mono-material recyclability, forcing reformulation trade-offs between shelf life and circularity claims.
Strategic Opportunities
- India BIS certification pathway:Personal care packaging import regulations are creating first-mover advantage for suppliers establishing local testing partnerships and compliance documentation.
- Aluminum-bottle hybrid formats:Fragrance houses are exploring lightweight metal primary containers with polymer overmold collars that merge chemical inertness with injection-molded precision.
- EU extended producer responsibility frameworks:Pending modulated fee structures will reward higher recycled content and penalize complex multi-material assemblies, reshaping RFP specifications.
Industry Challenges
- Chemical recycling certification gaps:Mass-balance accounting standards for pyrolysis-derived polymers remain inconsistent across EU member states, delaying brand marketing claims.
- Polymer science talent scarcity:Formulation chemists with circular design expertise command premium compensation, constraining mid-tier packaging converters' technical service capabilities.
- Legacy blow-molding asset stranding:Converting lines optimized for virgin PET require capital-intensive retrofit for high-recycled-content resins with varying IV and contamination profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Bottles Packaging Market |
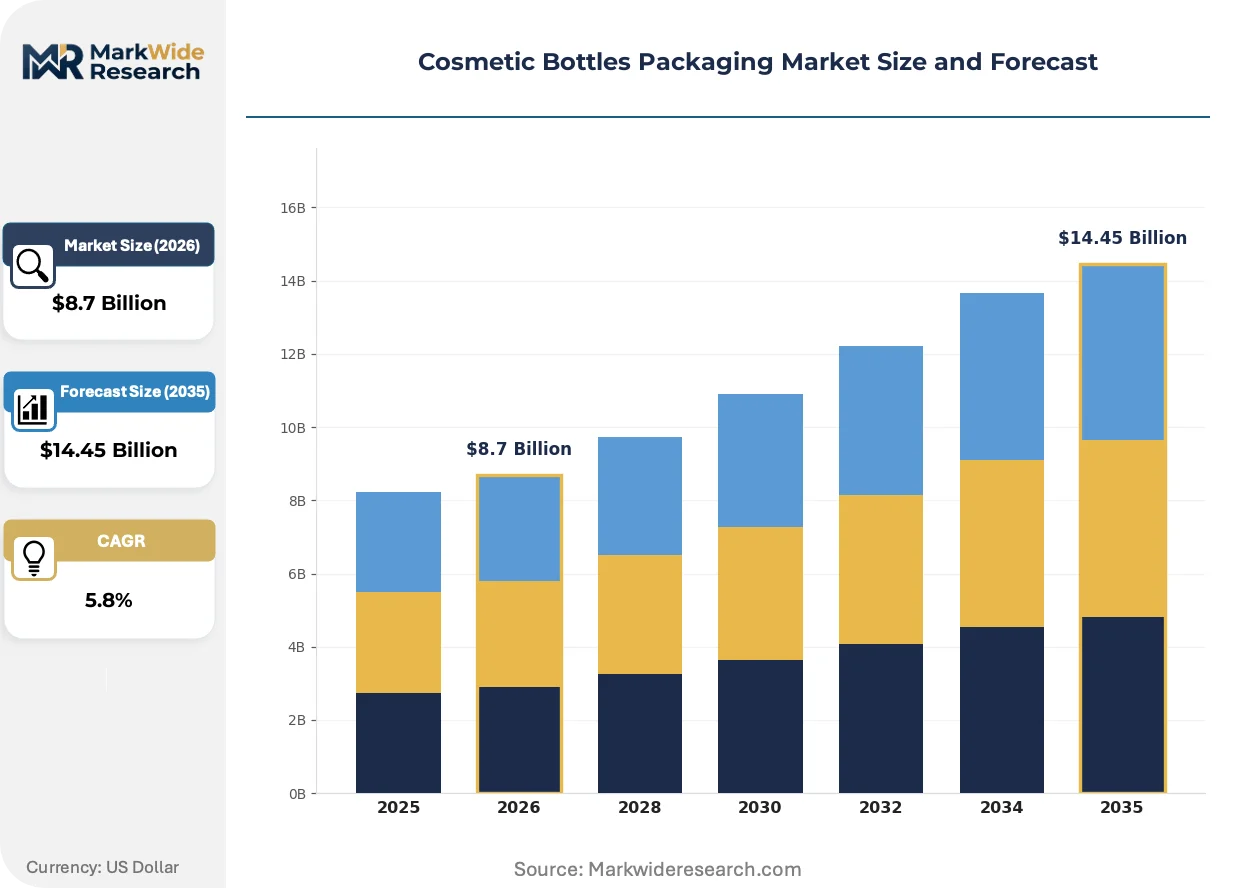
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dropper Bottles, Pump Bottles, Jars, Tubes Material: Glass, Plastic, Aluminum, Eco-friendly Materials Closure Type: Screw Cap, Flip Top, Spout, Spray Pump End User: Skincare, Makeup, Haircare, Fragrance |
| Companies Covered | Amcor plc, HCP Packaging, Berry Global, Albea SA, AptarGroup Inc., Silgan Holdings, DS Smith PLC, Quadpack Industries, Heinz-Glas GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Bottles Packaging Market Emerging Trajectories
Active materials science and regulatory chemistry are converging to redefine cosmetic bottle performance specifications. Brands now specify barrier properties, recyclability credentials, and dispensing ergonomics as interconnected design parameters rather than sequential trade-offs.
Mono-material pump mechanisms are miniaturizing. Advanced polypropylene spring and ball-valve assemblies now replicate metal-component performance in all-plastic constructions. Skincare brands in France and Germany are specifying these formats for serum lines requiring precise 0.15 mL dosing. This architecture is miniaturizing the traditional metal-spring pump into injection-molded components that sort cleanly in polyolefin recycling streams.
REACH authorization timelines are compressing substance approval windows. ECHA's evolving candidate list for SVHCs now captures several phthalate alternatives previously adopted as drop-in replacements. Cosmetic packaging compounders are accelerating substitution programs for plasticizers and UV stabilizers. Fragrance glass-coating suppliers face particular exposure as borosilicate surface treatments undergo renewed toxicological scrutiny.
Beauty conglomerates are consolidating supplier panels around circularity-verified partners. L'Oréal and Estée Lauder have reduced qualified blow-molding vendors by 40 percent since 2022, concentrating volume with converters demonstrating closed-loop material flows. This concentration is visible most acutely in Germany, where private-label skincare brands now piggyback on multinational auditing protocols rather than maintaining independent qualification systems.
Cosmetic Bottles Packaging Market Segmentation
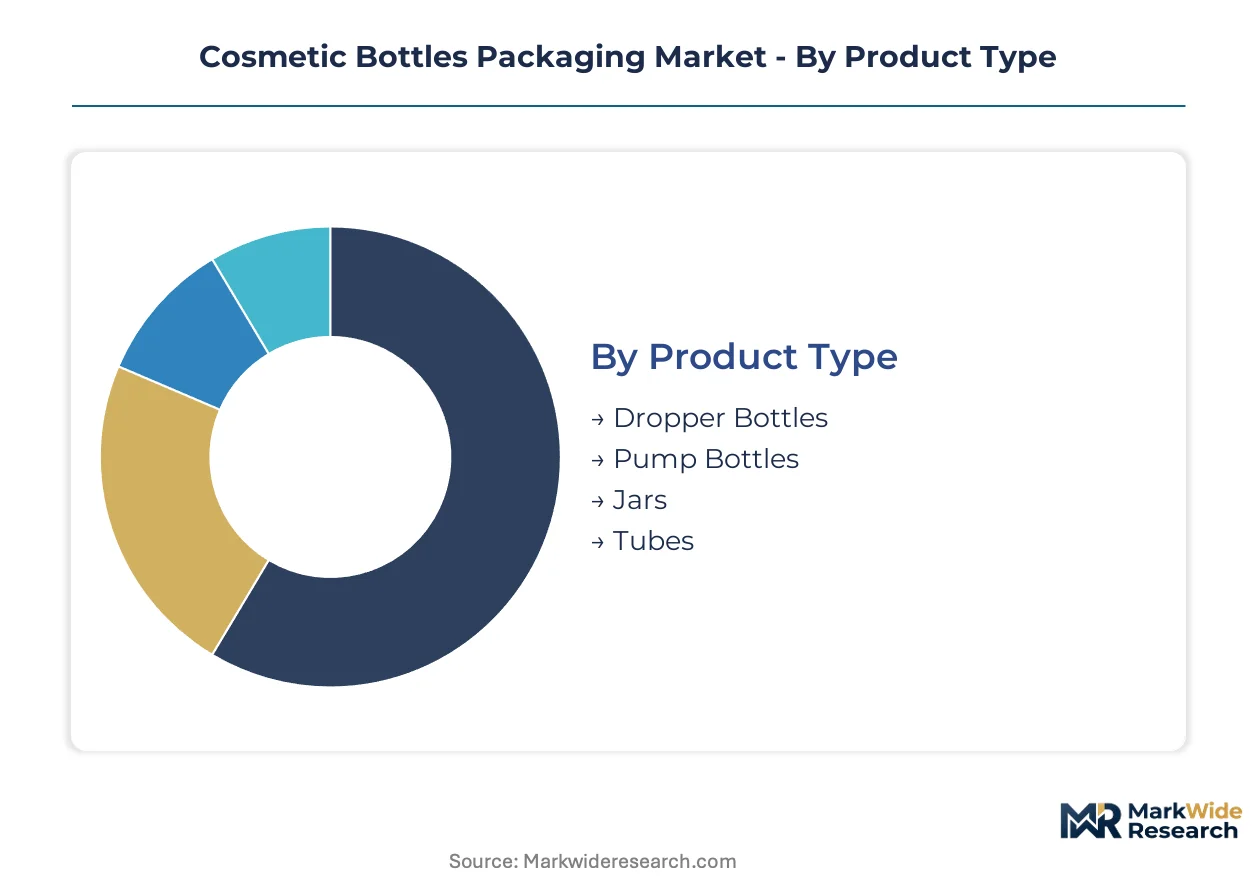
Packaging specifications diverge sharply across cosmetic categories, with serum brands demanding precision-dispensing formats while fragrance houses prioritize inert barrier properties. Understanding these segment boundaries clarifies where converter investments in blow-molding, injection molding, or glass forming assets generate differentiated returns.
Product Type:
Dropper and pump formats dominate export-led demand from European skincare brands, while jars and tubes serve more localized, price-sensitive personal care markets.
- Dropper Bottles:Borosilicate or amber glass bodies with calibrated rubber bulbs deliver 0.15-1.0 mL dosing precision for active serum formulations. Demand concentrates in France and Germany where prestige skincare brands specify child-resistant CRC closures meeting EU safety standards.
- Pump Bottles:Polypropylene or PET constructions integrate precision-metering actuators with 0.1-0.5 mL output consistency. Airless pump variants command premium positioning in Korean and Japanese skincare export markets seeking oxidation protection for vitamin C and retinol formulations.
- Jars:Wide-mouth PET or glass containers with threaded closures dominate domestic mass-market cream applications across India and Southeast Asia.
- Tubes:Laminated aluminum-plastic or all-plastic extrusions serve haircare and body care segments requiring high-viscosity product evacuation.
Dropper bottles command the established base in premium skincare. The steepest expansion runs through pump bottles as airless dispensing technology penetrates mid-tier serum categories.
Material:
Material selection stratifies across cost tiers, with virgin glass and aluminum anchoring luxury positioning while recycled PET and bio-based polymers reshape mid-market specifications.
- Glass:Soda-lime and borosilicate formulations provide complete oxygen and UV barrier with chemical inertness for fragrance and essential oil applications. European fragrance houses in Italy and France mandate minimum 30 percent post-consumer recycled content in glass feedstock under internal sustainability protocols.
- Plastic:PET, HDPE, and PP resins enable lightweight, shatter-resistant formats across skincare and haircare. REACH-compliant plasticizers and UV stabilizers are becoming non-negotiable in EU-qualified supply chains.
- Aluminum:Lightweight metal primary containers with polymer overmold collars merge chemical inertness with injection-molded precision for fragrance and deodorant segments.
- Eco-friendly Materials:Chemically recycled polypropylene and mass-balance certified bio-based PE attract investment from brands with net-zero commitments, though certification gaps delay marketing claims.
Glass retains the volume anchor in fragrance and prestige skincare. Eco-friendly materials are climbing the fastest as mono-material mandates and extended producer responsibility frameworks reshape procurement specifications.
Closure Type:
Closure engineering now determines recyclability outcomes as brands eliminate multi-material assemblies to satisfy EU Green Deal sorting requirements.
- Screw Cap:Continuous thread HDPE or PP closures remain standard for jars and wide-mouth bottles across mass-market applications.
- Flip Top:Living-hinge polypropylene designs dominate haircare and body wash segments requiring single-handed dispensing.
- Spout:Precision-molded LDPE or silicone valves enable controlled flow for hair oil and treatment formulations.
- Spray Pump:Crimp-on or screw-on actuator assemblies with dip tubes serve fragrance and facial mist applications, with mono-material all-PP variants gaining traction for recyclability.
Screw caps command the installed base across commodity formats. Spray pumps are expanding most quickly as fine-mist skincare and fragrance applications proliferate.
End User:
End-use concentration determines regional production clustering, with skincare and fragrance driving European and Asian premium demand while haircare and makeup serve broader geographic distribution.
- Skincare:Serum, treatment, and moisturizer brands specify precision-dispensing formats with validated barrier properties. Korean and Japanese beauty houses are extending airless pump requirements across their global supplier networks.
- Makeup:Foundation, primer, and liquid color cosmetic brands demand contamination-resistant packaging with ergonomic applicator integration.
- Haircare:Shampoo, conditioner, and treatment brands favor large-format pump bottles with high-output actuators.
- Fragrance:Parfum and eau de toilette houses prioritize glass bottle weight perception, magnetic closure differentiation, and refillable format development.
Skincare holds the revenue anchor across premium packaging segments. Fragrance is gaining share fastest as refillable and rechargeable formats attract sustainability-focused investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes cosmetic bottles through prestige fragrance and skincare channels that prioritize glass weight perception and mono-material mandates, diverging from Asia's pump-bottle concentration in mass-market serum exports.
France
L'Oréal and Estée Lauder procurement teams specify validated post-consumer recycled glass and rPET formats for Paris-headquartered skincare lines. ANSM enforces cosmetic contact material safety protocols that exceed baseline EU REACH requirements. The Île-de-France region hosts specialized glass-coating suppliers facing renewed toxicological scrutiny on borosilicate surface treatments.
Germany
Private-label skincare brands piggyback multinational auditing protocols rather than maintaining independent qualification systems, concentrating demand with circularity-verified converters. The EU Green Deal's packaging waste directive compresses design cycles for mono-material formats across German supply chains. North Rhine-Westphalia anchors blow-molding capacity serving both domestic beauty houses and export markets.
Italy
Fragrance houses in Milan and Florence mandate minimum recycled content thresholds in glass feedstock under internal sustainability protocols distinct from regulatory minimums. ECHA substance restrictions on plasticizers accelerate substitution programs for UV stabilizers in cosmetic contact materials. The Lombardy-Veneto corridor concentrates precision-molded glass and plastic hybrid production for luxury fragrance export markets.
United States
FDA material safety documentation requirements under the Federal Food, Drug, and Cosmetic Act create compliance thresholds for imported packaging serving American beauty conglomerates. Skincare brands specify airless pump variants for vitamin C and retinol formulations requiring oxidation protection. New Jersey and California host formulation labs driving specification trends that propagate through North American supplier networks.
India
BIS certification mandates testing protocols for plastic containers in personal care applications, creating first-mover advantage for suppliers establishing local compliance documentation. Mass-market cream applications in jars and wide-mouth bottles dominate domestic consumption patterns. Maharashtra and Gujarat host emerging blow-molding clusters serving both local brands and contract manufacturing for multinational beauty houses.
Cosmetic Bottles Packaging Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in cosmetic bottles packaging, with converters maintaining captive pump and dispenser assembly capabilities commanding procurement preference from beauty conglomerates. The middle tier fragments across regional blow-molding specialists lacking validated recycled content certification. Strategic archetypes include integrated format suppliers, pure-play glass formers, and precision closure engineers. Consolidation pressure runs through capacity expansion in chemically recycled polymer processing and backward integration into resin compounding.
Among North American integrated packaging groups, Berry Global exemplifies scale-driven converters leveraging blow-molding networks to supply rPET cosmetic bottles for major skincare labels. HCP Packaging occupies a position within Asian production networks serving luxury fragrance houses seeking precision-molded hybrid formats. Albea SA represents the specialized pump tier, with dispenser assembly integration distinguishing its offering from commodity bottle suppliers.
| Leading Market Players |
|---|
| Amcor plc |
| HCP Packaging |
| Berry Global |
| Albea SA |
| AptarGroup Inc. |
| Silgan Holdings |
| DS Smith PLC |
| Quadpack Industries |
| Heinz-Glas GmbH |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging waste directives gate both supplier qualification timelines and price differentiation simultaneously, compressing design cycles as brands demand mono-material formats with validated post-consumer recycled content. This regulatory architecture concentrates procurement preference with converters demonstrating closed-loop material flows, widening spreads between certified circularity partners and commodity blow-molding suppliers.
Pricing Analysis
Long-term offtake agreements anchor pricing for major skincare brands securing rPET volumes from qualified converters, while spot-market resin purchases expose mid-tier suppliers to post-consumer bottle flake cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates airless pump assemblies with validated migration testing from commodity screw-cap bottles and unverified recycled-content alternatives. Cost compression in standard-tier formats is intensifying because Asian blow-molding capacity expansion outpaces European demand growth. Mass-market personal care brands exhibit highest price sensitivity, while prestige fragrance houses prioritize chemical inertness and tactile weight perception over unit economics.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes and fluctuating vessel availability from Guangdong and Zhejiang provinces elevate inbound logistics costs for precision cosmetic bottle production. Manufacturing gravity centers on China, Germany, and Italy, with raw material supply drawing from Saudi Arabian virgin PET feedstock, Belgian chemically recycled polypropylene, and Italian borosilicate glass sand. Single-source vulnerability concentrates in Asian pump mechanism componentry, where precision-molded spring and ball-valve assemblies rely on concentrated injection-molding clusters. Distribution runs through beauty conglomerate direct procurement teams and specialized packaging distributors serving mid-tier contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where REACH compliance documentation and ECHA substance testing create switching costs that lock in qualified supplier relationships across multi-year beauty brand product cycles.
For Market Incumbents: Compound qualification advantages by deepening backward integration into resin compounding and captive pump assembly manufacturing, neutralizing emerging entrant threats from Asian converters with unverified recycled-content claims. Expand blow-molding capacity in North Rhine-Westphalia to capture German private-label skincare demand piggybacking multinational auditing protocols. Prioritize chemical recycling certification investment to secure preferred supplier status as EU extended producer responsibility frameworks modulate fees by recyclability credentials. For New Entrants and Emerging Players: BIS certification fast-track partnerships with Maharashtra testing laboratories create first-mover positioning in India's personal care packaging import regulations, the most penetrable geography given fragmented local compliance infrastructure. Target domestic mass-market cream jar applications where multinational auditing protocols have not yet concentrated procurement. Pursue joint-venture structures with established European glass coaters to bypass toxicological scrutiny barriers on borosilicate surface treatments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier blow-molding specialists lacking validated recycled-content certification but holding irreplaceable customer relationships with fragrance houses. Five-to-ten-year viability hinges on capital deployment timing for chemical recycling retrofit versus stranded legacy virgin-PET asset risk. Watch for ECHA SVHC candidate list expansion on phthalate alternatives as inflection indicator accelerating substitution program investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Format Development | Albea SA and AptarGroup integrate all-polypropylene pump mechanisms satisfying EU Green Deal sorting requirements. |
| Chemical Recycling Certification Investment | Mass-balance accounting standardization across EU member states enables validated marketing claims for pyrolysis-derived polymers. |
| Regional Blow-Molding Capacity Expansion | Berry Global leverages North American scale to supply rPET formats reducing trans-Pacific logistics exposure for skincare labels. |
| Backward Integration into Resin Compounding | Converters securing captive supply of REACH-compliant plasticizers and UV stabilizers compress supplier qualification timelines. |
| India BIS Compliance Documentation | Local testing partnerships in Maharashtra and Gujarat create procurement preference for personal care packaging imports. |
Methodological Framework
Operator-level perspectives from packaging engineering directors, beauty brand procurement leads, polymer compounder technical service managers, and ECHA regulatory affairs specialists anchored the qualitative base. Primary interview findings triangulated against customs trade data for PET and polypropylene resin flows, SEC 10-K filings from integrated packaging groups, EU packaging waste directive implementation reports, and BIS certification registry databases. Bottom-up volume estimates by product format and material category reconciled with top-down beauty industry production data across the analysis window.
Sensitivity analysis tested forecast robustness against rPET feedstock price volatility scenarios and REACH substance restriction expansion timelines. Segmentation dimensions modeled include product type, material composition, closure mechanism, and end-use application across regional regulatory clusters. CAGRs derived from historical shipment data and projected brand sustainability mandate adoption curves, incorporating airless pump technology penetration rates and chemically recycled polymer capacity buildout schedules as industry-specific inputs.
Underlying assumptions cover sustained EU Green Deal implementation, stable Asian manufacturing export volumes, and gradual chemical recycling certification standardization, with deviation risk concentrated in trade policy shifts affecting Guangdong-Zhejiang production clusters and ECHA SVHC list acceleration beyond modeled substitution program timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Anti-Counterfeit Pharmaceuticals and Cosmetics Packaging Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Middle East and Africa Personal Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market