
 Thread Seal Tape Market | 2026-2036
Thread Seal Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Thread Seal Tape Market Analytics
Industrial end users is collapsing as the dominant buyer archetype, while contractor and DIY channels capture incremental share through e-commerce platforms and specialty retail expansion. Saint-Gobain leverages its fluoropolymer expertise to sustain premium positioning across European and North American supply chains. Oatey Company anchors its competitive stance through deep channel control in plumbing distribution, while 3M Company differentiates via technology leadership in high-performance tape formulations for critical sealing applications.
Thread seal tape comprises extruded or skived PTFE film, typically 0.075 to 0.25 mm thick, engineered to deform under torque and fill thread voids for fluid and gas containment in metallic and plastic piping systems. PTFE formulations dominate value capture due to chemical inertness and temperature tolerance spanning cryogenic to 260°C service, while multi-layer constructions represent the fastest-growing formulation category as end users specify enhanced creep resistance and reduced cold-flow failure. Application demand fragments across plumbing, automotive, and HVAC sectors, with industrial maintenance representing the deepest margin pool due to specification-driven procurement and penalty costs of unplanned downtime.
EPA regulations on volatile organic compound emissions and OSHA workplace exposure limits shape product formulation requirements and manufacturing facility compliance burdens across the United States. ISO 9001 quality management and ASTM D3308 specifications govern dimensional consistency and performance benchmarking for supplier qualification in export markets. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in multiple jurisdictions, as regulatory reclassification of fluoropolymer feedstocks threatens raw material availability and forces reformulation investment timelines.
Market Dynamics
Multi-layer PTFE formulation development is compressing replacement cycles as industrial maintenance crews specify enhanced creep resistance for critical sealing applications under tightening plant uptime requirements.
Growth Catalysts
- Infrastructure Retrofit Cycles:Aging water distribution networks in the United States require systematic thread seal replacement, sustaining volume pull through plumbing and HVAC distribution channels.
- EPA Leak Prevention Standards:Elevated chemical compatibility thresholds for contractor-grade products are forcing specification upgrades across petrochemical and natural gas handling facilities.
- PTFE Chemical Inertness:Temperature tolerance spanning cryogenic to 260°C service enables penetration into semiconductor fabrication and aerospace fuel systems previously served by metal gaskets.
Market Restraints
- Fluoropolymer Feedstock Concentration:Virgin PTFE resin supply concentrates among specialty chemical producers in China and Germany, exposing converters to raw material availability shocks.
- PFAS Regulatory Reclassification:ECHA and multiple US state environmental agencies are reviewing per- and polyfluoroalkyl substance restrictions that threaten to delist PTFE from approved materials lists.
- Anaerobic Sealant Substitution:Liquid thread-locking compounds capture share in high-vibration automotive and heavy equipment applications where tape cold-flow remains a failure mode.
Strategic Opportunities
- Hydrogen Economy Infrastructure:Pipeline construction for hydrogen transport and storage creates demand for high-purity PTFE formulations compatible with embrittlement-sensitive metallic systems.
- E-Commerce Specialty Retail:Contractor and DIY channels bypass traditional plumbing distribution through direct-to-trade platforms, opening margin capture for branded product lines.
- EU F-Gas Regulation Phase-Down:Refrigerant containment mandates in commercial HVAC accelerate specification of low-permeability multi-layer tapes for flare and compression fittings.
Industry Challenges
- Reformulation Investment Timelines:PFAS restriction uncertainty forces parallel development tracks for fluoropolymer alternatives, straining R&D budgets without guaranteed regulatory clarity.
- Dimensional Consistency Certification:ASTM D3308 compliance for export qualification requires capital-intensive metrology infrastructure that smaller converters struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thread Seal Tape Market |
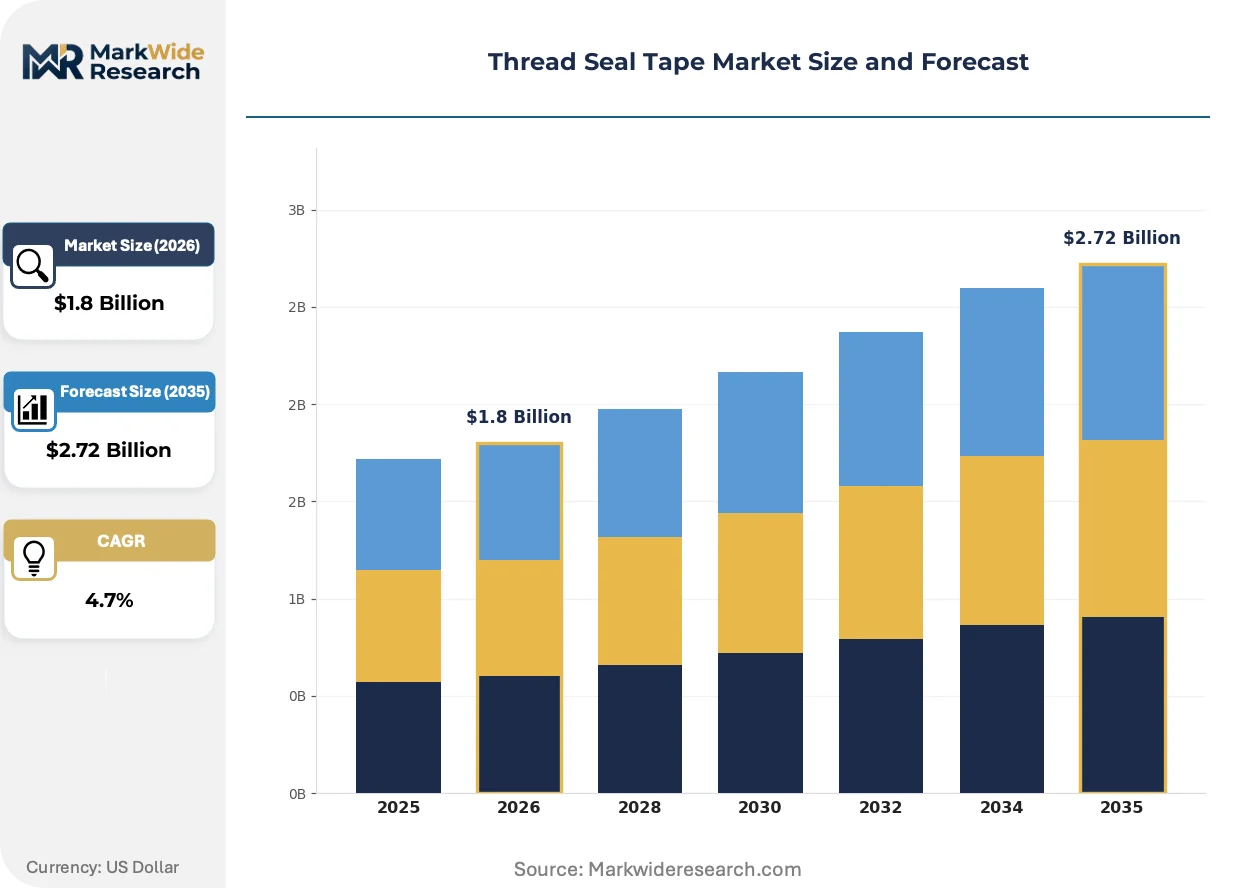
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, Fiberglass, PVC, Polyethylene Application: Plumbing, Automotive, Industrial, HVAC End User: Contractors, DIY Enthusiasts, Manufacturers, Distributors Formulation: Single Layer, Multi-layer, Biodegradable, Heat Resistant |
| Companies Covered | 3M Company, Saint-Gobain, Henkel AG & Co. KGaA, Oatey Company, A. W. Chesterton Company, Dixon Valve & Coupling Company, DeWAL Industries, Electro Tape Specialties, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thread Seal Tape Market Evolving Landscape
Formulation chemistry and distribution architecture are undergoing simultaneous transformation as regulatory pressure on fluoropolymers intersects with channel digitization and end-user specification intensification.
Multi-layer PTFE tape construction is miniaturizing thread engagement requirements while maintaining seal integrity under dynamic pressure cycling. Automotive transmission manufacturers specify these reduced-thickness formulations to accommodate compact fluid routing in electrified powertrains. The technology is miniaturizing fitting envelope constraints that previously dictated metal-to-metal sealing solutions in space-restricted engine bays.
REACH authorization procedures for perfluorinated substances are forcing European converters to document safe-use scenarios and exposure controls across the supply chain. Downstream industrial buyers now require extended safety data sheets and substitution roadmaps as qualification prerequisites. German chemical processing facilities face the most immediate compliance burden, accelerating supplier audits and dual-source requirements.
Maintenance procurement teams consolidate vendor relationships around integrated MRO suppliers capable of delivering thread seal tape alongside adjacent fluid system components. This pattern compresses spot-buying through independent distributors and elevates contract-based volume commitments with penalty clauses for stockouts. The shift is most pronounced in United States Gulf Coast petrochemical complexes where unplanned downtime costs exceed material procurement expenditures by orders of magnitude.
Thread Seal Tape Market Segmentation
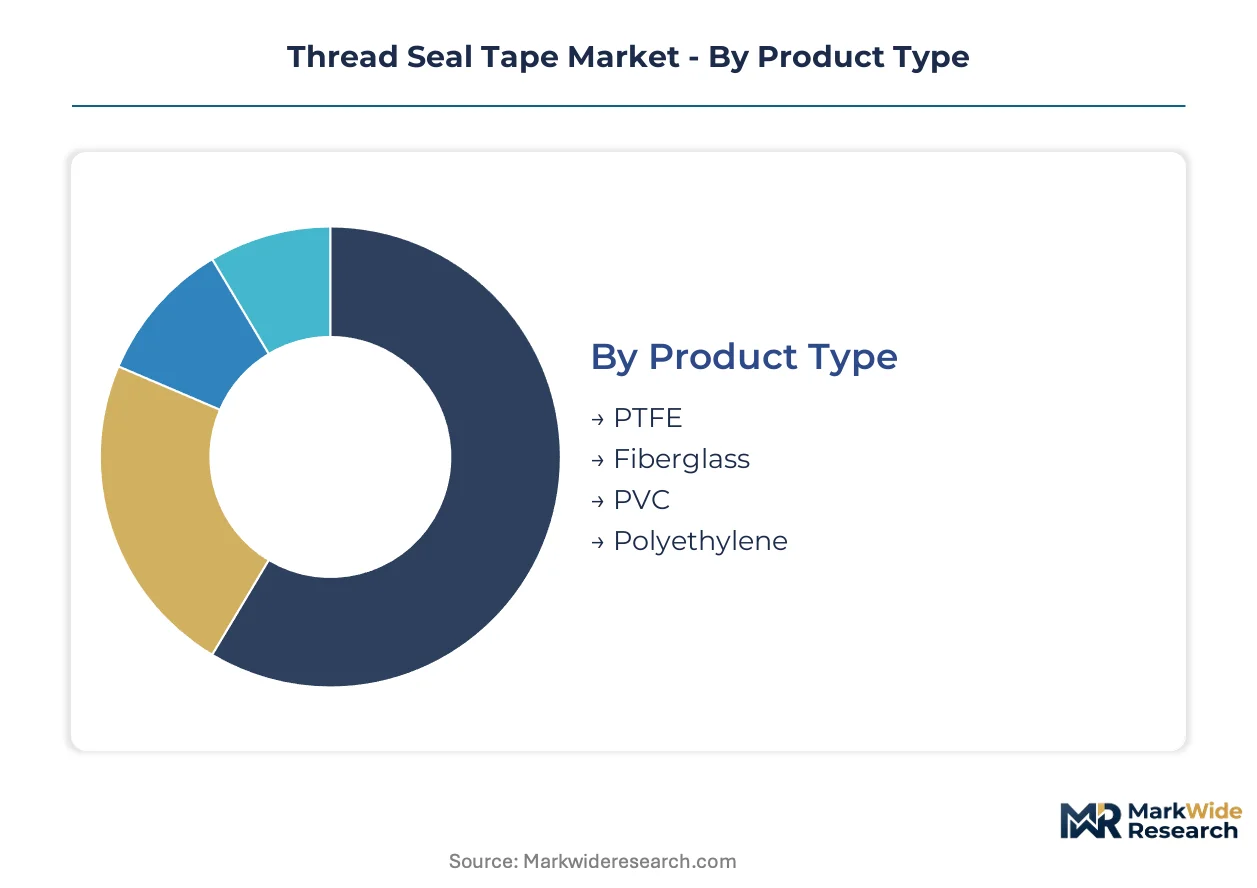
Thread seal tape procurement patterns diverge sharply across formulation chemistry, application environment, and buyer sophistication. Specification intensity varies from commodity plumbing installations to aerospace fuel systems, creating tiered margin structures that reward technical differentiation.
Product Type:
PTFE formulations dominate export qualification to Germany and Japan, while PVC and polyethylene variants serve price-sensitive domestic construction markets.
- PTFE:Extruded polytetrafluoroethylene film delivers chemical inertness across cryogenic to 260°C service envelopes. Semiconductor fabrication facilities in South Korea and aerospace fuel system manufacturers in France specify virgin resin grades with documented batch purity.
- Fiberglass:Reinforced PTFE composites incorporate woven glass fiber matrices to arrest creep deformation under sustained compressive loading. Petrochemical maintenance crews on the United States Gulf Coast specify these formulations for critical flange connections where unplanned downtime costs dwarf material expenditure.
- PVC:Cost-optimized vinyl formulations serve residential plumbing retrofits where temperature exposure remains below 60°C.
- Polyethylene:Low-density extrusions target irrigation and drainage applications with minimal chemical exposure requirements.
PTFE holds the largest share; momentum sits with fiberglass-reinforced variants as industrial uptime requirements tighten.
Application:
Cost tier separation distinguishes specification-grade industrial procurement from contractor spot-buying in residential construction.
- Plumbing:Municipal water distribution retrofits and new residential construction sustain volume throughput across distribution networks. EPA lead service line replacement mandates in Michigan and Illinois accelerate specification of NSF-certified PTFE formulations for potable water contact.
- Automotive:Electrified powertrain thermal management systems demand reduced-thickness multi-layer tapes for compact fluid routing. Transmission manufacturers in Stuttgart and Detroit specify these miniaturized formulations to replace metal gaskets in space-restricted engine bays.
- Industrial:Chemical processing and petrochemical maintenance represent the deepest margin pool due to penalty costs of seal failure.
- HVAC:Commercial refrigeration flare fittings require low-permeability constructions under EU F-Gas containment mandates.
Plumbing holds the largest share; HVAC is climbing the fastest as refrigerant phase-down regulations tighten.
End User:
Procurement consolidation around integrated MRO suppliers is reshaping traditional distributor relationships.
- Contractors:Licensed plumbing and mechanical trades specify contractor-grade products with documented ASTM D3308 compliance. E-commerce platforms now capture incremental share as trade buyers bypass traditional distribution for direct-to-job-site fulfillment.
- DIY Enthusiasts:Home improvement retail and specialty hardware channels serve residential repair demand with pre-cut rolls and color-coded thickness variants.
- Manufacturers:OEM fluid system assemblers qualify tape suppliers through PPAP submission and statistical process control audits.
- Distributors:Independent plumbing and industrial supply houses face margin compression as maintenance procurement teams consolidate vendor relationships.
Contractors hold the largest share; manufacturers are gaining share fastest as OEM specification intensity increases.
Formulation:
Supply concentration among specialty chemical converters in China and Germany shapes availability for advanced multi-layer constructions.
- Multi-layer:Laminated PTFE constructions with interleaved reinforcement layers deliver enhanced creep resistance under dynamic pressure cycling. These formulations command premium positioning as end users specify reduced replacement intervals for critical sealing applications.
- Heat Resistant:Filled PTFE compounds with ceramic or mineral additives extend service temperature envelopes beyond standard virgin resin limits. Aerospace and semiconductor equipment manufacturers in Japan and the Netherlands specify these grades for thermal management system integration.
- Single Layer:Standard skived or extruded PTFE film serves general-purpose plumbing and HVAC applications with moderate performance requirements.
- Biodegradable:Experimental starch-based and cellulose-reinforced formulations address emerging PFAS restriction pressures in European regulatory frameworks.
Single layer holds the largest share; multi-layer formulations show the steepest expansion trajectory as specification thresholds elevate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor in Texas anchors North American demand, while the Rhine-Ruhr industrial basin in Germany and the Yangtze River Delta in China concentrate converter capacity. These infrastructure nodes shape procurement patterns across three continents.
United States
Municipal water infrastructure retrofits and EPA lead service line replacement mandates drive specification-grade procurement. OSHA workplace exposure limits on fluoropolymer handling elevate compliance burdens for converters. Houston-Galveston petrochemical complexes sustain the deepest industrial maintenance demand, with unplanned downtime costs forcing premium multi-layer tape adoption.
Germany
REACH authorization procedures for perfluorinated substances force converters to document safe-use scenarios across supply chains. ECHA regulatory pressure accelerates substitution roadmap requirements from downstream buyers. The Rhine-Ruhr industrial cluster hosts specialty chemical converters supplying virgin PTFE resin to European tape manufacturers facing dual-source mandates.
China
Virgin PTFE resin production concentrates among specialty chemical producers serving domestic converter demand. MEE environmental compliance standards on fluoropolymer manufacturing reshape facility investment patterns. The Yangtze River Delta industrial corridor anchors skived and extruded film production for export qualification to Japan and South Korea.
Japan
Semiconductor fabrication facilities specify virgin resin grades with documented batch purity for thermal management systems. METI industrial standards govern dimensional consistency for automotive OEM qualification. The Osaka-Kobe manufacturing belt concentrates high-performance tape formulation for aerospace fuel system applications.
South Korea
Electronics manufacturing clusters drive demand for reduced-thickness multi-layer formulations in compact fluid routing. KOSHA workplace safety regulations align with international fluoropolymer handling protocols. The Gyeonggi-Incheon industrial zone anchors procurement consolidation around integrated MRO suppliers serving memory chip fabrication facilities.
Thread Seal Tape Market Competitive Landscape
Concentration sits with diversified materials conglomerates and specialty fluoropolymer converters. The vendor base spans three tiers: integrated chemical majors controlling resin supply, regional converters with deep distribution relationships, and niche specialists serving specification-intensive applications. Strategic moves center on backward integration into virgin PTFE resin production and geographic expansion through distributor acquisition in high-growth construction markets.
Within the diversified materials tier, 3M Company and Saint-Gobain exemplify technology-led positioning through fluoropolymer expertise and multi-layer formulation capabilities. Oatey Company anchors the distribution-integrated segment with channel control across North American plumbing networks. These three players represent distinct competitive archetypes: technology differentiation, materials science depth, and supply chain capture.
| Leading Market Players |
|---|
| 3M Company |
| Saint-Gobain |
| Henkel AG & Co. KGaA |
| Oatey Company |
| A. W. Chesterton Company |
| Dixon Valve & Coupling Company |
| DeWAL Industries |
| Electro Tape Specialties |
| Berry Global |
| Others |
Value Network & Pricing Analysis
Anaerobic sealant substitution in high-vibration automotive applications simultaneously redraws supply geography toward liquid adhesive producers in Germany and compresses pricing power for tape converters serving Detroit and Stuttgart OEM clusters. This displacement dynamic forces PTFE tape manufacturers to defend position through specification-grade certification investments while absorbing feedstock volatility from concentrated virgin resin suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified multi-layer formulations from contractor-grade single-layer products and private-label commodity rolls. Price differentiation rests on ASTM D3308 certification status and documented batch purity for semiconductor and aerospace buyers. Cost compression in the economy tier intensifies because Chinese converters flood export markets with unskived film. DIY enthusiasts exhibit highest price sensitivity; petrochemical maintenance crews demonstrate lowest sensitivity due to penalty costs of seal failure.
Supply Chain Analysis
Virgin PTFE resin concentration in China's Yangtze River Delta and Germany's Rhine-Ruhr basin creates chokepoint exposure for converters dependent on specialty chemical producers. Raw material sourcing draws from fluorspar mining operations, hydrofluoric acid processors, and polymerization facilities. Single-source vulnerability runs through German resin suppliers subject to REACH authorization delays. Distribution runs through integrated MRO suppliers consolidating spot-buying relationships with independent plumbing distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against liquid thread-locking compounds capturing share in electrified powertrain and heavy equipment applications. Incumbents must navigate specification erosion as automotive OEMs relax tape requirements for anaerobic alternatives.
For Market Incumbents: Secure captive supply of virgin PTFE resin through backward integration into Chinese or German polymerization capacity. Deepen ASTM D3308 certification moats to disqualify commodity converters from aerospace and semiconductor qualification pipelines. Counter anaerobic substitution by embedding tape specifications into OEM fluid system designs through collaborative engineering programs with Stuttgart and Detroit transmission manufacturers.
For New Entrants and Emerging Players: Anchor in biodegradable formulation development for European buyers confronting ECHA PFAS restriction timelines. Target German chemical processing facilities demanding substitution roadmaps as REACH authorization prerequisites. Pursue direct-to-trade e-commerce platforms bypassing Oatey Company's entrenched plumbing distribution control.
For Investors and Strategic Acquirers: The market sits at a regulatory transition phase that favors converters with dual-source resin relationships and documented safe-use scenario databases. Long-term viability hinges on PFAS regulatory clarity across multiple jurisdictions. Acquisition targets should demonstrate metrology infrastructure for dimensional consistency certification. Watch ECHA authorization decisions as the inflection signal for material substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive PTFE supply insulates converters from German and Chinese feedstock allocation shocks. |
| Multi-layer Formulation R&D Expansion | Enhanced creep resistance specifications penetrate semiconductor fabrication facilities in South Korea. |
| E-commerce Platform Development | Direct-to-trade channels bypass traditional plumbing distribution capturing contractor procurement consolidation. |
| Biodegradable Formulation Pipeline | Starch-based alternatives address ECHA substitution roadmap requirements from European industrial buyers. |
| Metrology Infrastructure Investment | ASTM D3308 compliance capability qualifies converters for export markets in Japan and Germany. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across plant maintenance directors, OEM procurement teams at automotive transmission manufacturers, plumbing distribution channel managers, and specialty chemical converters. Secondary validation drew from EPA enforcement databases, ECHA authorization registers, customs trade flows for PTFE resin, and SEC filings from diversified materials conglomerates. Bottom-up volume estimates from end-use application sizing were triangulated against top-down resin consumption data.
Across the analysis window, the analytical framework modeled formulation chemistry tiers, application environments from plumbing to aerospace, end-user procurement sophistication levels, and regional regulatory cluster variations. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated hydrogen economy infrastructure buildout assumptions and EU F-Gas regulation phase-down timelines for commercial HVAC demand.
Material uncertainties — ECHA PFAS reclassification decisions, virgin resin supply allocation disruptions, and anaerobic sealant penetration rates in automotive applications — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory clarity and substitution technology performance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Sterilization Tape Market
Tapes
Carton Sealing Tape Market
Tapes
Pressure Sensitive Adhesive Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Duct Tapes Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Seam Tapes Market
Tapes
Security Tape Market
Tapes
Tape Unwinder Market
Tapes
Paper Tapes Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Removal Strips Market
Tapes
Tape Applicator Machines Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Pouch Tapes Market
Tapes
Carbon Tapes Market