
 Australia Container Glass Market | 2026-2036
Australia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Container Glass Market Insights
Direct-to-brewery supply contracts is reshaping how container glass reaches Australian beverage producers. Orora Limited leverages its Gawler furnace complex to sustain vertical integration across melting and decoration stages. Visy Industries Australia anchors national supply through its Melbourne-based recycling and re-melt network. O-I Glass competes by specializing in lightweighting technology for premium export wine bottles.
Container glass comprises silica sand, soda ash, limestone, and cullet melted at temperatures exceeding 1500°C to form chemically inert, impermeable vessels for liquid and semi-solid storage. The material's oxygen barrier properties and inert surface chemistry make it indispensable for flavor-sensitive beverages and oxidation-prone pharmaceuticals. Beverage bottles dominate volume throughput, though pharmaceutical containers command superior margin pools due to TGA compliance requirements and batch traceability protocols. Food jars represent a mature segment with stable replacement cycles tied to seasonal agricultural processing. Capacity segmentation shows large-scale melting furnaces consolidating output while small-scale decorative operations proliferate near craft producer clusters.
Environment Protection Authority Victoria enforces emissions thresholds on glass furnace operations, while the Australian Packaging Covenant Organisation sets voluntary recovery targets that major suppliers now treat as binding benchmarks. TGA's Good Manufacturing Practice guidelines for pharmaceutical glass impose batch testing protocols that limit import substitution. The Therapeutic Goods Administration also mandates Type I borosilicate standards for parenteral applications, creating specification barriers for lower-grade imports. Stakeholders must monitor whether proposed container deposit scheme expansions alter cullet availability economics faster than furnace technology can adapt.
Market Dynamics
Australia's National Waste Policy Action Plan is compressing raw material sourcing timelines as recycled content mandates force furnace operators to reconfigure cullet supply chains faster than melting technology can adapt.
Growth Catalysts
- South Australia's wine corridor:Premium wine producers are expanding glass packaging commitments for export-grade bottles. Adelaide Hills and Barossa Valley clusters sustain demand concentration.
- TGA Good Manufacturing Practice:Batch testing protocols for pharmaceutical glass create specification barriers against lower-grade imports. Domestic manufacturers capture parenteral container contracts.
- Lightweighting technology:Furnace operators are reducing wall thickness in wine bottles without sacrificing structural integrity. Export logistics costs compress as gram weights drop.
Market Restraints
- Soda ash import dependency:Australia lacks domestic soda ash production. Price volatility in synthetic and natural soda ash feeds directly into furnace operating costs.
- Natural gas supply concentration:Victoria's gas transmission network supplies Gawler and Melbourne melting complexes. Pipeline constraints during peak winter demand elevate energy security risk.
- Aluminum substitution in beverage cans:Craft brewers are testing aluminum for certain SKUs. Glass retains premium positioning but loses volume in mid-tier segments.
Strategic Opportunities
- Container deposit scheme expansion:New South Wales and Queensland are considering scheme enhancements. Higher cullet recovery rates would improve furnace feedstock economics.
- Type I borosilicate parenteral vials:Biologic drug manufacturing is expanding in Melbourne's northern suburbs. TGA-mandated standards exclude most import competition.
- Direct-to-brewery supply contracts:Craft producers in Victoria's food manufacturing belt seek dedicated furnace output. Small-batch decorative operations proliferate near demand clusters.
Industry Challenges
- Furnace rebuild capex cycles:Large-scale melting assets require 10-15 year refractory rebuilds. Capital intensity limits mid-tier producer expansion.
- Emissions compliance timelines:Environment Protection Authority Victoria enforces tightening NOx and particulate thresholds. Retrofitting pollution controls disrupts production scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Container Glass Market |
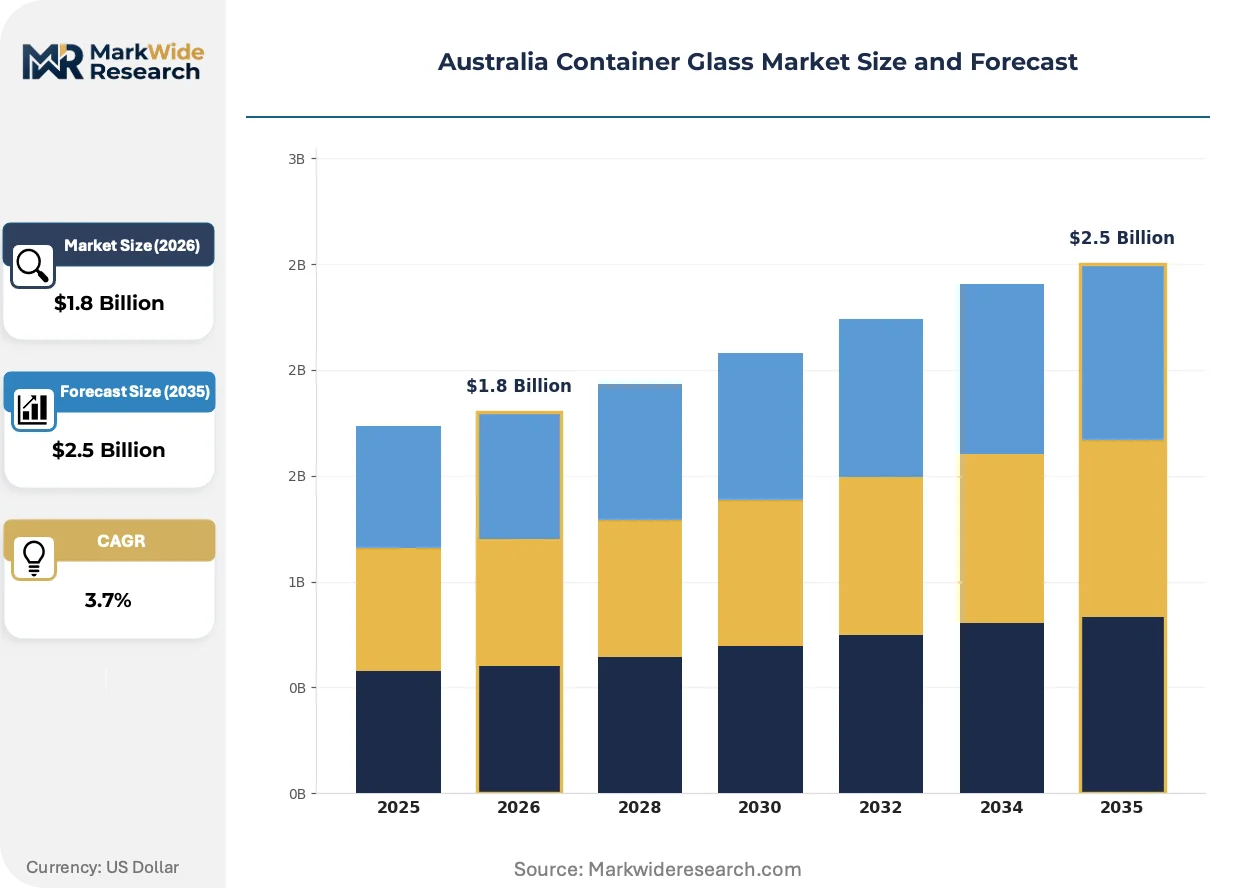
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverage Bottles, Food Jars, Pharmaceutical Containers, Cosmetic Containers End User: Food & Beverage Industry, Pharmaceuticals, Personal Care, Household Products Capacity: Small Scale, Medium Scale, Large Scale, Bulk Packaging Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Specialty Stores |
| Companies Covered | Orora Limited, O-I Glass, Visy Industries Australia, Ardagh Group, COSPAK, SCHOTT Australia, Plasdene Glass-Pak, Consol Glass, Amcor Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Container Glass Market Trends and Innovations
Active furnace technology migration and regulatory compliance automation are compressing traditional production economics across Australian glass manufacturing.
Oxygen-fired combustion technology is migrating from conventional air-fuel furnace designs to reduce NOx emissions and improve thermal efficiency. Melbourne-based recycling and re-melt networks are adopting oxy-fuel retrofits ahead of EPA Victoria enforcement milestones. The technology is migrating from premium producer installations to mid-tier furnace operations as capital costs moderate.
Environment Protection Authority Victoria's emissions thresholds are forcing real-time monitoring system deployment across furnace operations. Continuous emissions monitoring hardware and automated reporting platforms are becoming standard capital expenditures. Pharmaceutical container manufacturers face the steepest compliance costs due to 24/7 production requirements and TGA batch traceability protocols.
Direct contracting between craft beverage producers and decorative finishing operations is displacing traditional distributor-mediated supply chains. South Australia's wine corridor shows the densest concentration of these bilateral arrangements. Smaller producers bypass national distributors to secure customized bottle shapes and label adhesion specifications.
Australia Container Glass Market Segmentation
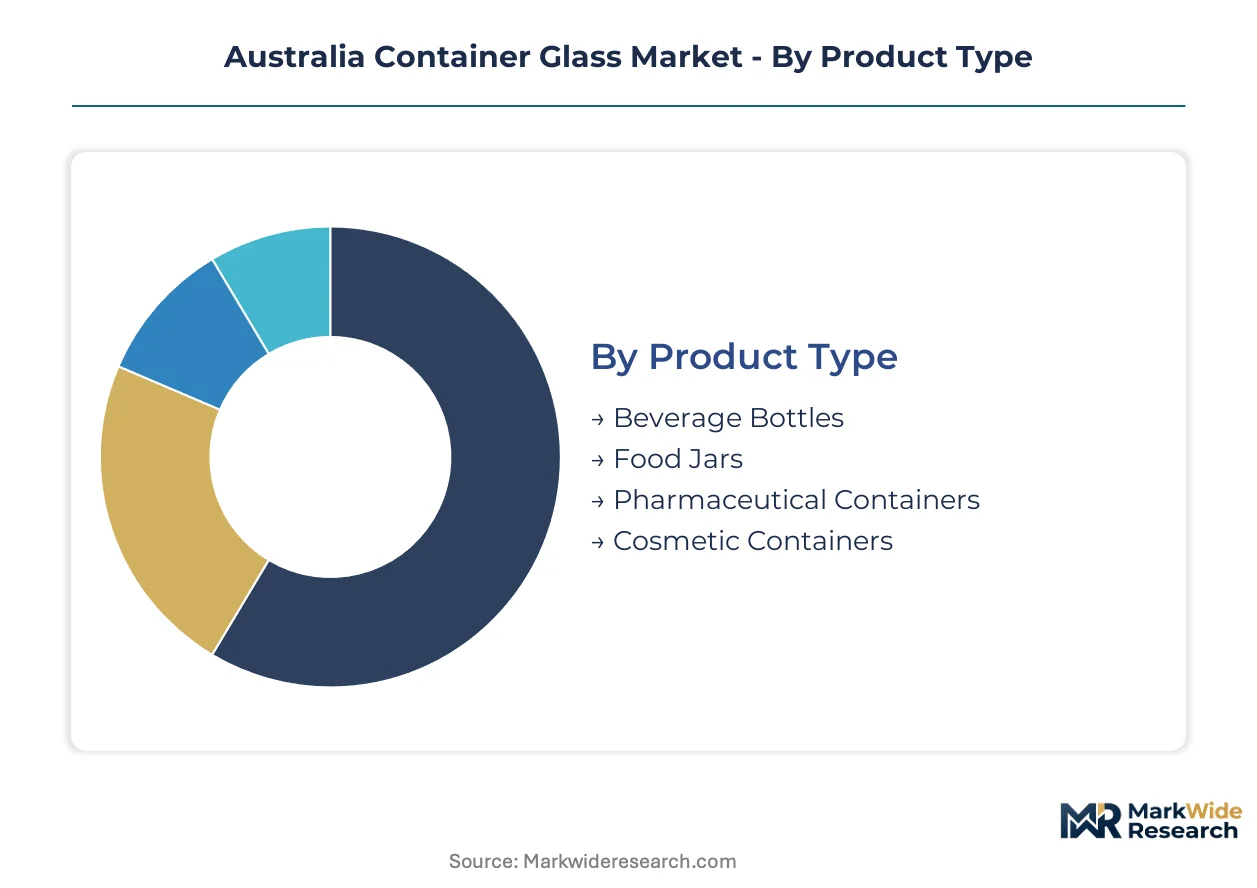
Segmentation in Australian container glass reveals how furnace output splits across radically different compliance regimes and margin structures. Pharmaceutical and beverage applications operate under incompatible specification standards, forcing manufacturers to commit to distinct production lines rather than flexible asset deployment.
Product Type:
The use-case spectrum spans oxidation-sensitive beverages through parenteral drug delivery, each demanding unique chemical inertness and barrier performance.
- Beverage Bottles:Silica-soda-lime compositions dominate wine and spirits packaging. South Australia's wine corridor concentrates demand for export-grade lightweight bottles with gram-weight reductions below 400g for standard bordeaux formats.
- Pharmaceutical Containers:Type I borosilicate glass meets TGA parenteral standards with thermal shock resistance exceeding 200°C. Melbourne's northern suburbs biologics manufacturing cluster sustains domestic vial and ampoule demand.
- Food Jars:Standard soda-lime vessels for preserved goods and spreads. Seasonal agricultural processing in Victoria's food manufacturing belt drives replacement cycles.
- Cosmetic Containers:Decorative flint and amber glass for premium skincare. Small-batch furnace output near Sydney and Melbourne serves niche fragrance and apothecary brands.
The dominant share belongs to Beverage Bottles, while Pharmaceutical Containers is closing the gap fastest.
End User:
Customer archetypes range from mass-market beverage bottlers through TGA-audited drug manufacturers, with procurement patterns diverging on batch traceability requirements.
- Food & Beverage Industry:Wine exporters and craft brewers constitute the volume anchor. Direct-to-brewery contracting is displacing distributor-mediated supply chains across Victoria's food manufacturing belt.
- Pharmaceuticals:TGA Good Manufacturing Practice mandates batch testing protocols that exclude lower-grade imports. Domestic manufacturers capture parenteral container contracts from Melbourne biologics facilities.
- Personal Care:Premium cosmetic houses source decorative amber and cobalt vessels. Label adhesion specifications and silk-screen compatibility drive supplier selection.
- Household Products:Cleaning agents and industrial chemicals in chemically resistant containers. Cullet quality tolerance is highest in this segment, supporting furnace feedstock flexibility.
Food & Beverage Industry commands the volume base, though Pharmaceuticals delivers the steepest margin expansion trajectory.
Capacity:
Scale tiers reflect furnace technology generations, from regenerative end-fired units through oxy-fuel mega-furnaces with 500+ tonne daily output.
- Large Scale:Continuous melting furnaces exceeding 300 tonnes daily output serve national beverage distributors. Orora's Gawler complex and Visy's Melbourne network anchor this tier with captive cullet supply.
- Medium Scale:Intermittent furnaces with 50-150 tonne capacity serve regional food processors. These assets face the steepest emissions compliance costs under EPA Victoria thresholds.
- Small Scale:Day-tank and pot furnace operations near craft producer clusters. South Australia's wine corridor shows dense concentration of decorative finishing operations at this scale.
- Bulk Packaging:Dedicated lines for industrial and institutional containers. Lower specification tolerances permit higher recycled content ratios under National Waste Policy Action Plan targets.
Large Scale furnaces consolidate throughput share, while Small Scale operations are expanding footprint fastest near demand clusters.
Distribution Channel:
Channel structure bifurcates between specification-heavy direct contracts and spot-market wholesale movement of standard SKUs.
- Wholesale Distributors:National networks inventory standard wine bottle formats and food jar specifications. Inventory carrying costs concentrate in Adelaide and Melbourne distribution hubs.
- Direct Supply Contracts:Bypassing distributors, craft producers negotiate dedicated furnace output. This channel is expanding most quickly in Victoria's food manufacturing belt and South Australia's wine corridor.
- Specialty Stores:Packaging supply houses serving micro-breweries and boutique food producers. Custom mold costs and minimum order quantities limit addressable market.
- Online Retail:E-commerce platforms for small-volume decorative containers. Freight economics constrain glass shipment beyond metropolitan zones due to weight-to-value ratios.
Wholesale Distributors retain the volume foundation, though Direct Supply Contracts is gaining share fastest as craft producers seek customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gawler furnace complex in South Australia anchors national container glass capacity through pipeline-connected natural gas infrastructure and integrated cullet recycling loops.
New South Wales
Sydney's metropolitan packaging demand and Newcastle port export logistics sustain container glass throughput. The state's proposed container deposit scheme enhancements would tighten cullet recovery economics for furnace operators. Western Sydney distribution hubs inventory standard beverage formats for national redistribution.
Victoria
Melbourne's northern suburbs biologics manufacturing cluster generates pharmaceutical container demand under TGA Good Manufacturing Practice protocols. EPA Victoria enforces tightening NOx emissions thresholds on furnace operations. The Melbourne-based recycling and re-melt network anchors national cullet supply chains.
South Australia
Adelaide Hills and Barossa Valley wine corridors concentrate premium export-grade bottle demand. Direct-to-winery supply contracts bypass traditional distributor channels. The Gawler furnace complex sustains vertical integration across melting and decoration stages for regional producers.
Queensland
Brisbane's food manufacturing belt drives seasonal jar demand for agricultural processing. Proposed container deposit scheme expansions would alter cullet availability for interstate furnace feedstock. The state's gas transmission network connects to eastern seaboard supply infrastructure.
Western Australia
Perth's isolated market position elevates freight costs for imported container glass. Local craft beverage producers face longer lead times for customized bottle procurement. The state's mining sector generates ancillary demand for industrial chemical containers with lower specification tolerances.
Australia Container Glass Market Competitive Landscape
On the supply side, the industry is consolidating around large-scale melting assets with captive cullet networks while decorative finishing operations fragment near demand clusters. Three strategic archetypes dominate: integrated furnace-to-decoration conglomerates, specialized pharmaceutical glass manufacturers, and regional recycling-re-melt operators. Capacity expansion and direct contracting with craft producers represent the dominant competitive moves reshaping channel structure.
Among Australia-based operators, Orora Limited, Visy Industries Australia, and O-I Glass occupy distinct positions within the supply architecture. Orora exemplifies the integrated conglomerate archetype through its Gawler complex operations. Visy anchors the recycling-re-melt tier with Melbourne-based network infrastructure. O-I Glass represents specialization in premium export wine bottle formats through lightweighting technology deployment.
| Leading Market Players |
|---|
| Orora Limited |
| O-I Glass |
| Visy Industries Australia |
| Ardagh Group |
| COSPAK |
| SCHOTT Australia |
| Plasdene Glass-Pak |
| Consol Glass |
| Amcor Limited |
| Others |
Pricing and Supply Chain Analysis
China's concentrated soda ash production anchors raw material cost volatility for Australian furnace operators, compressing margin pools downstream at beverage bottlers while pharmaceutical glass commands TGA-certified premiums. Soda ash import dependency forces pricing power toward synthetic and natural ash suppliers, with freight and currency exposure transferring risk to melting complexes.
Pricing Analysis
Volume-discount tiering structures separate export-grade wine bottles from standard food jars and economy bulk containers. Pricing stratifies across premium, standard, and economy tiers based on gram-weight reduction technology and TGA batch traceability certification. Cost compression in mid-tier beverage segments is intensifying because aluminum can substitution erodes glass volume commitments. Craft brewers show highest price sensitivity, while pharmaceutical manufacturers accept premium positioning for Type I borosilicate compliance.
Supply Chain Analysis
Export-control regimes on advanced furnace technology limit oxy-fuel combustion system flows to Australian operators, constraining emissions compliance upgrades. Supply concentrates in China for soda ash, the United States for specialized refractory materials, and Germany for precision forming equipment. Raw material dependencies span silica sand from Queensland and New South Wales, imported synthetic soda ash, and limestone from local quarries. Single-source vulnerability in natural gas transmission through Victoria's pipeline network elevates energy security risk. Distribution runs through direct-to-brewery contracts displacing traditional wholesale channels near South Australia's wine corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container glass procurement is shifting toward platform-style direct contracting between craft producers and decorative finishers, with interoperability between furnace output and small-batch customization driving ecosystem lock-in.
For Market Incumbents: Build captive cullet network moats through container deposit scheme pre-positioning ahead of National Waste Policy Action Plan enforcement. Secure long-term soda ash offtake agreements to hedge import price volatility. Aluminum substitution in mid-tier beverage cans threatens volume commitments; counter with lightweighting technology investment for export wine segments. Channel control through direct contracting locks out distributor competition.
For New Entrants and Emerging Players: Mid-scale decorative finishing operations in Victoria's food manufacturing belt represent the most penetrable entry point, bypassing capital-intensive melting furnace requirements. Target pharmaceutical glass specialization in Melbourne's northern suburbs biologics cluster, where TGA compliance barriers exclude import competition. Go-to-market through direct supply contracts with craft beverage producers seeking customized mold development and label adhesion specifications.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed recycling-re-melt operators holding EPA Victoria emissions compliance infrastructure. Five-to-ten year viability hinges on oxy-fuel technology migration completion and container deposit scheme economics stabilization. Acquisition targets include medium-scale furnace operators facing retrofit capex pressure. Watch for proposed New South Wales and Queensland container deposit scheme expansions as volume inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Retrofit | EPA Victoria NOx thresholds force Melbourne-based operators toward oxygen-fired combustion migration. |
| Direct-to-Brewery Supply Contract | South Australia's wine corridor shows densest concentration of bilateral craft producer arrangements bypassing distributors. |
| Type I Borosilicate Capacity Addition | Melbourne biologics manufacturing cluster sustains parenteral vial demand under TGA-mandated standards. |
| Cullet Network Integration | National Waste Policy Action Plan recycled content targets reconfigure raw material sourcing toward captive recycling loops. |
| Lightweighting Technology Deployment | Gram-weight reductions below 400g for standard bordeaux formats compress export logistics costs for premium wine. |
Research Methodology
Initial hypotheses were tested against primary input from furnace operations managers, beverage procurement directors, pharmaceutical regulatory affairs leads, and EPA Victoria compliance officers and refined through secondary validation. Primary interviews combined with customs trade data, TGA filing records, Australian Packaging Covenant Organisation recovery reports, and Environment Protection Authority Victoria emissions disclosures. Bottom-up furnace capacity modeling and top-down beverage production volume triangulation anchored market sizing.
Demand-supply-balance framing modeled furnace output against beverage bottling runs, pharmaceutical batch requirements, and seasonal food processing cycles across the analysis window. Segmentation dimensions spanned product type, end-user industry, furnace capacity tier, and distribution channel structure. CAGRs derived from production volume trajectories, import penetration rates, and recycled content mandate implementation timelines. Forecast inputs incorporated natural gas price volatility scenarios and soda ash import cost projections.
Practitioners should monitor container deposit scheme legislative progress and oxy-fuel technology capital cost curves for early signals of supply chain restructuring. Forecasts reflect assumptions regarding EPA Victoria enforcement timelines and National Waste Policy Action Plan compliance pathways. Material shifts in aluminum substitution rates or pharmaceutical manufacturing relocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Dominican Republic Container Glass Market
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Netherlands Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Latin America Glass Packaging Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
Boston Round Glass Bottle Market
Glass Packaging
United States Container Glass Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Spain Container Glass Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Container Glass in the UAE Market