
 Indonesia Container Glass Market | 2026-2036
Indonesia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Container Glass Market Insights
Aftermarket container refurbishment and closed-loop cullet recovery is rewriting margin distribution across Indonesia's glass value chain. PT Mulia Industrindo Tbk leverages integrated furnace operations to sustain cost advantages in soda-lime bottle production. Vetropack Indonesia anchors its position through Swiss-engineered glass technology adapted for tropical humidity conditions. Owens-Illinois Inc competes via lightweighting expertise that reduces per-unit silica consumption for beverage clients.
Container glass comprises hollow glassware formed through blow-and-blow or press-and-blow processes, typically containing silica sand, soda ash, and limestone with iron oxide content below 0.1% for flint clarity, serving as chemically inert packaging for consumables. Soda-lime glass dominates volume output due to its thermal compatibility with Indonesian filling lines and lower melting energy versus borosilicate alternatives. Bottles capture the largest share of end-user shipments, driven by beer and soft-drink bottlers in Java and Sumatra. Jars represent the fastest-growing product type as palm-oil derivatives and spice exporters adopt wide-mouth glass for premium positioning in European retail channels.
BIS-equivalent national standards and Indonesia's Ministry of Industry green industry certifications shape mandatory recycled-content thresholds for glass packaging sold domestically. The country's pharmaceutical regulator enforces USP-compliant borosilicate specifications for infusion and vaccine containers, limiting import substitution potential for local producers. Stakeholders must monitor enforcement timelines for extended producer responsibility rules and assess furnace upgrade requirements before compliance deadlines tighten.
Market Dynamics
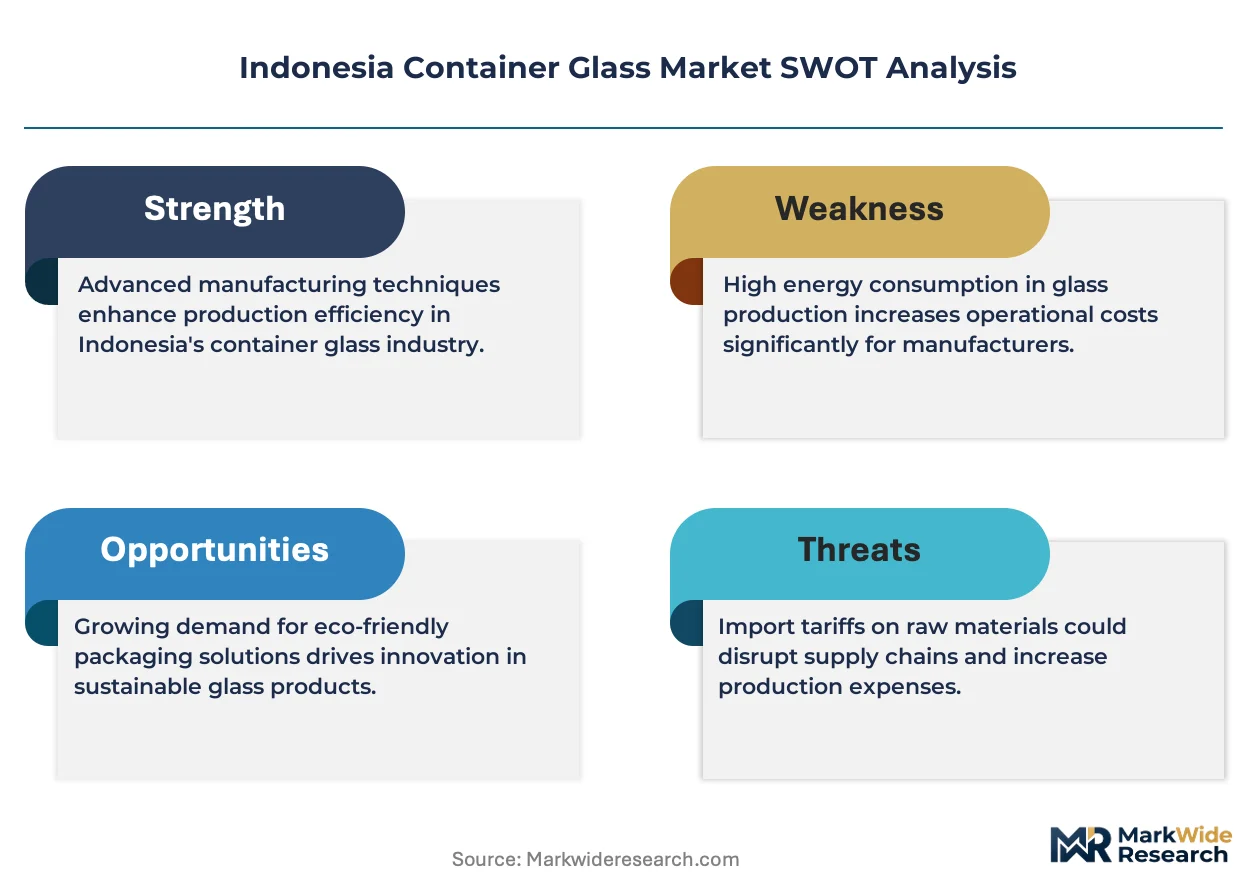
Indonesia's Ministry of Industry green industry protocols are compressing furnace upgrade timelines across Java's manufacturing corridor, forcing producers to integrate closed-loop cullet systems before recycled-content mandates tighten.
Growth Catalysts
- Green industry certification thresholds:Indonesia's Ministry of Industry mandates stricter recycled content minimums, compelling domestic glassworks to retrofit batch plants with post-consumer cullet handling. This regulatory pressure is expanding the addressable market for furnace refurbishment services.
- Premium spirits bottling:Craft distilleries and amber glass demand from European export buyers are pulling capacity toward specialty color production. Java-based manufacturers report order backlogs for pharmaceutical-grade flint containers.
- Closed-loop recovery infrastructure:Urban collection networks in Jakarta and Surabaya are densifying, reducing silica sand import dependency for soda-lime batch formulations. Cullet preprocessing investments are shortening raw material lead times.
Market Restraints
- Natural gas price volatility:Furnace operations depend on pipeline gas contracts indexed to regional LNG benchmarks, compressing margin stability for continuous-melt producers. Energy input spikes disproportionately burden mid-scale glassworks lacking long-term supply agreements.
- Import dependency for borosilicate:Indonesia's pharmaceutical regulator enforces USP-compliant specifications for infusion containers that local soda-lime capacity cannot satisfy. This technical limitation cedes vaccine packaging demand to imported borosilicate suppliers.
- Concentrated furnace ownership:Integrated producers with captive batch plants control access to molten glass supply, fragmenting toll-manufacturing options for independent brand owners. New entrants face capital barriers to greenfield furnace construction.
Strategic Opportunities
- Sumatra spice export packaging:Palm-oil derivative and seasoning producers in Medan are adopting wide-mouth glass jars for European retail shelf differentiation. This underpenetrated geography offers jar capacity expansion potential beyond Java's saturated beer bottle market.
- Lightweighting technology convergence:Swiss-engineered forming equipment combined with local silica sand beneficiation is enabling thinner-wall container production. Beverage bottlers are reducing per-unit shipping costs through gram-weight reduction programs.
- Extended producer responsibility preparation:Anticipated deposit-return scheme legislation will create first-mover advantages for producers with pre-integrated collection infrastructure. Early compliance investments position glassworks for preferred supplier status under future mandatory frameworks.
Industry Challenges
- Refractory engineering skill scarcity:Furnace rebuild cycles require specialized ceramic welding expertise that Indonesian technical institutes rarely produce. Producers compete for limited Southeast Asian talent pools during scheduled maintenance windows.
- BIS-equivalent certification timelines:National standards body testing queues for new container designs extend market entry lead times. Exporters face synchronization delays between domestic certification completion and overseas buyer qualification requirements.
- Legacy batch plant integration:Cullet preprocessing equipment must interface with decades-old furnace control systems, complicating automation retrofits. Downtime risks during system commissioning deter rapid technology adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Container Glass Market |
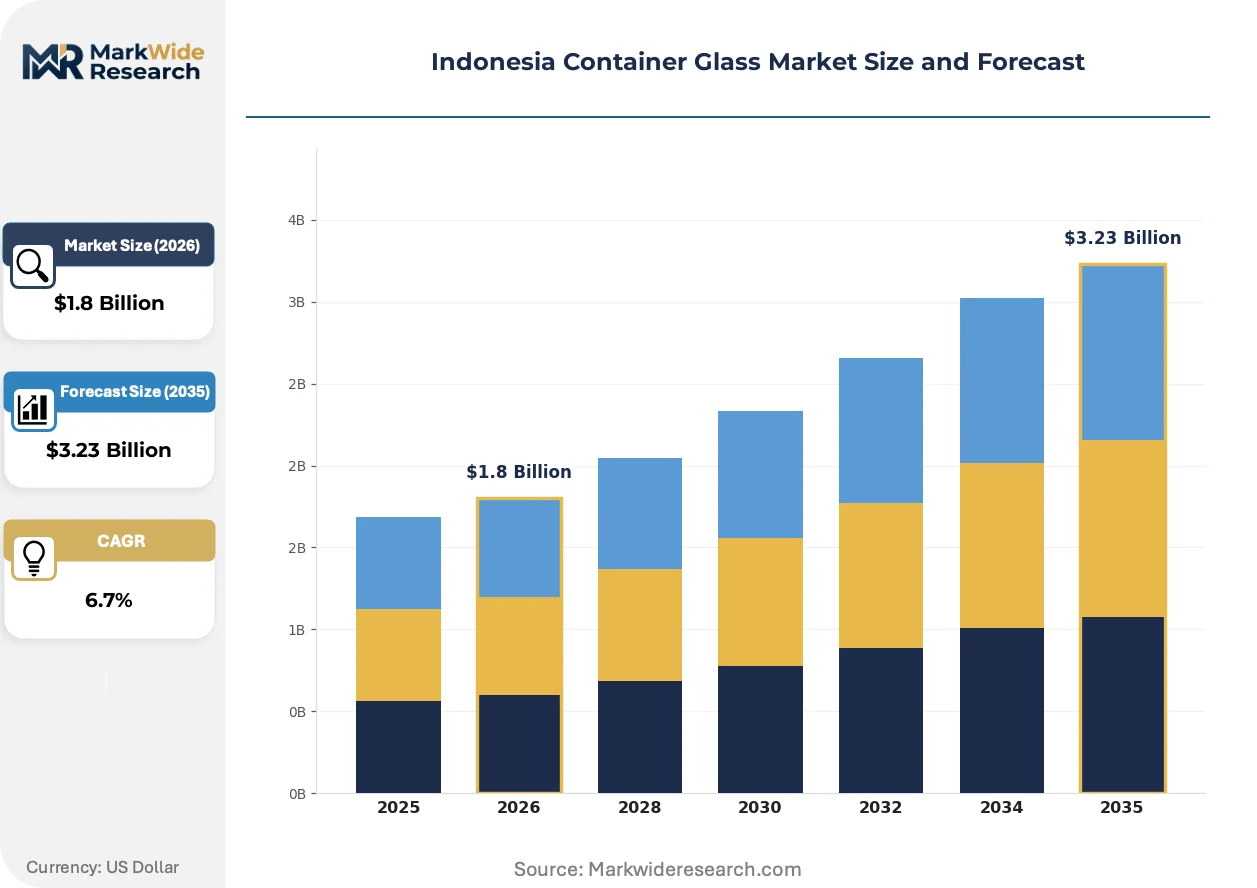
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Tumblers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Material: Cullet, Soda-Lime, Borosilicate, Lead Glass Packaging Type: Bulk Packaging, Retail Packaging, Customized Packaging, Recyclable Packaging |
| Companies Covered | Mulia Indah Packaging, FrigoGlas, Owens-Illinois Inc, Vetropack Indonesia, PT Muliaglass, PT Mulia Industrindo Tbk, PT Indoglas Jaya, PT Xinyi Glass Indonesia, Sukijo Bottle Packaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Container Glass Market Trends and Innovations
Forming technology and regulatory compliance frameworks are rewriting competitive requirements across Indonesia's container glass value chain, compressing the viable technology set for producers serving both domestic and export buyers.
Lightweighting expertise is migrating from European equipment licensors to Indonesian engineering teams through technology transfer agreements. Beer and soft-drink bottlers in Surabaya are adopting sub-300-gram standard bottle designs previously restricted to premium export contracts. This diffusion is enabling domestic producers to compete for regional ASEAN export orders on shipping cost metrics.
Indonesia's Ministry of Industry green industry protocols are mandating documented recycled content percentages for all glass packaging sold domestically. Furnace operators must now certify batch composition through third-party audit trails to maintain production licenses. Pharmaceutical and food-contact segments face the steepest compliance documentation burdens, driving investment in cullet sorting and contamination detection systems.
Consolidated procurement by multinational beverage bottlers is compressing supplier qualification cycles and unbundling after-sales technical support from base container contracts. Brand owners in Jakarta are centralizing glass purchasing through regional category managers, displacing legacy distributor relationships. This concentration is most visible in the carbonated soft-drink vertical, where three bottlers control the majority of flint glass volume.
Indonesia Container Glass Market Segmentation
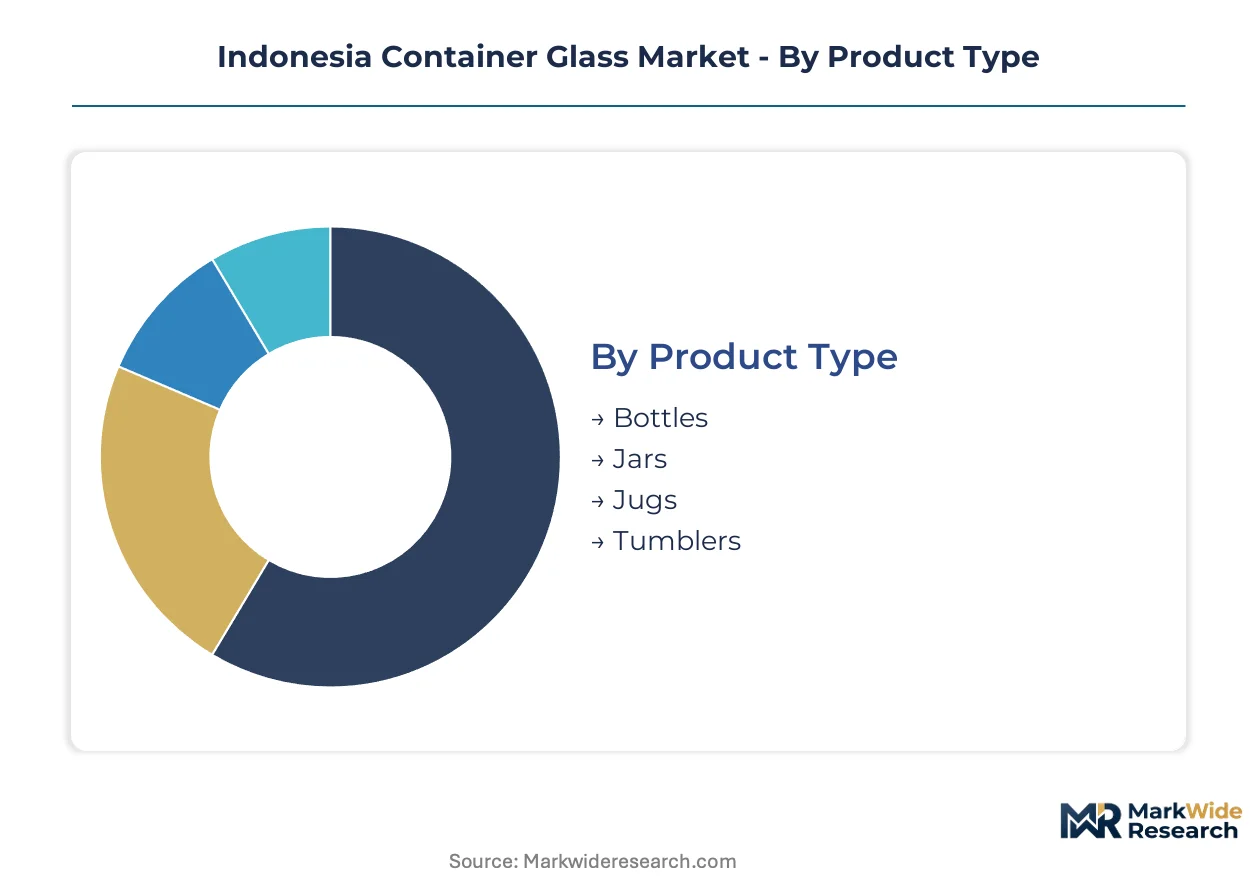
Segmentation reveals how furnace capacity allocation and regulatory compliance burdens vary sharply across container specifications. Understanding these divides helps producers prioritize batch plant retrofits and cullet preprocessing investments where returns concentrate.
Product Type:
Bottles turn on annual beverage bottling contracts with predictable replenishment cycles, while tumblers and jugs operate on longer replacement timelines tied to household durables purchasing.
- Bottles:Hollow glassware formed through blow-and-blow processes, containing silica sand, soda ash, and limestone with iron oxide below 0.1% for flint clarity. Beer and soft-drink bottlers in Java and Surabaya anchor demand, though lightweighting programs are compressing per-unit gram weights to reduce shipping costs.
- Jars:Wide-mouth containers produced via press-and-blow forming for viscous or solid contents. Palm-oil derivative and spice exporters in Medan are adopting jar packaging for European retail shelf differentiation, driving capacity expansion beyond Java's saturated bottle market.
- Jugs:Large-format containers typically exceeding one-liter capacity for bulk liquid storage. Household and institutional buyers in Sumatra drive intermittent demand tied to durables replacement cycles.
- Tumblers:Stemless drinking vessels with lower thermal shock requirements than borosilicate alternatives. Domestic hospitality and retail channels absorb volume with minimal export orientation.
Bottles anchors the volume base while Jars gains share at the steepest rate.
End User:
Cost tiers separate highly regulated pharmaceutical buyers from price-sensitive household segments, with compliance documentation burdens scaling proportionally.
- Food & Beverage:Chemically inert packaging for consumables requiring thermal compatibility with Indonesian filling lines. Jakarta-based carbonated soft-drink bottlers consolidate procurement through regional category managers, displacing legacy distributor relationships.
- Pharmaceuticals:USP-compliant borosilicate specifications for infusion and vaccine containers that local soda-lime capacity cannot satisfy. The country's pharmaceutical regulator enforces strict standards, limiting import substitution potential for domestic producers.
- Cosmetics:Premium positioning through amber and flint glass aesthetics for brand differentiation. European export buyers pull capacity toward specialty color production with documented batch composition audit trails.
- Household:Standard soda-lime containers for storage and tableware with minimal regulatory overlay. Price sensitivity dominates procurement, favoring integrated producers with captive batch plants.
Food & Beverage commands the largest capacity allocation while Pharmaceuticals imposes the steepest compliance cost per unit.
Material:
Supply concentration varies by melting energy requirements and import dependency, with cullet preprocessing investments reshaping raw material economics.
- Soda-Lime:Dominates volume output due to thermal compatibility with Indonesian filling lines and lower melting energy versus alternatives. Urban collection networks in Jakarta and Surabaya are densifying cullet supply, reducing silica sand import dependency for batch formulations.
- Cullet:Post-consumer recycled glass requiring contamination detection and sorting infrastructure. Indonesia's Ministry of Industry mandates stricter recycled content minimums, expanding the addressable market for furnace refurbishment services.
- Borosilicate:High thermal shock resistance for pharmaceutical and laboratory applications. Technical limitations in local furnace engineering cede vaccine packaging demand to imported suppliers.
- Lead Glass:Superior optical clarity for premium decorative and crystal applications. Niche demand from cosmetics and giftware channels with limited volume scale.
Soda-Lime anchors the volume base while Cullet is climbing the fastest as green industry protocols tighten.
Packaging Type:
Customer type stratification separates multinational beverage bottlers seeking standardized bulk supply from regional brand owners requiring customized differentiation.
- Retail Packaging:Individual unit presentation for supermarket and convenience store channels. European spice exporters in Medan demand wide-mouth jar configurations with premium shelf aesthetics.
- Bulk Packaging:Large-volume shipments for industrial bottlers with centralized processing facilities. Three carbonated soft-drink bottlers control the majority of flint glass volume through consolidated procurement.
- Customized Packaging:Brand-specific mold designs and color specifications for market differentiation. Craft distilleries order backlogs for pharmaceutical-grade flint containers with amber glass alternatives.
- Recyclable Packaging:Documentation of post-consumer recovery pathways for green industry certification. Anticipated deposit-return scheme legislation creates first-mover advantages for pre-integrated collection infrastructure.
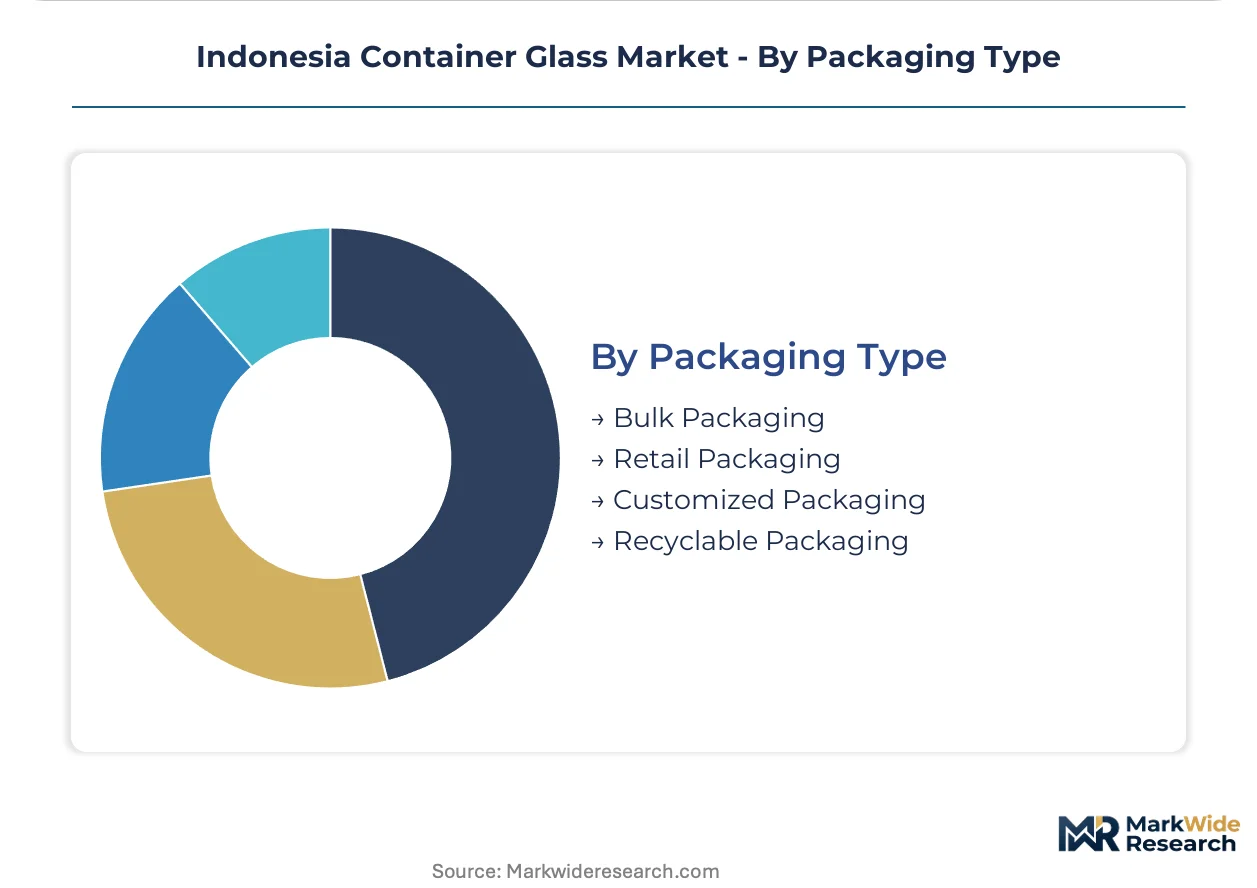
Bulk Packaging anchors the volume base while Recyclable Packaging is expanding most quickly as extended producer responsibility frameworks advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java's manufacturing corridor consumes container glass differently from Sumatra's export-oriented spice belt, with Jakarta bottlers prioritizing lightweight flint bottles while Medan packagers favor wide-mouth amber jars for European retail shelf differentiation.
Java
Jakarta and Surabaya anchor Indonesia's densest glassworks clusters, serving carbonated soft-drink bottlers and beer manufacturers with continuous-melt furnace output. Indonesia's Ministry of Industry green industry protocols mandate recycled content documentation for all domestic sales, compressing upgrade timelines for batch plants in Bekasi and Sidoarjo. Surabaya-based producers report order backlogs for pharmaceutical-grade flint containers as craft distilleries pull capacity toward specialty color production.
Sumatra
Palm-oil derivative and seasoning exporters in Medan drive jar demand for European retail channels, adopting wide-mouth glass configurations that bypass Java's saturated bottle market. The country's national standards body enforces BIS-equivalent certification for food-contact packaging, extending testing queues for new container designs. Lampung and North Sumatra host emerging collection networks that feed cullet preprocessing investments, reducing silica sand import dependency for regional batch formulations.
Sulawesi
Seafood processing and coconut oil bottlers in Makassar generate intermittent demand for large-format jugs and storage containers with minimal export orientation. Indonesia's pharmaceutical regulator holds local soda-lime capacity to USP-compliant borosilicate specifications that domestic furnace engineering cannot satisfy, ceding vaccine packaging demand to imported suppliers. South Sulawesi's industrial zones remain underpenetrated for container glass, with logistics costs favoring toll-manufacturing arrangements over greenfield furnace construction.
Kalimantan
Edible oil and mining chemical packagers in Balikpapan and Samarinda absorb standard soda-lime output for bulk liquid storage applications with lower regulatory overlay than pharmaceutical or food-contact segments. Extended producer responsibility legislation anticipated from Jakarta will create compliance preparation windows for producers serving this geography. East Kalimantan's industrial corridors lack integrated cullet recovery infrastructure, forcing reliance on imported batch materials despite proximity to Java's manufacturing base.
Bali and Nusa Tenggara
Premium cosmetics and artisanal beverage producers in Denpasar and Lombok generate niche demand for amber and decorative glass with documented batch composition audit trails. Tourism-driven hospitality channels absorb tumbler and tableware volume with minimal furnace-scale requirements. These islands remain dependent on Java-based suppliers for molten glass, with shipping costs compressing margin structures for mid-scale brand owners.
Indonesia Container Glass Market Competitive Landscape
Capability concentration sits with integrated producers commanding captive batch plants and furnace refurbishment expertise; scale advantage sits with multinational licensors transferring lightweighting technology to local engineering teams. The vendor base stratifies across three tiers: Swiss-engineered specialists, Chinese-backed volume players, and domestic incumbents with legacy distributor relationships. Competitive moves center on furnace upgrade timing ahead of green industry certification deadlines and technology licensing agreements that embed forming equipment vendors in long-term service contracts.
Among Indonesia-based producers, PT Mulia Industrindo Tbk and PT Muliaglass occupy positions within the integrated domestic tier, while Owens-Illinois Inc exemplifies multinational scale operators and Vetropack Indonesia represents Swiss-engineered technology adaptation. These named entities anchor archetype discussions without implying specific strategic actions or market share claims. New entrants face capital barriers to greenfield furnace construction while toll-manufacturing options fragment for independent brand owners lacking molten glass supply agreements.
| Leading Market Players |
|---|
| Mulia Indah Packaging |
| FrigoGlas |
| Owens-Illinois Inc |
| Vetropack Indonesia |
| PT Muliaglass |
| PT Mulia Industrindo Tbk |
| PT Indoglas Jaya |
| PT Xinyi Glass Indonesia |
| Sukijo Bottle Packaging |
| Others |
Pricing and Supply Chain Analysis
The Surabaya-Jakarta manufacturing corridor's freight cost dynamics concentrate supply power among integrated furnace operators while forcing downstream price differentiation between bulk beverage contracts and specialty pharmaceutical-grade shipments.
Pricing Analysis
Long-term offtake agreements dominate carbonated soft-drink procurement, with three bottlers locking in flint glass volumes through multi-year contracts indexed to natural gas benchmarks. Price differentiation separates USP-compliant pharmaceutical containers from standard soda-lime bottles through certification audit burdens and contamination detection requirements. Pricing pressure stems from LNG-indexed energy costs compressing margins for mid-scale glassworks lacking captive batch plants. Household and institutional buyers exhibit highest price sensitivity, while European spice exporters absorb premiums for documented recycled-content amber jars.
Supply Chain Analysis
Extended payment terms from multinational beverage bottlers strain working capital for toll-manufacturing-dependent producers, accelerating consolidation toward integrated furnace ownership. Silica sand beneficiation and cullet preprocessing draw from Australian and domestic Indonesian sources, with furnace control systems and Swiss-engineered forming equipment anchored in European supply channels. Single-source vulnerability concentrates in refractory ceramic welding expertise, where Southeast Asian talent pools face competition during scheduled maintenance windows. Distribution runs through Jakarta-based category managers consolidating procurement for carbonated soft-drink verticals, displacing legacy distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's container glass market presents a defensive-moat structure where regulatory entrenchment through green industry certification creates switching costs that cement incumbent positions.
For Market Incumbents: Pre-empt compliance deadlines by accelerating furnace refurbishment cycles ahead of Ministry of Industry recycled-content mandate tightening. Secure captive cullet preprocessing capacity to defend margin position against natural gas price volatility, while embedding Swiss-engineered lightweighting technology into long-term service contracts that raise rival's capital barriers.
For New Entrants and Emerging Players: Sumatra's Medan spice corridor offers underpenetrated jar capacity expansion beyond Java's saturated beer bottle market, where palm-oil derivative exporters seek wide-mouth configurations for European retail differentiation. Target toll-manufacturing arrangements with independent brand owners lacking molten glass supply agreements, leveraging Lampung's emerging collection networks for cullet feedstock advantages.
For Investors and Strategic Acquirers: Furnace refurbishment specialists with integrated batch plant engineering capabilities represent the optimal acquisition archetype, positioned to capture mandated upgrade spending across Indonesia's manufacturing corridor. Monitor enforcement timelines for extended producer responsibility legislation as the inflection signal determining first-mover advantages in deposit-return scheme infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Refurbishment with Cullet Integration | Ministry of Industry mandates compress upgrade timelines for green industry certification compliance. |
| Lightweighting Technology Licensing | Swiss-engineered forming equipment reduces per-unit silica consumption for Surabaya beverage bottlers. |
| Sumatra Jar Capacity Expansion | Medan spice exporters adopt wide-mouth glass for European retail shelf differentiation. |
| Extended Producer Responsibility Preparation | Anticipated deposit-return legislation creates first-mover advantages for pre-integrated collection infrastructure. |
| Pharmaceutical-Grade Flint Certification | USP-compliant specifications limit import substitution potential for domestic soda-lime capacity. |
Research Methodology
Initial hypotheses were tested against primary input from furnace operations managers, beverage procurement directors, pharmaceutical packaging specialists, and cullet preprocessing equipment vendors, then refined through secondary validation against Ministry of Industry regulatory filings, BIS-equivalent standards documentation, customs trade records, and SEC disclosures from multinational glass manufacturers. Bottom-up volume modeling triangulated with top-down value estimates across product type, end-user vertical, material composition, and geographic manufacturing cluster dimensions.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeling spanning bottle versus jar versus jug formats, food and beverage versus pharmaceutical versus cosmetics end-use, and soda-lime versus borosilicate material tiers. CAGRs were derived from installed furnace capacity utilization trajectories, green industry protocol compliance timelines, and lightweighting technology diffusion curves through Indonesian engineering teams.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese-backed volume players or accelerated enforcement of extended producer responsibility rules would shift outcomes. Macroeconomic deviation in LNG pricing, regulatory acceleration in recycled-content thresholds, or breakthroughs in borosilicate furnace engineering would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
United Kingdom Glass Packaging Market
Glass Packaging
Europe Glass Packaging Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Mexico Glass Packaging Market
Glass Packaging
Middle East and Africa Pharmaceutical Glass Packaging Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Europe Glass Bottles and Containers Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Mason Jars Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Japan Container Glass Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market