
 Cosmetic Vials Market | 2026-2036
Cosmetic Vials Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Vials Market Outlook
Post-consumer recycled glass is broadening cost structures across cosmetic vial supply chains as brands face Scope 3 emissions targets. Gerresheimer AG leverages captive glass-melting capacity across European sites to sustain margin control on pharmaceutical-grade cosmetic containers. AptarGroup, Inc. dominates precision dispensing closures, while SGD Pharma anchors its position through borosilicate expertise for high-end serum applications.
Cosmetic vials are small-format primary packaging vessels, typically ranging from 5 ml to 30 ml, designed to protect light-sensitive and oxidation-prone formulations through UV-filtering glass or multilayer plastic constructions. Their commercial purpose centers on preserving active ingredient stability while enabling precise, hygienic dosing for premium skincare and fragrance products. Glass vials command the dominant share of value pools due to perceived luxury positioning and chemical inertness, though droper closure systems represent the fastest-growing configuration as serum formats proliferate. Plastic and acrylic alternatives gain traction in travel-retail and sampling channels where weight reduction and breakage resistance outweigh premium tactile demands.
The US FDA governs cosmetic labeling and ingredient disclosure under the Modernization of Cosmetics Regulation Act, while REACH and the EU Green Deal constrain virgin plastic use and mandate recyclability disclosures across European supply chains. These frameworks elevate compliance costs for imported vials and favor regional manufacturers with established testing protocols. Stakeholders must monitor evolving extended producer responsibility schemes and biobased material certifications as decisive filters for supplier qualification and brand positioning.
Market Dynamics
Post-consumer recycled glass is forcing material recalibration across cosmetic vial supply chains as brands confront Scope 3 emissions disclosure mandates from major retailers.
Growth Catalysts
- REACH chemical safety mandates:European brands accelerate adoption of pharmaceutical-grade borosilicate vials to preempt compliance penalties and secure shelf placement in regulated markets.
- Serum format proliferation:High-potency skincare actives require UV-filtering amber glass and precision droper systems, expanding addressable packaging spend per SKU.
- Beauty cluster concentration:Manufacturing proximity to Paris, Hamburg, and New Jersey cosmetic R&D hubs compresses lead times and enables rapid formulation-to-packaging iteration.
Market Restraints
- Energy-intensive glass melting:Natural gas price volatility at European manufacturing sites compresses margin buffers for mid-tier suppliers without captive furnace capacity.
- Single-source boron supply:Concentrated extraction in Turkey and California creates geopolitical exposure for borosilicate glass producers serving premium serum applications.
- Aluminum closure substitution:Metal roller-ball applicators for eye serums displace traditional glass droppers in travel-retail formats below 10 ml.
Strategic Opportunities
- India PLI scheme for packaging:Domestic manufacturing incentives enable cost-competitive export bases for Middle Eastern and Southeast Asian beauty brands.
- Biobased polymer certification:USDA BioPreferred and EU Ecolabel standards open premium positioning for drop-in bio-acrylic vials in clean beauty portfolios.
- Direct-to-consumer sampling:Subscription box channels demand sub-5 ml plastic vial formats with tamper-evident closures, creating volume pools outside traditional retail procurement.
Industry Challenges
- Color-matching precision:Batch-to-batch consistency in UV-filtering amber glass requires skilled furnace technicians, constraining capacity expansion at legacy European plants.
- Multi-jurisdiction filing timelines:Simultaneous FDA cosmetic facility registration and EU REACH dossier preparation extends new product qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Vials Market |
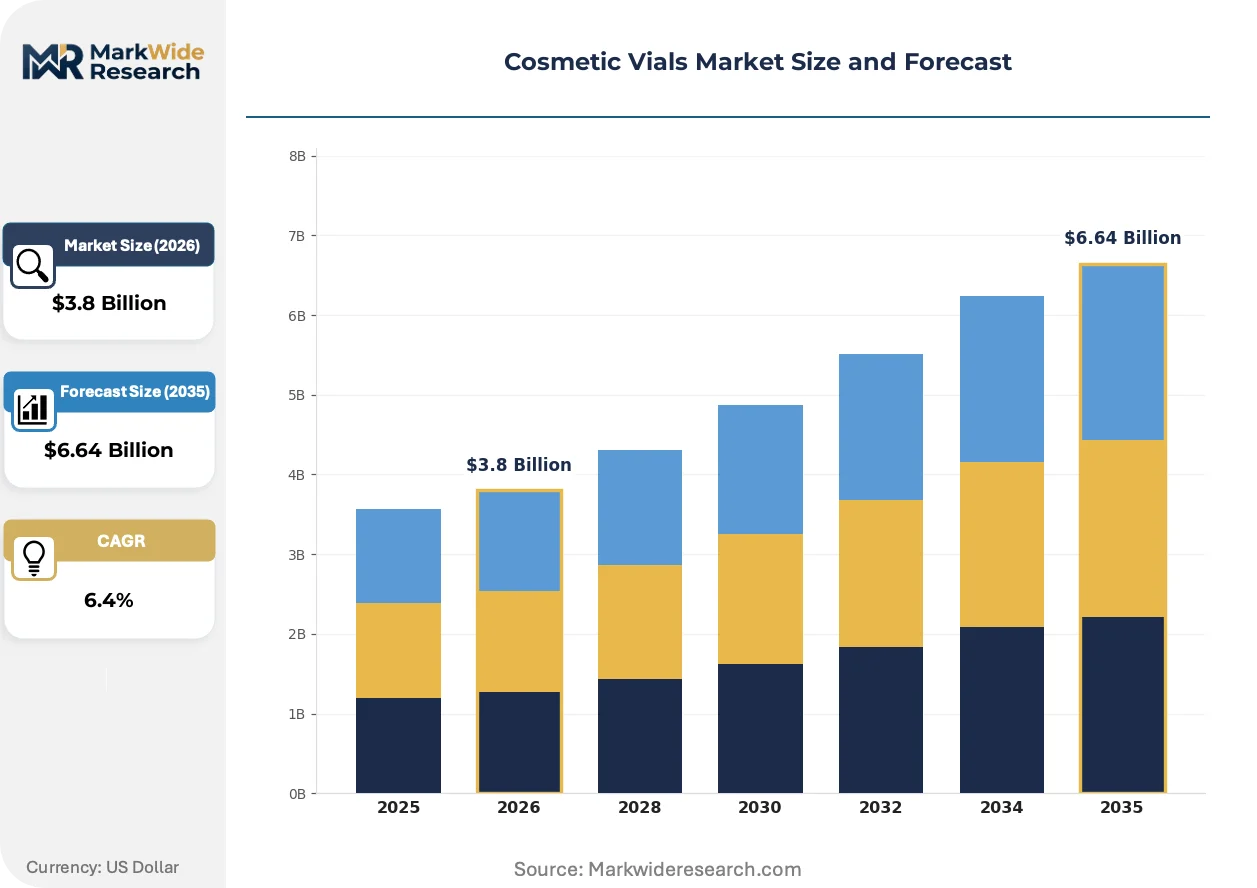
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Glass, Plastic, Acrylic, Polyethylene Closure Type: Dropper, Screw Cap, Pump, Spray Volume: 5 ml, 10 ml, 15 ml, 30 ml End User: Cosmetic Brands, Retailers, Distributors, Manufacturers |
| Companies Covered | Gerresheimer AG, AptarGroup, Inc., Bormioli Luigi S.p.A., Virospack SLU, SGD Pharma, Stoelzle Glass Group, Quadpack Industries, HEINZ-GLAS GmbH, FusionPKG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Vials Market Strategic Shifts
Active ingredient stability demands and circular economy mandates are compressing innovation cycles across material science, closure engineering, and end-of-life design for cosmetic primary packaging.
Monolayer bio-based polyethylene terephthalate is overtaking conventional fossil-derived PET in travel-retail vial applications. Clean beauty brands in Sephora and Ulta assortments specify minimum 30% biobased content for shelf placement. This material transition is overtaking cost-parity thresholds faster than supply chains anticipated, forcing molders to requalify injection parameters without secondary barrier coatings.
EU Green Deal packaging waste regulations mandate minimum recycled content thresholds and standardized recyclability labeling by 2030. Cosmetic brands must redesign multicomponent droper assemblies to achieve mono-material status or fund extended producer responsibility schemes. French and German manufacturers face the steepest compliance curves given existing premium positioning that relies on complex decoration and multi-material closures.
Refillable vial systems with permanent outer shells and replaceable inner cartridges are gaining traction among prestige skincare houses. Department store counters in Tokyo and Seoul pilot return-and-refill programs that displace single-use glass entirely for core serum SKUs. This consumption-pattern shift concentrates in Asia-Pacific markets where retail staff facilitate physical collection, contrasting with direct-to-consumer logistics challenges in North American suburban geographies.
Cosmetic Vials Market Segmentation
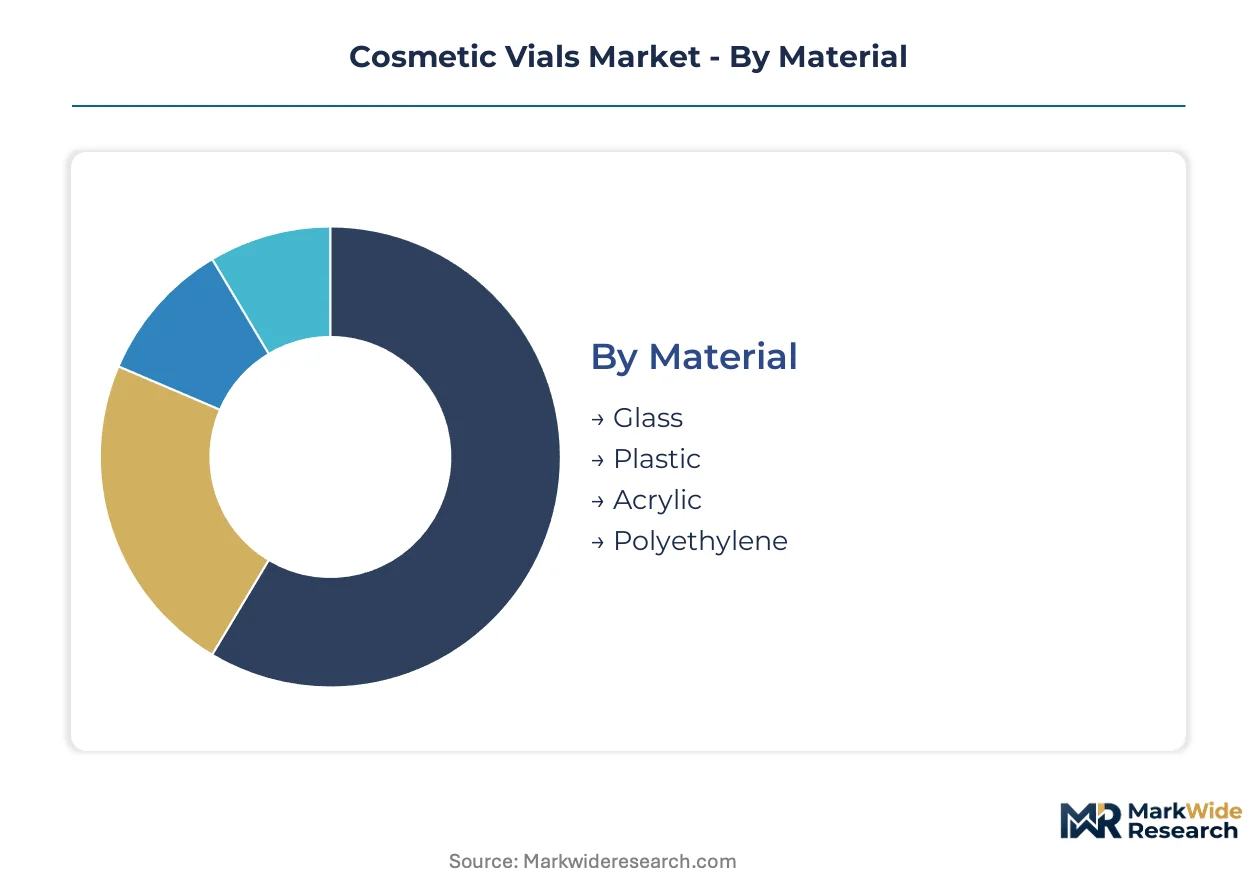
Material selection and closure engineering determine shelf appeal and formulation protection for cosmetic vials. Upgrade cycles accelerate as brands reformulate for clean beauty positioning and regulatory compliance.
Material:
Replacement cycles favor inert substrates that preserve active ingredient stability across reformulation events.
- Glass:UV-filtering amber and borosilicate constructions dominate premium serum applications. French and German cosmetic houses specify pharmaceutical-grade borosilicate to satisfy REACH chemical safety dossiers and secure regulated market placement.
- Plastic:Monolayer bio-based PET gains traction in travel-retail channels where weight reduction outweighs tactile luxury demands. Sephora and Ulta clean beauty assortments now mandate minimum biobased thresholds, compressing mold requalification timelines for suppliers.
- Acrylic:Crystal clarity and shatter resistance serve sampling programs and direct-to-consumer subscription formats.
- Polyethylene:Low-density grades enable squeeze-dispense functionality for gel and lotion vials in mass-market skincare.
Glass sits at the top of the volume ranking, with plastic climbing the fastest.
Closure Type:
Margin structures diverge sharply between precision-dispensing premium systems and commodity sealing formats.
- Dropper:Glass pipette and bulb assemblies with measured-dose calibration command packaging spend multiples for high-potency actives. Serum format proliferation across prestige skincare lines expands addressable closure spend per SKU.
- Screw Cap:Standard threaded closures serve fragrance oils and basic moisturizers where cost minimization dominates procurement.
- Pump:Airless pump mechanisms protect oxidation-sensitive formulations in vitamin C and retinol applications.
- Spray:Fine-mist atomizers accommodate facial mists and setting sprays in K-beauty influenced portfolios.
Dropper closures capture the highest value per unit, with pump systems expanding most quickly in anti-aging segments.
Volume:
Format sizing tracks consumption occasion fragmentation across trial, travel, and treatment-course applications.
- 5 ml:Micro-vial dimensions serve single-use sampling and subscription box insertion. Direct-to-consumer channels demand tamper-evident sub-5 ml plastic formats with break-resistant construction.
- 10 ml:Travel-retail standard size balances portability with sufficient supply for short-duration trips. Aluminum roller-ball applicators for eye serums displace glass droppers in this format tier.
- 15 ml:Mid-range capacity targets premium skincare trial sizes and concentrated treatment courses.
- 30 ml:Full-size serum and ampoule standard for department store counters and e-commerce replenishment.
30 ml formats lead absolute shipment volumes, with 5 ml sizes gaining share fastest in direct-to-consumer sampling channels.
End User:
Procurement authority concentrates with entities controlling shelf placement and formulation-to-packaging iteration speed.
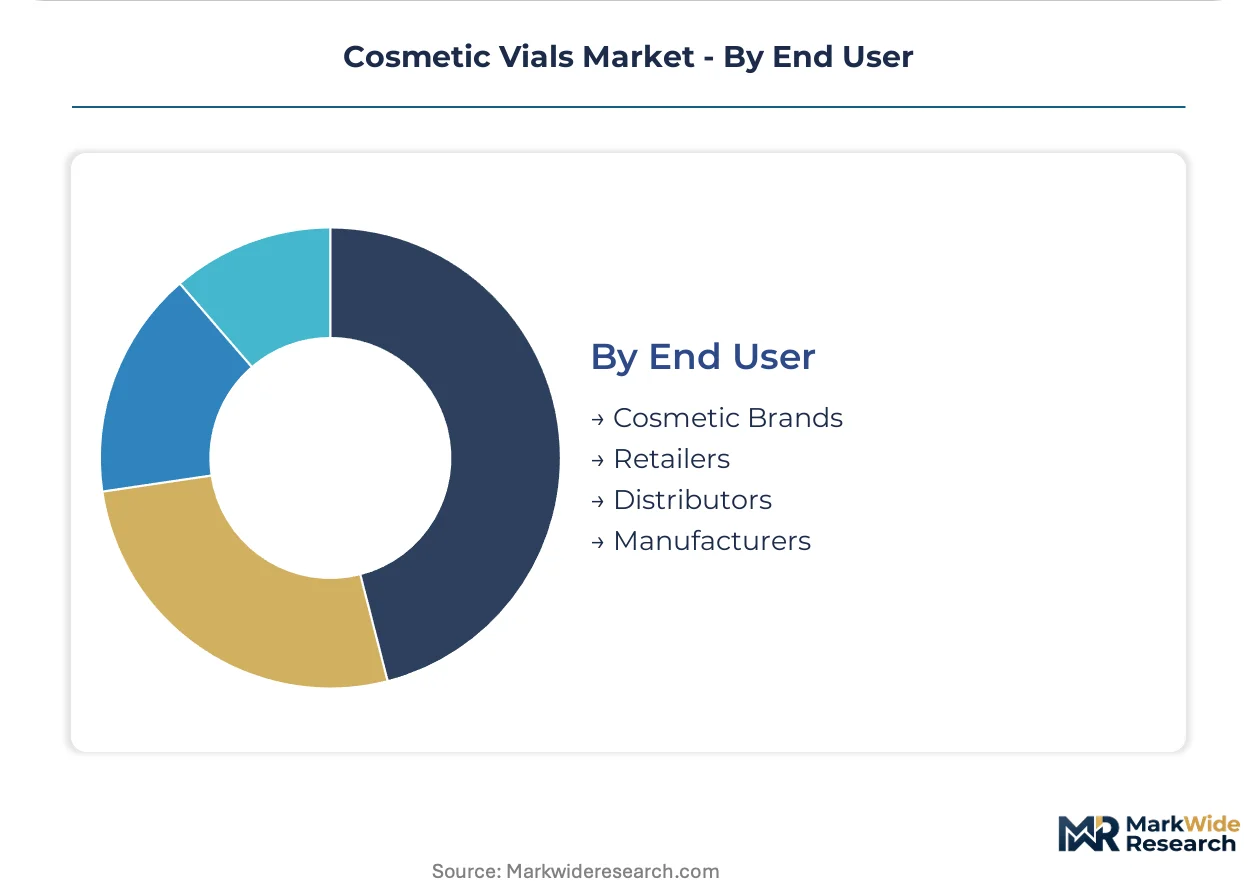
- Cosmetic Brands:L'Oréal, Estée Lauder, and LVMH beauty divisions specify primary packaging parameters and audit supplier compliance against Scope 3 targets. Beauty cluster proximity to Paris, Hamburg, and New Jersey R&D hubs compresses lead times for rapid iteration.
- Retailers:Sephora, Ulta, and Douglas impose biobased content minimums and recyclability labeling standards through vendor scorecards.
- Distributors:Regional logistics specialists aggregate fragmented brand demand in Middle Eastern and Southeast Asian markets.
- Manufacturers:Contract packagers and private-label producers source vials against tight cost benchmarks for mass-market retail placement.
Cosmetic brands command the largest procurement scale, with retailers ascending fastest in packaging specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors the global cosmetic vials trade through its dense concentration of luxury beauty headquarters and packaging innovation labs. German glass-melting sites supply pharmaceutical-grade borosilicate to prestige skincare houses. New Jersey and Seoul complete the quartet of demand centers where formulation-to-packaging iteration cycles compress below twelve weeks.
United States
Prestige skincare brands in New York and Los Angeles drive demand for UV-filtering amber glass and precision dropper systems. The FDA's Modernization of Cosmetics Regulation Act elevates compliance costs for imported vials and favors domestic contract manufacturers with established testing protocols. New Jersey's corridor between Newark and Edison hosts concentrated cosmetic R&D facilities that source vials on compressed lead times.
Germany
Hamburg and Berlin cosmetic houses specify pharmaceutical-grade borosilicate to satisfy REACH chemical safety dossiers. The EU Green Deal packaging waste regulations mandate recyclability disclosures that reshape material selection for export-bound brands. North Rhine-Westphalia's glass-melting corridor leverages captive furnace capacity to sustain margin control amid natural gas price volatility.
France
L'Oréal and LVMH beauty divisions in Paris impose Scope 3 emissions targets that accelerate post-consumer recycled glass adoption across supplier networks. ANSM cosmetic safety standards align with REACH frameworks to create unified compliance benchmarks for premium packaging. The Île-de-France cluster compresses formulation-to-packaging iteration cycles through proximity between brand headquarters and specialty glass decorators.
South Korea
Seoul-based K-beauty brands proliferate serum formats that demand 10 ml to 30 ml borosilicate vials with airless pump compatibility. MFDS cosmetic ingredient disclosure rules elevate documentation requirements for imported primary packaging. The Seoul Capital Area's dense network of contract manufacturers enables rapid SKU proliferation for multi-step skincare routines.
India
Mumbai and Delhi-NCR cosmetic brands source cost-competitive glass and plastic vials for domestic mass-market skincare and export to Middle Eastern beauty markets. The PLI scheme for packaging manufacturing incentivizes domestic production capacity that serves regional demand clusters. Maharashtra's emerging specialty packaging corridor attracts investment from brands seeking alternatives to Chinese supply chains.
Cosmetic Vials Market Competitive Environment
Global majors compete with regional champions across furnace capacity and precision closure engineering. The vendor base stratifies between integrated glass-melting conglomerates, specialist closure engineers, and regional decorators serving beauty cluster proximity demands. Three archetypes dominate: pharmaceutical-grade glass specialists with captive borosilicate capacity, precision dispensing engineers controlling dropper and pump mechanism patents, and agile regional fabricators compressing lead times through beauty cluster adjacency. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through distributor partnerships in Southeast Asian and Middle Eastern markets.
Among German-integrated glass conglomerates, Gerresheimer AG exemplifies the pharmaceutical-grade specialist archetype through its European furnace network. AptarGroup, Inc. occupies the precision dispensing tier with measured-dose closure systems. SGD Pharma represents the borosilicate expertise position for high-end serum applications. These three anchors illustrate how competitive positioning stratifies across material control, mechanism engineering, and formulation-protection specialization.
| Leading Market Players |
|---|
| Gerresheimer AG |
| AptarGroup, Inc. |
| Bormioli Luigi S.p.A. |
| Virospack SLU |
| SGD Pharma |
| Stoelzle Glass Group |
| Quadpack Industries |
| HEINZ-GLAS GmbH |
| FusionPKG |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade borosilicate certification creates a bifurcated cost structure where REACH-compliant European suppliers command substantial premiums over standard soda-lime alternatives, while procurement teams at L'Oréal and Estée Lauder exploit this tiering to negotiate volume rebates that compress mid-tier margins.
Pricing Analysis
Natural gas pass-through clauses in German and French furnace contracts expose pricing to energy market volatility, forcing buyers to absorb quarterly adjustments or shift procurement to fixed-rate suppliers. Three-tier pricing structure across premium pharmaceutical-grade, standard cosmetic-grade, and economy sampling-grade levels separates procurement pools by formulation sensitivity and brand positioning. Pricing pressure stems from Turkish boron supply concentration and aluminum roller-ball substitution in travel-retail formats. Mass-market contract packagers exhibit highest price sensitivity, while prestige houses prioritize batch consistency and regulatory documentation.
Supply Chain Analysis
Single-source vulnerability sits with Turkish and Californian boron extraction, which feeds borosilicate production for serum-grade vials. Manufacturing concentrates in Germany, France, and Italy, where captive glass-melting capacity anchors pharmaceutical-grade output. Raw material dependencies include soda ash, boron trioxide, and post-consumer recycled cullet. Supply chain risk centers on geopolitical exposure to concentrated boron reserves. Distribution runs through beauty cluster adjacency in Paris, Hamburg, and New Jersey, with regional decorators compressing lead times for formulation-to-packaging iteration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, as the EU Green Deal's 2030 recycled content mandates force reformulation-to-packaging redesign cycles that favor incumbent technical specialists.
For Market Incumbents: Lock in captive borosilicate furnace capacity and REACH dossier libraries to preempt mid-tier competitors from qualifying for prestige brand supplier lists. Aluminum roller-ball substitution in sub-10 ml formats and Indian PLI-subsidized challengers threaten margin buffers. Backward integration into post-consumer recycled cullet sorting secures Scope 3 compliance credibility with Paris and Hamburg beauty houses.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in 5 ml sampling formats invites specialized molders to capture direct-to-consumer subscription box demand outside traditional retail procurement channels. Biobased PET certification gaps in travel-retail applications and Middle Eastern export bases under India's PLI scheme offer penetrable white-space. Lead with USDA BioPreferred or EU Ecolabel credentials to bypass incumbent technical qualification barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier decorators lack captive furnace capacity and struggle to fund simultaneous FDA facility registration and REACH dossier preparation. Long-term viability favors pharmaceutical-grade glass specialists with beauty cluster proximity and precision closure engineering patents. Watch biobased polymer cost-parity inflection against fossil-derived PET as the signal for material substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Cullet | Captive post-consumer glass supply secures EU Green Deal compliance for French and German brands. |
| Precision Closure Patent Acquisition | Measured-dose dropper mechanisms command packaging spend multiples in prestige serum applications. |
| Beauty Cluster Manufacturing Expansion | Proximity to Paris and Hamburg R&D hubs compresses formulation-to-packaging iteration below twelve weeks. |
| Biobased Polymer Certification Investment | USDA BioPreferred and EU Ecolabel standards open clean beauty shelf placement at Sephora and Ulta. |
| Regulatory Dossier Service Capability | Simultaneous FDA registration and REACH preparation cuts new supplier qualification cycles for cosmetic brands. |
Study Parameters
Bottom-up cosmetic brand procurement modeling reconciled against top-down glass-melting capacity tracking forms the analytical core of this study. Primary interviews with packaging procurement managers at L'Oréal and Estée Lauder, furnace operations directors at German and French glass sites, regulatory affairs leads navigating REACH and FDA frameworks, and category buyers at Sephora and Ulta informed demand-side assumptions. Secondary validation drew from ECHA REACH dossier databases, FDA cosmetic facility registration records, EU Green Deal packaging waste regulation filings, and customs trade data on borosilicate glass imports.
Input-output matrix framing connects raw material cost indices for natural gas, boron trioxide, and recycled cullet against finished vial pricing across pharmaceutical-grade, cosmetic-grade, and sampling-grade tiers. Segmentation dimensions modeled include material substrate, closure mechanism, volume format, and end-user procurement authority across the analysis window. CAGRs derive from elasticity-adjusted volume projections calibrated to beauty cluster expansion rates and serum format proliferation trends. Forecast inputs incorporate energy price volatility scenarios and biobased polymer substitution curves.
Caveats apply where Turkish boron supply disruption, natural gas price spikes at European furnace sites, or accelerated aluminum roller-ball substitution could materially shift the outlook. Forecasts reflect documented assumptions on regulatory enforcement timelines and brand sustainability commitment durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
India Personal Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Lotion Tubes Market
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Latin America Cosmetic Packaging Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Global Eye Cosmetic Packaging Market