
 Chile Container Glass Market | 2026-2036
Chile Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Container Glass Market Insights
Preventive maintenance contracts for furnace rebuilds and forming machine calibration is decoupling capital equipment from pure production economics in Chile. Cristalerías de Chile S.A. leverages its Santiago-area furnace network to dominate domestic beverage supply. Owens-Illinois Perú S.A. anchors cross-border logistics for northern Chilean mining-camp food packaging. Verallia SA differentiates through pharmaceutical-grade borosilicate capacity serving Latin American drug distributors.
Container glass consists of silica sand, soda ash, limestone, and cullet melted at temperatures exceeding 1500°C before forming into hollow vessels by blow-and-blow or press-and-blow methods, primarily serving liquid and semi-solid product protection. The bottles segment leads Chilean output, absorbing most Central Valley wine and pisco volume, while pharmaceutical vials command the highest unit margins due to USP Type I certification requirements. Jars compete in artisanal food exports where oxygen barrier performance determines shelf stability for Pacific Rim shipments.
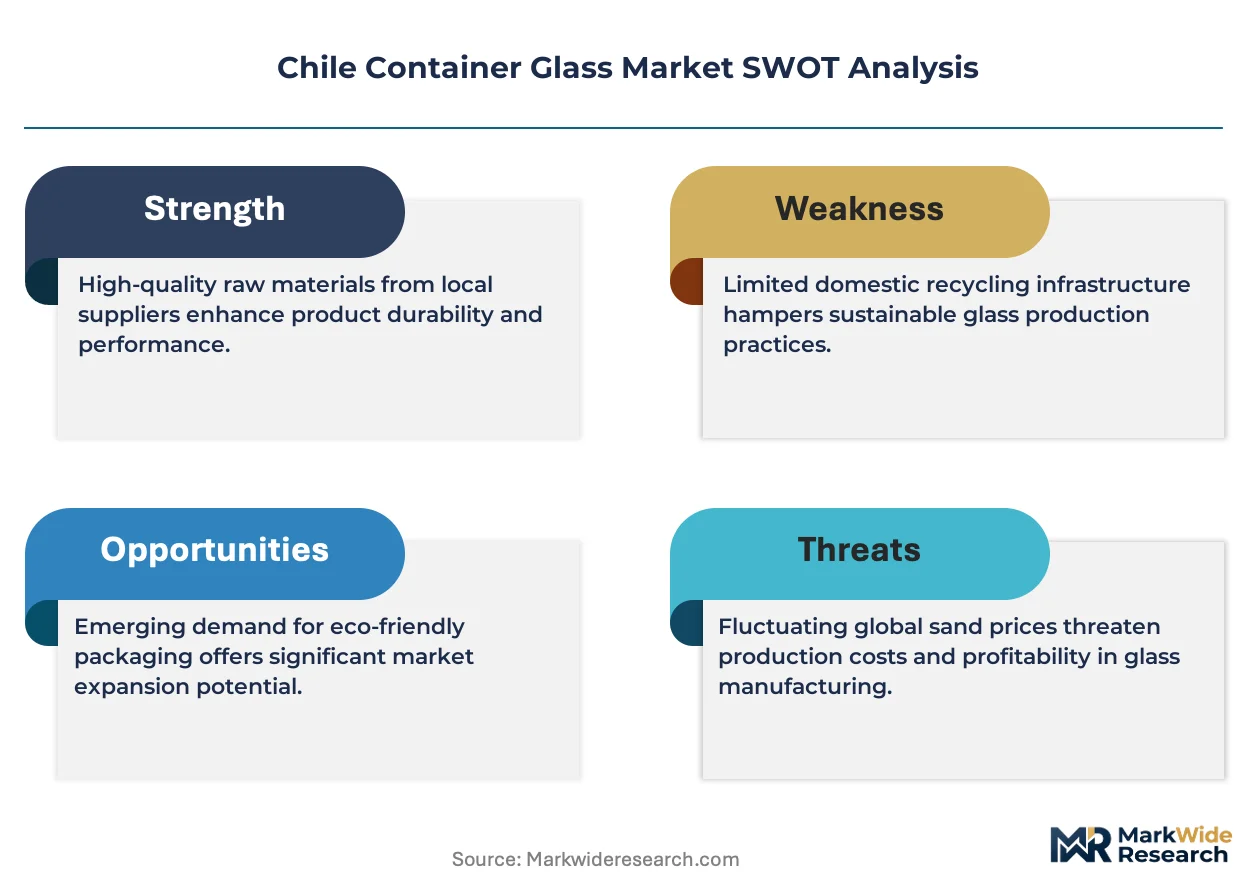
Chile's Ministry of Environment enforces Extended Producer Responsibility frameworks that mandate post-consumer cullet collection targets, while the Superintendency of Electricity and Fuels regulates natural gas pricing that directly shapes furnace operating economics. BIS-equivalent INN standards govern pharmaceutical container dimensional tolerances, creating compliance barriers for uncertified imports. Stakeholders must monitor whether carbon border adjustments on European wine imports will force accelerated electric furnace conversion decisions ahead of regulatory deadlines.
Market Dynamics
Chile's Extended Producer Responsibility law is forcing furnace operators to reconfigure cullet sourcing networks and rebuild batch houses for higher recycled content ratios, compressing legacy virgin-sand economics across the Central Valley production corridor.
Growth Catalysts
- Wine export bottling demand:Premium Central Valley wineries are specifying lightweight containers with 30-50% post-consumer cullet for Pacific Rim shipments, pulling capacity investments toward Santiago metropolitan forming lines.
- Energy efficiency retrofit mandates:The Superintendency of Electricity and Fuels is tightening natural gas consumption benchmarks for continuous furnaces, accelerating oxy-fuel burner upgrades at existing plants.
- Pharmaceutical packaging certification:USP Type I borosilicate vial requirements from Latin American drug distributors are creating specialized capacity premiums for certified Chilean producers.
Market Restraints
- Natural gas price volatility:Furnace operating economics hinge on regulated pipeline tariffs set by national energy authorities, exposing margins to import-dependency fluctuations.
- Cullet collection infrastructure gaps:Post-consumer glass recovery rates in northern mining regions and southern agricultural zones trail Santiago metropolitan collection density by substantial margins.
- Aluminum can substitution:Beverage packagers in mass-market beer and soft drinks are converting filling lines to lightweight metal formats for cold-chain distribution efficiency.
Strategic Opportunities
- Antofagasta mining-camp food packaging:Remote extraction operations require durable jar formats for extended shelf stability, creating pull for thicker-walled container specifications.
- Electric furnace pilot programs:Grid decarbonization roadmaps from national energy planners may unlock capital subsidies for zero-emission melting trials ahead of European carbon border adjustment timelines.
- Artisanal food export channels:Small-batch producers in Maule and Biobío regions are adopting premium jar presentations for direct-to-consumer e-commerce shipments to North American specialty retailers.
Industry Challenges
- Furnace rebuild cycle compression:Campaign extensions beyond 15 years risk refractory failure and glass defect rates, yet capital allocation for cold repairs competes with cullet preprocessing equipment mandates.
- Forming machine technician scarcity:IS machine calibration and blow-mold maintenance expertise concentrates among aging workforces in Santiago suburbs, constraining shift expansion at secondary plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Container Glass Market |
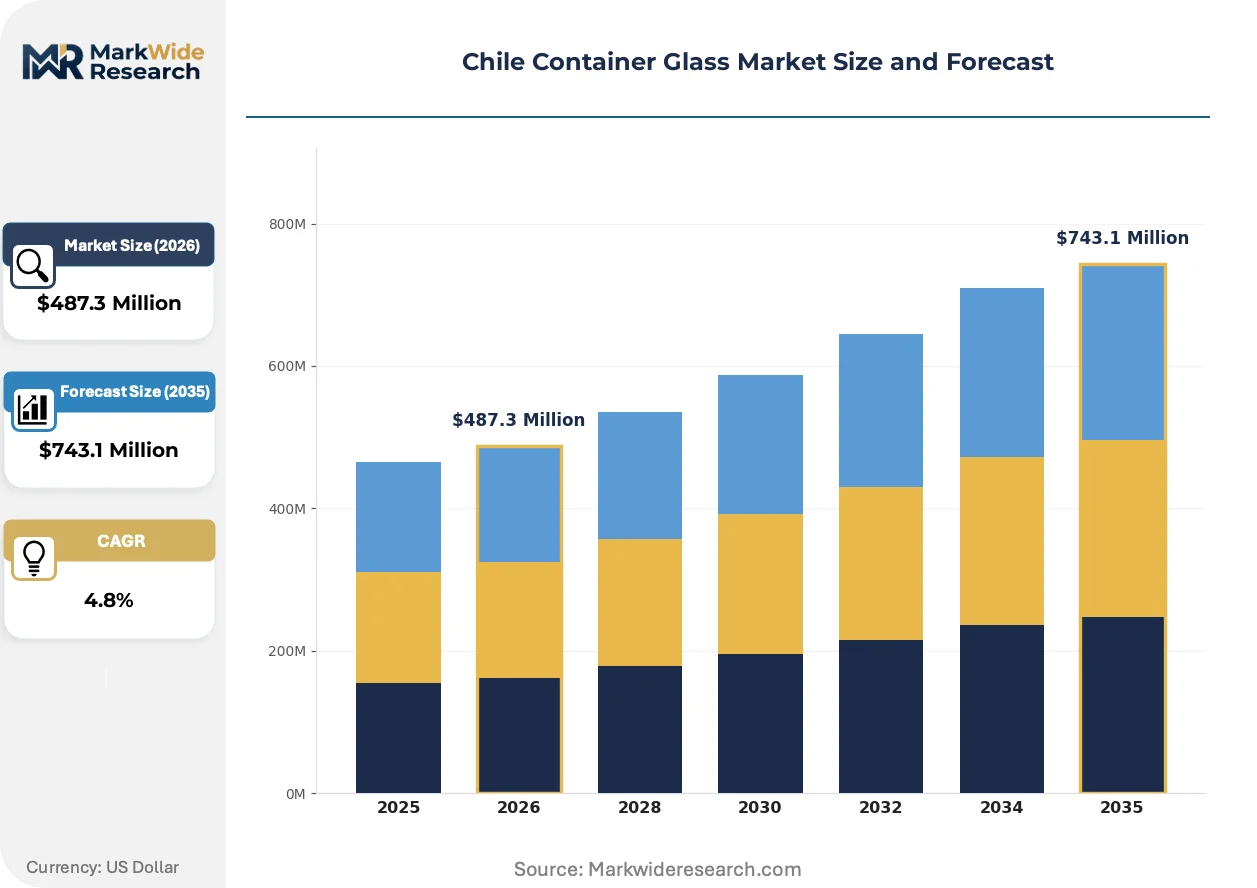
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Jugs, Vials End User: Beverage, Food, Pharmaceuticals, Cosmetics Application: Packaging, Storage, Transportation, Display Distribution Channel: Retail, Wholesale, Online, Direct |
| Companies Covered | Cristalerías de Chile S.A., Owens-Illinois Perú S.A., Verallia SA, Ardagh Group S.A., Vidrala SA, Gerresheimer Querétaro S.A. de C.V., O-I Glass, Vitro S.A.B. de C.V., Saint-Gobain S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Container Glass Market Trends and Innovations
Active melting and forming technologies are compressing energy intensity benchmarks while digital process controls reshape quality assurance protocols across Chilean container glass operations.
Oxy-fuel combustion systems are converging with real-time furnace atmosphere monitoring to cut specific energy consumption per ton of melted glass. Wineries in Colchagua and Maipo valleys are specifying these lower-carbon containers for export markets with embedded emissions disclosure requirements. The technology is converging with batch preheating equipment to form integrated low-carbon melting platforms that redefine plant upgrade roadmaps.
Chile's Ministry of Environment Extended Producer Responsibility framework mandates post-consumer cullet collection targets that escalate through the forecast window. Glass producers must finance reverse logistics networks or face non-compliance penalties that escalate operating levies. Pharmaceutical and premium wine segments are responding fastest, embedding collection cost recovery into bottle pricing structures.
Direct procurement relationships between Central Valley wineries and Santiago-area furnace operators are displacing traditional distributor intermediaries for volume contracts. Large bottlers are consolidating supplier panels to capture volume discounts and technical collaboration on lightweighting roadmaps. This pattern is most visible in the Colchagua and Casablanca valley corridors where export-oriented estates command substantial packaging procurement authority.
Chile Container Glass Market Segmentation
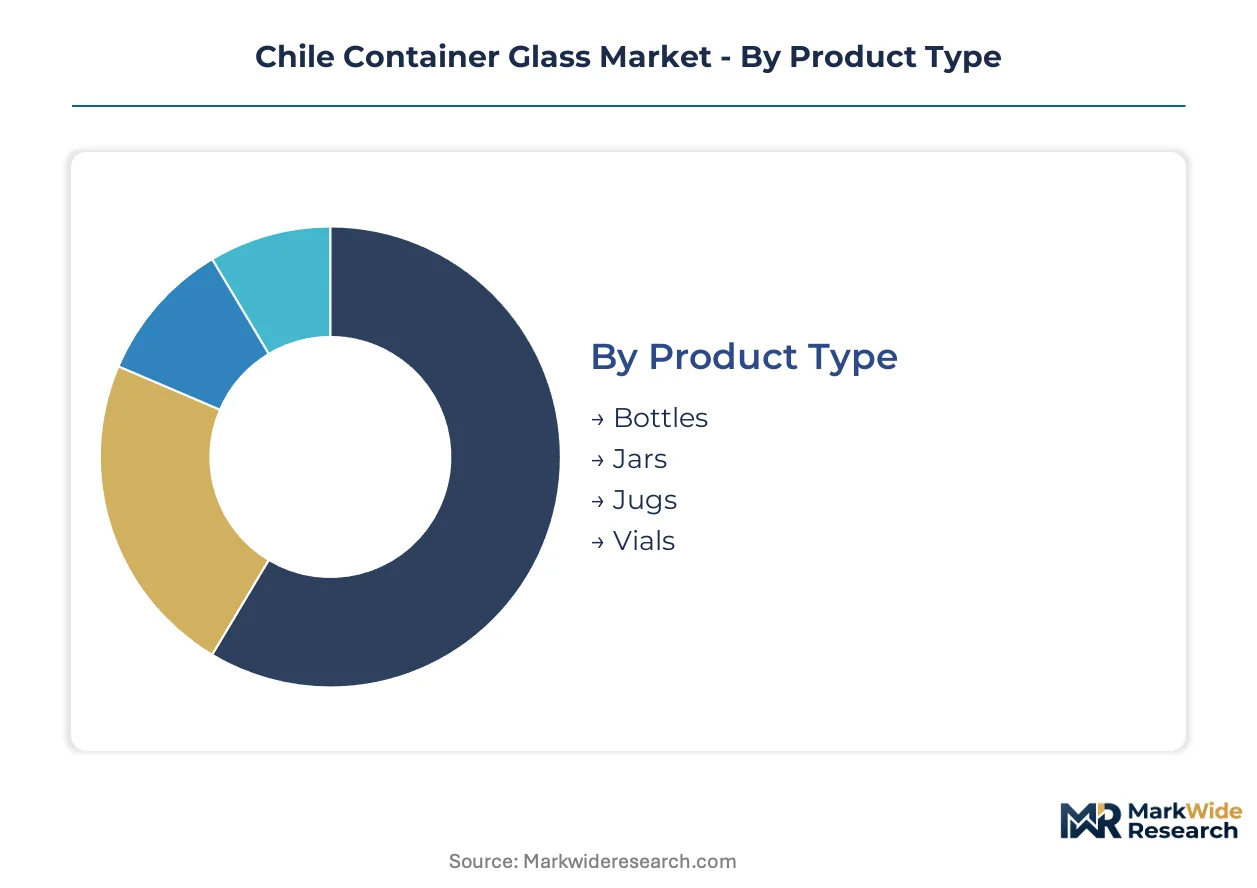
Chilean container glass producers must align furnace output with divergent customer specifications across wine export bottlers, pharmaceutical certifiers, and mining-camp food packagers. Segmentation reveals where technical capabilities command premium pricing versus where volume throughput drives plant economics.
Product Type:
Bottle geometry and wall thickness specifications separate premium wine exporters from mass-market beverage packagers in procurement negotiations.
- Bottles:Standard and lightweight configurations dominate Central Valley wine and pisco volume, with lightweight 30-50% cullet specifications now mandatory for Pacific Rim export contracts. Santiago metropolitan forming lines absorb the bulk of this demand, though Colchagua valley wineries are consolidating direct procurement relationships to capture technical collaboration on weight reduction roadmaps.
- Jars:Thicker-walled formats serve artisanal food exports and Antofagasta mining-camp provisions where oxygen barrier performance determines shelf stability for extended distribution cycles. Maule and Biobío small-batch producers are adopting premium jar presentations for direct-to-consumer e-commerce channels to North American specialty retailers.
- Jugs:Bulk liquid containers for institutional food service and industrial chemical applications carry lower unit margins but stabilize furnace load factors during seasonal wine bottling troughs.
- Vials:USP Type I borosilicate certification requirements from Latin American drug distributors create specialized capacity premiums for certified Chilean producers serving pharmaceutical distribution networks.
Volume sits with bottles; growth tilts toward vials.
End User:
Regulatory compliance intensity and carbon disclosure requirements fragment customer technical demands across furnace campaigns.
- Beverage:Premium Central Valley wineries specify lightweight containers with embedded emissions tracking for export markets, while mass-market beer packagers face aluminum can substitution pressure in cold-chain distribution.
- Pharmaceuticals:USP Type I borosilicate vial requirements command the highest unit margins due to certification barriers and dimensional tolerance standards enforced under INN-equivalent protocols.
- Food:Artisanal export producers in southern agricultural zones drive demand for thicker-walled jar formats with superior oxygen barrier performance for Pacific Rim shipment stability.
- Cosmetics:Specialty fragrance and skincare bottlers in Santiago metropolitan area require small-batch forming flexibility with decorative surface treatments.
Revenue concentrates in pharmaceuticals; volume expansion tracks beverage.
Application:
Functional performance requirements determine whether customers prioritize barrier properties, mechanical durability, or aesthetic presentation in container specifications.
- Packaging:Primary containment for liquid and semi-solid products absorbs the majority of Chilean container glass output, with wine export bottling dominating Santiago-area furnace capacity allocation.
- Storage:Extended shelf stability requirements in mining-camp food distribution and pharmaceutical cold chain drive specifications for thicker wall sections and optimized headspace geometry.
- Transportation:Palletization and intermodal handling durability influence secondary packaging decisions and container wall thickness tolerances for export shipments.
- Display:Premium cosmetic and specialty food presentations require decorative surface treatments and distinctive silhouette designs that constrain forming machine changeover efficiency.
Capacity utilization depends on packaging; technical differentiation emerges in storage.
Distribution Channel:
Order consolidation patterns and logistics cost structures shape how producers allocate furnace output across customer relationship types.
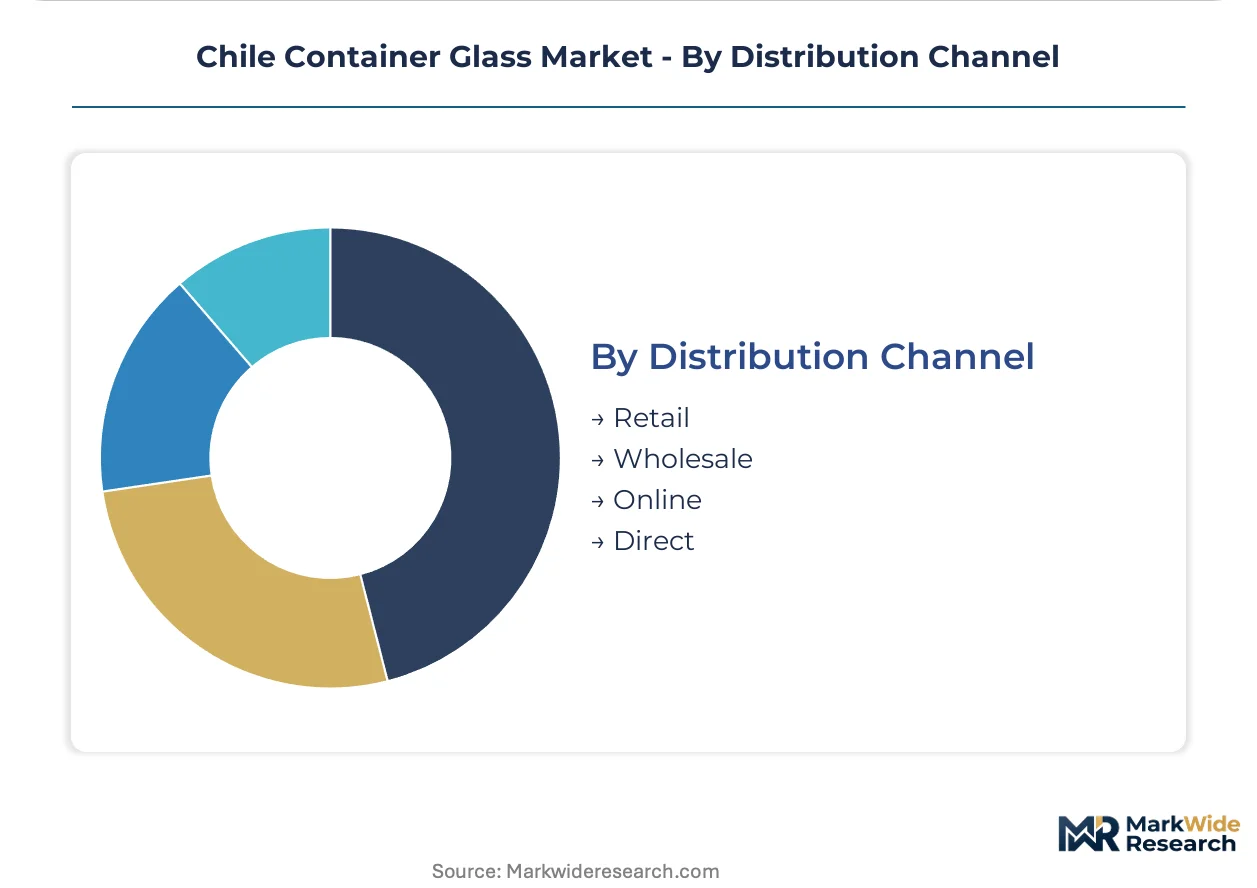
- Direct:Large Central Valley wineries are consolidating supplier panels and displacing distributor intermediaries for volume contracts, capturing technical collaboration on lightweighting roadmaps and volume discounts through Santiago-area furnace networks.
- Wholesale:Regional beverage distributors aggregate fragmented demand from smaller producers, constraining batch size flexibility and extending lead times for specialty container specifications.
- Retail:Specialty food and cosmetic packagers source through packaging distributors with inventory holding functions, adding margin layers but reducing working capital requirements for small-batch producers.
- Online:E-commerce procurement channels for artisanal food exporters enable direct access to North American specialty retailers, though logistics consolidation remains underdeveloped outside Santiago metropolitan collection density.
Margin capture favors direct; geographic reach expands through wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Santiago anchors Chile's container glass production through its metropolitan furnace network, while demand radiates outward to wine valleys and mining corridors. The Central Valley production corridor concentrates technical capacity, with northern and southern regions presenting divergent sourcing challenges.
Metropolitan Santiago
Santiago's furnace network processes the majority of domestic beverage glass demand, serving direct procurement relationships with Colchagua and Maipo valley wineries. The Superintendency of Electricity and Fuels regulates natural gas tariffs that shape plant operating economics across the capital region. Forming machine technician expertise concentrates in Santiago suburbs, constraining shift expansion at secondary facilities.
Central Valley Wine Corridor
Colchagua and Casablanca valley exporters specify lightweight containers with 30-50% post-consumer cullet for Pacific Rim shipments. Chile's Extended Producer Responsibility law mandates escalating collection targets that reshape batch house configurations. Direct winery-furnace procurement relationships are displacing traditional distributor intermediaries for volume contracts.
Antofagasta Mining Region
Remote extraction operations pull thicker-walled jar formats for extended shelf stability in mining-camp food distribution. Post-consumer glass recovery rates trail Santiago metropolitan density by substantial margins, compressing cullet availability. Owens-Illinois Perú S.A. anchors cross-border logistics networks serving northern Chilean packaging demand.
Maule and Biobío Regions
Small-batch artisanal food producers in southern agricultural zones adopt premium jar presentations for direct-to-consumer e-commerce channels. Oxygen barrier performance specifications determine shelf stability for Pacific Rim export shipments. Collection infrastructure gaps constrain post-consumer cullet sourcing outside metropolitan collection density.
Chile Container Glass Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Chile's container glass sector, with furnace ownership creating structural barriers to entry. The market consolidates around integrated melting and forming operations rather than toll manufacturing arrangements. Three archetypes dominate: domestic furnace operators with Santiago-area networks, cross-border logistics specialists leveraging Peruvian supply bases, and pharmaceutical-grade certified producers commanding specialized capacity premiums. Competitive moves center on direct procurement relationship consolidation and oxy-fuel burner retrofit programs ahead of energy efficiency mandates.
Among domestic furnace operators, Cristalerías de Chile S.A. occupies the central position exemplifying integrated metropolitan production capacity. Cross-border logistics capabilities find representation in Owens-Illinois Perú S.A., which anchors northern supply arrangements. Pharmaceutical certification specialization sits with Verallia SA, representing the premium-tier archetype serving Latin American drug distribution networks.
| Leading Market Players |
|---|
| Cristalerías de Chile S.A. |
| Owens-Illinois Perú S.A. |
| Verallia SA |
| Ardagh Group S.A. |
| Vidrala SA |
| Gerresheimer Querétaro S.A. de C.V. |
| O-I Glass |
| Vitro S.A.B. de C.V. |
| Saint-Gobain S.A. |
| Others |
Pricing and Supply Chain Analysis
Winery procurement consolidation in Colchagua and Casablanca valleys is compressing distributor margins and forcing Santiago furnace operators to absorb cullet preprocessing costs into contract pricing structures. Extended Producer Responsibility mandates from Chile's Ministry of Environment escalate operating levies that reshape how producers quote multi-year volume agreements.
Pricing Analysis
Margin tightening in pharmaceutical vials reflects USP Type I certification scarcity and INN-equivalent dimensional tolerance enforcement. Three-tier pricing structure across premium wine export, standard beverage, and industrial jug segments stratifies by cullet content ratio and energy disclosure requirements. Cost-down pressure on lightweight containers accelerates because Central Valley exporters demand 30-50% post-consumer recycled specifications without price premiums. Mass-market beer packagers show highest price sensitivity as aluminum can substitution threatens volume commitments.
Supply Chain Analysis
Freight cost differentials between Santiago metropolitan furnace networks and northern mining regions favor cross-border Peruvian supply for Antofagasta food packaging demand. Silica sand extraction concentrates in Chile's northern desert basins, while soda ash imports draw from US and Turkish producers. Single-source vulnerability sits with natural gas pipeline tariffs regulated by the Superintendency of Electricity and Fuels. Distribution runs through direct winery-furnace contracts for premium tiers and wholesale beverage distributors for fragmented regional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's container glass sector is transitioning from natural gas-fired continuous furnaces toward oxy-fuel and electric melting platforms as energy efficiency mandates tighten operating benchmarks.
For Market Incumbents: Extend preventive maintenance contract offerings to decouple capital equipment economics from pure production volumes, locking in multi-year furnace rebuild schedules ahead of campaign compression risks. Deepen backward integration into cullet collection networks across Santiago metropolitan density zones to secure post-consumer supply against northern and southern infrastructure gaps. Aluminum can substitution in mass-market beer threatens beverage volume stability; counter with technical collaboration on lightweighting roadmaps for premium wine export contracts. For New Entrants and Emerging Players: The price-point gap between USP Type I certified pharmaceutical vials and standard beverage bottles offers white-space capture for borosilicate capacity investment serving Latin American drug distributors. Target artisanal food export channels in Maule and Biobío regions where premium jar presentations command margin premiums through direct-to-consumer e-commerce linkages. Enter through toll-forming arrangements with existing Santiago furnace operators to bypass capital-heavy melting infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical-grade certified producers given USP Type I capacity premiums and Latin American distribution network expansion. Long-term viability favors integrated melting-forming operations with oxy-fuel retrofit completion ahead of electric furnace pilot program subsidies. Watch carbon border adjustment implementation timelines on European wine imports as inflection signal for accelerated plant upgrade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Burner Retrofit | Superintendency of Electricity and Fuels mandates cut specific energy consumption per melted ton. |
| Cullet Collection Network Expansion | Extended Producer Responsibility law compliance requires reverse logistics financing or penalty exposure. |
| Pharmaceutical Certification Investment | USP Type I borosilicate capacity commands specialized premiums from Latin American drug distributors. |
| Direct Procurement Relationship Consolidation | Colchagua valley wineries displace distributor intermediaries for technical collaboration access. |
| Electric Furnace Pilot Program | Grid decarbonization roadmaps may unlock capital subsidies ahead of European carbon border adjustments. |
Research Methodology
Multi-period observation of furnace campaign extensions, cullet recovery rates, and natural gas tariff adjustments anchored the trend analysis, supplemented by interviews with plant operations managers, Central Valley winery procurement directors, pharmaceutical packaging specifiers, and mining-camp food service distributors. Secondary validation drew from Chile's Ministry of Environment regulatory filings, Superintendency of Electricity and Fuels tariff schedules, INN standards documentation, and customs trade data on container glass imports. Bottom-up plant capacity modeling triangulated against top-down end-use demand aggregation.
Segment-weighting approaches distributed value and volume projections across product type, end user, application, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis of historical production data against explanatory variables including wine export volumes, pharmaceutical distribution growth, and energy cost trajectories. Forecast inputs incorporated furnace rebuild cycle timing, Extended Producer Responsibility compliance cost pass-through assumptions, and aluminum substitution elasticity estimates for mass-market beverage segments.
Underlying measurement precision varies by segment; pharmaceutical vial and premium wine export categories carry tighter precision than industrial jug and mining-camp food packaging due to certification documentation and direct procurement transparency. Forecasts reflect documented assumptions regarding regulatory implementation schedules, natural gas price trajectories, and cullet collection infrastructure development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Russia Container Glass Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
North America Glass Bottles/Containers Market
Glass Packaging
Peru Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Cosmetic and Perfume Glass Bottle Market
Glass Packaging
Germany Glass Packaging Market
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Guatemala Container Glass Market
Glass Packaging
Egypt Glass Packaging Market